
 North America LFP Battery Pack Market | 2026-2036
North America LFP Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
North America LFP Battery Pack Market Insights
Commercial fleet operators are rotating demand away from consumer automotive toward heavy-duty and stationary applications. American Battery Solutions Inc leverages its Michigan manufacturing base to supply regional commercial vehicle builders. A123 Systems LLC anchors its position through specialized LFP cell production for power grid and transit bus segments. Clarios International Inc competes across dual channels, sustaining aftermarket distribution while building direct OEM relationships for next-generation pack architectures.
Lithium iron phosphate battery packs employ cathodes composed of lithium iron phosphate rather than nickel or cobalt oxides, delivering thermal runaway thresholds above 270 degrees Celsius and cycle lives exceeding three thousand charge events. Their primary purpose centers on providing safe, durable electrochemical storage for applications where energy density requirements remain secondary to longevity and capital cost control. Energy Storage Systems represent the fastest-expanding application segment as utilities deploy grid-scale LFP installations across Texas and California ISO territories. Battery Management Systems technology commands disproportionate margin pools because thermal monitoring and cell balancing algorithms differentiate pack reliability in high-utilization commercial settings. OEM Partnerships distribution is displacing traditional distributor networks as automakers and energy developers seek captive supply agreements with cell-to-pack integrators.
The US Inflation Reduction Act's domestic content provisions, administered through Treasury Department guidance, require qualifying battery components to originate from North American free trade partners to access full tax credits. EPA emissions standards for medium and heavy-duty vehicles, alongside NHTSA fuel economy rules, compel fleet operators toward electrification pathways where LFP chemistry satisfies total cost of ownership requirements. OSHA workplace safety directives for battery handling and storage further shape facility design and technician certification across the value chain. Stakeholders must monitor how forthcoming FERC interconnection rulemakings affect utility-scale storage deployment timelines and whether state-level public utility commission decisions in California and Texas accelerate or constrain merchant storage revenue models.
Market Dynamics
The US Inflation Reduction Act's domestic content bonus credit is compressing supply chain timelines as pack integrators scramble to qualify North American cell sourcing before Treasury guidance deadlines.
Growth Catalysts
- IRA domestic content thresholds:Treasury Department guidance requiring 40 percent North American value-add for full tax credits is pulling cell production capacity toward Michigan and Tennessee manufacturing corridors.
- Transit bus electrification mandates:EPA emissions standards for medium and heavy-duty vehicles are compelling municipal fleet operators to specify LFP chemistry for route duty cycles exceeding three hundred thousand miles.
- Grid-scale storage deployment:Texas and California ISO territories are absorbing merchant storage capacity as interconnection queues clear, with LFP packs dominating four-hour duration installations.
Market Restraints
- Graphite anode supply concentration:Over 70 percent of battery-grade spherical graphite originates from Chinese processing facilities, creating tariff exposure under Section 301 trade actions.
- Cell formation energy intensity:LFP cathode material requires extended high-temperature aging cycles that inflate electricity costs at formation facilities.
- Energy density ceiling:The chemistry's theoretical limit of 170 Wh/kg constrains pack designers targeting Class 8 long-haul trucking applications where payload penalties accumulate.
Strategic Opportunities
- Second-life stationary repurposing:Retired transit bus packs retain 70-80 percent capacity and can displace new cell purchases for behind-the-meter commercial installations.
- Cell-to-pack architecture adoption:Eliminating module housings reduces pack mass 15-20 percent while simplifying thermal management for heavy-duty vehicle builders.
- FERC Order 2222 implementation:Aggregated distributed energy resource participation in wholesale markets creates recurring revenue streams for fleet-owned storage assets.
Industry Challenges
- Electrolyte formulation expertise gap:High-voltage LFP cell designs require specialized additive packages that few North American material suppliers currently manufacture at scale.
- UL 9540A test facility bottlenecks:Cell-level thermal runaway propagation certification queues extend six to nine months, delaying utility interconnection approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America LFP Battery Pack Market |
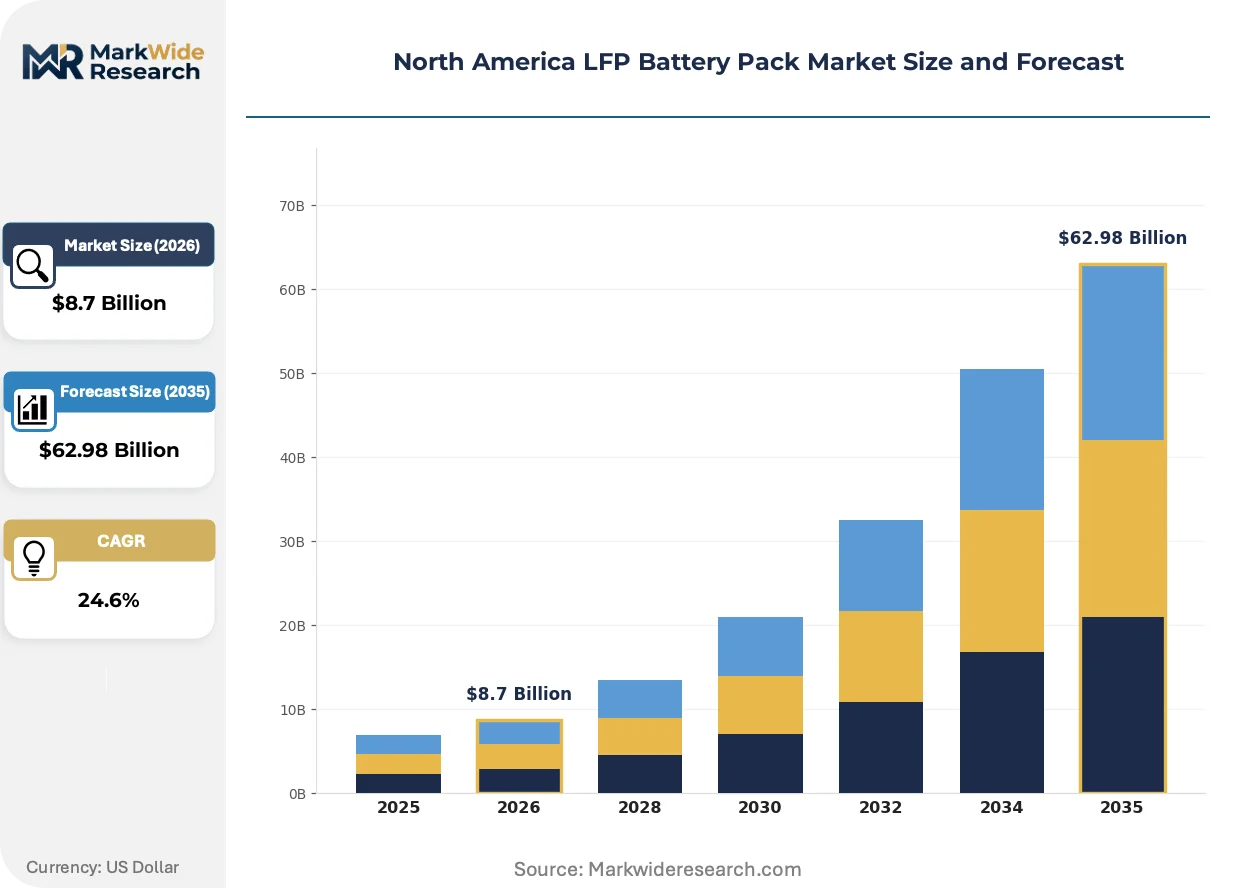
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electric Vehicles, Energy Storage Systems, Backup Power, Renewable Integration End User: Automotive Manufacturers, Energy Providers, Residential Consumers, Commercial Users Technology: Battery Management Systems, Charge Controllers, Thermal Management, Power Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, OEM Partnerships |
| Companies Covered | Clarios International Inc, American Battery Solutions Inc, A123 Systems LLC, SK On, QuantumScape Corp, LG Energy Solution Ltd, Electrovaya Inc, Nikola Corporation, Contemporary Amperex Technology Co Ltd (CATL), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America LFP Battery Pack Market Trends and Innovations
Pack architecture is shedding modular legacy designs as integrators pursue mass reduction and thermal uniformity. Three concurrent developments are compressing conventional supply relationships and rewiring competitive advantage.
Cell-to-pack engineering is bifurcating the supplier base into cell manufacturers capable of direct OEM integration versus module-dependent pack assemblers facing margin compression. Transit bus and grid storage buyers are specifying cell-to-pack configurations for 2026 delivery slots. The structural consequence is collapsing tier-two module housing suppliers as cell makers capture pack integration value previously held by independent assemblers.
OSHA's forthcoming battery handling standards for high-voltage workplace safety are mandating arc-flash containment and technician certification protocols at fleet maintenance depots. The rulemaking forces pack designers to incorporate service disconnects and insulated busing that add 3-5 percent pack cost. Commercial vehicle operators in California and Texas are pre-emptively upgrading facilities to avoid operational shutdowns during compliance audits.
Fleet procurement committees are consolidating supplier relationships from multi-source distributor networks toward single-source cell-to-pack integrators with captive North American cell supply. The distributor channel serving aftermarket replacement packs is losing share to direct OEM partnerships. This concentration is most visible among Class 4-7 delivery fleet operators in the US Southeast manufacturing corridor seeking IRA credit certainty through qualified domestic content documentation.
North America LFP Battery Pack Market Segmentation
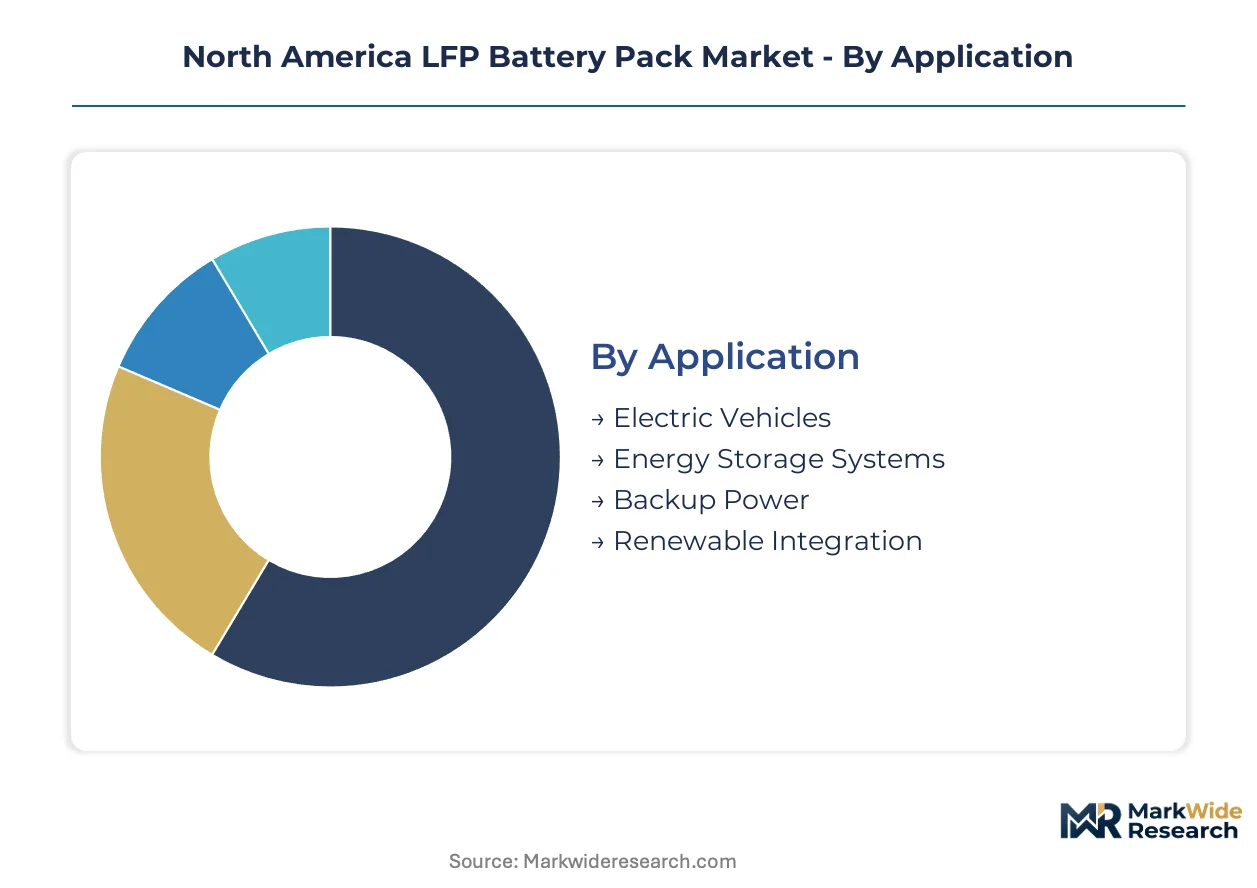
LFP battery pack segmentation reveals where chemistry advantages translate into durable revenue streams versus where substitute technologies threaten displacement. Understanding these fault lines guides capital allocation across manufacturing capacity and R&D portfolios.
Application:
Energy Storage Systems faces the most acute substitution pressure as sodium-ion and flow battery developers target four-hour grid duration economics.
- Electric Vehicles:Heavy-duty transit buses and Class 4-7 delivery trucks specify LFP packs for route duty cycles exceeding three hundred thousand miles. Texas and California fleet operators are consolidating procurement around cell-to-pack architectures to capture IRA domestic content bonuses.
- Energy Storage Systems:Utility-scale installations across ERCOT and CAISO territories absorb merchant storage capacity as interconnection queues clear. Four-hour duration configurations dominate, though longer duration requirements expose LFP to vanadium redox and compressed air alternatives.
- Backup Power:Data center operators in the US Southeast specify LFP for uninterruptible power supply redundancy.
- Renewable Integration:Solar-plus-storage developers in California pair LFP with photovoltaic assets to firm evening ramp periods.
Electric Vehicles retains volume leadership; Energy Storage Systems holds the steepest expansion curve.
End User:
Customer type determines pricing power, with direct OEM relationships commanding premium terms over fragmented residential channels.
- Automotive Manufacturers:Transit bus builders and commercial vehicle OEMs in Michigan and Tennessee manufacturing corridors specify qualified domestic content packs to satisfy Treasury Department guidance thresholds.
- Energy Providers:Investor-owned utilities and independent power developers deploy grid-scale assets across Texas and California ISO territories, with procurement committees consolidating supplier relationships toward single-source integrators.
- Residential Consumers:Behind-the-meter solar-plus-storage buyers in California and Texas face longer payback periods as net metering reforms compress value stacking opportunities.
- Commercial Users:Fleet operators and industrial facilities prioritize total cost of ownership over upfront capital expenditure, favoring LFP cycle life economics.
Automotive Manufacturers anchor current revenue concentration; Energy Providers are climbing the fastest as utility procurement accelerates.
Technology:
Component-level margin pools concentrate where thermal runaway prevention and cell balancing algorithms differentiate pack reliability.
- Battery Management Systems:High-voltage LFP designs require specialized firmware for state-of-charge estimation across wide temperature ranges. Pack integrators with captive BMS development capture margin premiums in commercial vehicle segments.
- Thermal Management:Liquid cooling circuits and phase-change materials maintain cell temperatures below forty-five degrees Celsius during fast-charge events. Heavy-duty applications in Texas and Arizona desert corridors drive specification intensity.
- Charge Controllers:Bidirectional power electronics enable vehicle-to-grid revenue streams under FERC Order 2222 aggregation models.
- Power Electronics:Inverter integration at pack level reduces installation labor for utility-scale deployments.
Battery Management Systems commands the widest margin spread; Thermal Management is gaining specification share fastest as energy density increases.
Distribution Channel:
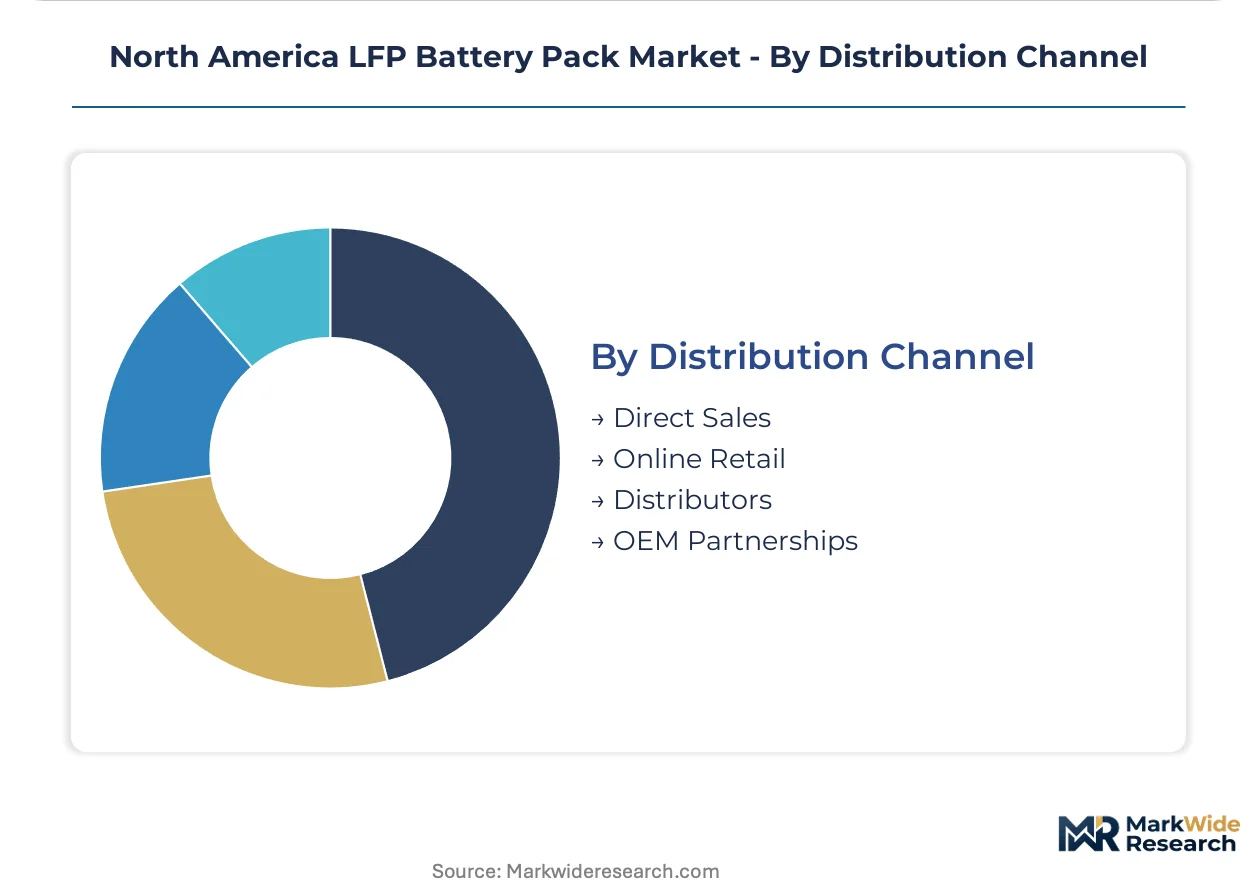
Channel structure is bifurcating between qualified domestic content direct relationships and traditional distributor networks losing IRA-exposed volume.
- OEM Partnerships:Captive supply agreements with cell-to-pack integrators displace multi-source distributor networks. Fleet operators in the US Southeast manufacturing corridor seek documentation certainty for Treasury Department bonus credits.
- Direct Sales:Utility-scale developers negotiate frame agreements with pack manufacturers for multi-year deployment schedules across Texas and California.
- Distributors:Aftermarket replacement pack channels face margin compression as OEM direct relationships capture lifecycle value.
- Online Retail:Residential and small commercial buyers access standardized pack configurations through e-commerce platforms with limited customization.
OEM Partnerships holds the dominant revenue position; Direct Sales is expanding most quickly as utility procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell formation capacity clusters along the US Southeast manufacturing corridor and Great Lakes industrial belt. Michigan and Tennessee anchor cathode material processing and pack assembly operations. The US Inflation Reduction Act's domestic content thresholds are redrawing supplier geography across North American free trade partners.
United States
Texas and California ISO territories absorb merchant storage deployments as interconnection queues clear. EPA emissions standards for medium and heavy-duty vehicles compel fleet operators toward electrification pathways. The US Southeast manufacturing corridor from Georgia to Tennessee concentrates cell-to-pack assembly investments seeking Treasury Department bonus credit qualification.
Canada
Ontario's automotive supply base pivots toward LFP module assembly for commercial vehicle OEMs. Federal clean technology investment tax credits support cathode precursor material facilities in Quebec. The Windsor-Detroit cross-border cluster leverages integrated North American supply chains for qualified domestic content documentation.
Mexico
Baja California and Sonora states attract formation facility investments seeking USMCA tariff advantages and lower electricity costs. Nuevo León's Monterrey metro area hosts pack assembly operations serving Texas fleet operators. The country's national energy regulator shapes grid interconnection timelines for utility-scale storage projects near the US border.
North America LFP Battery Pack Market Competitive Landscape
Concentration sits with integrated cell-to-pack specialists and established automotive suppliers diversifying into commercial electrification. The supplier base compresses around three strategic archetypes: captive cell manufacturers with direct OEM relationships, independent pack integrators leveraging regional manufacturing proximity, and diversified battery conglomerates spanning multiple chemistries. Dominant competitive moves include backward integration into cathode material production and strategic partnerships securing qualified domestic content supply.
Among US-based pack integrators, American Battery Solutions Inc and Clarios International Inc exemplify the regional manufacturing archetype. A123 Systems LLC occupies a position within specialized LFP cell production for power grid and transit applications. These three companies represent distinct competitive positioning strategies: Michigan-based commercial vehicle supply, dual-channel aftermarket and OEM distribution, and dedicated energy storage cell manufacturing respectively.
| Leading Market Players |
|---|
| Clarios International Inc |
| American Battery Solutions Inc |
| A123 Systems LLC |
| SK On |
| QuantumScape Corp |
| LG Energy Solution Ltd |
| Electrovaya Inc |
| Nikola Corporation |
| Contemporary Amperex Technology Co Ltd (CATL) |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between pack integrators and cathode material suppliers lock in IRA domestic content qualification and insulate procurement committees from lithium carbonate spot volatility. These contracts bundle volume commitments with price collars that transfer commodity risk upstream while securing Treasury Department bonus credit eligibility for fleet operators in the US Southeast manufacturing corridor.
Pricing Analysis
Volume-discount tiering separates transit bus fleet operators purchasing thousand-unit annual volumes from merchant storage developers negotiating project-specific frame agreements. Pricing stratifies across premium certified domestic content tiers, standard qualified North American value-add configurations, and economy imports facing tariff exposure. Cost compression in the economy tier intensifies because Chinese cell imports face Section 301 duties. Transit bus operators with captive maintenance depots exhibit lowest price sensitivity; residential behind-the-meter buyers in California face compressed payback calculations and highest sensitivity.
Supply Chain Analysis
Inbound logistics costs from Chinese spherical graphite processors through West Coast ports create working capital strain for anode material buyers. Cathode precursor supply draws from Quebec processing facilities and Tennessee manufacturing corridors. Cell formation energy intensity rests on Great Lakes electricity pricing. Tariff exposure on Chinese graphite concentrates creates structural risk. Distribution runs through direct OEM partnerships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery Management Systems firmware licensing and predictive maintenance subscriptions expand faster than hardware unit economics as fleet operators monetize uptime guarantees. Recurring revenue from thermal monitoring analytics and cell balancing algorithm updates commands margin premiums exceeding pack hardware sales.
For Market Incumbents: Shield IRA credit qualification by securing captive North American cathode supply through backward integration into Quebec precursor facilities. Defend against sodium-ion substitution in grid storage by accelerating four-hour duration cost curves. Channel control through direct OEM partnerships locks out distributor-dependent challengers.
For New Entrants and Emerging Players: Second-life pack refurbishment services represent a service-layer gap where incumbents under-serve commercial behind-the-meter installations. Target Texas industrial facilities seeking refurbished transit bus packs at seventy percent of new cell cost. Pursue FERC Order 2222 aggregation software partnerships as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a capacity-construction phase that favors integrated cell-to-pack specialists with qualified domestic content documentation. Long-term viability hinges on cathode material upstream control and BMS firmware differentiation. Cell formation facility investments in Michigan and Tennessee signal inflection toward supply security over pure cost optimization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Quebec precursor facilities secure IRA domestic content thresholds for Treasury Department bonus credits. |
| Cell-to-Pack Architecture Adoption | Eliminating module housings reduces mass fifteen to twenty percent for heavy-duty vehicle builders. |
| FERC Order 2222 Aggregation Platform | Bidirectional power electronics enable vehicle-to-grid revenue streams for Texas fleet operators. |
| Second-Life Refurbishment Capability | Retired transit bus packs displace new cell purchases for California commercial installations. |
| UL 9540A Test Facility Investment | Thermal runaway propagation certification queues delay utility interconnection approvals six to nine months. |
Research Methodology
Operator-level perspectives from fleet procurement directors, utility planning officers, pack integration engineers, and cathode material procurement leads anchored the qualitative base. Primary interview data triangulated against secondary sources including EIA storage deployment databases, FERC interconnection filings, EPA emissions compliance records, and Treasury Department IRA guidance documents. Bottom-up unit economics modeled across application segments and top-down market sizing from regional deployment pipelines cross-validated volume estimates.
Sensitivity analysis tested forecast outputs against variable IRA domestic content threshold scenarios and lithium carbonate price band assumptions across the projection horizon. Segmentation dimensions modeled include application type, end user category, technology component, and distribution channel structure. CAGRs derived from installed base growth curves and replacement cycle dynamics. Forecast inputs incorporated interconnection queue clearance rates and transit bus electrification mandate compliance timelines.
Forecasts assume regulatory continuity in IRA domestic content provisions and EPA emissions standards; material policy shifts would require re-modeling. Commodity price volatility in lithium and graphite markets, FERC interconnection rulemaking delays, and OSHA battery handling standard implementation pace constitute specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market