
 North America Industrial Battery Market | 2026-2036
North America Industrial Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Battery Market Analytics
A capital-intensity divergence between thin-margin lead-acid incumbents and high-investment lithium-ion scale-ups is bifurcating competitive dynamics across the region. EnerSys leverages its motive power service network to sustain recurring revenue in material handling. East Penn Manufacturing Company anchors its position through in-house lead recycling and vertical control over raw material inputs. Exide Technologies competes on price in telecom backup segments where replacement cycles remain predictable.
North America industrial batteries are electrochemical storage systems engineered for cyclic deep-discharge duty, typically operating at voltages from 12V to 80V with energy densities spanning 30-250 Wh/kg depending on chemistry selection, designed to power forklifts, telecom shelters, and grid-scale buffering installations. The lithium iron phosphate technology segment leads value creation as thermal stability and cycle life justify premium positioning in renewable energy storage applications. Lead-acid chemistry occupies a mature cost-optimized niche in electric forklifts where fleet operators prioritize capital expenditure control over total cost of ownership. Solid-state technology remains pre-commercial but attracts development focus for future UPS systems demanding higher energy density in constrained footprints.
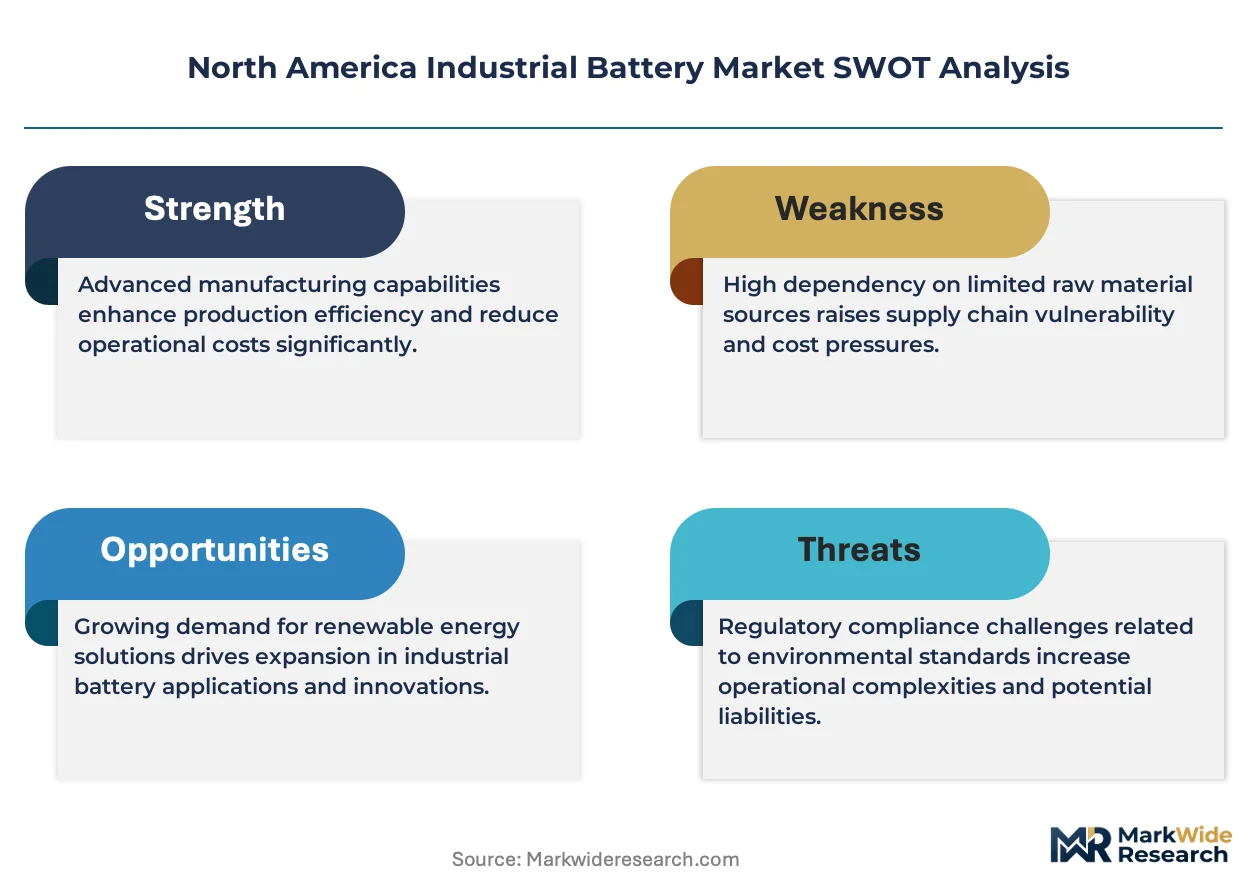
OSHA workplace safety standards and EPA hazardous waste rules govern lead-acid battery handling and recycling compliance across United States facilities, while Canada's PMRA and provincial environmental regulators enforce parallel chemical stewardship protocols affecting cross-border supply chains. The Inflation Reduction Act's standalone storage investment tax credit reshapes procurement economics for utility-scale buyers, accelerating chemistry transitions that incumbent lead-acid manufacturers must navigate. Stakeholders should monitor how NERC reliability standards evolve to incorporate distributed battery assets into bulk power system planning, as this integration pathway determines which technology configurations capture incremental grid investment.
Market Dynamics
The Inflation Reduction Act's standalone storage investment tax credit is compressing payback periods for lithium-ion deployments, forcing lead-acid incumbents to defend installed base in motive power while utility-scale procurement tilts toward electrochemical density.
Growth Catalysts
- Data Center UPS Expansion:Hyperscale operators in Virginia and Texas are doubling uninterruptible power supply footprints to support AI training clusters, pulling premium lithium iron phosphate capacity into regional supply chains.
- IRA Storage Tax Credits:The Inflation Reduction Act's energy storage incentives are rewriting procurement economics for independent power producers, accelerating chemistry transitions in California and Texas grid-scale corridors.
- Lead Recycling Mandates:EPA hazardous waste rules and state-level extended producer responsibility frameworks are tightening closed-loop requirements, advantaging domestic recyclers with in-house smelting capabilities.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings for battery-grade lithium salts are compressing margins for cell assemblers without long-term offtake agreements with Chilean or Australian producers.
- Electrolyte Supply Concentration:Fluorinated electrolyte additives production clusters in China and Japan create single-source vulnerability for North American lithium-ion manufacturers seeking thermal stability formulations.
- Lead-Acid Replacement Cycles:Predictable five-to-seven-year swap schedules in telecom backup segments limit revenue upside for incumbent chemistry suppliers facing lithium substitution pressure.
Strategic Opportunities
- Mexico Manufacturing Migration:Battery pack assembly operations are relocating to Baja California and Chihuahua to capture USMCA duty advantages and proximate supply to Texas grid storage demand.
- Solid-State Pre-Commercial Development:Next-generation ceramic electrolyte research programs targeting data center UPS applications promise energy density multiples above current lithium-ion limitations.
- Second-Life Automotive Packs:Retired electric vehicle batteries from California and Michigan fleets are entering stationary storage refurbishment channels, creating circular feedstock for behind-the-meter installations.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design and thermal management specialists command premium compensation, constraining scale-up velocity for emerging lithium-ion manufacturers competing with automotive sector recruiters.
- NERC Interconnection Queue Delays:Bulk power system reliability certification timelines for utility-scale battery installations are stretching eighteen to twenty-four months in ERCOT and CAISO territories, compressing project IRRs.
- UL 9540A Fire Safety Testing:Large-scale thermal runaway propagation certification requirements are adding six-figure validation costs and six-month schedule risks to containerized storage system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Battery Market |
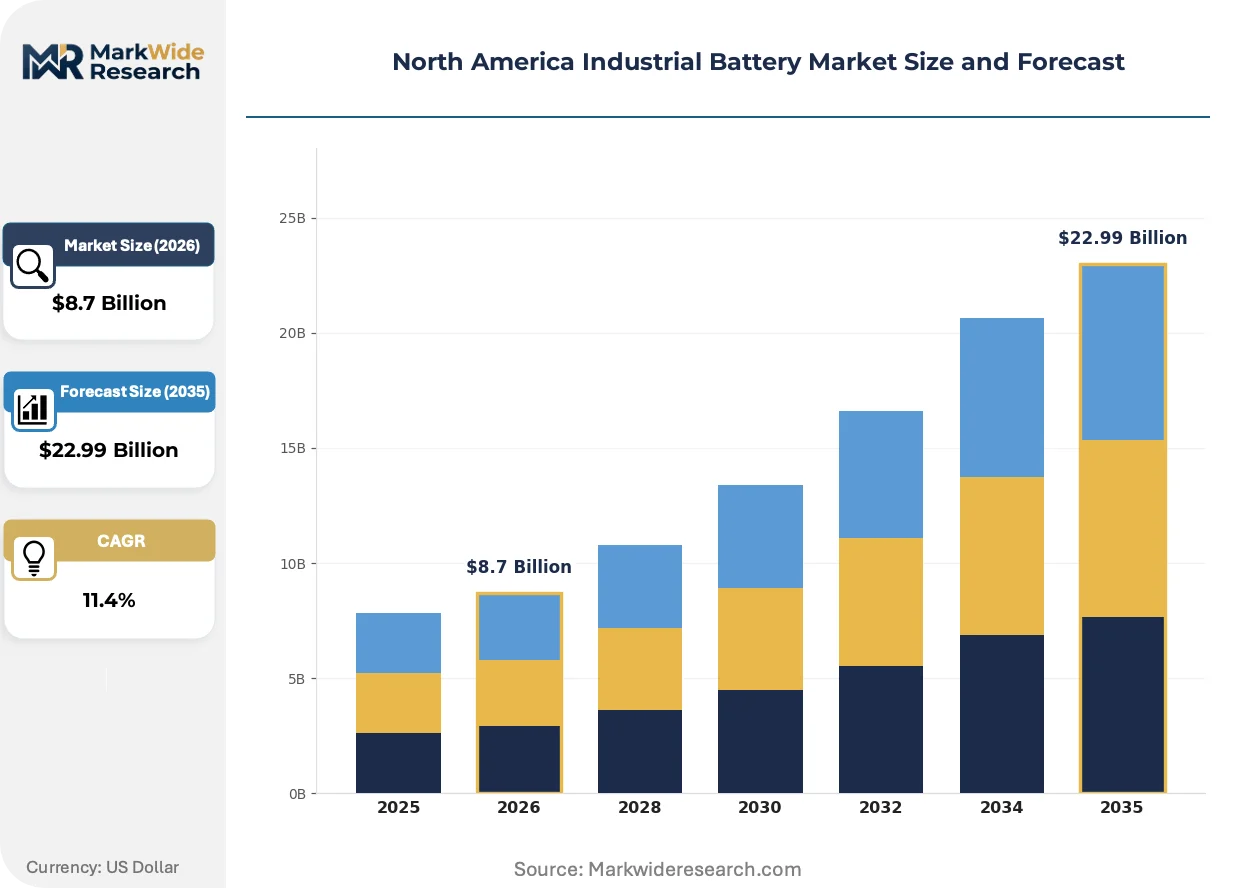
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Flow Batteries Technology: Advanced Lead-Acid, Lithium Iron Phosphate, Nickel-Metal Hydride, Solid-State End User: Manufacturing, Telecommunications, Transportation, Renewable Energy Application: Backup Power, Electric Forklifts, Renewable Energy Storage, UPS Systems |
| Companies Covered | EnerSys, East Penn Manufacturing Company, Exide Technologies, Johnson Controls International plc, C&D Technologies, Inc., GS Yuasa Corporation, NorthStar Battery Company, LLC, Crown Battery Manufacturing Company, A123 Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Battery Market Evolving Landscape
Chemistry selection is splitting competitive positioning across duty cycles, with thermal stability and cycle life specifications now dictating procurement winners in ways that transcend simple cost-per-kilowatt-hour metrics.
Lithium iron phosphate cathode formulations are bifurcating the industrial battery landscape. The chemistry delivers superior thermal runaway resistance for grid-scale buffering and data center UPS applications. Texas and California utility procurement teams are specifying LFP exclusively for four-hour duration storage assets. This chemistry preference is compressing nickel-manganese-cobalt alternatives into premium mobility segments where energy density remains paramount.
The Inflation Reduction Act's domestic content bonus credits are reshaping cell and module sourcing patterns. Manufacturers must prove North American assembly and qualifying critical mineral extraction to capture full incentive stacks. Battery system integrators serving ERCOT and PJM territories are requalifying supply chains to meet forty percent domestic content thresholds for projects commencing construction.
Power purchase agreement structures are displacing traditional equipment ownership models for grid-scale deployments. Independent power producers now procure battery storage as contracted capacity rather than capital assets, transferring operational risk to technology providers. This financing evolution is most visible in ERCOT territory, where merchant storage developers face merchant price exposure and demand guaranteed availability contracts from cell suppliers.
North America Industrial Battery Market Segmentation
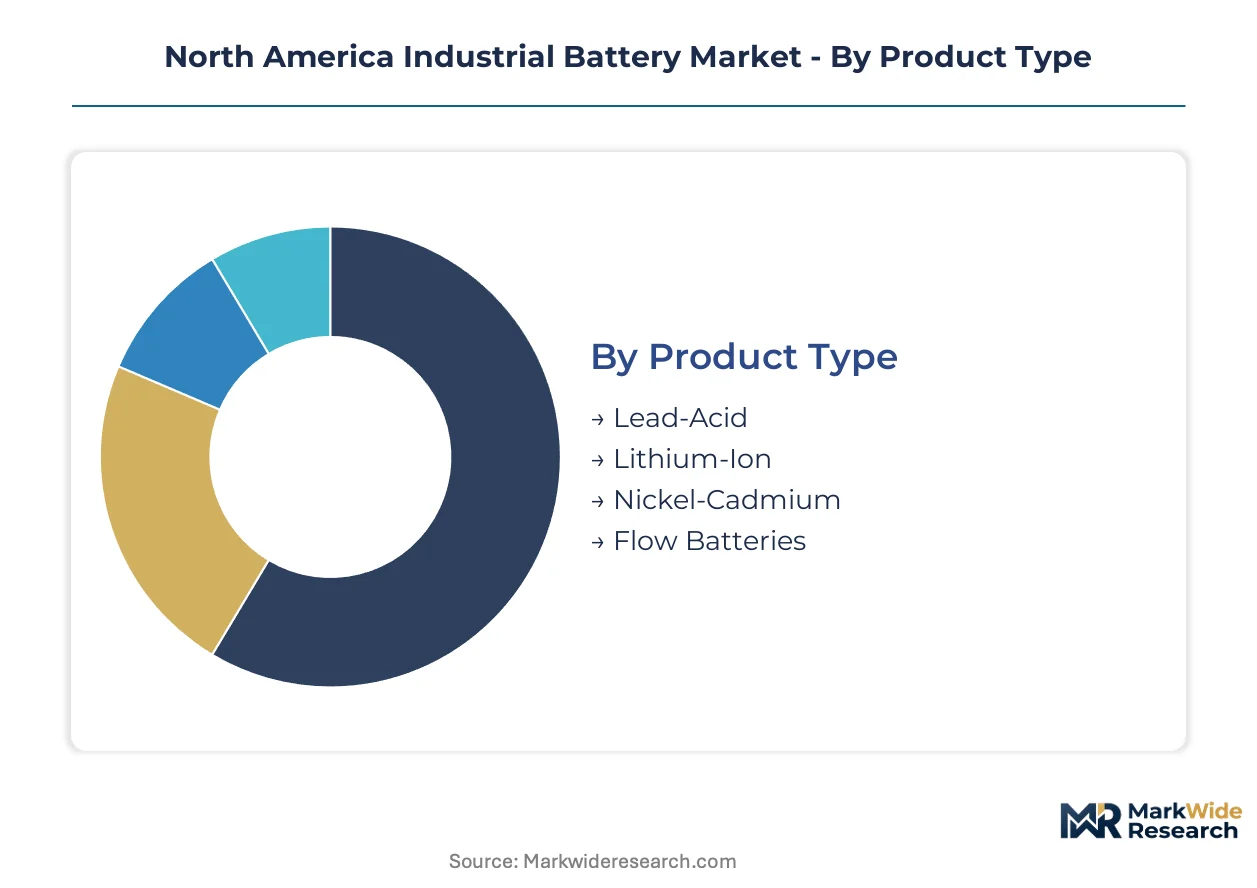
Industrial battery procurement patterns diverge sharply across chemistry types and duty cycles, with grid-scale deployments favoring electrochemical density while motive power segments prioritize capital discipline. Understanding these segment boundaries reveals where substitution pressure concentrates and where incumbents retain defensive moats.
Product Type:
Lead-acid chemistry dominates domestic manufacturing footprints serving forklift fleets and telecom backup, while lithium-ion capacity increasingly serves export-oriented grid storage deployments to Mexico and Canada under USMCA terms.
- Lead-Acid:Flooded and valve-regulated designs deliver 300-500 cycle life at the lowest capital cost per kilowatt-hour. Demand concentrates in Ohio and Pennsylvania manufacturing corridors where electric forklift fleets operate on predictable swap schedules and total cost of ownership calculations favor upfront savings.
- Lithium-Ion:Cylindrical and prismatic cell formats achieve 3,000-5,000 cycles with 95% round-trip efficiency. California and Texas utility procurement teams specify lithium-ion exclusively for four-hour duration storage assets, though IRA domestic content requirements are forcing supply chain requalification toward North American cell assembly.
- Nickel-Cadmium:Sintered plate construction withstands extreme temperature cycling from -40°C to 50°C. Canadian rail signaling and Arctic telecom shelters represent the primary demand concentration as sintered plate reliability justifies premium positioning.
- Flow Batteries:Vanadium redox systems decouple power and energy scaling for 8-12 hour duration applications. Washington and Oregon utility pilots are testing flow chemistry for seasonal storage, though electrolyte supply chains remain concentrated outside the region.
Lead-Acid commands the established base. The steepest expansion runs through Lithium-Ion.
Technology:
Cost tiers separate mature absorption-glass-mat designs from premium ceramic electrolyte research programs, with mid-tier LFP chemistry capturing volume in renewable integration applications.
- Advanced Lead-Acid:Carbon-enhanced negative electrodes reduce sulfation and extend partial-state-of-charge operation. Material handling fleets in Illinois and Michigan are retrofitting charging infrastructure to accommodate opportunity charging protocols that advanced lead-acid supports.
- Lithium Iron Phosphate:Olivine crystal structure eliminates cobalt dependency while delivering thermal runaway onset above 270°C. ERCOT and CAISO interconnection queues show LFP specified for 78% of pending utility-scale battery storage capacity.
- Nickel-Metal Hydride:Rare-earth lanthanum alloys enable moderate energy density with established recycling pathways. Hybrid locomotive and airport ground support equipment in California represent niche demand concentration.
- Solid-State:Sulfide and oxide ceramic electrolytes promise energy density exceeding 400 Wh/kg at cell level. Department of Energy ARPA-E funding supports pre-commercial development targeting data center UPS footprint constraints in Virginia and Texas.
Advanced Lead-Acid retains the cost-optimized tier. Lithium Iron Phosphate is climbing the fastest.
End User:
Customer type determines procurement sophistication, with hyperscale data center operators driving specification stringency while municipal utilities lag in technical evaluation capacity.
- Manufacturing:Automotive and food processing plants deploy batteries for electric material handling and peak shaving. Detroit and Chattanooga manufacturing clusters are consolidating fleet procurement to secure volume pricing on motive power systems.
- Telecommunications:5G small cell densification and fiber backhaul expansion require distributed backup power. Tower operators in Texas and Florida are specifying lithium-ion for new builds while managing lead-acid replacement cycles in legacy installations.
- Transportation:Electric bus depots and rail yards require high-throughput charging infrastructure with buffering storage. Los Angeles Metro and New York MTA pilot programs are testing second-life automotive pack integration.
- Renewable Energy:Solar-plus-storage and standalone battery assets require four-hour duration capability. Independent power producers in ERCOT and PJM territories are procuring storage as contracted capacity rather than owned equipment.
Manufacturing anchors the installed base. Renewable Energy shows the steepest expansion trajectory.
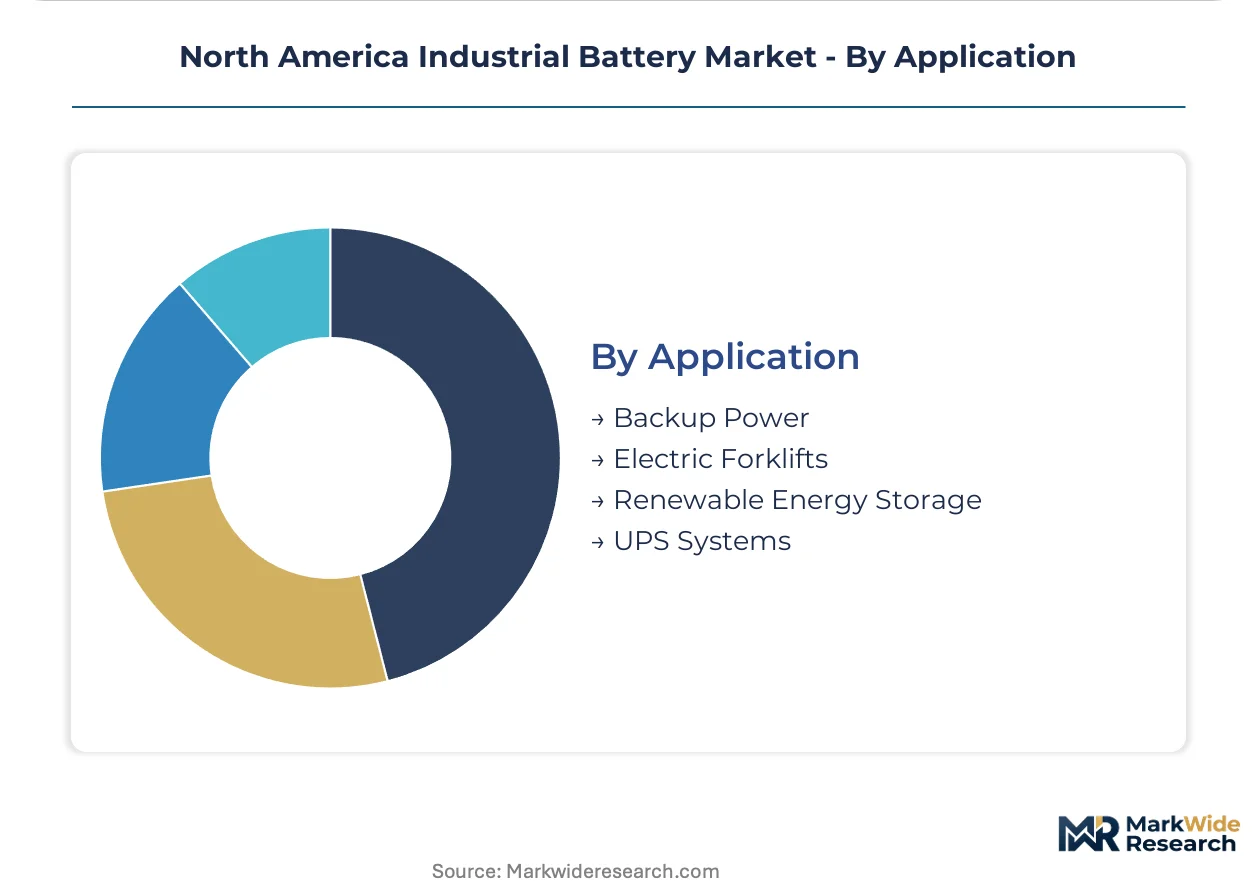
Application:
Volume concentration splits between replacement-driven telecom backup and greenfield grid storage, with UPS systems representing a premium specification segment.
- Backup Power:Diesel generator replacement and grid resilience applications require 15-minute to 4-hour duration capability. Hurricane-prone Florida and Gulf Coast utilities are procuring battery backup for critical infrastructure.
- Electric Forklifts:Class I and II warehouse vehicles operate on 24V to 80V battery systems with opportunity charging protocols. Amazon and Walmart distribution centers in Indiana and Kentucky are trialing lithium-ion conversions on select fleet segments.
- Renewable Energy Storage:Solar and wind integration requires diurnal shifting and ancillary services capability. California ISO resource adequacy procurement mandates are pulling storage capacity into the state from Nevada and Arizona projects.
- UPS Systems:Double-conversion and line-interactive topologies demand instantaneous transfer with 5-15 minute runtime. Northern Virginia data center clusters are specifying lithium iron phosphate for 10-20 MW scale UPS installations.
Backup Power represents the mature replacement cycle. Renewable Energy Storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale buyers in Texas and California exhibit low price elasticity for lithium-ion systems, while material-handling fleets in Ohio and Pennsylvania remain highly sensitive to capital expenditure differentials. This demand-elasticity contrast shapes regional deployment patterns across North America.
United States
Virginia data center clusters and Texas ERCOT corridors are driving hyperscale UPS and grid-scale storage procurement. The Inflation Reduction Act's standalone storage investment tax credit is compressing payback periods for lithium-ion deployments. Northern California's solar-plus-storage pipeline is pulling battery capacity from Nevada and Arizona manufacturing nodes.
Canada
Arctic telecom shelters and rail signaling infrastructure sustain demand for temperature-resilient nickel-cadmium systems. Health Canada and PMRA enforce chemical stewardship protocols affecting cross-border supply chain compliance. Ontario's manufacturing corridor around Toronto anchors motive power battery production serving Great Lakes distribution networks.
Mexico
Baja California and Chihuahua are attracting battery pack assembly operations seeking USMCA duty advantages and proximate supply to Texas grid storage demand. The country's federal environmental regulator enforces hazardous waste rules parallel to EPA frameworks. Mexico City Metro and Monterrey industrial zones are piloting electric bus depot buffering systems.
North America Industrial Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America industrial battery landscape. The vendor base splits between established lead-acid manufacturers with dense service networks and emerging lithium-ion scale-ups pursuing utility-scale procurement contracts. Three strategic archetypes dominate: vertically integrated recyclers with raw material control, motive power service specialists leveraging recurring revenue streams, and grid-storage integrators capturing IRA incentive stacks. Capacity expansion and supply chain requalification for domestic content compliance represent the dominant competitive moves.
Within the established manufacturer tier, EnerSys and East Penn Manufacturing Company exemplify service-network-centric positioning, while Exide Technologies occupies a position representing price-focused competition in predictable replacement segments. These three anchors demonstrate how incumbent lead-acid specialists are navigating chemistry transition pressures while defending installed base positions in capital-sensitive end-use applications.
| Leading Market Players |
|---|
| EnerSys |
| East Penn Manufacturing Company |
| Exide Technologies |
| Johnson Controls International plc |
| C&D Technologies, Inc. |
| GS Yuasa Corporation |
| NorthStar Battery Company, LLC |
| Crown Battery Manufacturing Company |
| A123 Systems LLC |
| Others |
Value Network & Pricing Analysis
Lithium carbonate substitution for lead-acid raw material inputs is simultaneously redrawing extraction geography toward Chilean and Australian salt flats and compressing procurement economics for North American cell assemblers without long-term offtake coverage.
Pricing Analysis
After-sales service contracts and recycling credits drive lifetime value capture for industrial battery vendors. Project-based equipment sales with attached maintenance agreements dominate grid-scale procurement, while motive power segments favor per-unit transactional pricing with volume discounts. Price differentiation rests on UL 9540A certification status and domestic content compliance under IRA provisions. Cost compression in lithium-ion cell assembly is intensifying because raw material volatility outpaces contract pass-through mechanisms. Fleet operators in Ohio and Pennsylvania manufacturing corridors exhibit highest price sensitivity, whereas hyperscale data center buyers in Virginia and Texas prioritize thermal stability specifications over capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of battery-grade lithium salts and electrolyte additives prevails among North American manufacturers confronting raw material volatility, contrasting with just-in-time cathode active material flows from South Korean and Japanese precursor suppliers. Cell assembly capacity concentrates in China, South Korea, and Japan, with Mexico emerging as a USMCA-advantaged pack integration node for Texas grid storage demand. Supply chains draw from Chilean and Australian lithium extraction, Chinese fluorinated electrolyte additive production, and Canadian nickel refining. Single-source vulnerability in electrolyte formulation creates structural risk for thermal stability specifications. Distribution runs through regional integrators serving ERCOT and CAISO interconnection queues with containerized storage system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among hyperscale data center operators and independent power producers, fragmenting price-setting leverage away from incumbent manufacturers toward procurement coalitions with technical specification authority.
For Market Incumbents: Fortify installed base positions in electric forklift fleets through backward integration into lead recycling and captive smelting capacity. Extend service network density in Ohio and Pennsylvania manufacturing corridors to capture recurring revenue streams. Lithium substitution pressure from California and Texas utility procurement teams threatens lead-acid volume retention. Prioritize UL 9540A certification investment to maintain eligibility for grid-scale project shortlists. For New Entrants and Emerging Players: Lead with second-life automotive pack refurbishment for behind-the-meter installations in California and Michigan, where retired electric vehicle batteries create circular feedstock availability. Target Mexico manufacturing migration to capture USMCA duty advantages and proximate supply positioning for Texas ERCOT demand. Pursue solid-state ceramic electrolyte pre-commercial development for data center UPS footprint constraints as the most penetrable white-space application. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed lithium-ion scale-ups pursuing utility-scale procurement contracts and domestic content compliance requalification. Long-term viability over a multi-year horizon favors vendors with integrated recycling capabilities and IRA incentive stack capture. Monitor NERC interconnection queue clearance velocities as the signal to watch for grid-scale deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Requalification | IRA bonus credit eligibility hinges on proving North American assembly and qualifying critical mineral thresholds. |
| Backward Integration into Lead Recycling | In-house smelting capabilities satisfy EPA hazardous waste rules and secure raw material cost control. |
| Second-Life Automotive Pack Refurbishment | Retired California and Michigan electric vehicle batteries create circular feedstock for stationary storage channels. |
| Solid-State Ceramic Electrolyte Development | ARPA-E funding supports pre-commercial research targeting Virginia and Texas data center UPS density constraints. |
| Mexico Manufacturing Migration | Baja California and Chihuahua assembly operations capture USMCA duty advantages for Texas grid storage supply. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility procurement officers, data center infrastructure directors, battery system integrators, and motive power fleet managers; and secondary validation against EIA storage deployment databases, FERC interconnection filings, SEC 10-K disclosures from publicly traded manufacturers, and IRA domestic content guidance documents. Bottom-up triangulation across project-level procurement records and top-down reconciliation against regional grid operator interconnection queues ensured consistency.
Across the projection horizon, the analytical framework modeled chemistry type, end-use application, technology tier, and regional regulatory cluster dimensions. CAGRs were derived from segment-level demand build-ups incorporating IRA incentive phase-out assumptions and lithium carbonate price trajectory scenarios. Forecast inputs included ERCOT and CAISO interconnection queue velocities, NERC reliability standard evolution timelines, and OSHA workplace safety compliance cost projections.
Forecasts assume regulatory continuity in IRA tax credit regimes and EPA hazardous waste enforcement; material policy shifts would require re-modeling. Revision becomes warranted when lithium carbonate price volatility crosses threshold levels that trigger supply contract renegotiation cascades or when NERC interconnection certification timelines extend beyond modeled ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Micro Battery Market
Batteries
Global Battery Market
Batteries
48 Volt Battery System Market
Batteries
18650 And 21700 Battery Market
Batteries
Rechargeable Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Aluminum Wire Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Battery Plate Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Lead Carbon Battery Market
Batteries
East Asia Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Romania Rechargeable Battery Market
Batteries
Drone Lithium Battery Charger Market