
 Electronic Vehicle (EV) Cells Market | 2026-2036
Electronic Vehicle (EV) Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Vehicle (EV) Cells Market Foresight
China's battery megafactory corridor is reconfiguring how cathode-active materials flow into finished cell packs. CATL leverages vertical integration from lithium refining to module assembly across its Ningde and Yibin facilities. LG Energy Solution anchors premium nickel-cobalt-aluminum supply lines for North American and European OEM programs. BYD sustains cost leadership through in-house LFP cathode production and captive electric vehicle demand.
Electronic vehicle cells are electrochemical energy storage devices comprising an anode, cathode, separator, and electrolyte, typically housed in cylindrical, prismatic, or pouch formats with nominal voltages ranging from 3.2V to 4.3V depending on chemistry. Their primary commercial purpose is to store and discharge electrical energy to power traction motors in battery electric and plug-in hybrid vehicles. Lithium-ion cells dominate installed capacity owing to mature manufacturing economics and established recycling infrastructure, while solid-state formats attract R&D capital for their potential energy density gains and reduced thermal runaway risk. Passenger vehicles command the largest application share as consumer range expectations rise, though commercial vehicle segments are gaining traction where total-cost-of-ownership logic favors electrification.
China's MIIT enforces GB standards for cell safety and cycle life that shape product certification timelines for domestic and export-bound manufacturers. The EU's F-Gas Regulation and REACH chemical restrictions constrain electrolyte formulation choices while the EU Green Deal's transport decarbonization targets mandate minimum recycled content in future cell production. In the US, the IRA's domestic content bonuses redirect supply chain investment toward North American cathode and separator plants. Stakeholders must track how regulatory thresholds for carbon intensity and local value addition evolve across these three jurisdictions to avoid stranded capacity commitments.
Market Dynamics
Passenger vehicle electrification is compressing cell procurement cycles as OEMs shift from annual contracts to quarterly price renegotiations tied to lithium carbonate spot markets, forcing manufacturers to absorb volatility or index pricing.
Growth Catalysts
- EU Green Deal transport mandates:Binding zero-emission vehicle sales quotas for 2035 are locking OEMs into multi-year cell offtake agreements, securing demand visibility for gigafactory investments.
- LFP cathode chemistry maturation:Iron phosphate formulations are displacing nickel-rich alternatives in mass-market passenger vehicles, reducing raw material cost exposure and thermal runaway risk.
- Jiangsu-Fujian manufacturing corridor:Co-located precursor refining, cathode production, and cell assembly are compressing logistics costs and lead times for export-bound capacity.
Market Restraints
- Lithium carbonate price volatility:Spot market swings of over 400% since 2021 are destroying margin predictability for cell producers locked into fixed-price automotive contracts.
- Separator supply concentration:Wet-process polypropylene membrane production clusters in South Korea and Japan, creating single-source vulnerability for European and North American cell plants.
- Energy density ceiling:Conventional liquid electrolyte lithium-ion architectures are approaching theoretical limits, capping range extension potential for mainstream vehicle segments.
Strategic Opportunities
- India PLI scheme for ACC batteries:Production-linked incentives covering 50 GWh of domestic cell capacity are attracting cathode and electrolyte suppliers to establish co-located operations.
- Commercial vehicle electrification:Battery-electric buses and medium-duty trucks are creating demand for high-cycle-life LFP configurations with 8,000+ cycle durability requirements.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator technologies are opening pathways to lithium-metal anodes, potentially doubling volumetric energy density for premium passenger vehicles.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturers in Europe and North America are competing for finite pools of experienced dry-room process engineers and formation protocol specialists.
- GB standard certification timelines:China's MIIT safety testing protocols require 12-18 months for new cell formats, delaying product launches for export-focused manufacturers.
- Recyclate qualification complexity:OEM specifications for post-consumer nickel and lithium content are outpacing hydrometallurgical refining capacity, creating feedstock bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Vehicle (EV) Cells Market |
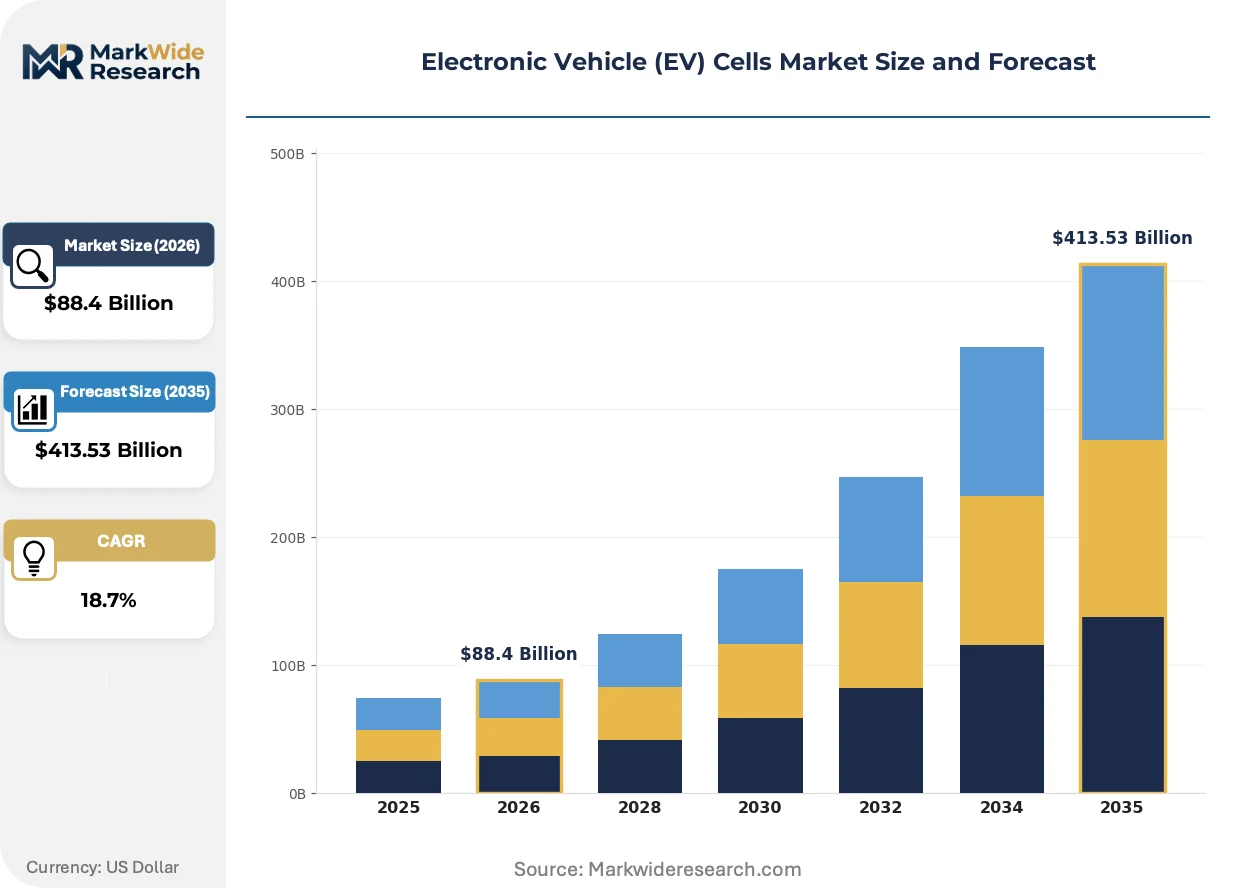
| Market Size in 2026 | $88.4 Billion |
| Market Size in 2035 | $413.53 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead Acid Technology: Battery Management Systems, Thermal Management, Regenerative Braking, Charging Infrastructure End User: OEMs, Fleet Operators, Aftermarket Providers, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | CATL, LG Energy Solution, Panasonic, BYD, Samsung SDI, SK On, Gotion, EVE Energy, Sunwoda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Vehicle (EV) Cells Market Shifts & Advancements
Cell manufacturing is bifurcating between commodity LFP scale plays and premium solid-state technology bets, with equipment suppliers redesigning production lines for chemistry-agnostic flexibility.
Silicon-dominant anodes are rendering obsolete graphite-only electrode designs in premium passenger vehicle segments. Korean cell producers are qualifying 15-20% silicon oxide blends for 2025 model year platforms. This chemistry transition is compressing formation cycle times and requiring dry-room humidity controls below 1% RH.
REACH chemical restrictions are forcing electrolyte reformulation across European-bound cell production. Linear carbonate solvents face substitution pressure from fluorinated alternatives with lower volatility. High-voltage cathode formats above 4.4V nominal are most affected, driving additive supplier consolidation.
Fleet operators are consolidating cell procurement through battery-as-a-service contracts that unbundle asset ownership from energy consumption. Commercial vehicle lessors in California and Germany are piloting per-mile pricing models. This shift is transferring residual value risk from OEMs to financial intermediaries with valuation expertise.
Electronic Vehicle (EV) Cells Market Segmentation
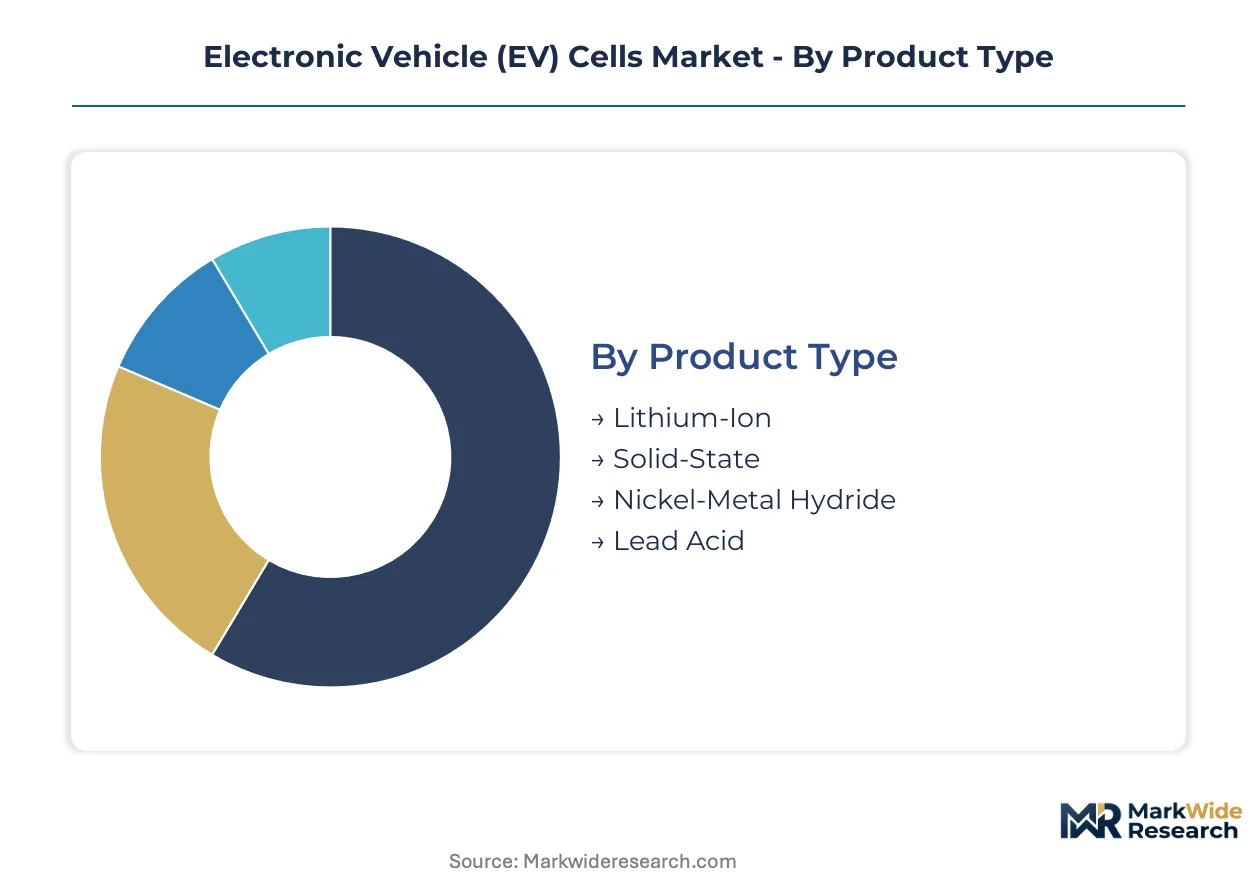
EV cell procurement cycles vary dramatically across segment boundaries. Chemistry selection locks in raw material exposure for years. Application type dictates thermal management specifications and cycle life requirements. Understanding where margins concentrate versus where volumes scale separates viable positioning from stranded capacity.
Product Type:
Cylindrical formats turn inventory fastest in high-volume passenger vehicle programs, while prismatic and pouch configurations sit longer in premium platforms with extended qualification timelines.
- Lithium-Ion:Liquid electrolyte architectures with graphite or silicon-blend anodes and layered oxide cathodes dominate current production. Demand concentrates in China's Jiangsu and Fujian manufacturing corridors where cathode refining and cell assembly co-locate, driven by passenger vehicle electrification mandates from the EU Green Deal and China's MIIT GB standards.
- Solid-State:Ceramic or sulfide electrolyte separators paired with lithium-metal anodes promise energy density gains above 400 Wh/kg. Expansion concentrates in Japanese and South Korean pilot lines targeting premium electric sedans, constrained by dry-room humidity requirements below 1% RH and formation protocol complexity.
- Nickel-Metal Hydride:Mature chemistry with aqueous electrolyte and rare-earth hydride anodes retains niche demand in hybrid-electric vehicle auxiliary power units.
- Lead Acid:Flooded or absorbed glass mat designs persist in low-voltage auxiliary systems and starter batteries for commercial vehicle electrification retrofits.
Lithium-Ion dominates installed base. Solid-State is where expansion concentrates.
Technology:
Cost tiers separate commodity cell management from premium thermal engineering, with mid-tier regenerative integration capturing fleet operator procurement.
- Battery Management Systems:Cell-level voltage and temperature monitoring with state-of-charge estimation algorithms. Demand concentrates in OEM direct procurement programs where functional safety certification to ISO 26262 ASIL-C drives qualification timelines and supplier consolidation.
- Thermal Management:Liquid cold plates, refrigerant loops, and phase-change materials maintaining cell temperatures within 15-35°C operating windows. Expansion concentrates in high-performance passenger vehicles and electric buses where fast-charging protocols generate heat flux exceeding passive dissipation capacity.
- Regenerative Braking:Kinetic energy recovery systems with bi-directional power electronics capturing deceleration energy.
- Charging Infrastructure:Onboard chargers and DC fast-charge port electronics managing grid-to-battery power conversion.
Battery Management Systems anchor value capture in integrated cell-pack assemblies. Thermal Management is climbing the fastest as power density rises and fast-charging becomes standard.
End User:
Volume concentrates with OEMs running multi-year offtake agreements, while margin pools shift toward fleet operators experimenting with battery-as-a-service models.
- OEMs:Original equipment manufacturers specifying cell formats, chemistry, and module architectures for platform integration. Demand concentrates in German and Chinese automotive groups where vertical control over cell supply chains is tightening under IRA domestic content rules and EU battery passport requirements.
- Fleet Operators:Commercial vehicle lessors and logistics companies procuring cells through energy-as-a-service contracts. Expansion concentrates in California and Germany where per-mile pricing models transfer residual value risk from asset owners to financial intermediaries with battery valuation expertise.
- Aftermarket Providers:Independent service facilities and remanufacturers replacing degraded packs in out-of-warranty vehicles.
- Research Institutions:National laboratories and university consortia testing next-generation chemistries and recycling protocols.
OEMs dominate installed base. Fleet Operators are gaining share fastest as commercial vehicle electrification accelerates.
Application:
Passenger vehicles generate volume scale while commercial vehicles offer pricing power through durability specifications and total-cost-of-ownership logic.
- Passenger Vehicles:Battery electric and plug-in hybrid sedans, SUVs, and crossovers requiring 50-100 kWh pack capacities. Demand concentrates in Chinese and European markets where consumer range expectations above 400 km per charge are compressing cell energy density requirements and cathode chemistry selection toward nickel-rich or high-voltage LFP alternatives.
- Commercial Vehicles:Battery-electric buses, delivery vans, and medium-duty trucks with 100-300 kWh configurations and 8,000+ cycle life requirements. Expansion concentrates in urban transit authorities and last-mile logistics operators where overnight depot charging and predictable duty cycles favor LFP chemistry and simplify thermal management design.
- Two-Wheelers:Electric motorcycles and scooters with 2-5 kWh swappable or fixed packs dominating Asian urban mobility.
- Energy Storage Systems:Stationary grid-scale and residential battery installations repurposing automotive cell formats.
Passenger Vehicles dominate installed base. Commercial Vehicles are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the regulatory framework shaping cell safety certification and export compliance timelines for manufacturers targeting domestic and international markets. The country's dual carbon goals and GB standards enforcement create the dominant geography for cathode refining and cell assembly capacity expansion.
China
Jiangsu and Fujian provinces concentrate cathode-active material refining alongside cell pack assembly for export-bound capacity. The MIIT enforces GB standards for cycle life and thermal runaway testing that extend certification timelines to 12-18 months for new formats. Ningde and Yibin facilities exemplify co-located lithium refining through module assembly corridors compressing logistics costs.
Germany
OEM direct procurement programs concentrate in Baden-Württemberg and Lower Saxony where functional safety certification to ISO 26262 ASIL-C drives supplier consolidation. The EU Green Deal's transport decarbonization targets mandate zero-emission vehicle sales quotas locking manufacturers into multi-year offtake agreements. KBA oversight intersects with EU battery passport requirements tightening supply chain traceability.
United States
The IRA's domestic content bonuses redirect cathode and separator plant investment toward North American manufacturing. Michigan and Tennessee anchor OEM platform integration programs where quarterly price renegotiations tied to lithium carbonate spot markets are displacing annual contracting. NHTSA safety protocols and FERC grid interconnection standards shape pack-level thermal management specifications.
South Korea
Wet-process polypropylene separator production clusters in Gyeonggi and Chungcheong provinces, creating supply concentration for European and North American cell plants. MFDS chemical oversight and METI-aligned technical standards influence electrolyte formulation choices for high-voltage cathode formats. Korean producers are qualifying silicon-oxide anode blends for premium passenger vehicle platforms requiring dry-room humidity controls below 1% RH.
India
Tamil Nadu and Gujarat are attracting cathode and electrolyte suppliers establishing co-located operations under the PLI scheme for ACC batteries covering 50 GWh of domestic cell capacity. BIS safety standards and CEA grid codes shape pack integration requirements for commercial vehicle electrification pilots. Maharashtra-based fleet operators are testing per-mile pricing models transferring residual value risk to financial intermediaries.
Electronic Vehicle (EV) Cells Market Competitive Landscape
Integrated battery-chemical conglomerates and specialized cell manufacturers split the market between captive raw material control and flexible chemistry-agnostic production. The structure concentrates around three strategic archetypes: vertically integrated miners-to-modules players, chemistry-focused pure-plays, and automotive-captive producers securing internal demand. Dominant competitive moves include backward integration into lithium refining and cathode precursor production, plus strategic partnerships locking in multi-year offtake volumes with OEM platform programs.
Within the integrated conglomerate tier, CATL and BYD exemplify archetypes spanning lithium refining through module assembly with captive electric vehicle demand anchoring volume certainty. LG Energy Solution occupies a position representing premium nickel-cobalt-aluminum supply line specialization for North American and European OEM qualification programs. These three anchors demonstrate how geographic clustering in China's manufacturing corridor combines with regulatory compliance capabilities across MIIT, EU Green Deal, and IRA jurisdictions to shape competitive positioning.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic |
| BYD |
| Samsung SDI |
| SK On |
| Gotion |
| EVE Energy |
| Sunwoda |
| Others |
Supply & Pricing Matrix
Jiangsu and Fujian manufacturing corridors anchor global cell capacity, compressing cathode-to-assembly logistics costs while amplifying pricing power for producers with co-located precursor refining. Quarterly price renegotiations tied to lithium carbonate spot markets are displacing annual contracting, forcing margin absorption or index-linked pricing structures.
Pricing Analysis
Geographic price spreads between Chinese export-bound capacity and North American IRA-compliant cells exceed 15% on equivalent energy density specifications. Three-tier pricing structure across premium nickel-cobalt-aluminum, standard high-voltage LFP, and economy-grade LFP configurations separates OEM qualification tiers. Pricing pressure stems from lithium carbonate spot volatility destroying margin predictability for fixed-price automotive contracts. Fleet operators demonstrate highest price sensitivity through battery-as-a-service procurement, while premium passenger vehicle OEMs absorb cost premiums for silicon-anode and high-nickel formulations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cathode-active material flows. Cell production draws from Chinese lithium refining, South Korean separator membranes, and Japanese electrolyte additive specialists. Single-source vulnerability concentrates in wet-process polypropylene separator production clustering in Gyeonggi and Chungcheong provinces. Distribution runs through OEM direct procurement programs with multi-year offtake agreements and fleet operator energy-as-a-service intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as battery-as-a-service models unbundle asset ownership from energy consumption, creating interoperability requirements between cell manufacturers and financial intermediaries.
For Market Incumbents: Harden supply chain resilience through backward integration into lithium refining and cathode precursor production, securing captive raw material flows against spot market volatility. Invest in MIIT GB standard certification capabilities to compress 12-18 month approval timelines for new cell formats. Prioritize dry-room process engineering talent acquisition in Europe and North America where formation protocol specialists face acute scarcity.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI scheme for ACC batteries covering 50 GWh of domestic capacity, where cathode and electrolyte supplier co-location remains underdeveloped. Target commercial vehicle electrification segments with 8,000+ cycle life LFP specifications, where total-cost-of-ownership logic favors new entrants over passenger vehicle incumbents. Deploy per-mile pricing models through fleet operator partnerships to transfer residual value risk and bypass OEM qualification barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive-captive producers seeking to monetize non-core cell manufacturing assets amid platform consolidation. Long-term viability centers on chemistry-agnostic production equipment and solid-state electrolyte R&D pipelines. Monitor silicon-anode qualification timelines at Korean producers as inflection indicator for next-generation energy density transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive nickel and lithium refining secures margin control against MIIT and IRA compliance requirements. |
| Solid-State Electrolyte Pilot Scale-Up | Sulfide and oxide ceramic separator investments position for lithium-metal anode transitions above 400 Wh/kg. |
| Battery-as-a-Service Platform Launch | Per-mile pricing models transfer residual value risk to financial intermediaries with valuation expertise. |
| EU Battery Passport Compliance Investment | Supply chain traceability systems satisfy KBA oversight and Green Deal recycled content mandates. |
| Dry-Room Process Engineering Talent Acquisition | Formation protocol specialists enable silicon-oxide anode qualification for premium passenger vehicle platforms. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing executives, OEM platform engineers, cathode procurement leads, and fleet operator energy managers, and refined through secondary validation. Primary fieldwork encompassed dry-room process engineers, formation protocol specialists, and battery-as-a-service financial intermediaries. Secondary sources included MIIT GB standard filings, EU battery passport regulatory drafts, IRA domestic content guidance, customs trade data for lithium carbonate flows, and SEC filings from integrated battery-chemical conglomerates. Bottom-up cell capacity buildouts were triangulated against top-down vehicle electrification mandates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling passenger vehicle, commercial vehicle, two-wheeler, and energy storage system applications alongside lithium-ion, solid-state, nickel-metal hydride, and lead-acid chemistry splits. CAGRs were derived from installed capacity expansion trajectories, OEM offtake agreement visibility, and regulatory mandate enforcement timelines. Forecast inputs incorporated lithium carbonate spot price elasticity, separator supply concentration risk, and solid-state formation protocol yield assumptions.
Sensitivities concentrate around lithium carbonate price volatility, GB standard certification timeline extensions, and IRA domestic content bonus threshold adjustments. Forecasts reflect documented assumptions on cathode chemistry transition speeds and silicon-anode blend adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Traction Battery Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Thermal Interface Material for EV Battery Market