
 Asia-Pacific LFP Battery Pack Market | 2026-2036
Asia-Pacific LFP Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific LFP Battery Pack Market Insights
China's dual carbon goals is pivoting procurement patterns across the Asia-Pacific LFP battery pack value chain. CATL leverages integrated cathode-to-pack manufacturing to sustain cost leadership in electric vehicle applications. BYD Company Ltd anchors its competitive position through proprietary blade cell architecture and captive demand from its automotive division. Gotion High-Tech specializes in modular pack platforms for energy storage system integrators, competing on design flexibility rather than scale alone.
An Asia-Pacific LFP battery pack combines lithium iron phosphate cathode material with graphite anodes in prismatic or blade-form cells, assembled into thermally managed enclosures delivering nominal voltages of 3.2V per cell and cycle lives exceeding 3,000 charge events at 80% depth of discharge. The product serves electric mobility and stationary energy storage applications where safety tolerance and cost-per-kilowatt-hour outweigh gravimetric energy density priorities. Electric vehicles dominates product type revenue, though energy storage systems represents the fastest-expanding application segment as renewable energy penetration rises across the region. Smart BMS technology is capturing margin pools through cell-level monitoring and predictive thermal management, while liquid cooling configurations lead in premium electric mobility platforms where sustained discharge rates stress passive thermal designs.
China's MIIT enforces GB standards for battery safety and recycling traceability, while India's BIS certification mandates and PLI scheme eligibility criteria shape import substitution trajectories for domestic pack assembly. Japan's METI directs funding toward solid-state alternatives but maintains JIS standards that LFP packs must satisfy for industrial equipment integration. Stakeholders must monitor how evolving carbon border adjustment mechanisms and country-of-origin rules for critical minerals reshape sourcing economics across Southeast Asian pack assembly hubs.
Market Dynamics
China's dual carbon goals and India's PLI scheme for advanced chemistry cells are redirecting capital toward domestic LFP gigafactories, compressing import dependency and reshaping regional procurement corridors.
Growth Catalysts
- MIIT's GB standards enforcement:China's mandatory battery safety and recycling traceability protocols are accelerating fleet electrification timelines across municipal bus operators.
- Blade cell architecture adoption:Prismatic form factors with enhanced thermal stability are displacing cylindrical alternatives in premium electric mobility platforms.
- Jiangsu-Guangdong production clusters:Cathode material and cell manufacturing co-location with downstream pack assembly is compressing logistics costs and lead times.
Market Restraints
- Graphite anode supply concentration:Spherical graphite processing capacity concentrates in China's Shandong and Heilongjiang provinces, creating single-source vulnerability.
- Gravimetric energy density ceiling:LFP chemistry's inherent cathode material limitation constrains pack-level range performance in long-haul electric trucking applications.
- BIS certification timelines:India's Bureau of Indian Standards testing protocols extend product qualification cycles for imported cell components.
Strategic Opportunities
- Indonesia's nickel-to-LFP pivot:The country's mineral processing investments are creating downstream cathode precursor supply for ASEAN pack assembly hubs.
- Smart BMS integration:Cell-level monitoring and predictive thermal management systems are capturing margin pools from commodity pack assemblers.
- Stationary energy storage convergence:Renewable energy penetration across Vietnam and Thailand is opening procurement channels for modular ESS platforms.
Industry Challenges
- Thermal management engineering scarcity:Liquid cooling system design expertise concentrates with tier-one automotive suppliers, constraining second-tier pack integrator capabilities.
- Gigafactory capex intensity:Cell production equipment and dry room infrastructure requirements limit viable entry to state-backed or automotive-captive consortia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific LFP Battery Pack Market |
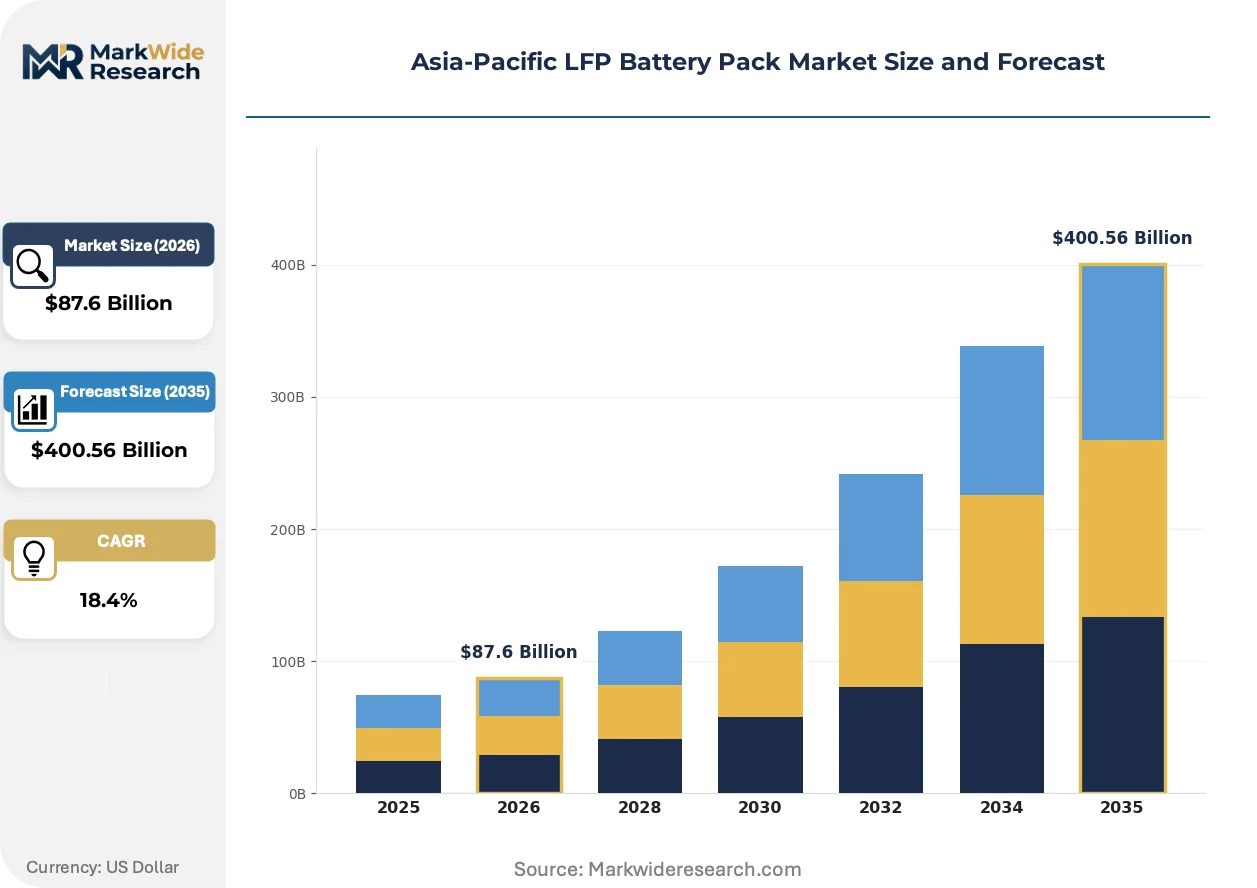
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Equipment End User: Manufacturers, Distributors, Retailers, OEMs Technology: Liquid Cooling, Air Cooling, Modular Design, Smart BMS Application: Renewable Energy, Electric Mobility, Backup Power, Grid Stabilization |
| Companies Covered | CATL, BYD Company Ltd, CALB, Panasonic Corporation, LG Chem, Samsung SDI, Gotion High-Tech, A123 Systems, EVE Energy, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific LFP Battery Pack Market Trends and Innovations
Cell-to-pack structural integration and intelligent battery management systems are compressing traditional module-tier value extraction, while regulatory carbon accounting is reshaping sourcing verification protocols.
Cell-to-pack architecture is consolidating manufacturing steps by eliminating module housings and interconnection layers. Electric vehicle OEMs are adopting this design at scale for their new platform generations. The structural simplification is consolidating tier-two module suppliers into pack-assembly-only operations.
India's PLI scheme eligibility criteria are mandating domestic value-add thresholds for cell and pack production. The industrial consequence is redirecting cathode active material investments toward Gujarat and Tamil Nadu manufacturing zones. Energy storage system integrators are responding by establishing captive pack assembly to qualify for incentive disbursement.
Long-term service agreements are displacing transactional pack sales in fleet operator procurement. Bus and commercial vehicle fleet managers are contracting for guaranteed cycle life performance rather than capital equipment purchase. This shift is most visible across Chinese state-owned transport authorities and emerging Indian electric bus tenders.
Asia-Pacific LFP Battery Pack Market Segmentation
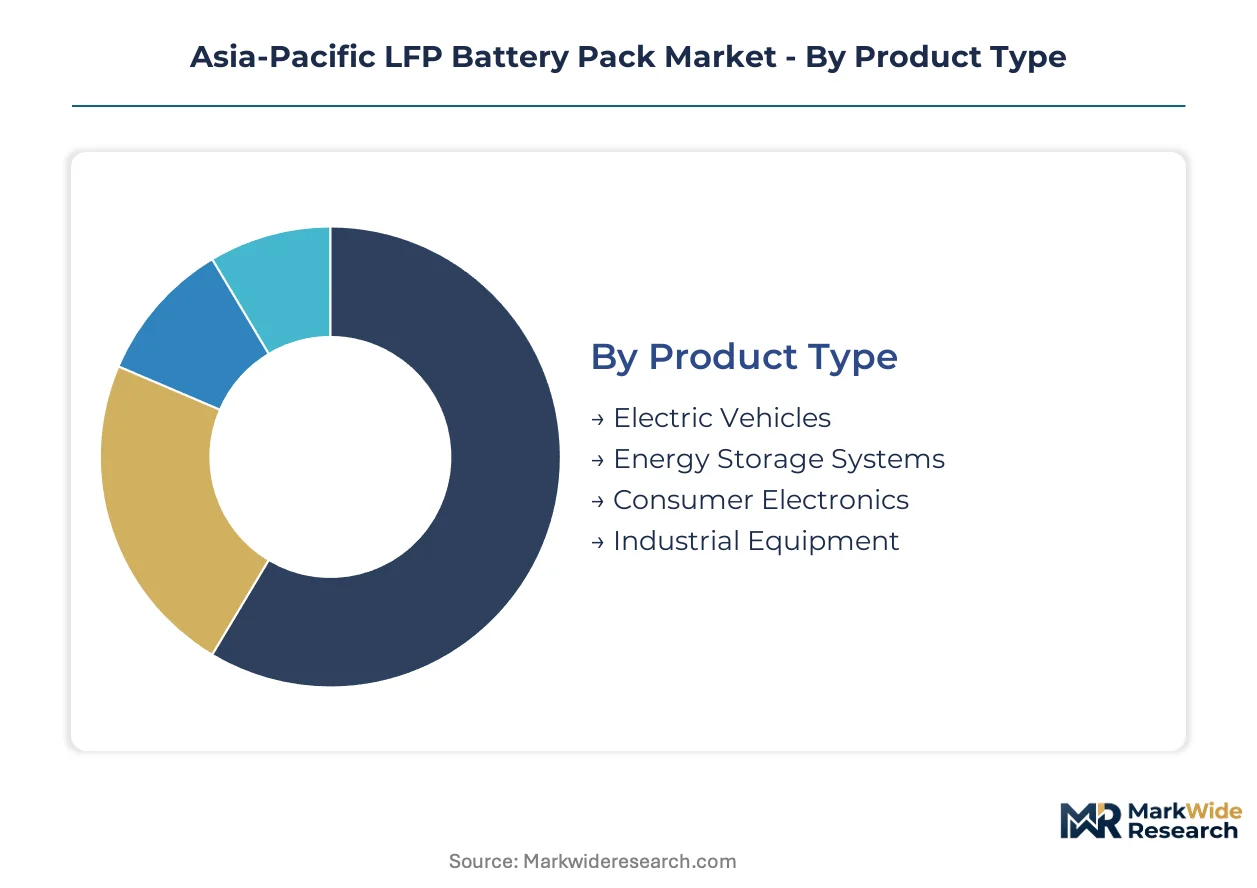
Segmentation in the Asia-Pacific LFP battery pack market reveals how cathode chemistry specifications, thermal management architectures, and downstream application requirements partition procurement behavior. Buyers across electric mobility and stationary storage verticals impose distinct validation protocols on pack suppliers.
Product Type:
Cell-to-pack integration density and cycle life specifications differentiate procurement economics across downstream verticals.
- Electric Vehicles:Blade cell and prismatic configurations dominate automotive platforms, with Jiangsu and Guangdong province clusters supplying integrated pack-to-vehicle assembly lines. Fleet electrification mandates from Chinese municipal bus operators compress qualification timelines for high-volume suppliers.
- Energy Storage Systems:Modular rack architectures with 3,000+ cycle ratings serve utility-scale renewable integration across Vietnam and Thailand. ESS procurement is expanding most quickly as grid operators impose frequency regulation requirements on solar and wind assets.
- Consumer Electronics:Compact pouch and cylindrical formats address portable power tools and residential backup units with lower discharge rate requirements.
- Industrial Equipment:Ruggedized enclosures with IP67 ratings serve forklift and automated guided vehicle fleets in Japanese manufacturing zones.
Electric vehicles leads on scale; energy storage systems leads on momentum.
End User:
Channel position determines margin capture and technical support obligations in the value chain.
- Manufacturers:CATL and BYD operate captive cathode-to-pack operations serving internal automotive divisions and external OEM contracts.
- Distributors:Regional logistics hubs in Singapore and Hong Kong manage inventory for Southeast Asian project developers with fragmented demand patterns.
- Retailers:E-commerce platforms and industrial supply houses serve replacement pack demand for consumer and light commercial applications.
- OEMs:Bus and commercial vehicle assemblers specify pack performance guarantees rather than component procurement, shifting warranty risk upstream.
Manufacturers capture value through backward integration; OEMs are restructuring procurement toward outcome-based contracting.
Technology:
Thermal management sophistication separates premium platforms from commodity pack assemblies.
- Liquid Cooling:Aluminum cold plate and coolant loop architectures sustain sustained C-rate discharge in premium electric mobility platforms. Engineering talent for liquid cooling system design concentrates with tier-one automotive suppliers, constraining second-tier integrator capabilities.
- Air Cooling:Passive fin-and-fan configurations serve lower-duty-cycle applications where pack mass and cost tolerance favor simplicity over thermal headroom.
- Modular Design:Standardized rack units with hot-swappable cell strings reduce downtime for utility-scale ESS operators.
- Smart BMS:Cell-level voltage and temperature monitoring with predictive algorithms captures margin pools from commodity assemblers through software-enabled lifecycle optimization.
Liquid cooling dominates premium mobility; smart BMS is gaining share fastest through software differentiation.
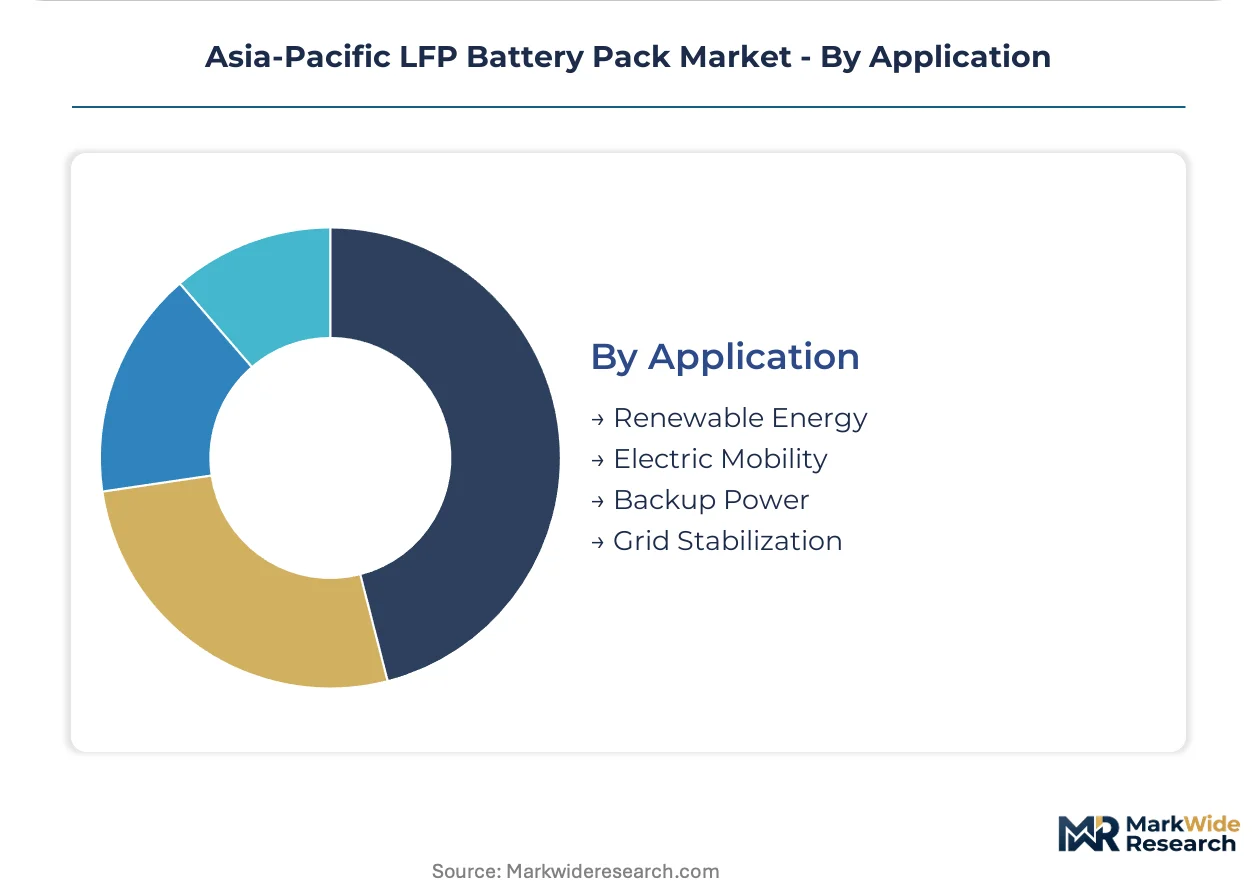
Application:
Grid service requirements and duty cycle profiles shape pack specification and validation protocols.
- Renewable Energy:Solar-plus-storage and wind farm co-location projects across India and Australia demand 6,000+ cycle warranties with guaranteed round-trip efficiency.
- Electric Mobility:State-owned transport authorities in China and emerging Indian electric bus tenders impose GB standards and BIS certification requirements on fleet suppliers.
- Backup Power:Data center and telecommunications applications prioritize instantaneous response over energy density, favoring LFP safety characteristics.
- Grid Stabilization:Frequency regulation and peak shaving services in Japan and South Korea require sub-second response times with high cycling tolerance.
Electric mobility commands current volume; renewable energy is climbing the fastest as auction mechanisms expand across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium iron phosphate chemistry achieved commercial scale in Chinese cathode plants during the early 2010s, establishing production protocols that now dominate Asia-Pacific pack assembly. Jiangsu and Guangdong provinces remain the historical core where cathode material fabrication first integrated with downstream cell manufacturing.
China
MIIT's GB standards enforcement and dual carbon goals accelerate municipal bus fleet electrification across Beijing, Shanghai, and Shenzhen. Jiangsu province hosts cathode-to-pack manufacturing clusters where CATL and BYD operate integrated production lines adjacent to automotive OEM assembly plants.
India
State-owned transport authorities in Delhi, Mumbai, and Bangalore tender electric bus contracts requiring BIS-certified LFP packs. The PLI scheme for advanced chemistry cells redirects capital toward Gujarat and Tamil Nadu manufacturing zones where domestic gigafactory construction is underway.
Japan
Industrial equipment integrators in Osaka and Nagoya specify JIS-compliant LFP packs for forklift and automated guided vehicle fleets. METI directs public funding toward solid-state alternatives while maintaining safety standards that LFP chemistry satisfies for manufacturing automation applications.
South Korea
Grid stabilization operators in Seoul and Busan procure high-cycling LFP packs for frequency regulation services supporting renewable penetration. Domestic cell manufacturers face margin pressure from Chinese imports while supplying premium liquid-cooled configurations for domestic electric mobility platforms.
Vietnam
Solar-plus-storage project developers in Ho Chi Minh City and Hanoi source modular ESS racks with extended cycle warranties. Renewable energy auction mechanisms expand procurement channels for utility-scale battery installations serving transmission congestion relief.
Asia-Pacific LFP Battery Pack Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal management sophistication and BMS integration depth. The vendor base stratifies into three tiers: automotive-captive manufacturers with cathode-to-pack integration, independent cell suppliers serving third-party assemblers, and project-focused ESS integrators competing on design flexibility. Dominant competitive moves include backward integration into cathode active material production and geographic expansion through ASEAN assembly hub establishment.
Within the integrated-manufacturer tier, CATL and BYD Company Ltd occupy positions defined by captive demand from automotive divisions and proprietary cell architectures. Gotion High-Tech represents the modular-platform specialist archetype, competing through design flexibility for energy storage system integrators rather than scale alone. These three anchors exemplify how competitive positioning in Asia-Pacific LFP battery packs depends on vertical scope choices between cathode material control and downstream application specialization.
| Leading Market Players |
|---|
| CATL |
| BYD Company Ltd |
| CALB |
| Panasonic Corporation |
| LG Chem |
| Samsung SDI |
| Gotion High-Tech |
| A123 Systems |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
Cathode active material costs cascade through three distinct pricing tiers before reaching fleet procurement contracts, with Jiangsu province cathode plants feeding premium liquid-cooled packs for municipal bus operators while commodity air-cooled configurations serve Southeast Asian ESS project developers under thinner margin structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled automotive platforms with smart BMS integration from modular ESS racks and basic industrial forklift packs. Price differentiation rests on thermal management sophistication and GB standards certification tier. Cost compression in the economy tier intensifies as Indonesian nickel-to-LFP pivot investments expand cathode precursor supply. Fleet operators represent the most price-sensitive buyers, while data center backup power procurement shows lowest sensitivity due to safety-critical application requirements.
Supply Chain Analysis
Engineering talent scarcity in liquid cooling system design concentrates in Shanghai and Shenzhen manufacturing zones, constraining second-tier pack integrator capabilities across the region. Geographic supply concentration centers on China, South Korea, and Japan for cell production equipment and dry room infrastructure. Raw material dependencies draw from Australian spodumene concentrate, Chilean lithium carbonate, and Chinese spherical graphite processing. Single-source vulnerability runs through Shandong province graphite anode capacity. Distribution runs through Singapore and Hong Kong logistics hubs serving fragmented Southeast Asian project demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific LFP battery pack market represents a late-cycle quality story where procurement is shifting toward guaranteed cycle life performance contracts rather than capital equipment purchase, rewarding suppliers with validated thermal management and predictive BMS capabilities.
For Market Incumbents: Extend backward integration into cathode active material production to defend margin position against Indonesian nickel-to-LFP pivot investments compressing precursor costs. Anchor capacity expansion in Gujarat and Tamil Nadu manufacturing zones to capture India's PLI scheme disbursement eligibility. Prioritize smart BMS software development as solid-state alternatives from METI-funded Japanese programs threaten long-term chemistry relevance. For New Entrants and Emerging Players: Launch via modular ESS platform specialization targeting Vietnam and Thailand utility-scale solar-plus-storage auction mechanisms. Penetrate the stationary energy storage segment fastest-expanding application vertical where design flexibility outweighs scale advantages held by integrated automotive-captive manufacturers. Establish captive pack assembly operations to qualify for India's domestic value-add thresholds. For Investors and Strategic Acquirers: Consolidation pressure builds where gigafactory capex intensity limits viable entry to state-backed or automotive-captive consortia, squeezing independent cell suppliers serving third-party assemblers. Target acquisition archetype: modular-platform specialists with validated ESS integration credentials and established ASEAN assembly hub presence. Watch for inflection where carbon border adjustment mechanisms reshape sourcing economics across Southeast Asian pack assembly corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Material | CATL and BYD sustain cost leadership through captive cathode-to-pack manufacturing in Jiangsu province clusters. |
| Smart BMS Technology Licensing | Cell-level monitoring and predictive thermal management capture margin pools from commodity pack assemblers. |
| ASEAN Assembly Hub Establishment | Singapore and Hong Kong logistics hubs enable inventory management for fragmented Southeast Asian ESS demand. |
| Long-Term Service Agreement Structuring | Chinese state-owned transport authorities contract for guaranteed cycle life performance rather than capital equipment purchase. |
| GB Standards and BIS Certification Investment | MIIT enforcement and India's PLI eligibility criteria redirect procurement toward qualified domestic pack suppliers. |
Research Methodology
Direct dialogue with battery pack engineering directors, ESS project developers, fleet procurement managers, and cathode material plant operators grounded the qualitative assessment, cross-referenced with MIIT GB standards documentation, India's PLI scheme eligibility filings, customs trade data for lithium carbonate and spherical graphite, and vehicle production databases from IHS Markit. Bottom-up and top-down triangulation validated volume estimates across the projection horizon.
Bottom-up modeling segmented the market by product type, end user, technology, and application, with particular attention to thermal management architecture and BMS integration depth as value-capture differentiators. Top-down validation drew from regional automotive OEM procurement disclosures and utility-scale ESS auction announcements across Vietnam and Thailand. CAGRs were derived from installed base growth trajectories and replacement cycle assumptions. Forecast inputs incorporated MIIT fleet electrification timelines and India's BIS certification throughput constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden graphite anode supply disruption or accelerated solid-state chemistry substitution from METI-funded Japanese programs. Forecasts reflect assumptions regarding PLI scheme disbursement continuity and ASEAN renewable energy auction mechanism expansion. Material deviation in carbon border adjustment implementation timelines or critical minerals country-of-origin rule changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Traction Battery Market
EV Batteries
China EV Battery Pack Market
EV Batteries
EV Batteries Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle Battery Materials Market