
 France Electric Vehicle Battery Manufacturing Market | 2026-2036
France Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Manufacturing Market Insights
Project finance tied to automotive OEM offtake agreements is rewriting competitive entry conditions for France's battery sector. Verkor leverages its Dunkirk gigafactory financing structure to anchor large-scale lithium-ion output. Saft Groupe S.A. specializes in advanced cell chemistries for premium mobility applications. Automotive Cells Company sustains its position through integrated cathode active material production.
France electric vehicle battery manufacturing encompasses the industrial production of electrochemical energy storage systems, typically lithium-ion cells with nickel-cobalt-manganese or lithium-iron-phosphate cathodes, assembled into modules and packs for traction applications. Battery cells dominate value capture, while solid-state technology represents the fastest-advancing segment as manufacturers compete on energy density thresholds. OEM end users command the largest procurement volumes, though electric fleet operators are emerging as a concentrated growth channel for standardized pack formats.
France's national implementation of the EU Battery Regulation, enforced by national market surveillance authorities under CE marking frameworks, mandates recycled content minimums and supply chain due diligence. DGCCRF oversight on product safety and the EU's forthcoming digital battery passport requirements shape design and traceability investments. Stakeholders must track how carbon border adjustments on imported cells interact with domestic manufacturing incentives to determine optimal sourcing and production location decisions.
Market Dynamics
The EU Battery Regulation's carbon footprint thresholds and recycled content mandates are forcing French manufacturers to reconfigure cathode supply chains and secure European-sourced precursor materials ahead of compliance deadlines.
Growth Catalysts
- EU Battery Regulation mandates:France's DGCCRF enforces recycled lithium minimums that pull domestic gigafactory output toward circular production models.
- Hauts-de-France cluster concentration:Dunkirk's port infrastructure and grid connectivity anchor cathode active material plants alongside cell assembly.
- Lithium-iron-phosphate chemistry:Lower nickel dependence reduces exposure to Class 1 nickel price volatility while meeting fleet operator range requirements.
Market Restraints
- Lithium hydroxide supply concentration:Spodumene processing capacity bottlenecks in Western Australia translate to feedstock insecurity for French cathode plants.
- CE marking compliance costs:Digital battery passport traceability systems require capital outlays that compress margins for sub-gigawatt-hour producers.
- Solid-state timeline uncertainty:Sulfide electrolyte moisture sensitivity delays commercialization beyond current lithium-ion contract horizons.
Strategic Opportunities
- Nouvelle-Aquitaine industrial corridor:Bordeaux's automotive heritage and Atlantic port access position the region for second-wave gigafactory deployment.
- Electric fleet standardization:Commercial vehicle operators in Île-de-France seek swappable pack formats that bypass cell-level procurement complexity.
- EU Green Deal industrial funding:Innovation Fund and Important Projects of Common European Interest financing de-risk cathode precursor investments.
Industry Challenges
- Electrolyte formulation talent scarcity:France's chemical engineering pipeline lacks sufficient specialists in non-flammable additive development.
- Module-to-pack integration complexity:Thermal runaway propagation testing under UN 38.3 extends certification timelines for novel cell-to-pack architectures.
- Legacy automotive tooling incompatibility:Existing Stellantis and Renault assembly lines require retrofitting for battery-electric skateboard platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Manufacturing Market |
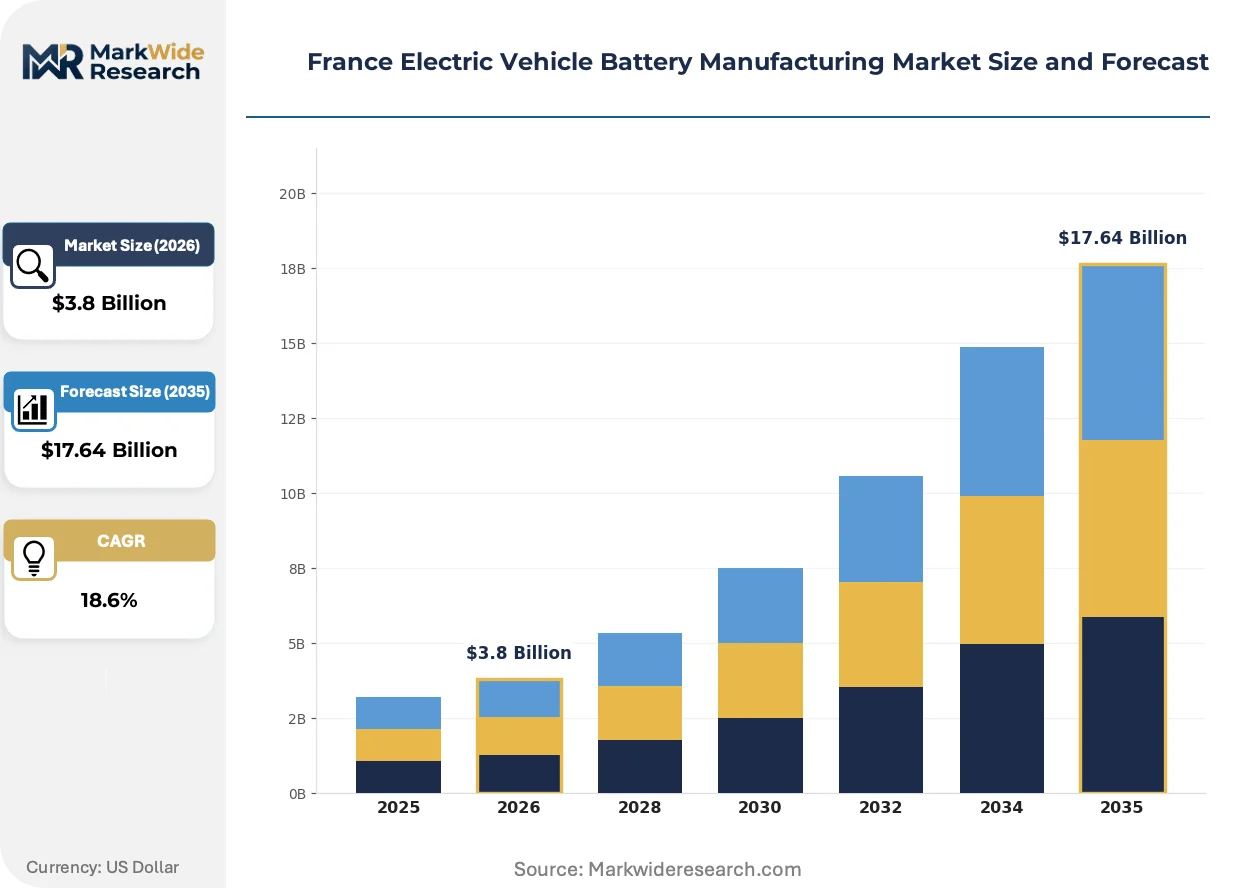
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Battery Cells, Battery Packs, Battery Management Systems, Thermal Management Systems Technology: Lithium-ion, Solid-State, Nickel-Metal Hydride, Lead-Acid End User: OEMs, Aftermarket Providers, Electric Fleet Operators, Charging Infrastructure Providers Production Stage: Manufacturing, Assembly, Testing, Recycling |
| Companies Covered | Verkor, Contemporary Amperex Technology Co. Limited, Saft Groupe S.A., Automotive Cells Company, Envision AESC, ProLogium, Blue Solutions, Forsee Power, LG Energy Solution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell chemistry evolution, regulatory traceability mandates, and fleet procurement consolidation are compressing traditional supplier-OEM contracting models across French battery manufacturing.
Solid-state electrolyte research is hybridizing sulfide and oxide material systems to bridge the gap between ionic conductivity and manufacturing scalability. French materials startups target automotive OEM pilot programs for 2026-2027 validation cycles. This hybridization is compressing the timeline for silicon-anode integration by reducing interfacial instability risks.
France's transposition of the EU Battery Regulation through DGCCRF enforcement creates binding due diligence obligations for cobalt and lithium sourcing. Manufacturers must deploy blockchain-anchored supply chain documentation to satisfy upcoming digital passport requirements. The cathode active material segment faces the steepest compliance burden as origin verification cascades through precursor chemical suppliers.
Fleet operators in Paris and Lyon are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle acquisition. This model transfers residual value risk to manufacturers while demanding standardized pack geometries across multiple OEM platforms. The shift is most visible in last-mile delivery electrification where route predictability enables precise cycle-life pricing.
France Electric Vehicle Battery Manufacturing Market Segmentation
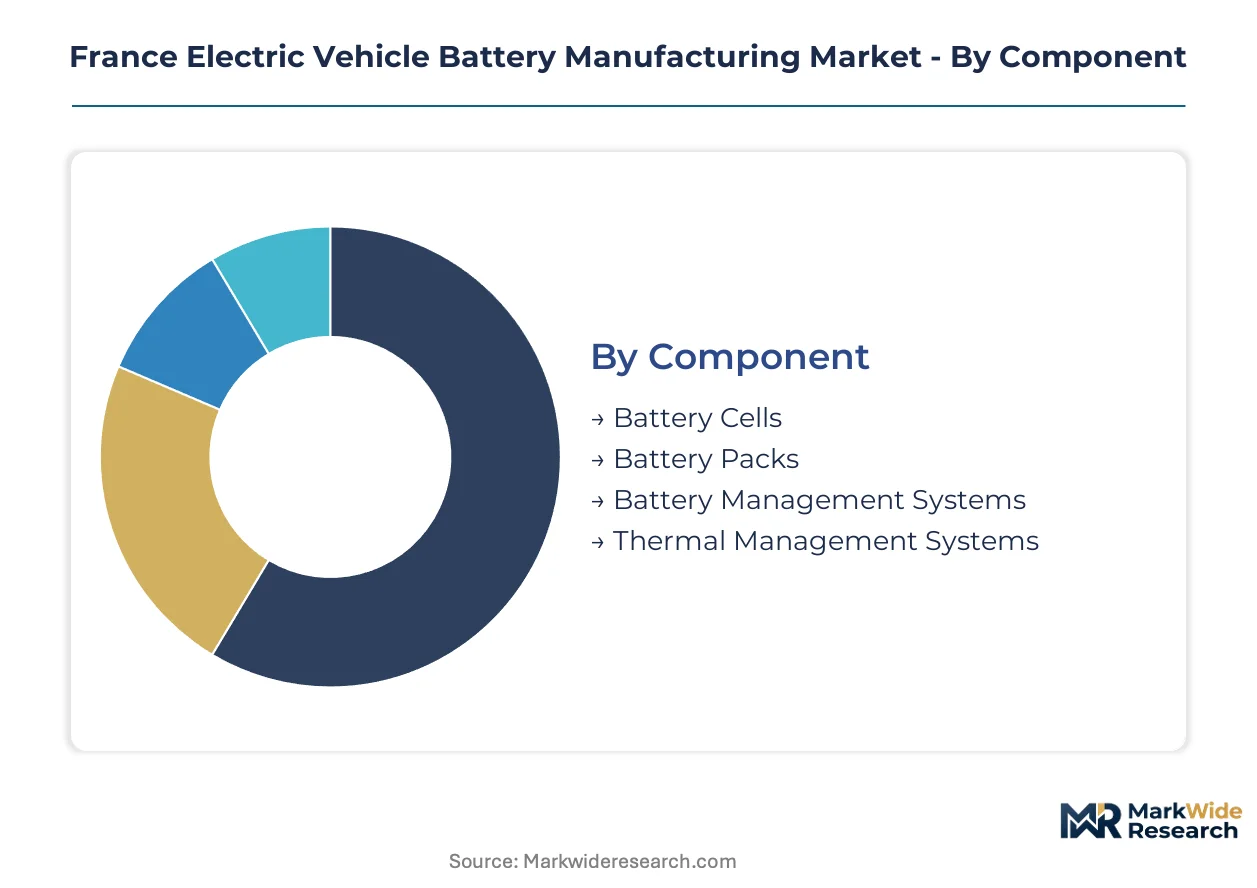
France's battery manufacturing sector segments across four critical dimensions that determine capital allocation, margin structure, and regulatory exposure. Each category reflects distinct competitive dynamics shaped by EU Battery Regulation compliance timelines and domestic industrial clustering.
Component:
Mature cell production anchors value capture while emerging thermal and battery management systems reshape system-level differentiation.
- Battery Cells:Electrochemical energy storage units utilizing nickel-cobalt-manganese or lithium-iron-phosphate cathodes constitute the highest-value manufacturing tier. Hauts-de-France gigafactories concentrate cathode active material production alongside cell assembly to satisfy carbon footprint mandates under DGCCRF enforcement.
- Battery Packs:Module-to-pack integration with cell-to-pack architectures eliminates intermediate module housings, reducing weight and cost. Renault and Stellantis procurement specifications drive standardization pressures across Nouvelle-Aquitaine assembly facilities.
- Battery Management Systems:Electronic control platforms monitor cell voltage, temperature, and state-of-charge with functional safety requirements under ISO 26262.
- Thermal Management Systems:Liquid cooling circuits and phase-change materials prevent thermal runaway propagation in high-energy-density configurations.
Battery Cells handles the majority of throughput; Thermal Management Systems is the fastest mover on share.
Technology:
Cost tier stratification separates mass-market chemistries from premium solid-state development programs absorbing disproportionate R&D investment.
- Lithium-ion:Dominant electrochemistry spanning NCM layered oxides and LFP olivine structures with established supply chains for electrolyte salts and separators. French OEM offtake agreements from Verkor and ACC lock in volume commitments through Hauts-de-France production.
- Solid-State:Sulfide and oxide electrolyte systems promise energy density thresholds exceeding current lithium-ion limits by eliminating flammable liquid electrolytes. Pilot production lines in Grenoble and Bordeaux target automotive validation cycles with moisture-sensitive manufacturing protocols.
- Nickel-Metal Hydride:Mature chemistry retaining niche applications in hybrid electric vehicles where power density requirements exceed energy density priorities.
- Lead-Acid:Legacy technology constrained to auxiliary power units and low-voltage systems by weight and cycle-life limitations.
Lithium-ion handles the majority of throughput; Solid-State is expanding most quickly on share.
End User:
Customer type fragmentation splits between integrated OEM procurement and emerging service-based models transferring residual value risk.
- OEMs:Integrated automotive manufacturers specify cell formats, chemistry ratios, and pack geometries through multi-year offtake agreements. Stellantis and Renault sourcing committees prioritize domestic gigafactory output to secure CE marking compliance under EU Battery Regulation carbon footprint thresholds.
- Electric Fleet Operators:Commercial vehicle and last-mile delivery consolidators in Île-de-France adopt battery-as-a-service contracts decoupling cell ownership from vehicle acquisition. Route predictability enables precise cycle-life pricing and standardized swappable pack formats across multiple OEM platforms.
- Aftermarket Providers:Independent service networks address replacement demand and refurbishment outside OEM warranty channels.
- Charging Infrastructure Providers:Stationary storage integrators repurpose end-of-life automotive cells for grid-buffering applications.
OEMs handles the majority of throughput; Electric Fleet Operators is climbing the fastest on share.
Production Stage:
Geographic concentration across France's industrial corridors segments value-add intensity from raw material conversion to circular recovery.
- Manufacturing:Cathode precursor synthesis, electrode coating, and cell formation constitute the highest capital-intensity stage. Dunkirk's port infrastructure enables integrated precursor-to-cell production with direct maritime access to lithium hydroxide feedstocks.
- Assembly:Module and pack integration with thermal management component mounting occurs proximate to OEM final assembly plants. Bordeaux's Atlantic corridor positioning supports second-wave gigafactory deployment with automotive heritage supply base access.
- Testing:UN 38.3 certification and thermal runaway propagation validation extend timelines for novel cell-to-pack architectures.
- Recycling:Hydrometallurgical and pyrometallurgical recovery of lithium, cobalt, and nickel closes material loops under EU Battery Regulation recycled content minimums.
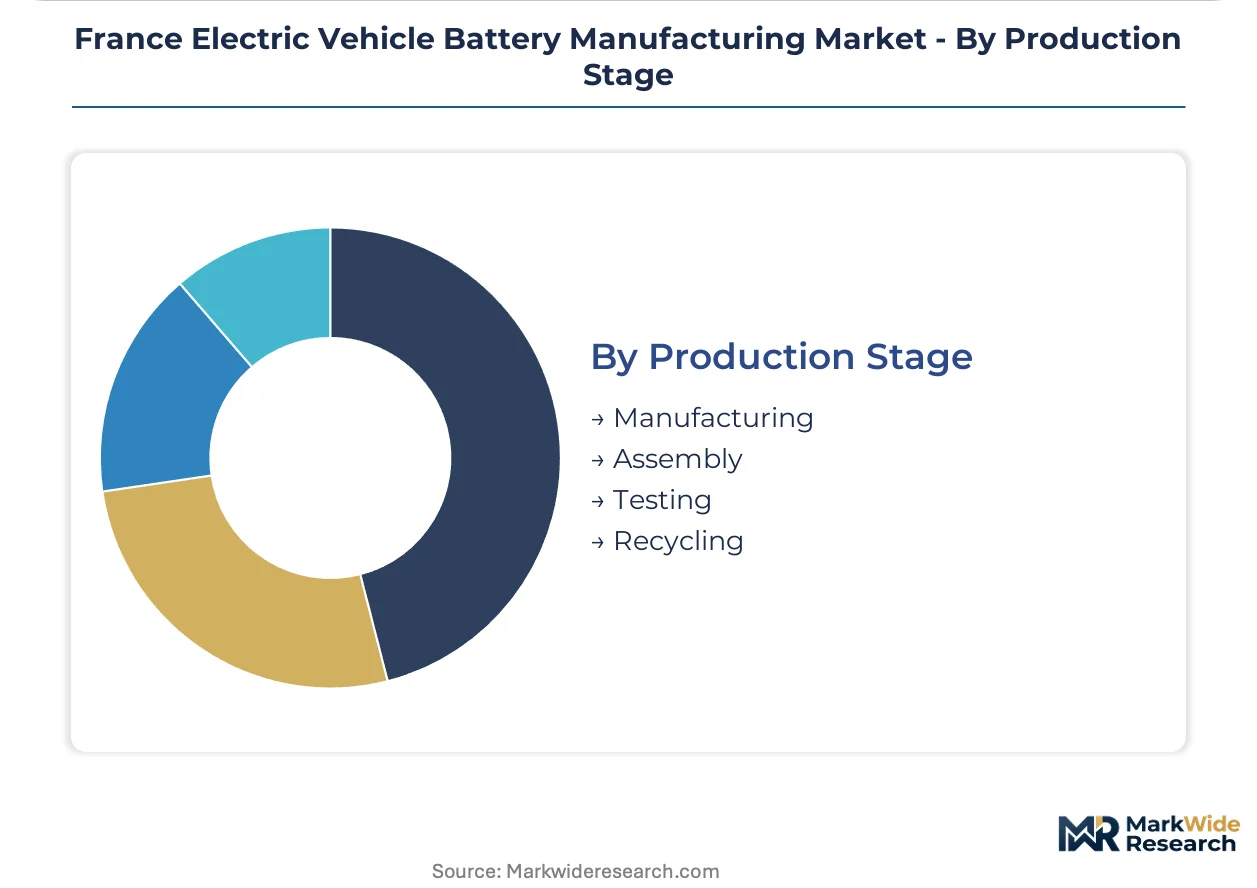
Manufacturing handles the majority of throughput; Recycling is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hauts-de-France commands pricing leverage through integrated cathode-to-cell production, while Nouvelle-Aquitaine competes on Atlantic port access for lithium hydroxide feedstocks. This asymmetry shapes investment flows across French industrial corridors.
Hauts-de-France
Dunkirk's port infrastructure and grid connectivity anchor cathode active material plants alongside Verkor's gigafactory assembly. DGCCRF enforcement of EU Battery Regulation carbon footprint thresholds pulls domestic output toward circular production models. The cluster concentrates electrode coating and cell formation capacity with direct maritime access to Western Australian spodumene supply chains.
Nouvelle-Aquitaine
Bordeaux's automotive heritage supply base supports second-wave gigafactory deployment targeting fleet operator procurement. Regional authorities coordinate Atlantic corridor positioning with CE marking compliance frameworks for module-to-pack integration. The sub-region attracts testing and validation facilities for novel cell-to-pack architectures serving Stellantis assembly requirements.
Île-de-France
Paris and Lyon fleet operators consolidate demand through battery-as-a-service contracts that unbundle cell ownership from vehicle acquisition. Route predictability in last-mile delivery electrification enables precise cycle-life pricing across standardized swappable pack formats. The metropolitan concentration drives software and battery management system development for commercial vehicle applications.
Auvergne-Rhône-Alpes
Grenoble's materials science ecosystem hosts solid-state electrolyte pilot production lines targeting automotive OEM validation cycles. Research institutions bridge sulfide and oxide material system hybridization to reduce interfacial instability risks. The cluster specializes in moisture-sensitive manufacturing protocols for next-generation cell chemistries.
France Electric Vehicle Battery Manufacturing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cathode active material and thermal management subsystems. The French battery sector exhibits tiered concentration with gigafactory-scale producers anchoring volume commitments while mid-scale fabricators occupy niche chemistry segments. Two strategic archetypes dominate: integrated cell-to-pack manufacturers securing multi-year OEM offtake agreements, and materials-focused specialists advancing solid-state electrolyte formulations. Competitive moves center on backward integration into cathode precursor supply and strategic partnerships for lithium hydroxide feedstock security.
Within the integrated manufacturing tier, Verkor and Automotive Cells Company exemplify platform-scale entry through Dunkirk-based production capacity. Saft Groupe S.A. occupies a specialist position in advanced cell chemistries for premium mobility applications. These three entities represent divergent strategic postures: volume-anchored domestic supply security versus differentiated chemistry development for constrained application segments.
| Leading Market Players |
|---|
| Verkor |
| Contemporary Amperex Technology Co. Limited |
| Saft Groupe S.A. |
| Automotive Cells Company |
| Envision AESC |
| ProLogium |
| Blue Solutions |
| Forsee Power |
| LG Energy Solution |
| Others |
Pricing and Supply Chain Analysis
Dunkirk's maritime corridor to Western Australian spodumene terminals concentrates freight cost volatility into cathode precursor pricing, compressing margins for sub-gigawatt-hour producers while amplifying volume discounts for integrated Hauts-de-France gigafactories serving Stellantis and Renault procurement committees.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with three-tier differentiation across premium high-nickel NCM, standard LFP, and economy-tier hybrid chemistries. Price differentiation rests on CE marking certification tier and cathode active material integration depth. Cost compression in economy-tier LFP is intensifying because Chinese cell imports undercut domestic formation capacity. Fleet operators exhibit highest price sensitivity due to battery-as-a-service margin constraints, while premium mobility OEMs show lowest sensitivity for solid-state pilot programs.
Supply Chain Analysis
Spodumene concentrate from Western Australia, Chilean lithium carbonate, and Indonesian nickel matte constitute the upstream feedstock triad for French cathode plants. The supply chain draws from Australian mining majors, Chinese chemical processors, and Korean precursor specialists. Single-source vulnerability in lithium hydroxide conversion capacity threatens feedstock security for Dunkirk's electrode coating lines. Distribution runs through maritime bulk freight to port-integrated gigafactories with just-in-time cathode delivery to OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's battery sector suffers acute electrolyte formulation talent scarcity, with Grenoble's materials science pipeline insufficient to supply sulfide-oxide hybrid development programs across emerging solid-state ventures.
For Market Incumbents: Entrench cathode precursor captive production through backward integration into lithium hydroxide offtake agreements, insulating margin structures from Western Australian spodumene processing bottlenecks. Prioritize DGCCRF compliance infrastructure investment ahead of digital battery passport enforcement timelines. Secure module-to-pack thermal runaway certification for cell-to-pack architectures before second-wave Nouvelle-Aquitaine competitors reach validation cycles. For New Entrants and Emerging Players: Establish a beachhead in standardized swappable pack formats for Île-de-France last-mile delivery fleets, bypassing cell-level procurement complexity through battery-as-a-service contracts. Target Nouvelle-Aquitaine's Atlantic corridor for testing and validation facilities serving Stellantis assembly requirements. Pursue EU Green Deal Innovation Fund co-financing to de-risk cathode precursor capital intensity. For Investors and Strategic Acquirers: Solid-state electrolyte specialists with moisture-sensitive manufacturing protocols represent the priority acquisition archetype for automotive OEM validation exposure. Long-term viability hinges on bridging sulfide-oxide hybridization to commercial scale within the mid-decade window. Watch for EU Battery Regulation carbon border adjustment implementation as the inflection signal for domestic manufacturing cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive lithium hydroxide supply secures DGCCRF carbon footprint compliance for Hauts-de-France output. |
| Battery-as-a-Service Platform Launch | Swappable pack standardization transfers residual value risk from Île-de-France fleet operators to manufacturers. |
| Solid-State Pilot Production Scale-Up | Grenoble sulfide-oxide hybrid lines target Stellantis and Renault automotive validation cycles. |
| Digital Battery Passport Infrastructure | Blockchain-anchored traceability satisfies EU Battery Regulation due diligence for cobalt and lithium sourcing. |
| EU Green Deal Funding Access | Innovation Fund and IPCEI financing de-risks Nouvelle-Aquitaine second-wave gigafactory deployment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU customs trade data, DGCCRF regulatory filings, automotive OEM procurement disclosures, and IHS Markit vehicle production databases. Battery cell engineering directors, cathode plant managers, Stellantis and Renault sourcing committee members, and fleet operator procurement leads provided operational perspective. Bottom-up capacity buildout modeling triangulated against top-down OEM offtake commitment aggregation.
Forecast inputs span cell chemistry evolution, EU Battery Regulation compliance timelines, and regional industrial cluster concentration across the projection horizon. Segmentation dimensions include component tier, technology platform, end-user archetype, and production stage intensity. CAGRs derived from installed capacity ramp schedules, OEM electrification targets, and fleet operator battery-as-a-service adoption curves. Lithium hydroxide feedstock availability and solid-state commercialization timelines shaped scenario weightings.
Stress conditions across spodumene price volatility, CE marking compliance cost inflation, and solid-state timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on OEM electrification commitment durability and EU industrial funding continuity. Cross-checking against IEA critical mineral supply projections and European Battery Alliance capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
EV Battery Heating System Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
EV Batteries Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market