
 Middle-East and Africa Electric Vehicle Battery Anode Market | 2026-2036
Middle-East and Africa Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Electric Vehicle Battery Anode Market Insights
Fleet operators are rotating toward electric commercial vehicles as the dominant buyer archetype across the Middle-East and Africa, displacing early passenger-vehicle-centric procurement patterns. SGL Carbon GmbH anchors its position through backward integration into synthetic graphite precursors, securing feedstock access for regional battery makers. Elkem ASA specializes in silicon-based anode formulations, targeting the high-energy density segment where local automakers seek differentiated range performance. Middle East Battery Company dominates domestic assembly channels, leveraging its proximity to Saudi Arabian industrial zones for logistics cost control.
The Middle-East and Africa Electric Vehicle Battery Anode comprises the negative electrode material within lithium-ion cells, typically engineered from crystalline graphite with theoretical capacity near 372 mAh/g or silicon composites exceeding 3,500 mAh/g, manufactured through calcination, milling, and surface coating processes to enable reversible lithium intercalation during charge-discharge cycling. Its primary purpose is to store and release lithium ions efficiently while maintaining structural integrity across thousands of cycles in electric drivetrain applications. Graphite anodes currently occupy the largest volume share across passenger vehicle applications, though silicon-based variants are capturing the fastest growth trajectory as regional automakers pursue extended-range electric buses. Fast charging technology represents the most contested margin pool, with fleet operators demanding fifteen-minute charge capabilities that stress conventional anode architectures and reward suppliers with proprietary electrolyte-compatible surface treatments.
Saudi Arabia's SFDA and the UAE's MOHAP enforce chemical handling standards that indirectly shape anode manufacturing facility permitting, while South Africa's national automotive regulator applies EU-aligned REACH substance restrictions on imported battery materials. The EU Green Deal's carbon border adjustment mechanism is forcing North African anode suppliers to document embedded emissions or risk exclusion from European battery supply chains. Stakeholders must monitor how Gulf sovereign wealth funds allocate capital between domestic anode production and offtake agreements with Asian graphite processors, as this capital flow structure will determine which technology tiers achieve commercial scale in the region.
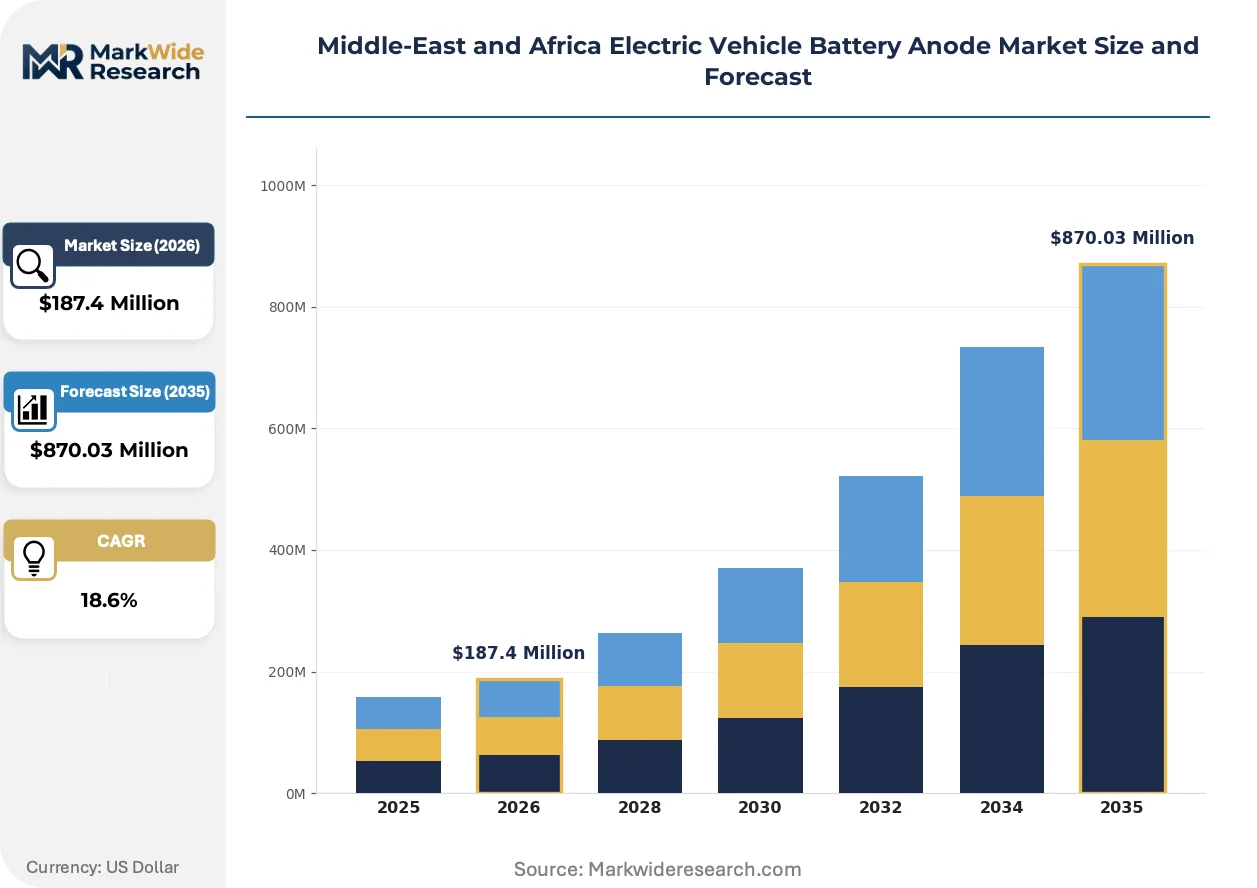
Market Dynamics
Fleet electrification across Middle-East and Africa is compressing anode procurement cycles, with commercial vehicle operators now dictating specifications previously set by passenger car OEMs. This demand rotation is restructuring supplier relationships around thermal stability guarantees and fast-charge compatibility rather than cost-per-kilogram metrics.
Growth Catalysts
- EU Green Deal carbon border rules:North African anode exporters must document embedded emissions to retain European battery supply chain access, accelerating local decarbonization investments.
- Saudi Arabian industrial zone expansion:Domestic battery assembly clusters near Jubail and Yanbu are concentrating graphite precursor demand within sovereign wealth fund-backed manufacturing corridors.
- Silicon composite anode formulations:Regional electric bus manufacturers are specifying silicon-graphite blends exceeding 500 mAh/g practical capacity for extended-range fleet operations.
Market Restraints
- Spherical graphite feedstock concentration:Over 80% of battery-grade spherical graphite originates from Chinese calcination and milling facilities, exposing regional anode makers to single-source supply risk.
- Petroleum coke price volatility:Synthetic graphite precursor costs fluctuate with refining margins and needle coke allocation to steel electrodes, compressing anode producer margins unpredictably.
- Silicon expansion cycling degradation:Silicon anodes swell 300% during lithiation, causing particle pulverization and electrolyte consumption that limits cell cycle life below fleet operator warranty thresholds.
Strategic Opportunities
- South African automotive manufacturing corridors:Gauteng and Eastern Cape provinces are attracting anode material toll processing investments to serve emerging domestic lithium-ion cell assembly.
- UAE fast-charging infrastructure mandates:Dubai and Abu Dhabi regulatory frameworks requiring 350kW charging compatibility are creating premium demand for anodes with enhanced lithium-ion transport kinetics.
- Silicon oxide pre-lithiation integration:Converting silicon monoxide anodes with stabilized solid electrolyte interphase layers offers regional suppliers a technical differentiation path against established graphite incumbents.
Industry Challenges
- Electrochemical materials engineering talent scarcity:Regional universities produce limited graduates with lithium-ion intercalation chemistry expertise, forcing anode producers to recruit from Asian battery manufacturing clusters.
- Cell-to-pack thermal runaway certification:Saudi SFDA and UAE MOHAP chemical handling permits require extended safety documentation timelines that delay commercial anode qualification by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Electric Vehicle Battery Anode Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Graphite, Silicon-based, Composite Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Electric Buses Technology: Fast Charging, High-energy Density, Solid State, Standard End User: Automakers, Energy Storage Systems, Fleet Operators, Research Institutions |
| Companies Covered | Nexeon Limited, SGL Carbon GmbH, Elkem ASA, Amprius Technologies Inc., Sila Nanotechnologies Inc., Middle East Battery Company, Targray Technology International Inc., BASF SE, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Electric Vehicle Battery Anode Market Trends and Innovations
Anode architectures across Middle-East and Africa are fragmenting into parallel technology tracks as fleet operators diverge from passenger vehicle specifications. Material suppliers must now maintain dual qualification pathways for conventional graphite and advanced silicon composite formulations.
Silicon-graphite composite anodes are bifurcating regional supply chains into distinct qualification tiers. Electric bus manufacturers in Saudi Arabia and UAE are adopting 10-15% silicon loadings for 400+ km range targets, while passenger vehicle programs retain graphite dominance for cost control. This technical divergence is forcing anode producers to maintain parallel coating and electrolyte compatibility development streams, compressing R&D efficiency.
EU Green Deal carbon border adjustment mechanisms are reshaping North African export economics. Moroccan and Tunisian anode material processors must install emissions monitoring systems and secure renewable electricity contracts to document carbon intensity below 8 kg CO2 per kg anode. Suppliers failing verification face exclusion from European battery supply chains, redirecting investment toward solar-powered calcination facilities.
Fleet procurement specifications are consolidating around fifteen-minute fast-charge capability as a non-negotiable operational requirement. Regional logistics operators in South Africa and Gulf states are rejecting anode materials without demonstrated lithium plating suppression below 0°C and stable solid electrolyte interphase formation above 3C charge rates. This performance threshold is eliminating second-tier graphite suppliers lacking proprietary surface treatment intellectual property.
Middle-East and Africa Electric Vehicle Battery Anode Market Segmentation
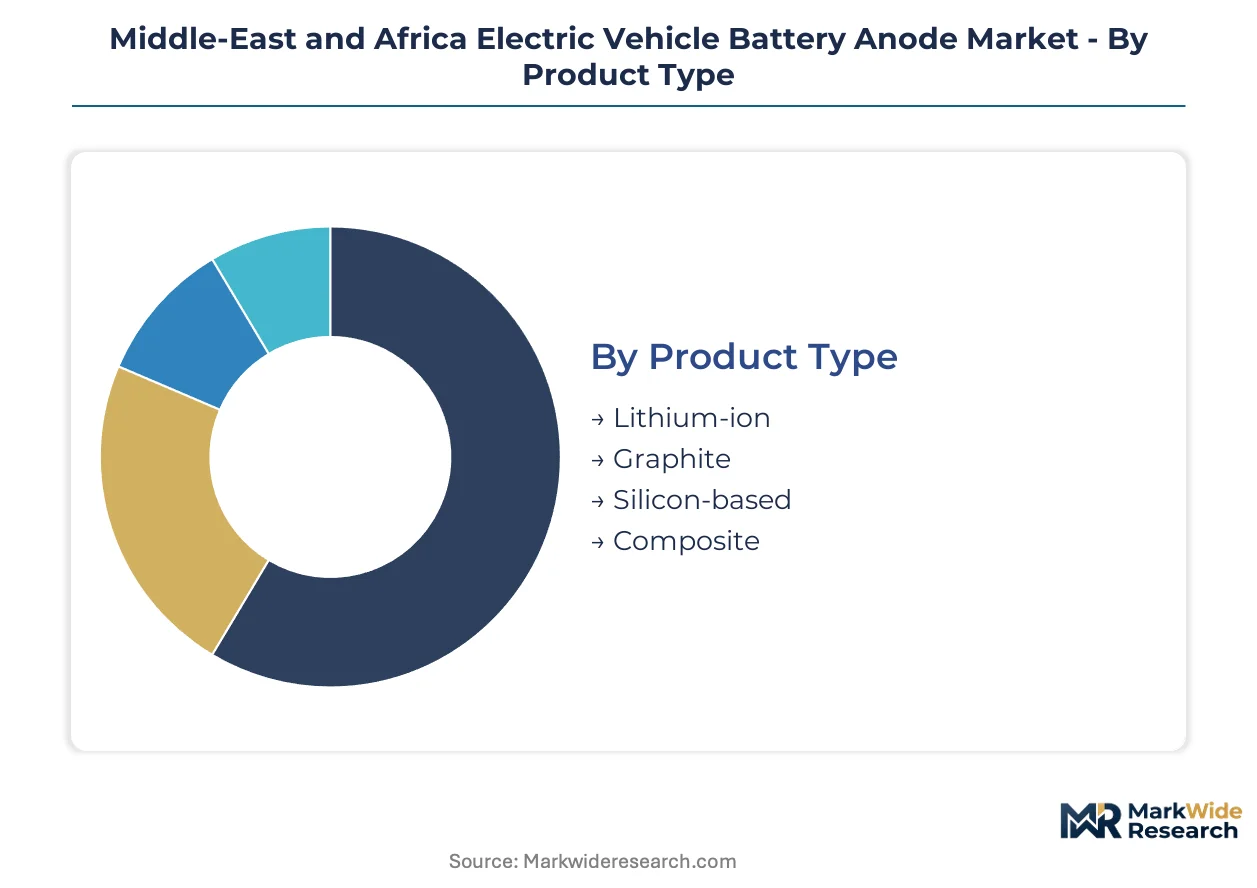
Anode procurement patterns across the Middle-East and Africa fragment sharply by end-use application, with fleet operators and passenger vehicle OEMs demanding incompatible performance specifications. Suppliers must maintain parallel qualification pathways for each segment cluster, compressing R&D efficiency and concentrating margin pools in fast-charge compatible formulations.
Product Type:
Channel flows diverge by precursor chemistry, with synthetic graphite dominating toll-processing contracts through Saudi industrial zones while silicon composites command direct supplier relationships from UAE-based electric bus manufacturers.
- Graphite:Crystalline carbon structures with theoretical capacity near 372 mAh/g, manufactured through petroleum coke calcination and spherical milling. Saudi Arabian battery assembly clusters near Jubail and Yanbu concentrate procurement of synthetic graphite precursors backed by sovereign wealth fund manufacturing corridors.
- Silicon-based:Elemental silicon or silicon oxide formulations exceeding 3,500 mAh/g theoretical capacity, constrained by 300% volume expansion during lithiation. UAE electric bus manufacturers are specifying silicon-graphite blends for 400+ km range targets, accepting shortened cycle life in exchange for energy density.
- Composite:Engineered blends of graphite and silicon phases with optimized particle architecture. South African automotive corridors are attracting toll-processing investments for composite anode materials serving emerging domestic cell assembly.
- Lithium-ion:Broad category encompassing all intercalation anode materials compatible with lithium-ion cell chemistry. Regional research institutions are qualifying experimental lithium-ion anode formulations for next-generation solid-state prototypes.
By volume, graphite leads procurement across passenger vehicle channels. By growth pace, silicon-based formulations are climbing the fastest as fleet operators prioritize range extension over cycle life warranties.
Application:
Cost tier stratification separates premium fast-charge specifications in commercial deployments from economy-grade cycle-life priorities in passenger segments.
- Commercial Vehicles:Medium-duty trucks and delivery vans requiring thermal stability under sustained high-rate discharge. Fleet operators in South Africa and Gulf states are consolidating procurement around fifteen-minute fast-charge capability as a non-negotiable operational threshold.
- Electric Buses:Heavy-duty transit applications demanding 3,000+ cycle life under abusive duty cycles. Saudi and UAE regulatory mandates for 350kW charging compatibility are creating premium demand for anodes with enhanced lithium-ion transport kinetics.
- Passenger Vehicles:Private automobile applications prioritizing cost-per-kilogram metrics and established supply security. Graphite anodes retain dominance here as regional automakers defer silicon adoption pending warranty performance validation.
- Two-wheelers:Motorcycles and scooters with constrained battery pack volume and weight budgets. North African assemblers serving European export markets must document embedded emissions below EU Green Deal carbon border thresholds to retain supply chain access.
Passenger vehicles anchor current volume procurement. Electric buses are gaining share fastest as municipal transit authorities accelerate fleet electrification timelines.
Technology:
Customer type fragmentation separates fleet operators demanding fast-charge compatibility from energy storage system developers prioritizing cycle stability.
- Fast Charging:Anode architectures engineered for lithium plating suppression below 0°C and stable solid electrolyte interphase formation above 3C charge rates. Dubai and Abu Dhabi regulatory frameworks requiring 350kW infrastructure compatibility are consolidating procurement specifications around this performance tier.
- High-energy Density:Formulations maximizing gravimetric and volumetric capacity for extended-range applications. Regional electric bus manufacturers are specifying silicon-graphite blends exceeding 500 mAh/g practical capacity.
- Standard:Conventional graphite anodes with established electrolyte compatibility and proven cycle life. Passenger vehicle OEMs retain this technology tier for cost control and supply security.
- Solid State:Anode materials compatible with sulfide or oxide solid electrolyte interfaces. Research institutions across the UAE and South Africa are qualifying experimental formulations for next-generation cell architectures.
Standard technology leads current procurement volumes. Fast charging specifications are expanding most quickly as fleet operators rewrite procurement requirements.
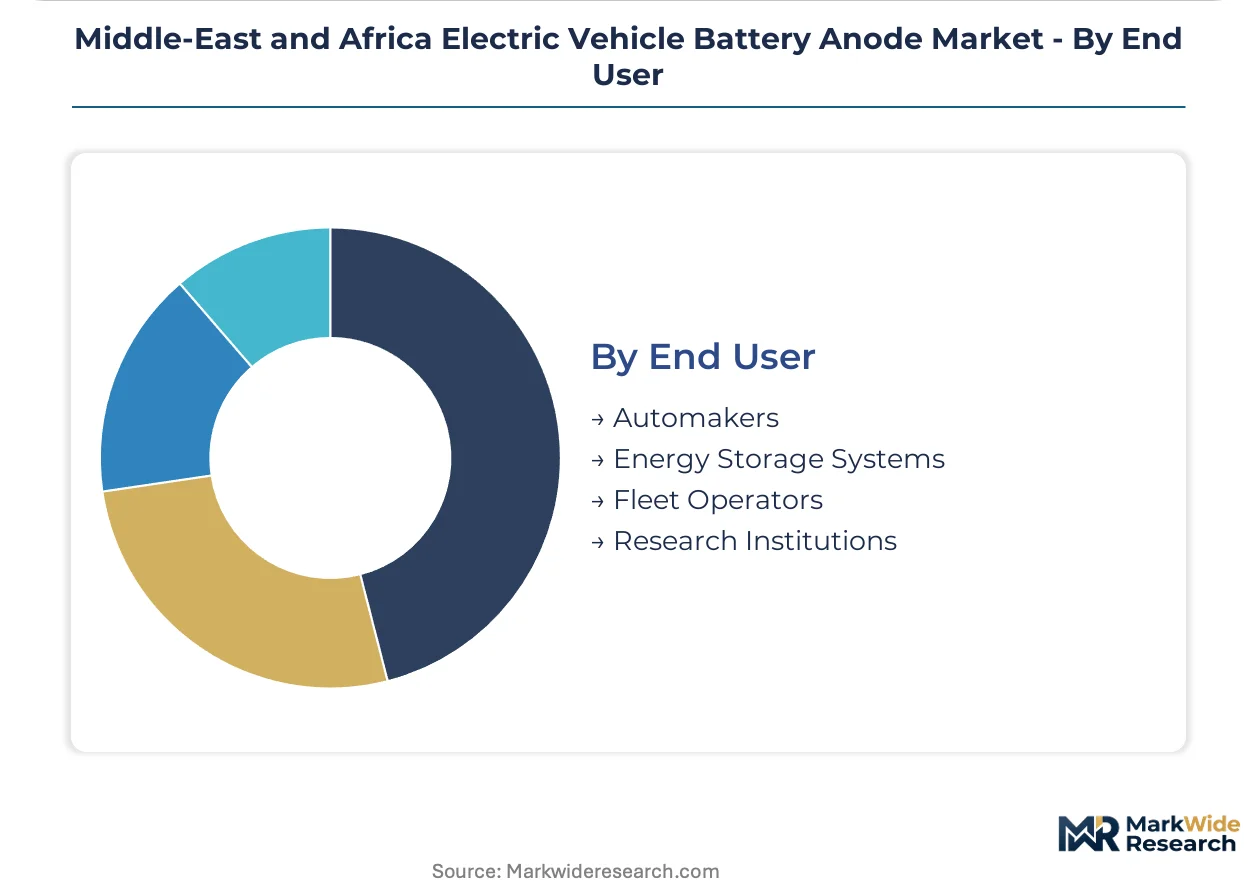
End User:
Supply concentration varies by buyer sophistication, with automakers demanding qualified supplier relationships and fleet operators accepting toll-processed materials from emerging regional processors.
- Fleet Operators:Commercial vehicle owners specifying performance guarantees rather than material composition. Logistics operators in South Africa and Gulf states are rejecting anode materials without demonstrated fifteen-minute charge capability.
- Automakers:Original equipment manufacturers with formal qualification programs and multi-year supply agreements. Saudi Arabian industrial zone expansion is concentrating graphite precursor demand within sovereign wealth fund-backed manufacturing corridors serving automaker customers.
- Energy Storage Systems:Stationary battery developers prioritizing cycle life over power density. This segment sources primarily from established Asian graphite processors with documented carbon intensity compliance.
- Research Institutions:Universities and national laboratories qualifying next-generation formulations. Regional electrochemical materials engineering talent scarcity forces these institutions to collaborate with Asian battery manufacturing clusters for technical expertise.
Automakers dominate current procurement volumes. Fleet operators are pulling ahead fastest in specification-setting influence as commercial vehicle electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco and Tunisia export anode materials to European battery manufacturers under EU Green Deal carbon border rules, forcing emissions documentation upgrades across North African processing facilities.
Saudi Arabia
Sovereign wealth funds are financing battery assembly corridors near Jubail and Yanbu industrial zones. The Saudi Food and Drug Authority enforces chemical handling standards that shape anode manufacturing facility permitting timelines. Domestic graphite precursor demand concentrates within these petrochemical-backed manufacturing clusters serving regional automakers.
United Arab Emirates
Dubai and Abu Dhabi municipal mandates for 350kW charging infrastructure are driving procurement of fast-charge compatible anode architectures. The Ministry of Health and Prevention applies chemical safety protocols that extend commercial qualification timelines. Industrial zones in Jebel Ali and Khalifa Port are attracting toll-processing investments for imported spherical graphite.
South Africa
Gauteng and Eastern Cape automotive manufacturing corridors are concentrating demand for graphite and silicon-based anode materials. The national automotive regulator applies EU-aligned REACH substance restrictions on imported battery materials. Domestic battery assembly expansion is drawing toll-processing investments for composite anode formulations.
Morocco
Phosphate processing expertise is transferring into battery material manufacturing for European export markets. EU Green Deal carbon border adjustment mechanisms require emissions monitoring systems and renewable electricity contracts below 8 kg CO2 per kg anode. Solar-powered calcination facilities are emerging near OCP Group industrial sites to meet verification standards.
Egypt
Suez Canal logistics corridors are positioning the country as a re-export hub for Asian graphite materials entering African markets. General regulatory frameworks for industrial chemical handling apply to battery material warehousing and processing. New Cairo and Alexandria industrial zones are developing basic toll-processing capacity for regional battery assemblers.
Middle-East and Africa Electric Vehicle Battery Anode Market Competitive Landscape
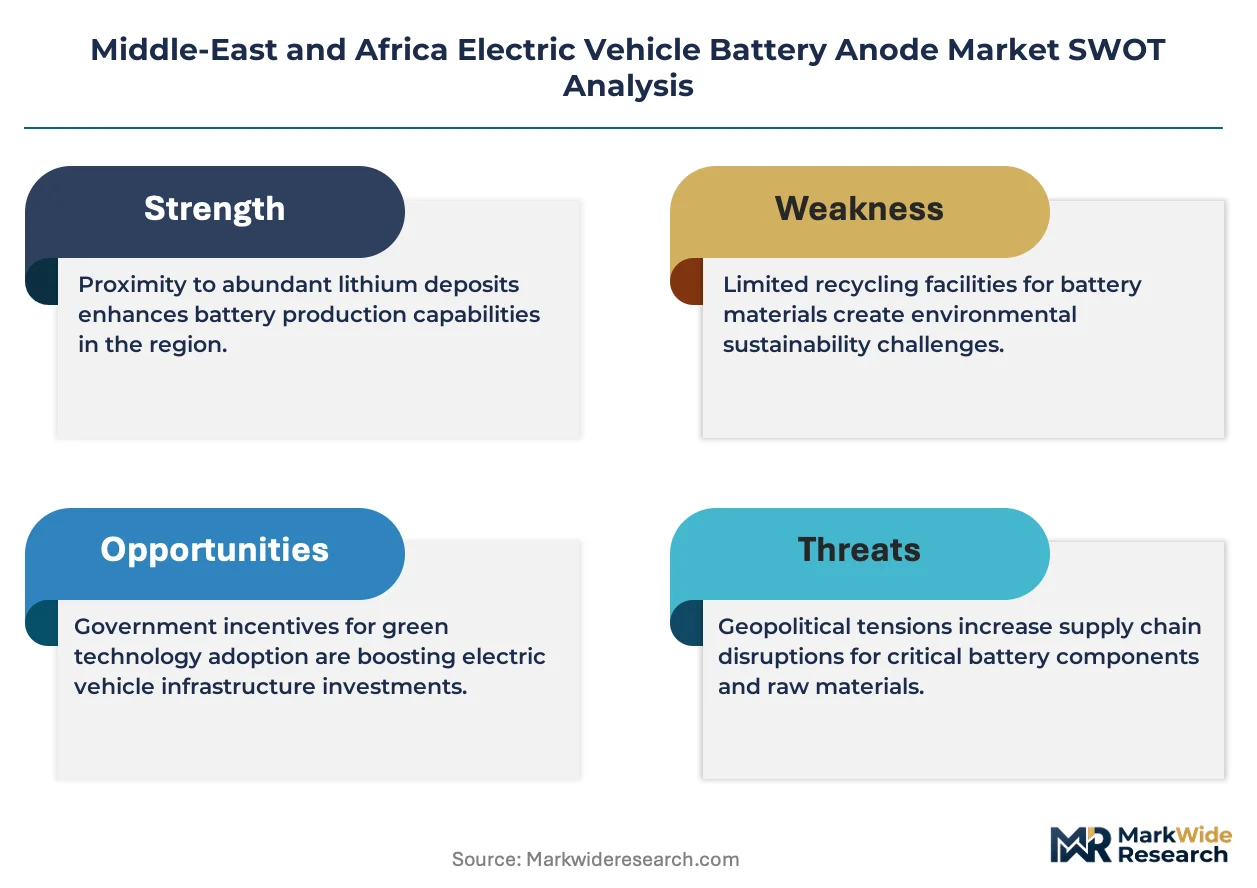
Player mix skews toward European and Asian material specialists with established carbon processing expertise, creating a tiered structure where technology licensors sit above regional toll processors. The competitive terrain separates synthetic graphite incumbents from silicon composite challengers, with qualification timelines serving as the primary barrier to entry. Strategic archetypes include backward-integrated carbon specialists, silicon anode technology licensors, and regional battery assemblers with captive anode sourcing. Dominant competitive moves center on securing spherical graphite offtake agreements and establishing electrolyte-compatible surface treatment intellectual property.
Among European-based material specialists, SGL Carbon GmbH and Elkem ASA exemplify distinct strategic positions within the supplier hierarchy. SGL Carbon GmbH represents the backward-integrated archetype with captive synthetic graphite precursor capabilities. Elkem ASA occupies the silicon-based formulation tier, targeting energy density differentiation. Middle East Battery Company anchors the regional assembler category, leveraging proximity to Saudi industrial zones for logistics cost control. These three entities illustrate how geographic positioning and feedstock access determine competitive standing in anode procurement networks.
| Leading Market Players |
|---|
| Nexeon Limited |
| SGL Carbon GmbH |
| Elkem ASA |
| Amprius Technologies Inc. |
| Sila Nanotechnologies Inc. |
| Middle East Battery Company |
| Targray Technology International Inc. |
| BASF SE |
| Mitsubishi Chemical Group Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon border adjustment mechanisms gate both supply qualification and price differentiation simultaneously, forcing North African anode processors to invest in emissions documentation systems that separate premium-tier materials from standard-grade exports. Fleet operators in Saudi Arabia and the UAE now demand fast-charge compatible formulations as a non-negotiable procurement threshold, compressing margins for suppliers lacking proprietary surface treatment capabilities while rewarding certified producers with pricing power.
Pricing Analysis
Fast-charge compatible next-generation anodes command substantial premiums over standard graphite formulations, while legacy synthetic graphite precursors face persistent cost compression from petroleum coke price volatility. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with fleet operators showing lowest price sensitivity due to operational uptime requirements. Pricing pressure stems from Chinese spherical graphite feedstock concentration, squeezing regional toll processors unable to secure long-term offtake agreements.
Supply Chain Analysis
Port congestion along Asia-Middle East trade lanes elevates inbound logistics costs for spherical graphite shipments arriving at Jebel Ali and Khalifa Port, compressing margins for UAE-based toll processors. Supply concentrates in China, South Korea, and Japan for battery-grade graphite precursors, with regional anode makers drawing from petroleum coke, needle coke, and silicon monoxide feedstocks. Single-source vulnerability from Chinese calcination facility dominance threatens supply continuity, while distribution runs through sovereign wealth fund-backed manufacturing corridors near Jubail and Yanbu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anode qualification services and technical support contracts represent the fastest-expanding recurring-revenue layer, outpacing hardware margins as fleet operators demand performance guarantees rather than commodity procurement.
For Market Incumbents: Secure long-term spherical graphite offtake agreements with Chinese processors before carbon border documentation requirements harden, and invest in electrolyte-compatible surface treatment R&D to defend against silicon composite substitution threats from specialized challengers.
For New Entrants and Emerging Players: Lead with silicon oxide pre-lithiation formulations targeting UAE electric bus manufacturers seeking 400+ km range specifications, penetrating the premium fast-charge segment where established graphite suppliers lack technical differentiation.
For Investors and Strategic Acquirers: EU Green Deal carbon border enforcement reshapes the acquisition landscape toward North African processors with installed emissions monitoring and renewable electricity contracts, positioning solar-powered calcination facilities as priority targets within the five-to-ten year viability window; watch for Gulf sovereign wealth fund capital allocation shifts between domestic production and Asian offtake agreements as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Graphite Precursors | SGL Carbon GmbH's captive petroleum coke processing secures feedstock access for Saudi battery assembly clusters. |
| Silicon Composite Formulation Licensing | Elkem ASA's silicon anode technology enables regional bus manufacturers to achieve extended-range targets. |
| Fast-Charge Compatibility Certification | Dubai's 350kW infrastructure mandates create premium demand for anodes with enhanced lithium-ion transport kinetics. |
| Carbon Border Documentation Systems | Moroccan processors installing emissions monitoring secure continued European battery supply chain access. |
| Toll-Processing Joint Ventures | South African automotive corridors attract composite anode investments serving emerging domestic cell assembly. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC filings from listed material suppliers, and IEA energy transition reports. Primary interviews engaged anode procurement managers at fleet operators, technical directors at regional battery assemblers, and plant managers at North African processing facilities. Secondary validation drew from SFDA chemical handling guidelines, EU Green Deal technical documentation, and Gauteng automotive corridor investment filings. Bottom-up volume estimates triangulate against top-down market sizing from production capacity announcements.
Segmentation dimensions modeled span product type, application, technology tier, and end-user category across the projection horizon. The analytical framework incorporates vehicle electrification timelines, charging infrastructure deployment rates, and regulatory compliance thresholds to derive growth trajectories. CAGRs reflect installed capacity expansion, fleet procurement cycle compression, and carbon border adjustment implementation pace throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained sovereign wealth fund commitment to domestic battery assembly, stable Chinese graphite export policies, and EU carbon border enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding fleet operator specification consolidation and regional talent availability for electrochemical materials engineering. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
France EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Traction Battery Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market