
 United States Electric Vehicle Battery Anode Market | 2026-2036
United States Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Battery Anode Market Insights
Modular anode-cell bundling is shifting how battery pack architects configure energy density against thermal management trade-offs. Group14 Technologies specializes in silicon-carbon composite architectures that sustain higher cycle stability than conventional graphite formulations. Anovion LLC anchors its position through synthetic graphite production at domestic scale, while NEI Corporation differentiates via customized anode slurry formulations for niche battery chemistries.
The United States Electric Vehicle Battery Anode comprises the negative electrode material in rechargeable lithium-ion cells, typically structured from carbonaceous substrates with intercalation capacities near 372 mAh/g for graphite and exceeding 3,500 mAh/g for silicon composites, engineered to accept lithium ions during charging while maintaining structural integrity across thousands of cycles. Silicon-based material variants command widening interest from automakers seeking range extension, though graphite retains manufacturing scale advantages and cost structures that dominate near-term procurement. Solid-state technology development is redirecting R&D spending toward anode interfaces compatible with ceramic electrolytes, while fast-charging formulations represent the fastest-growing technology segment as fleet operators prioritize turnaround time.
The Inflation Reduction Act, EPA tailpipe emissions standards, and NHTSA fuel economy regulations collectively mandate domestic battery supply chain localization and accelerate OEM demand for qualified U.S.-produced anode materials. OSHA process safety directives and emerging EPA graphite purification emissions rules further shape facility permitting and capital deployment timelines for anode manufacturers. Stakeholders must monitor IRA critical mineral sourcing thresholds and state-level clean manufacturing incentives to secure offtake agreements before capacity constraints harden.
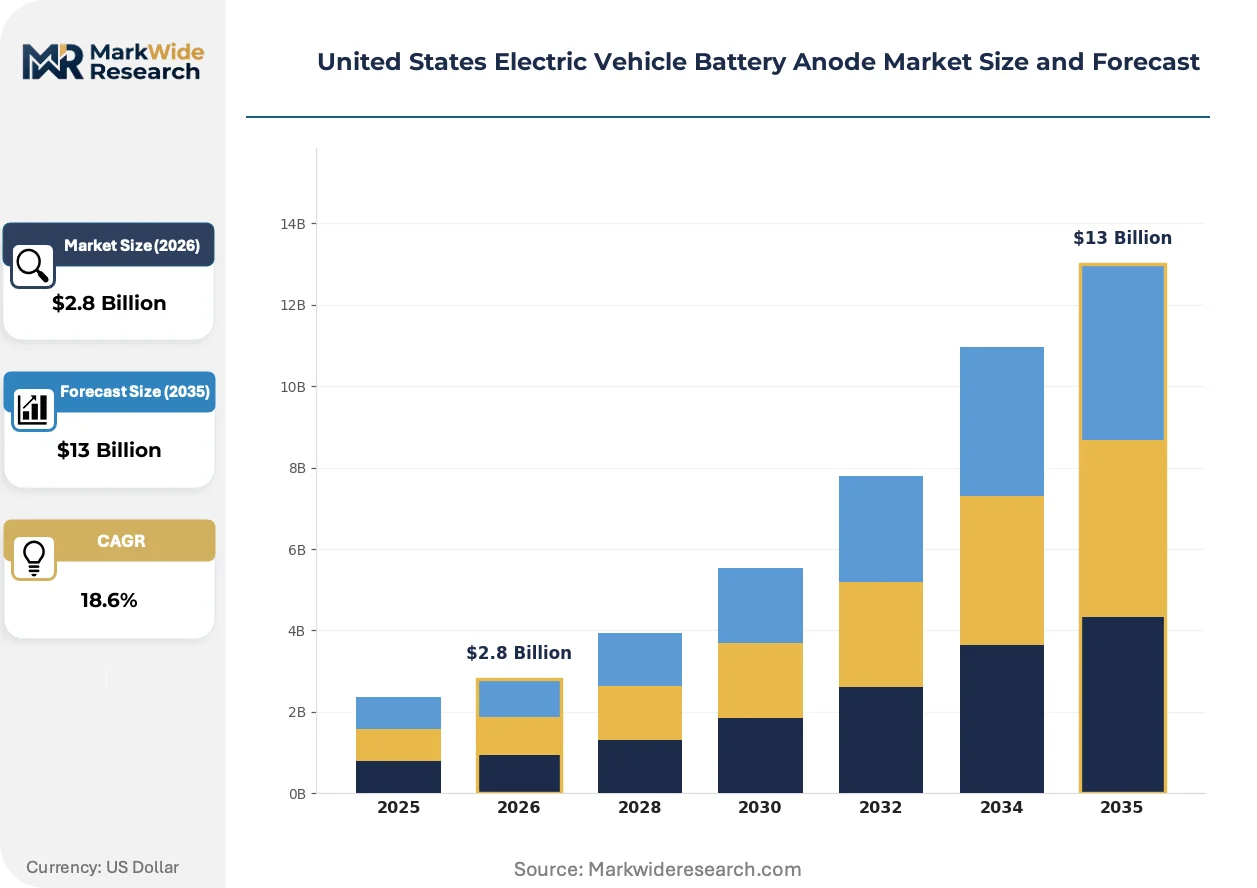
Market Dynamics
Silicon-enhanced anode formulations are compressing graphite's incumbent position as automakers prioritize range extension over cycle-life tolerance, while the Inflation Reduction Act's domestic content thresholds force immediate supply chain reconfiguration toward North American processing capacity.
Growth Catalysts
- IRA Domestic Content Requirements:Battery cell manufacturers must qualify critical mineral sourcing thresholds to capture tax credits, redirecting capital toward U.S.-based graphite purification and synthetic anode production.
- Silicon-Carbon Composite Maturation:Higher intercalation capacity materials exceeding 3,500 mAh/g are penetrating premium EV platforms as cycle stability formulations improve.
- Michigan Manufacturing Corridor Concentration:OEM final assembly proximity to anode material processing reduces logistics costs and satisfies just-in-time battery pack assembly requirements.
Market Restraints
- Spherical Graphite Supply Concentration:Battery-grade purified spherical graphite remains concentrated among Asian suppliers, creating qualification bottlenecks for U.S. cell producers seeking IRA compliance.
- Silicon Volume Expansion Degradation:Silicon's 300% lithiation-induced swelling fractures particle structures and consumes electrolyte, limiting commercial loadings below 10% in most cell designs.
- EPA Graphite Purification Emissions Rules:Emerging air quality standards for thermal and chemical purification processes extend facility permitting timelines and raise capital intensity for greenfield projects.
Strategic Opportunities
- Solid-State Electrolyte Interface Engineering:Ceramic electrolyte chemistries demand redesigned anode architectures, creating first-mover advantages for material suppliers with sintering-compatible carbon substrates.
- Fast-Charging Fleet Applications:Commercial vehicle operators prioritize 15-minute charging capability, accelerating demand for engineered carbon structures with enhanced lithium-ion transport kinetics.
- Midwest Secondary Processing Clusters:Ohio and Tennessee battery gigafactory announcements are pulling anode finishing capacity into the Ohio River Valley logistics network.
Industry Challenges
- Electrochemist Talent Scarcity:Cell manufacturers and material suppliers compete for finite pools of battery scientists with silicon anode formulation experience, compressing R&D timelines.
- Qualification Cycle Duration:OEM cell validation protocols require 18-24 months of cycle-life testing before production contracts, delaying revenue recognition for novel material entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Battery Anode Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Graphite, Lithium Ion, Silicon, Graphene Battery Type: LFP, NMC, NCA, LMO End User: Automakers, Component Suppliers, Aftermarket Providers, Fleet Operators Technology: Conventional, Solid-State, Hybrid, Fast-Charging |
| Companies Covered | Group14 Technologies, NEI Corporation, Sionic Energy, Anovion LLC, Enevate Corporation, Nouveau Monde Graphite, OneD Battery Sciences, NanoGraf Corporation, Paraclete Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Battery Anode Market Trends and Innovations
Pre-lithiation techniques and artificial solid-electrolyte interphase coatings are compressing formation cycle overhead, while dry electrode processing eliminates solvent recovery capital and energy intensity from anode manufacturing.
Silicon nanowire architectures deposited directly on copper current collectors are decentralizing the traditional powder-mixing-and-coating paradigm that has dominated anode production for two decades. Cell manufacturers including premium EV platforms are piloting these structures at 500 MWh annual scales. The elimination of polymeric binders and conductive additives is compressing electrode thickness tolerances and enabling 40% faster roll-to-roll line speeds.
The Inflation Reduction Act's critical mineral and battery component bonus credits are forcing immediate supply chain restructuring. Domestic content percentage thresholds escalate annually, compelling cell producers to qualify North American anode suppliers before foreign alternatives lose economic viability. Michigan and Ohio battery plants are accelerating local supplier audits to maintain credit eligibility through the 2027 phase-in period.
Fleet operators are consolidating procurement around performance-guaranteed material supply contracts rather than spot-market graphite purchases. Large commercial vehicle deployers in California and Texas are demanding volumetric energy density warranties that shift technical risk upstream to anode manufacturers. This behavioral shift is most pronounced among last-mile delivery electrification programs where route optimization depends on predictable range degradation curves.
United States Electric Vehicle Battery Anode Market Segmentation
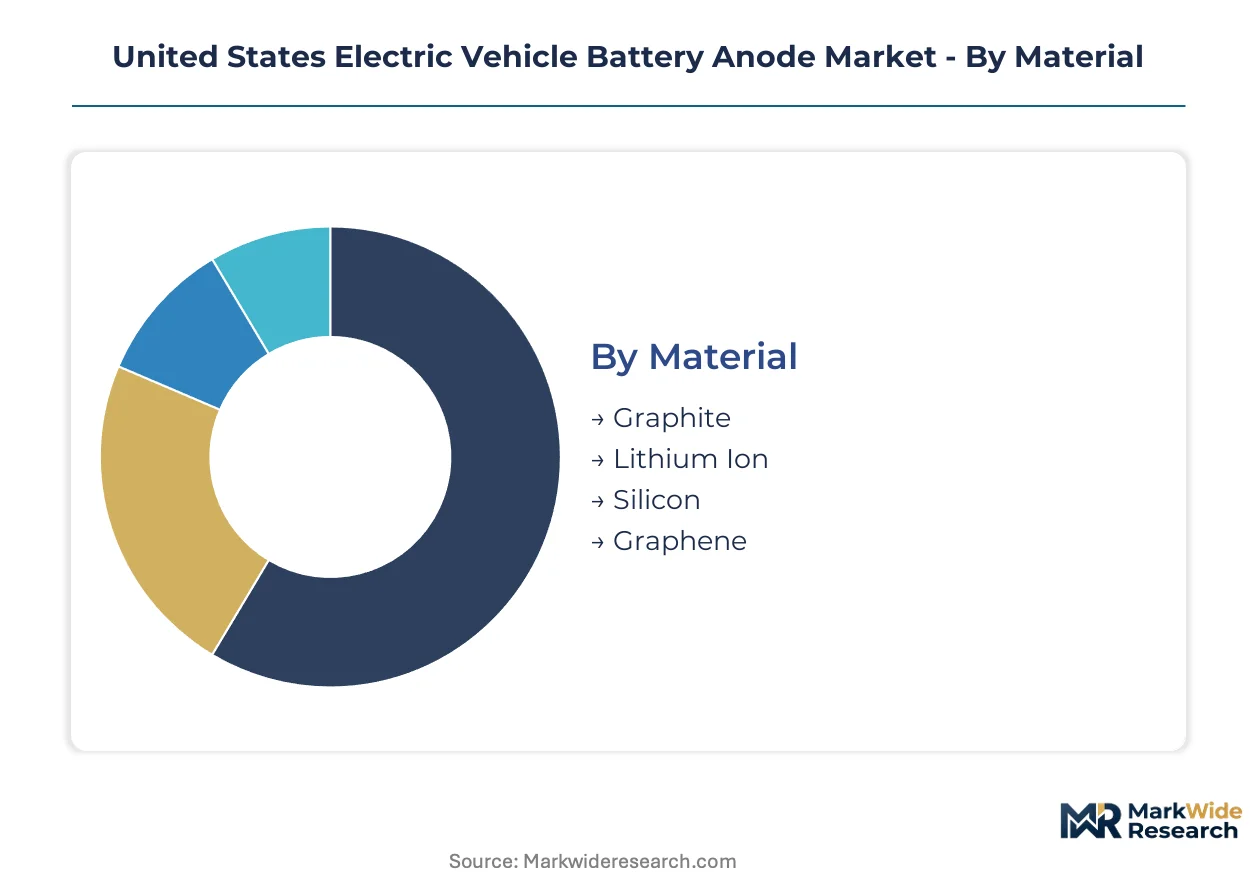
Anode procurement patterns diverge sharply across material chemistries and battery architectures, with IRA domestic content thresholds forcing OEMs to map supplier qualifications against each segment's certification burden. Fleet operators and premium automakers now maintain parallel qualification tracks for conventional and next-generation formulations.
Material:
EPA graphite purification emissions rules and OSHA process safety directives impose facility-level certification requirements that vary by feedstock origin and synthetic versus natural processing pathways.
- Graphite:Purified spherical graphite derived from natural flake or synthetic feedstock delivers 372 mAh/g intercalation capacity with established supply chains. Michigan-based cell plants qualify domestic synthetic sources to satisfy IRA bonus credit thresholds, though purification capacity bottlenecks constrain near-term procurement.
- Silicon:Silicon-carbon composites exceeding 3,500 mAh/g are penetrating premium EV platforms as cycle stability formulations improve. Volume expansion challenges limit commercial loadings below 10% in most designs, though pre-lithiation techniques are compressing formation overhead for Midwest automakers.
- Lithium Ion:Lithium metal anodes enable solid-state architectures with theoretical capacities tenfold above graphite. Emerging EPA air quality standards for lithium handling extend permitting timelines for greenfield facilities.
- Graphene:Single-layer carbon structures offer exceptional conductivity for fast-charging applications. Production costs and scalability constraints restrict deployment to niche performance segments.
Leading the category by volume: Graphite. Growing fastest: Silicon.
Battery Type:
Cell chemistry determines anode interface engineering requirements and thermal management specifications, with cost tiers separating mass-market from premium applications.
- LFP:Lithium iron phosphate cells prioritize cycle life and thermal stability over energy density. Anode specifications emphasize low-cost graphite formulations with conservative silicon loadings for commercial vehicle fleets in Texas and California.
- NMC:Nickel-manganese-cobalt chemistries balance energy density and cycle stability for mainstream passenger EVs. Anode suppliers customize particle size distributions to match cathode nickel ratios and optimize pack-level cost structures.
- NCA:Nickel-cobalt-aluminum formulations command premium anode materials with enhanced lithium-ion transport kinetics. Silicon-enhanced architectures are qualifying first in NCA cells for luxury OEM platforms.
- LMO:Lithium manganese oxide cells serve power-tool and specialty mobility applications with moderate energy density requirements. Anode procurement emphasizes supply security over performance optimization.
Highest volume concentration: NMC. Steepest expansion trajectory: LFP.
End User:
Customer procurement sophistication separates spot-market purchasers from performance-guaranteed contract negotiators, with warranty terms shifting technical risk upstream.
- Automakers:OEM cell validation protocols require 18-24 months of cycle-life testing before production contracts, delaying revenue recognition for novel material entrants. IRA compliance teams audit anode suppliers against escalating domestic content percentage thresholds.
- Component Suppliers:Battery pack integrators in Ohio and Tennessee maintain dual-source strategies across graphite and silicon-carbon formulations. Just-in-time assembly requirements favor anode finishing capacity within the Midwest logistics network.
- Aftermarket Providers:Replacement cell producers prioritize cost-optimized graphite procurement without IRA credit eligibility constraints. Quality verification relies on third-party testing rather than OEM qualification protocols.
- Fleet Operators:Commercial vehicle deployers demand volumetric energy density warranties that shift degradation risk to material suppliers. Last-mile delivery electrification programs in California consolidate procurement around predictable range curves.
Dominant procurement volume: Automakers. Contract sophistication advancing fastest: Fleet Operators.
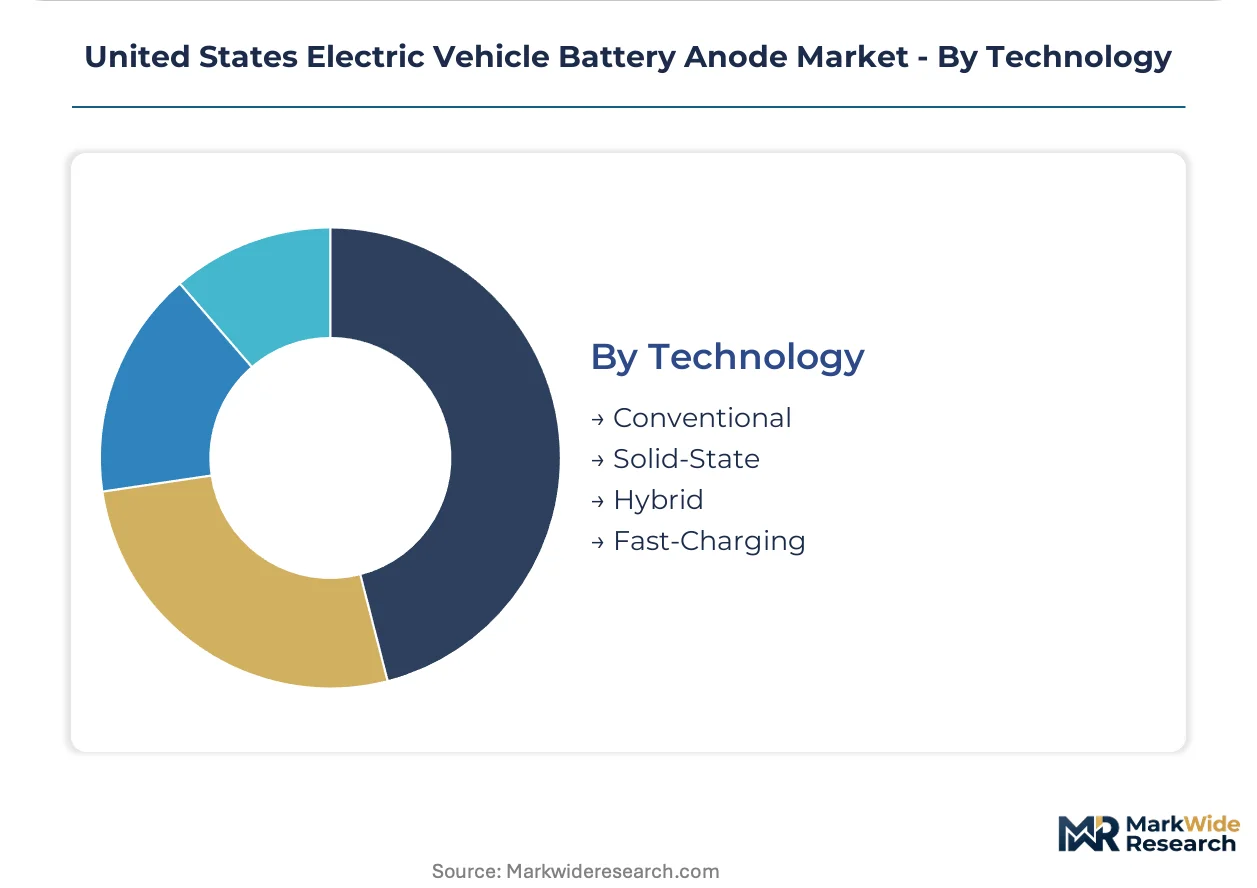
Technology:
Manufacturing maturity and R&D intensity create divergent margin profiles across technology tiers, with solid-state development consuming disproportionate capital allocation.
- Conventional:Powder-mixing-and-coating paradigms dominate anode production with two decades of process optimization. Slurry formulations from NEI Corporation and synthetic graphite scale from Anovion LLC anchor near-term supply security.
- Solid-State:Ceramic electrolyte chemistries demand redesigned anode architectures with sintering-compatible carbon substrates. First-mover advantages accrue to material suppliers with interface engineering capabilities.
- Hybrid:Semi-solid electrolyte systems bridge liquid and all-solid architectures, requiring anode formulations compatible with gel polymer matrices. Pilot lines in Michigan are qualifying hybrid cell suppliers.
- Fast-Charging:Engineered carbon structures with enhanced lithium-ion transport kinetics enable 15-minute charging capability. Fleet operators prioritize this segment for commercial vehicle turnaround time.
Volume leadership: Conventional. Technology investment intensity highest: Solid-State.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA Advanced Manufacturing Production Credit zone concentrates anode investment across the Midwest automotive corridor, pulling purification capacity toward Ohio River Valley logistics networks and Michigan cell assembly plants.
Michigan
OEM final assembly proximity drives anode finishing demand from Detroit-area battery plants. EPA graphite purification emissions rules extend permitting timelines for greenfield facilities in the Great Lakes region. Midland and Holland host emerging synthetic graphite processing clusters serving just-in-time pack assembly requirements.
Ohio
Ohio River Valley battery gigafactory announcements pull secondary anode processing into Cincinnati-Dayton logistics corridors. OSHA process safety directives shape facility design for thermal purification operations. Columbus anchors electrochemist talent recruitment for silicon anode formulation development.
Tennessee
Mid-South automotive manufacturing heritage supports cathode-to-anode supply chain integration near Nashville. NHTSA fuel economy regulations accelerate OEM demand for qualified domestic suppliers. Chattanooga and Knoxville emerge as fast-charging formulation qualification sites for commercial fleet operators.
California
Last-mile delivery electrification programs in Los Angeles and San Francisco Bay Area demand volumetric energy density warranties with predictable range curves. California Air Resources Board fleet mandates compress procurement timelines for silicon-enhanced materials. Sacramento policy coordination influences IRA credit stacking strategies for multi-state operators.
Texas
Commercial vehicle fleet operators in Dallas-Fort Worth and Houston prioritize 15-minute charging capability for route turnaround optimization. ERCOT grid stability considerations shape battery storage co-location strategies for anode material processors. Port of Houston graphite import infrastructure supports qualified supplier qualification for IRA compliance.
United States Electric Vehicle Battery Anode Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the anode material value chain, creating tiered supplier structures where scale-driven synthetic graphite producers face silicon-carbon composite innovators. The vendor base segments between purification-focused feedstock processors and formulation-centric slurry engineers. Two dominant competitive moves define current positioning: capacity expansion into Midwest logistics corridors and strategic partnerships securing OEM qualification pipelines.
Within the silicon-carbon composite tier, Group14 Technologies and OneD Battery Sciences exemplify material architecture specialists developing higher intercalation capacity formulations. Anovion LLC anchors the synthetic graphite scale position among domestic producers. These three occupy distinct archetype positions—composite innovation, nanostructure engineering, and synthetic scale—without direct product overlap in current procurement cycles.
| Leading Market Players |
|---|
| Group14 Technologies |
| NEI Corporation |
| Sionic Energy |
| Anovion LLC |
| Enevate Corporation |
| Nouveau Monde Graphite |
| OneD Battery Sciences |
| NanoGraf Corporation |
| Paraclete Energy |
| Others |
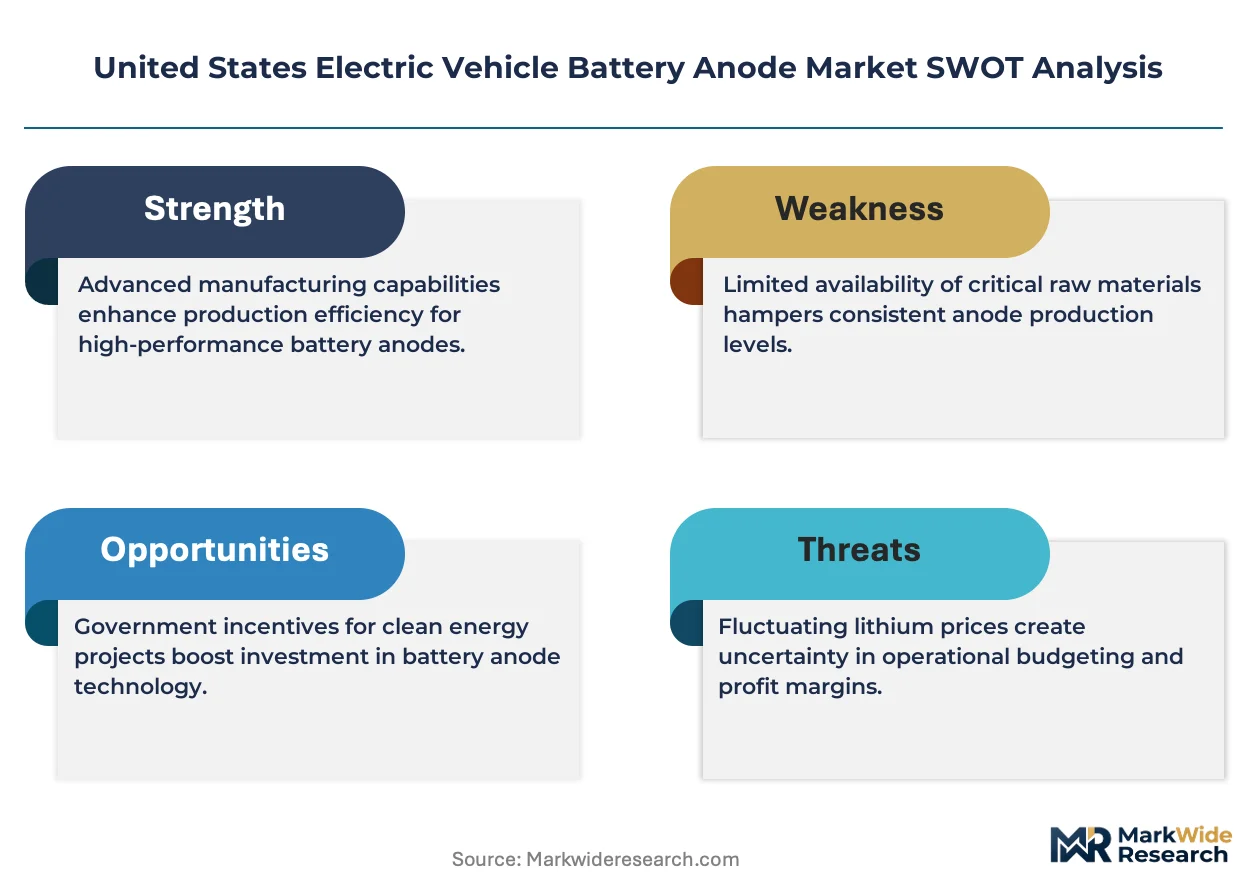
Pricing and Supply Chain Analysis
Automaker IRA compliance teams concentrate procurement authority around long-term offtake contracts rather than spot-market transactions, compressing pricing power toward suppliers with qualified domestic content. This buyer-archetype concentration locks in contract-based pricing structures that penalize foreign-sourced spherical graphite and reward synthetic anode producers with Michigan and Ohio processing footprints.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as OEMs accelerate qualification timelines to meet IRA phase-in deadlines. Pricing stratifies across battery-grade synthetic graphite, silicon-carbon composite, and fast-charging engineered carbon tiers, with certification status and volume scale as primary differentiation drivers. Cost compression in conventional graphite formulations is intensifying because purification capacity bottlenecks force cell manufacturers to absorb margin pressure from qualified suppliers. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while premium automakers prioritize energy density performance over unit economics.
Supply Chain Analysis
IRA domestic content thresholds are reshaping sourcing patterns away from Chinese spherical graphite toward U.S. synthetic production and Canadian natural flake processing. Feedstock dependencies center on petroleum coke for synthetic routes, natural graphite concentrate from Quebec and Ontario mines, and metallurgical-grade silicon from domestic polysilicon producers. Single-source vulnerability concentrates in battery-grade purified spherical graphite where Asian suppliers retain process expertise. Distribution runs through Midwest logistics corridors anchored by Detroit-area cell plants and Ohio River Valley gigafactory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electric Vehicle Battery Anode Market sits in a technology-transition phase where silicon-carbon composites are displacing conventional graphite in premium platforms, forcing incumbents to straddle legacy scale and next-generation formulation capabilities.
For Market Incumbents: Hedge graphite purification investments against silicon-carbon R&D acceleration by maintaining dual-capability production lines. Synthetic anode specialists should secure captive petroleum coke supply through backward integration into refinery partnerships before feedstock competition intensifies. Silicon volume expansion degradation remains the critical technical threat requiring pre-lithiation process patents as defensive moats. For New Entrants and Emerging Players: Direct qualification partnerships with Midwest battery pack integrators bypass OEM validation bottlenecks and compress revenue recognition timelines. Fleet operator fast-charging applications represent the most penetrable white-space segment given warranty-driven procurement consolidation. Target Ohio and Tennessee gigafactory corridors with just-in-time slurry delivery capabilities rather than competing on commodity graphite scale. For Investors and Strategic Acquirers: The window for entry favors silicon-carbon composite specialists with OEM qualification pipelines over undifferentiated purification capacity. Long-term viability over the mid-decade horizon rests on solid-state electrolyte interface engineering capabilities rather than conventional slurry formulation expertise. Watch EPA graphite purification emissions rule finalization as the inflection signal for synthetic versus natural processing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Graphite Capacity Expansion | IRA compliance teams at Michigan OEMs prioritize qualified domestic anode supply for tax credit eligibility. |
| Silicon-Carbon Composite R&D Partnership | Pre-lithiation technique patents secure first-mover positioning for premium EV platform qualifications. |
| Midwest Logistics Network Integration | Ohio River Valley finishing capacity reduces transport costs for Tennessee and Kentucky battery plants. |
| Solid-State Electrolyte Interface Development | Ceramic-compatible carbon substrates attract licensing interest from next-generation cell developers. |
| Fleet Operator Performance Guarantee Contracts | Volumetric energy density warranties shift degradation risk upstream to material suppliers. |
Research Methodology
Independent corroboration across electrochemist interviews at cell manufacturers, procurement leads at Tier 1 battery pack integrators, and regulatory affairs directors at anode material suppliers underwrites the qualitative findings. Secondary validation drew from EPA emissions rule dockets, IRA implementation guidance from Treasury, and customs data tracking graphite concentrate imports. Bottom-up capacity build estimates triangulated against top-down OEM demand projections across the analysis window.
Rate-of-change decomposition anchored the forecast framework, separating volume growth from price trajectory and mix shift effects across material chemistry, battery type, and end-user segments. Modeled dimensions included graphite versus silicon-composite material tiers, NMC versus LFP cell architectures, and automaker versus fleet operator procurement channels. CAGRs were derived from segment-level growth rate blending informed by IRA credit phase-in schedules and EPA permitting timeline assumptions.
Inputs from primary stakeholder interviews were available through the study window; gaps in pre-commercial solid-state anode qualification data introduce uncertainty bands around technology adoption timelines. Forecasts reflect assumptions regarding IRA domestic content threshold enforcement and Michigan battery plant ramp schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
US EV Battery Pack Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market