
 Posture Correction Market | 2026-2036
Posture Correction Market Size, Share, and Industry Trends Forecast 2026-2036
Posture Correction Market Outlook
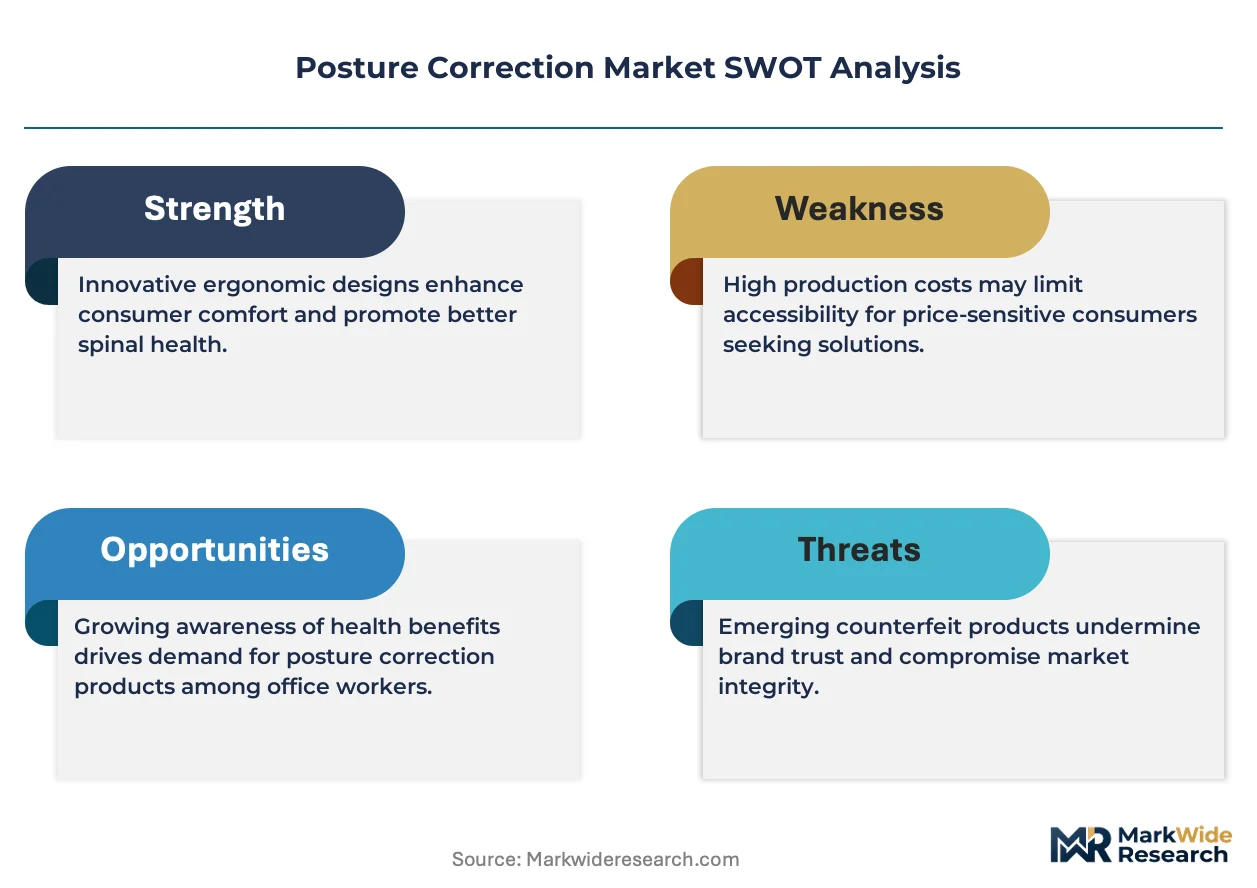
Corporate wellness spending is realigning demand toward ergonomic workplace solutions. Swedish Posture leverages its Scandinavian design heritage to dominate European office supply channels. Ottobock anchors its position through rehabilitation clinic partnerships and orthopedic certification depth. Aspen Medical Products specializes in clinical-grade posture supports for post-surgical recovery protocols.
Posture correction encompasses mechanical, electronic, and sensor-based systems engineered to realign spinal curvature, reduce musculoskeletal load, and prevent chronic back disorders through sustained biomechanical intervention. Smart sensor-equipped wearable devices incorporate accelerometers and gyroscopes measuring thoracic tilt angles with precision thresholds below two degrees deviation. Wearable devices with biofeedback technology represent the fastest-expanding segment as real-time haptic alerts replace passive brace designs. Traditional braces and supports retain volume leadership in rehabilitation settings where insurance reimbursement favors established product categories. Mobile applications integrated with wearable hardware are capturing margin pools through subscription-based coaching revenue models.
The FDA classifies posture correction wearables as Class I or II medical devices depending on therapeutic claims, requiring 510(k) clearance for biofeedback-enabled units marketed for pain relief. The EU MDR and CE marking framework mandate clinical evidence for posture devices carrying medical indications, tightening market access for unverified products. HIPAA compliance obligations bind corporate wellness platforms handling employee biometric data from connected posture monitors. Stakeholders must track evolving digital health reimbursement codes and MDR notified body capacity constraints as decisive variables for commercialization timelines.
Market Dynamics
Corporate biometric data collection through wearable posture devices is forcing HIPAA compliance obligations onto wellness platform operators, reshaping vendor liability structures and procurement vetting protocols across employer-sponsored health programs.
Growth Catalysts
- EU MDR clinical evidence mandates:Posture devices carrying medical indications now require notified body certification, filtering low-quality competitors and elevating reimbursement eligibility for compliant manufacturers across Germany, France, and Italy.
- Sensor fusion miniaturization:Accelerometer-gyroscope integration below 2-degree precision thresholds enables real-time haptic biofeedback in workplace settings, displacing passive brace designs among knowledge worker populations.
- Rehabilitation clinic procurement:Post-surgical recovery protocols in orthopedic centers are standardizing clinical-grade posture supports, anchoring volume demand through insurance-preferred product categories.
Market Restraints
- MDR notified body capacity constraints:Limited certification bandwidth in Europe extends commercialization timelines for biofeedback-enabled devices seeking CE marking under medical device classifications.
- Semiconductor input volatility:MEMS sensor supply concentration in East Asian foundries exposes wearable posture device margins to foundry allocation disruptions and tariff exposure.
- Passive brace substitution persistence:Traditional elastic supports retain cost advantage in price-sensitive consumer channels, compressing smart wearable penetration in direct-to-retail segments.
Strategic Opportunities
- Subscription coaching revenue models:Mobile application integration with wearable hardware captures recurring margin pools through personalized biomechanical coaching services.
- Scandinavian design premium positioning:Aesthetic-forward ergonomic solutions command office supply channel preference in Northern European corporate wellness deployments.
- FDA 510(k) pathway optimization:Streamlined clearance for Class II biofeedback devices marketed for pain relief accelerates US market access relative to EU regulatory complexity.
Industry Challenges
- Biomechanical engineering talent scarcity:Cross-functional expertise spanning orthopedics, sensor physics, and UX design concentrates in Boston and Stockholm clusters, constraining R&D scaling for mid-tier vendors.
- Legacy EHR integration complexity:Corporate wellness platforms face API fragmentation when connecting posture biometric streams to existing employer health record systems, delaying enterprise contract closures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Posture Correction Market |
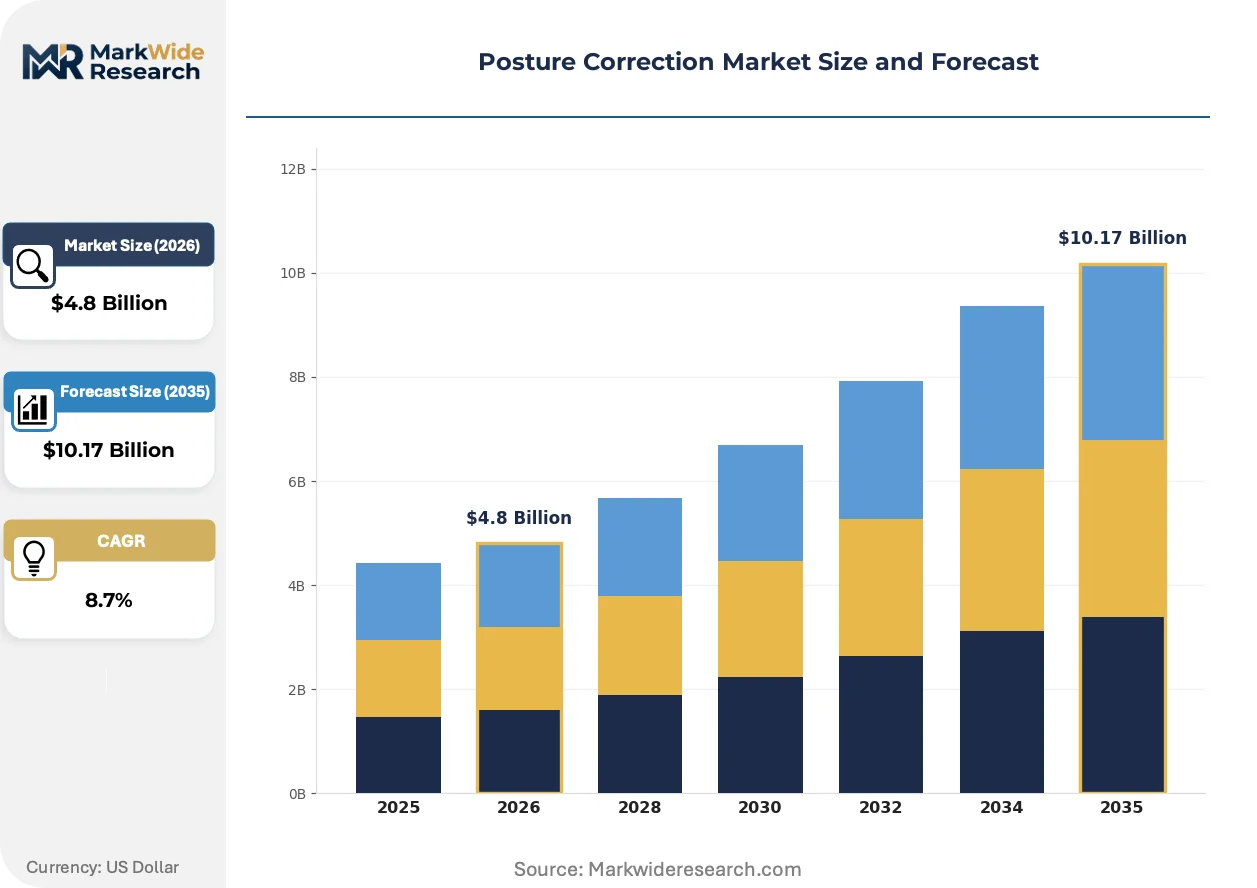
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Supports, Wearable Devices, Cushions End User: Individuals, Corporates, Healthcare Facilities, Fitness Trainers Technology: Smart Sensors, Biofeedback, Traditional Methods, Mobile Applications Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Direct Sales |
| Companies Covered | BackJoy, Swedish Posture, Upright, Aspen Medical Products, Evoke Pro, Comfy Brace, ITA-Med Co., Ottobock, BetterBack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Posture Correction Market Strategic Shifts
Real-time spinal tracking is compressing the gap between clinical intervention and daily behavioral correction, embedding biomechanical monitoring into continuous workplace health infrastructure rather than episodic treatment.
Machine learning inference at the edge is automating posture classification directly on wearable processors, eliminating cloud latency for haptic feedback loops. Manufacturing engineers in Shenzhen and Taipei are adopting on-device neural architectures for sub-100-millisecond alert generation. This compression of decision architecture is automating the shift from reactive brace support to predictive musculoskeletal load management.
EU MDR Article 10 clinical evidence requirements are elevating post-market surveillance obligations for posture devices with pain relief claims. Manufacturers must now maintain periodic safety update reports and vigilance systems, increasing regulatory operating overhead. Rehabilitation-focused product lines in Germany and the Netherlands are responding by deepening orthopedic surgeon advisory board engagement to preempt scrutiny.
Employer procurement committees are unbundling posture hardware from bundled wellness contracts, demanding standalone ROI demonstration for connected device deployments. Benefits consultants in London and New York are replacing all-inclusive vendor relationships with modular point-solution evaluations. This purchasing pattern shift is most visible in Fortune 500 technology sector implementations, where procurement autonomy for ergonomic equipment has decentralized to facilities management departments.
Posture Correction Market Segmentation
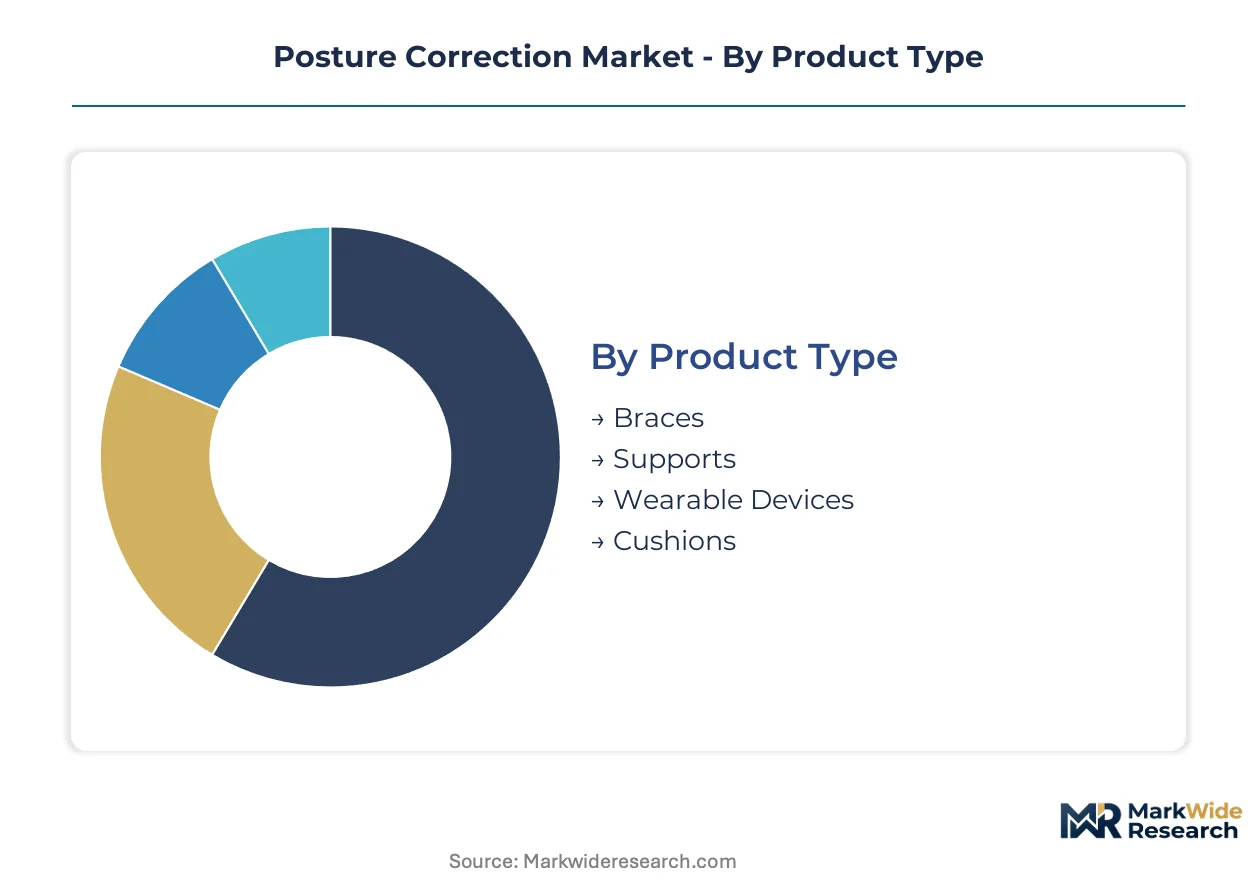
Posture correction solutions span divergent regulatory pathways, with medical-grade wearables facing FDA 510(k) or EU MDR scrutiny while consumer braces navigate lighter compliance burdens. Segmentation reveals where certification investments concentrate returns and where price compression dominates.
Product Type:
EU MDR Article 10 clinical evidence mandates bifurcate this category: wearable devices with pain relief claims require notified body certification, while passive braces fall under general wellness exemptions unless marketed for post-surgical recovery.
- Wearable Devices:Accelerometer-gyroscope fusion enables sub-2-degree thoracic tilt precision with real-time haptic biofeedback. Demand clusters in German corporate wellness programs where employers demand HIPAA-compliant biometric platforms for knowledge worker populations.
- Braces:Elastic and rigid mechanical designs dominate post-surgical rehabilitation protocols in orthopedic centers. Insurance reimbursement channels in the United States and Germany favor these established categories over unproven smart alternatives, anchoring volume through clinical procurement.
- Supports:Lumbar and cervical support systems target occupational health interventions with lower regulatory thresholds.
- Cushions:Ergonomic seating accessories penetrate office supply channels without medical device classification.
Leading the category by volume: Braces. Growing fastest: Wearable Devices.
End User:
Procurement autonomy decentralizes across this dimension, with corporate facilities managers gaining independent purchasing authority while healthcare systems maintain centralized orthopedic supply committees.
- Healthcare Facilities:Rehabilitation clinics and orthopedic centers standardize clinical-grade posture supports for post-surgical recovery, with procurement tied to surgeon preference and insurance pre-authorization workflows. German hospital networks concentrate demand for MDR-certified devices with vigilance system documentation.
- Corporates:Fortune 500 technology sector employers unbundle posture hardware from bundled wellness contracts, demanding standalone ROI demonstration for connected device deployments. Benefits consultants in London and New York drive modular point-solution evaluations.
- Individuals:Direct-to-consumer channels favor price-competitive passive solutions over premium smart wearables.
- Fitness Trainers:Boutique coaching studios adopt biofeedback tools for client retention and differentiated service offerings.
Highest certification burden: Healthcare Facilities. Steepest expansion trajectory: Corporates.
Technology:
Edge computing architectures and cloud latency elimination differentiate premium tiers from commodity alternatives, with on-device neural inference commanding manufacturing premiums in Shenzhen and Taipei foundries.
- Smart Sensors:MEMS accelerometer and gyroscope integration enables continuous spinal tracking with sub-100-millisecond alert generation. Manufacturing concentrates in East Asian foundries exposed to semiconductor allocation volatility and tariff exposure.
- Mobile Applications:Subscription-based coaching revenue models capture recurring margin pools when integrated with wearable hardware. HIPAA compliance obligations bind corporate wellness platforms handling employee biometric data streams.
- Biofeedback:Haptic and visual alert systems displace passive designs among biomechanically sophisticated users.
- Traditional Methods:Mechanical correction without electronic components retains cost advantage in price-sensitive retail channels.
Margin concentration: Smart Sensors. Fastest-climbing adoption curve: Mobile Applications.
Distribution Channel:
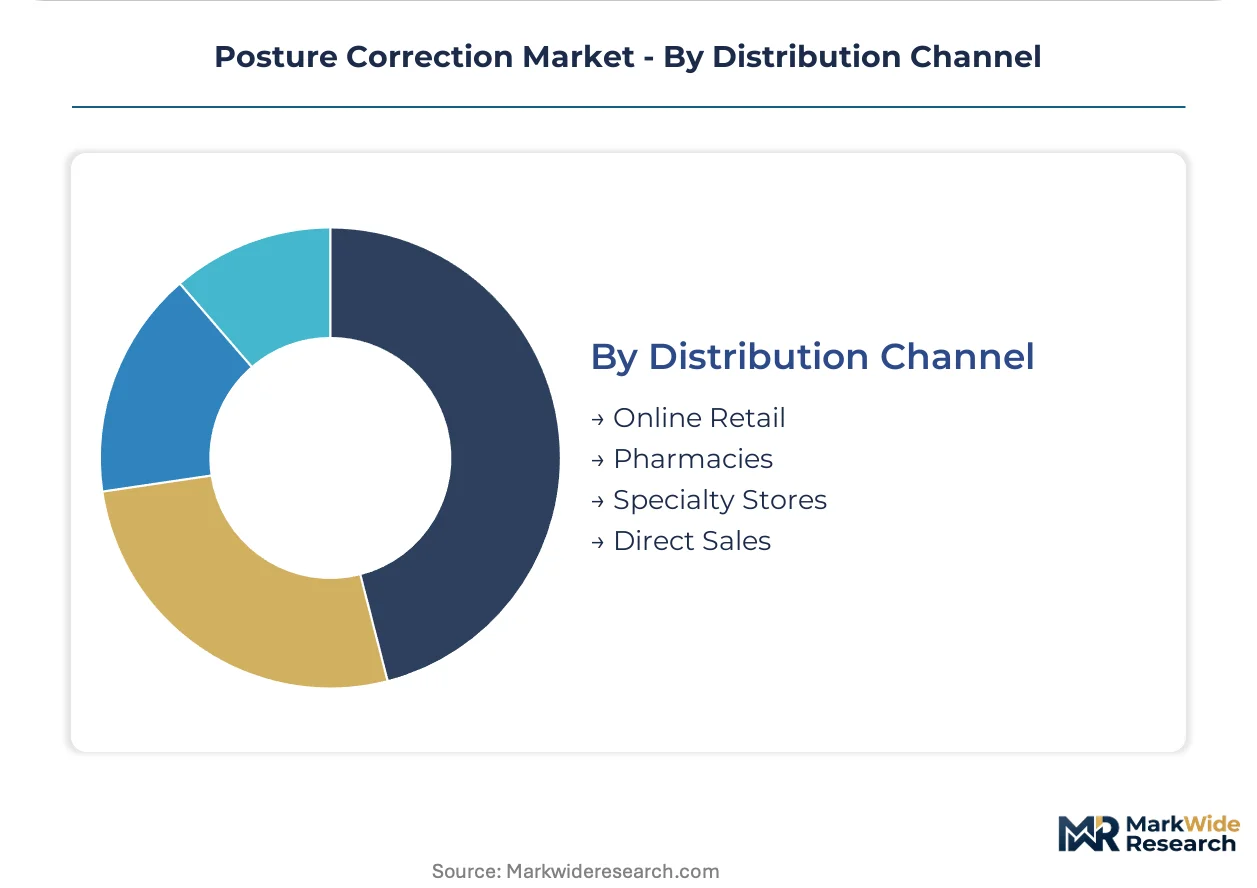
Channel selection determines regulatory exposure, with pharmacy and specialty store routes demanding CE marking or FDA clearance while online retail accommodates broader wellness positioning.
- Direct Sales:Rehabilitation clinic partnerships and orthopedic surgeon advisory relationships anchor clinical-grade product distribution, particularly for post-surgical recovery protocols in Germany and the Netherlands. Deep certification documentation supports premium pricing.
- Specialty Stores:Scandinavian design-forward ergonomic solutions command office supply channel preference in Northern European corporate wellness deployments, with aesthetic differentiation supporting margin capture.
- Online Retail:Direct-to-consumer platforms compress margins through price transparency and passive brace substitution.
- Pharmacies:Regulated retail environments favor established product categories with reimbursement eligibility.
Deepest certification integration: Direct Sales. Widest volume penetration: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundries concentrate MEMS sensor production while European and North American markets absorb the majority of certified posture correction devices. Regulatory divergence between FDA 510(k) pathways and EU MDR Article 10 mandates shapes where manufacturers prioritize commercialization timelines.
Germany
Corporate wellness procurement in Frankfurt and Munich drives demand for HIPAA-compliant biometric platforms. EU MDR notified body certification elevates entry barriers for pain-relief wearable devices. The Rhine-Ruhr industrial corridor hosts orthopedic supply chain consolidation for post-surgical recovery protocols.
United States
Fortune 500 technology employers in Seattle and Austin unbundle posture hardware from bundled wellness contracts. FDA Class II clearance requirements for biofeedback-enabled devices accelerate relative to European regulatory complexity. Greater Boston concentrates biomechanical engineering talent for sensor-physics R&D.
China
Shenzhen and Taipei foundries manufacture sub-100-millisecond alert generation systems for edge-computing wearables. NMPA medical device registration applies to products with therapeutic pain-relief claims. Yangtze River Delta assembly plants face semiconductor allocation volatility from MEMS sensor supply concentration.
Sweden
Scandinavian design heritage commands premium positioning in Northern European office supply channels. CE marking under EU MDR applies to devices marketed for medical indications. Stockholm clusters concentrate cross-functional expertise spanning orthopedics and UX design.
Netherlands
Rehabilitation clinics in Amsterdam and Rotterdam standardize clinical-grade posture supports with vigilance system documentation. EMA-aligned medical device regulation governs post-market surveillance obligations. Eindhoven's high-tech systems sector supplies precision sensor components to wearable manufacturers.
Posture Correction Market Competitive Environment
Top-tier vendors anchor premium certification tiers, while mid-market specialists compete on design differentiation and channel access. The vendor base stratifies across three layers: MDR-certified medical device manufacturers, Scandinavian design-forward ergonomic brands, and price-competitive passive brace fabricators. Strategic archetypes include rehabilitation clinic partnership builders, corporate wellness platform integrators, and direct-to-consumer hardware marketers. Dominant competitive moves include orthopedic surgeon advisory board cultivation and subscription coaching service layering onto hardware margins.
Within the Scandinavian design tier, Swedish Posture exemplifies aesthetic-forward ergonomic solutions commanding office supply channel preference. Among rehabilitation-focused specialists, Ottobock and Aspen Medical Products occupy positions anchored by clinical-grade certification depth and post-surgical protocol integration. These three entities represent distinct competitive vectors: design premiumization, medical regulatory compliance, and institutional procurement penetration.
| Leading Market Players |
|---|
| BackJoy |
| Swedish Posture |
| Upright |
| Aspen Medical Products |
| Evoke Pro |
| Comfy Brace |
| ITA-Med Co. |
| Ottobock |
| BetterBack |
| Others |
Value Chain & Pricing Dynamics
Biomechanical engineering talent concentration in Greater Boston and Stockholm clusters creates labor-cost differentials that widen pricing-tier spreads between MDR-certified medical devices and consumer-grade passive braces.
Pricing Analysis
Margin tightening in the consumer brace tier traces to passive elastic substitution and direct-to-retail price transparency. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) certification depth and Scandinavian design heritage. Cost-down pressure on smart wearables accelerates because semiconductor input volatility from East Asian MEMS foundries compresses hardware margins. Healthcare facilities demonstrate lowest price sensitivity due to insurance reimbursement workflows, while individual consumers in online retail channels exhibit highest elasticity.
Supply Chain Analysis
Returns and refurbishment flows for biofeedback-enabled devices concentrate reverse logistics networks around Eindhoven's high-tech systems sector and Shenzhen assembly hubs. MEMS sensor production draws from Taiwan, South Korea, and China's Yangtze River Delta, with foundry allocation volatility posing single-source vulnerability. Raw material dependencies span accelerometer-grade silicon wafers, gyroscope MEMS substrates, and haptic actuator components. Distribution runs through rehabilitation clinic direct sales for certified tiers and online retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 clinical evidence mandates are forcing consolidation as subscale vendors face unsustainable notified body certification overhead.
For Market Incumbents: Acquire orthopedic surgeon advisory board relationships to preempt post-market surveillance scrutiny. Deepen FDA 510(k) pathway investments to accelerate US market access ahead of EU regulatory complexity. Anchor volume through rehabilitation clinic procurement standardization for post-surgical recovery protocols. For New Entrants and Emerging Players: Begin with corporate wellness platform integration for Fortune 500 technology sector employers unbundling posture hardware from bundled contracts. Target facilities management procurement autonomy in London and New York as the most penetrable entry channel. Deploy subscription coaching revenue models to capture recurring margin pools. For Investors and Strategic Acquirers: Re-rating potential sits with MDR-certified device manufacturers given EU notified body capacity constraints filtering low-quality competitors. Long-term viability favors archetypes with orthopedic certification depth and hospital system penetration. Monitor FDA 510(k) clearance velocity and MDR notified body queue lengths as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Notified Body Certification | CE marking under EU MDR Article 10 unlocks German hospital network procurement and reimbursement eligibility. |
| Orthopedic Surgeon Advisory Board | Clinical credibility preempts post-market surveillance scrutiny and anchors rehabilitation clinic partnerships. |
| Subscription Coaching Service Launch | Mobile application integration captures recurring revenue from corporate wellness biometric data platforms. |
| MEMS Sensor Supply Diversification | Reducing Taiwan and South Korea foundry concentration mitigates semiconductor allocation volatility exposure. |
| FDA 510(k) Pathway Optimization | Streamlined Class II clearance accelerates US market access relative to EU MDR commercialization timelines. |
Study Parameters
SEC 10-K filings, EU MDR notified body databases, and hospital procurement contract records formed the secondary backbone for market sizing. Primary interviews with orthopedic surgeons, corporate benefits consultants, biomedical engineers, and GPO contracts managers validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against regulatory filing data and channel shipment records.
Bottom-up modeling aggregated segment-level demand across product type, end user, technology, and distribution channel dimensions. Top-down validation referenced macroeconomic healthcare expenditure trends and corporate wellness program adoption rates. CAGRs were derived from regression analysis of historical certification timelines and reimbursement code evolution. Forecast inputs incorporated MEMS sensor foundry capacity constraints and MDR notified body queue length projections.
Regulatory timeline delays, semiconductor supply disruptions, and corporate wellness budget freezes are the dominant revision risks for posture correction market forecasts. Practitioners should monitor FDA 510(k) clearance backlogs, East Asian foundry allocation announcements, and Fortune 500 ergonomic procurement committee decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spectacle Lens Market
Medical Devices
Neuroprosthetics Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Venturi Mask Market
Medical Devices
Carotid Stents Market
Medical Devices
US C-Arms Market
Medical Devices
Midline Catheters Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Global Smart Biopsy Devices Market