
 Tattoo Removal Devices Market | 2026-2036
Tattoo Removal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Removal Devices Market Intelligence
Maintenance contracts and software-defined pulse-duration tuning is consolidating recurring revenue into device economics. Lumenis Ltd leverages its service infrastructure to lock in clinic loyalty across North America. Alma Lasers Ltd anchors its position in Asia-Pacific through localized technical support networks. Cutera, Inc. differentiates by bundling training certifications with hardware leases, raising switching costs for dermatology practices.
Tattoo removal devices employ nanosecond or picosecond laser pulses to fragment dermal ink particles without ablating surrounding tissue, with spot sizes ranging from 2 mm to 10 mm and wavelengths spanning 532 nm to 1064 nm to target specific pigment colors. Q-switched lasers still occupy the largest installed base due to lower capital requirements, though pico lasers are capturing the fastest growth as reduced treatment sessions improve clinic throughput. Home users represent the smallest end-user segment but carry the highest margin dilution risk from unregulated devices sold through e-commerce channels.
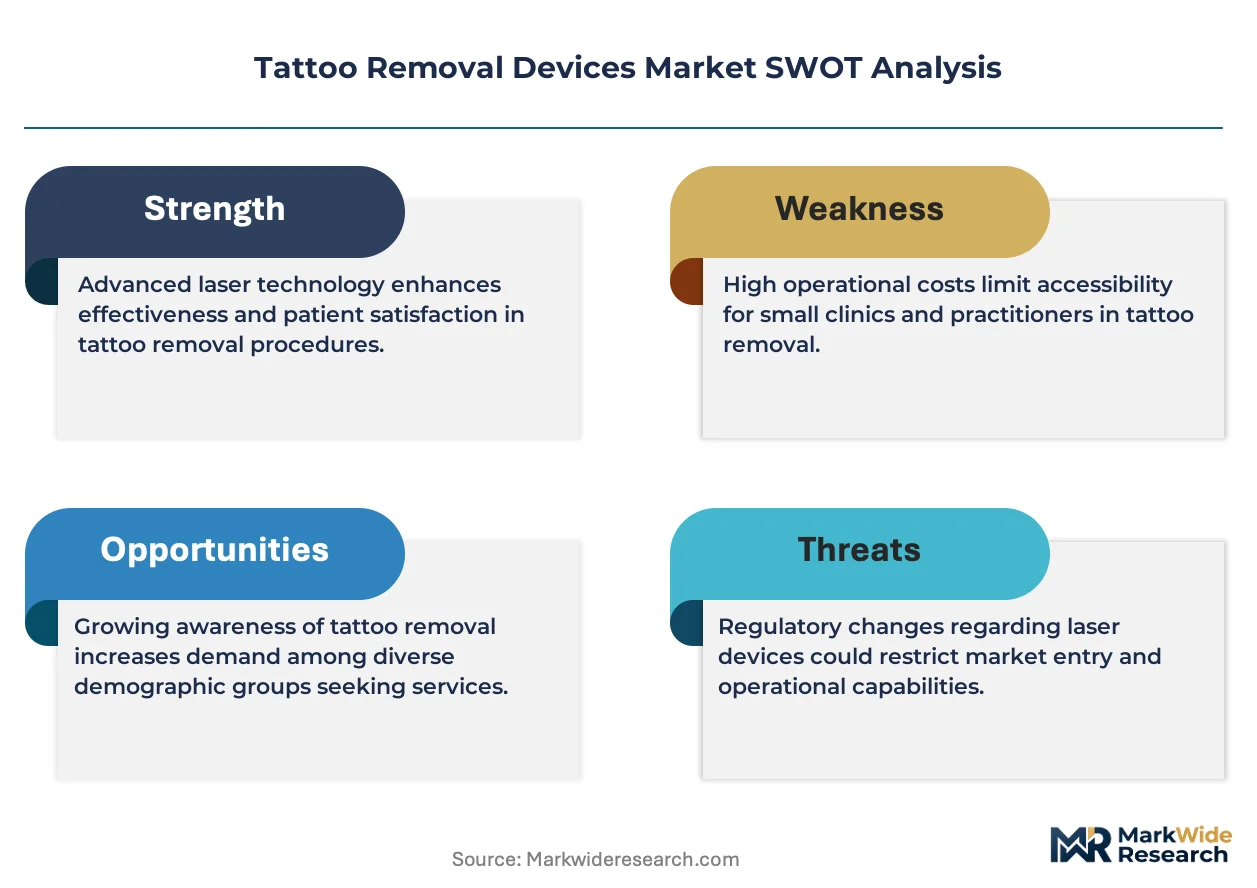
FDA 510(k) clearance pathways govern commercialization in the United States, while the EU MDR and CE marking requirements enforce clinical evidence standards for laser classification across European markets. The FDA's continued scrutiny of at-home IPL devices is compressing gray-market supply, redirecting price-sensitive consumers toward supervised clinic settings. Stakeholders must monitor how reimbursement coding for tattoo removal evolves relative to cosmetic versus medically indicated procedures, as this distinction determines addressable patient pools.
Market Dynamics
Picosecond laser systems are compressing treatment protocols from ten sessions to four, forcing clinic operators to recalibrate revenue-per-patient models and retire Q-switched hardware faster than depreciation schedules allow.
Growth Catalysts
- Millennial Tattoo Regret:One-third of US millennials now seek removal, creating sustained procedure demand that absorbs new device capacity across dermatology practices and med-spa chains.
- FDA 510(k) Pathway Streamlining:Expedited clearances for picosecond platforms with predicate device claims are accelerating commercialization timelines for manufacturers with established laser portfolios.
- Seoul Clinic Expansion:South Korean dermatology chains are deploying capital into dedicated removal centers, importing technical expertise from aesthetic surgery to standardize outcomes.
Market Restraints
- Capital Intensity:Picosecond systems require $150,000–$300,000 upfront investment, constraining independent clinic adoption and favoring consolidated healthcare networks with equipment leasing relationships.
- EU MDR Compliance Burden:Clinical evidence requirements for laser classification under the Medical Device Regulation are extending certification timelines and raising documentation costs for European manufacturers.
- Home-Device Substitution:Unregulated IPL devices sold through e-commerce channels capture price-sensitive consumers, diverting volume from supervised clinical settings and eroding margin pools.
Strategic Opportunities
- Brazilian Market Underpenetration:Tattoo culture penetration exceeds removal infrastructure by a factor of five, creating whitespace for device distributors to establish training partnerships with São Paulo dermatology networks.
- Software-Defined Pulse Tuning:Firmware-upgradable wavelength modules allow hardware to address emerging pigment types without capital replacement, converting one-time sales into recurring upgrade revenue.
- Medical Indication Expansion:Reimbursement coding for traumatic tattoo removal and post-surgical pigmentation correction is opening addressable patient pools beyond cosmetic self-pay segments.
Industry Challenges
- Laser Safety Officer Shortage:Certified technicians capable of calibrating picosecond systems are concentrated in Seoul, Los Angeles, and London, forcing clinics in secondary markets to pay 40% wage premiums.
- Legacy Q-Switched Stranded Assets:Rapid technology turnover leaves clinics with depreciated but functional equipment, complicating trade-in negotiations and residual value recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Removal Devices Market |
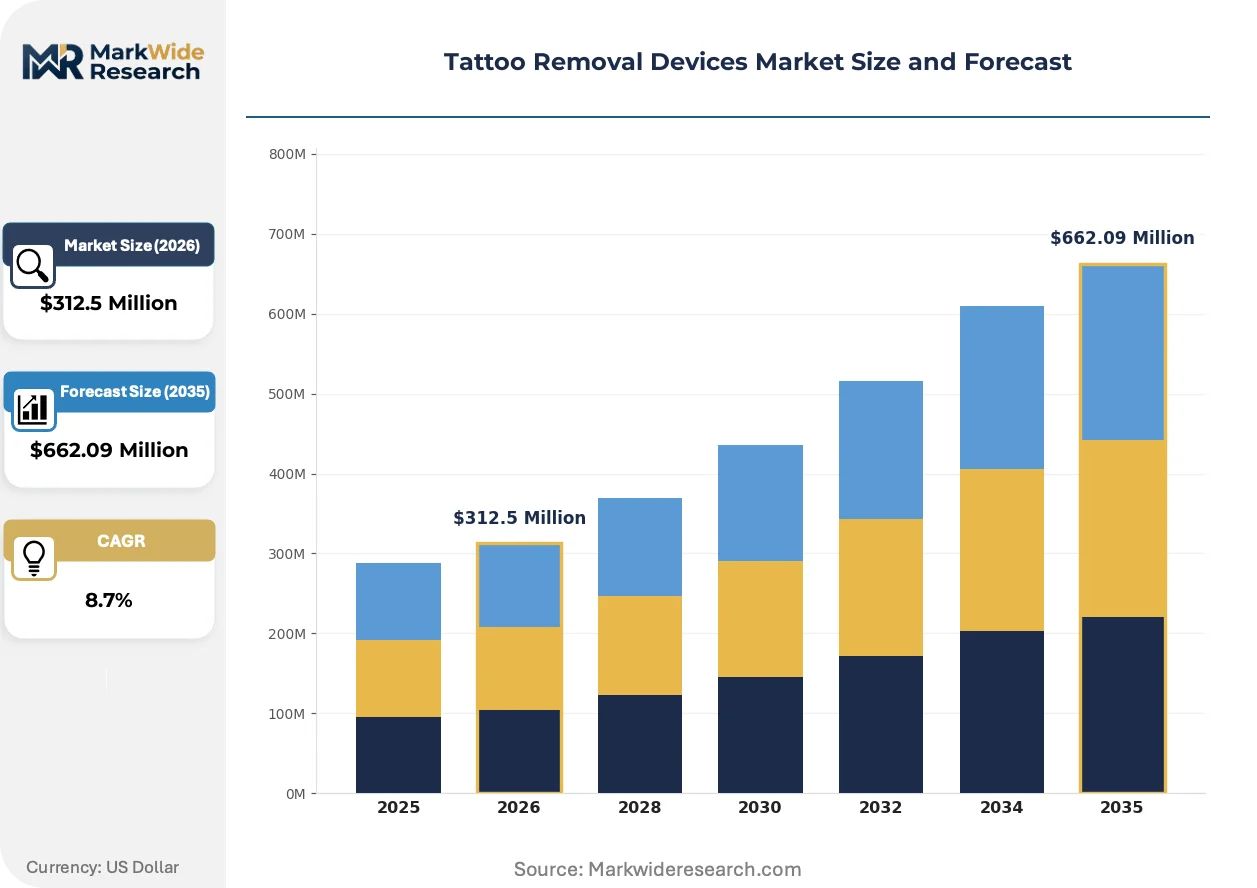
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Q-Switched Lasers, Pico Lasers, Surgical Devices, Creams End User: Clinics, Salons, Hospitals, Home Users Treatment Method: Laser Treatment, Surgical Excision, Dermabrasion, Chemical Peels Application: Cosmetic Removal, Tattoo Correction, Skin Rejuvenation, Scar Removal |
| Companies Covered | Lumenis Ltd, Astanza Laser, Inc., Alma Lasers Ltd, Asclepion Laser Technologies GmbH, Lutronic Corporation, Cutera, Inc., Fotona d.o.o., Syneron Medical Ltd, Cynosure, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Removal Devices Market Strategic Shifts & Innovations
Device economics are pivoting from hardware margins to recurring revenue streams, with manufacturers embedding software locks and service dependencies that extend customer lifetime value beyond the initial sale.
Picosecond platforms with dual-wavelength 532 nm and 1064 nm capability are consolidating market share among high-volume dermatology practices seeking to treat multicolor tattoos without hardware switching. Seoul-based clinic chains are adopting these systems at three times the rate of US counterparts, compressing per-session pricing and forcing competitors to match throughput efficiency or exit the segment.
The EU MDR's clinical evidence requirements for active optical devices are reshaping how manufacturers structure pre-market validation, with notified bodies demanding prospective pigmentation studies that add eighteen months to commercialization timelines. German manufacturers are responding by acquiring existing CE-marked portfolios rather than developing de novo systems, concentrating regulatory expertise within a handful of compliance-heavy firms.
Clinic procurement is fragmenting as independent practices bypass traditional distributor relationships to source refurbished Q-switched systems from secondary markets in Eastern Europe. This channel shift is most visible in Poland and Hungary, where cost-conscious operators prioritize capital preservation over picosecond performance, creating a bifurcated installed base that complicates manufacturer service standardization.
Tattoo Removal Devices Market Segmentation
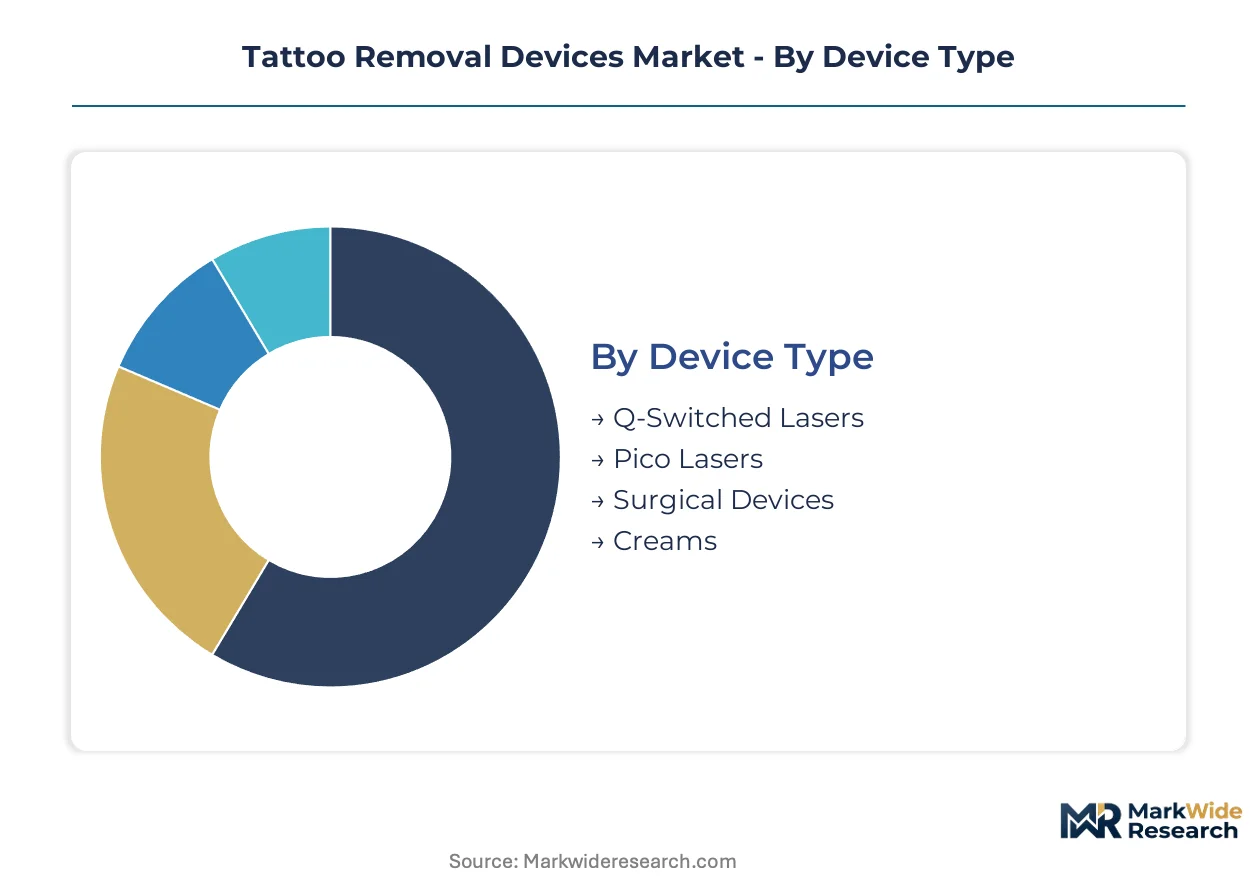
Segmentation in tattoo removal devices reveals divergent capital requirements, clinical workflows, and margin structures across hardware categories. Understanding these divisions clarifies where procurement budgets concentrate and which technology trajectories reshape competitive positioning.
Device Type:
Capital intensity varies sharply across this category, with picosecond platforms demanding $150,000–$300,000 upfront investment versus sub-$50,000 alternatives.
- Q-Switched Lasers:Nanosecond pulse technology dominates the installed base through lower acquisition costs and established service networks. Demand concentrates among independent dermatology practices in Poland and Hungary seeking capital preservation over performance gains.
- Pico Lasers:Picosecond pulse duration fragments ink particles more efficiently, compressing treatment protocols from ten sessions to four. Seoul clinic chains deploy these systems at three times the rate of US counterparts, prioritizing throughput efficiency over per-session pricing.
- Surgical Devices:Excision tools serve localized pigment removal with minimal equipment overhead.
- Creams:Topical formulations target home users with minimal regulatory burden.
Q-Switched Lasers absorb the bulk of installed capacity; Pico Lasers are expanding most quickly.
End User:
Customer type determines procurement authority, with consolidated healthcare networks wielding superior leasing leverage over fragmented independent operators.
- Clinics:Dermatology practices and med-spa chains generate the highest procedure volumes through supervised laser protocols. US millennials seeking removal sustain capacity utilization across metropolitan networks in Los Angeles and New York.
- Salons:Aesthetic service providers capture price-sensitive demand with lower regulatory compliance burdens than medical facilities.
- Hospitals:Academic medical centers handle complex traumatic tattoo cases and post-surgical pigmentation correction.
- Home Users:Consumers purchasing unregulated IPL devices through e-commerce channels erode margin pools from supervised clinical settings.
Clinics command the dominant share of professional-grade device procurement; Home Users represent the smallest but most margin-diluting segment.
Treatment Method:
Clinical efficacy and session count differentiate approaches, with laser-based protocols displacing mechanical alternatives through superior pigment clearance rates.
- Laser Treatment:Selective photothermolysis targets specific wavelengths to 532 nm for red pigments and 1064 nm for black ink without ablating surrounding tissue. Seoul operators standardize dual-wavelength platforms to treat multicolor tattoos without hardware switching.
- Surgical Excision:Physical removal suits small, localized tattoos where laser protocols prove impractical.
- Dermabrasion:Mechanical abrasion of epidermal layers persists in cost-constrained markets despite inferior cosmetic outcomes.
- Chemical Peels:Acid-based exfoliation occupies niche applications with limited clinical adoption.
Laser Treatment anchors professional practice revenue; Surgical Excision retains utility for specific anatomical constraints.
Application:
Reimbursement eligibility separates cosmetic self-pay procedures from medically indicated treatments, altering addressable patient pools.
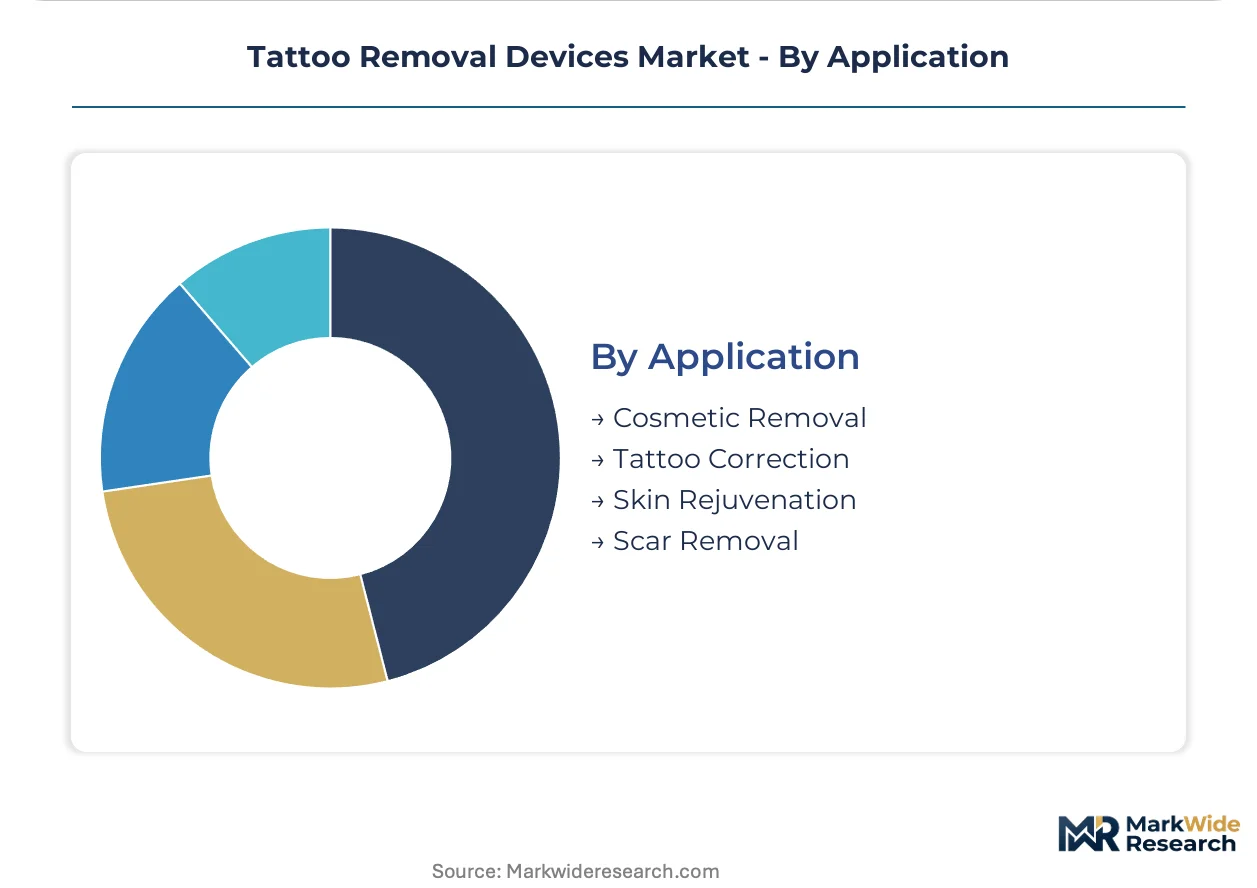
- Cosmetic Removal:Elective procedures driven by tattoo regret among millennials constitute the volume base. FDA 510(k) clearance pathways govern commercialization for this indication.
- Tattoo Correction:Partial removal and cover-up preparation services command premium pricing for artistic refinement.
- Skin Rejuvenation:Collateral tissue effects from laser protocols extend device utility into adjacent aesthetic applications.
- Scar Removal:Traumatic tattoo and post-surgical pigmentation cases qualify for reimbursement coding in select jurisdictions.
Cosmetic Removal generates the predominant procedure volume; Scar Removal opens the fastest-expanding reimbursable patient pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production clusters in Germany, South Korea, and the United States while consumption concentrates in dermatology markets with high tattoo prevalence and disposable income. Manufacturing capacity favors precision optics hubs, yet procedure volume drives revenue realization in metropolitan clinic networks.
United States
Millennial tattoo regret sustains procedure demand across Los Angeles and New York dermatology networks. FDA 510(k) clearance pathways govern commercialization timelines for picosecond platforms entering the market. Metropolitan clinic chains in California and Texas deploy dual-wavelength systems to capture multicolor removal volume.
Germany
EU MDR compliance requirements extend certification timelines for laser classification, favoring established manufacturers with regulatory expertise. The Medical Device Regulation enforces clinical evidence standards that concentrate market access among capital-heavy firms. Manufacturing clusters in Bavaria and Baden-Württemberg supply precision optical components to global device assemblers.
South Korea
Seoul clinic chains adopt picosecond platforms at triple the rate of US counterparts, compressing per-session pricing through throughput efficiency. MFDS oversight aligns with international standards while enabling faster domestic approval pathways. Gangnam district dermatology centers import technical expertise from aesthetic surgery to standardize removal outcomes.
Brazil
Tattoo culture penetration exceeds removal infrastructure by a factor of five, creating whitespace for distributor partnerships with São Paulo networks. ANVISA regulates active optical devices under medical equipment classifications that delay market entry for unprepared applicants. Southeastern clinic operators in Rio de Janeiro and Belo Horizonte represent the primary addressable demand pool.
Poland
Cost-conscious operators source refurbished Q-switched systems from secondary markets, prioritizing capital preservation over picosecond performance. National pharmaceutical regulator oversight of laser classification remains less stringent than EU MDR standards. Warsaw and Krakow independent practices drive procurement through distributor bypass channels.
Tattoo Removal Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a bifurcated structure where regulatory compliance costs favor consolidated incumbents. The installed base fragments between premium picosecond platforms and legacy Q-switched hardware serving price-sensitive segments. Three archetypes dominate: vertically integrated optics manufacturers, service-leasing bundlers, and refurbished equipment traders. Consolidation accelerates through M&A of CE-marked portfolios and capacity expansion into underpenetrated Latin American markets.
Among Israel-based laser specialists, Lumenis Ltd and Alma Lasers Ltd exemplify the service-infrastructure archetype, locking clinic loyalty through technical support networks. California-incorporated Cutera, Inc. occupies a position within the training-certification bundler tier. German GmbH-structured Asclepion Laser Technologies GmbH represents the precision-optics manufacturing archetype, supplying components that anchor European device assembly.
| Leading Market Players |
|---|
| Lumenis Ltd |
| Astanza Laser, Inc. |
| Alma Lasers Ltd |
| Asclepion Laser Technologies GmbH |
| Lutronic Corporation |
| Cutera, Inc. |
| Fotona d.o.o. |
| Syneron Medical Ltd |
| Cynosure, Inc. |
| Others |
Cost & Logistics Intelligence
EU MDR clinical evidence requirements for active optical devices gate qualified supply and premium-tier pricing access, concentrating certified picosecond platform distribution among capital-heavy manufacturers with established notified body relationships. This regulatory filtering compresses margin pools for uncertified competitors while elevating reimbursement-eligible device premiums.
Pricing Analysis
Price erosion across refurbished Q-switched tiers traces to secondary market sourcing in Poland and Hungary, where independent clinics prioritize capital preservation. Three-tier pricing structure across premium picosecond, standard Q-switched, and economy refurbished segments separates FDA-cleared platforms from CE-marked alternatives from gray-market equipment. Cost-down pressure on premium tiers accelerates because Seoul clinic chains compress per-session pricing through throughput efficiency. Home users exhibit highest price sensitivity; consolidated US dermatology networks wield lowest sensitivity due to equipment leasing relationships.
Supply Chain Analysis
German domestic-content mandates under EU MDR enforcement reshape sourcing toward Bavaria and Baden-Württemberg precision optics clusters. Manufacturing concentrates in Germany, South Korea, and the United States; component supply draws from specialized laser cavity foundries and wavelength module assemblers. Single-source vulnerability concentrates in picosecond pulse generation electronics sourced from Seoul-based suppliers. Distribution runs through authorized medical device distributors with service bundling capabilities, bypassed only in Eastern European secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tattoo removal devices market sits in a technology-transition phase where picosecond laser platforms displace legacy Q-switched hardware, compressing treatment protocols and forcing clinic operators toward capital-intensive upgrades.
For Market Incumbents: Cement service infrastructure lock-in through software-defined pulse tuning subscriptions that raise switching costs for dermatology practices. Acquire CE-marked portfolios to concentrate regulatory expertise under EU MDR compliance burdens, neutralizing emerging entrant certification delays.
For New Entrants and Emerging Players: Begin with Brazilian distributor partnerships targeting São Paulo dermatology networks where tattoo culture penetration exceeds removal infrastructure fivefold. Bundle training certifications with hardware leases to match Cutera's positioning without matching its capital base.
For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for picosecond predicate devices is the leading indicator that regulatory pathway efficiency is concentrating returns among established laser portfolios. Target vertically integrated optics manufacturers with captive wavelength module production across the mid-term horizon.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines for laser classification, favoring incumbents with notified body relationships. |
| Hospital System Partnership | Academic medical centers handling traumatic tattoo cases open reimbursable patient pools beyond cosmetic self-pay segments. |
| Software Companion Development | Firmware-upgradable wavelength modules convert one-time hardware sales into recurring upgrade revenue streams. |
| Reimbursement Strategy | Coding expansion for post-surgical pigmentation correction differentiates medically indicated from cosmetic procedure volumes. |
| Geographic Expansion | São Paulo and Rio de Janeiro dermatology networks represent underpenetrated whitespace for distributor partnerships. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR notified body guidance, and MFDS regulatory circulars, complemented by interviews with dermatology clinic operators, biomedical engineers calibrating picosecond systems, GPO contracts managers, and laser safety officers. Secondary validation drew from customs trade data, SEC equipment manufacturer disclosures, and hospital procurement database extracts. Bottom-up procedure volume estimates triangulated against top-down device shipment data.
Market size outputs across the projection horizon reflect installed base modeling by device type and treatment protocol compression rates. Segmentation dimensions span laser pulse duration category, end-user facility type, and reimbursable versus cosmetic indication. CAGRs derived from clinician adoption curve analysis and capital expenditure cycle timing. Procedure volume assumptions incorporated millennial tattoo regret survey data and clinic throughput efficiency gains.
Underlying measurement precision varies by segment; picosecond platform adoption rates carry tighter precision than home-device gray-market estimates. Forecasts reflect assumptions around regulatory clearance timelines and reimbursement coding evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Electrosurgical Generators Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Medical Tricorder Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Medical Electronics Market
Medical Devices
Infusion Pump Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market