
 Orthopedic Braces Market | 2026-2036
Orthopedic Braces Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Braces Market Intelligence
Medical-grade certification tiers is bifurcating the competitive landscape into premium validated products and basic consumer-grade alternatives. DJO LLC leverages extensive rehabilitation clinic partnerships to sustain North American channel dominance. Bauerfeind differentiates through proprietary knit compression technology and specialized sports medicine positioning. Ottobock anchors European demand with its long-standing prosthetics and orthotics manufacturing heritage.
Orthopedic braces are mechanical support devices constructed from neoprene, molded plastics, aluminum alloys, or composite fabrics, engineered to restrict joint motion, redistribute load, or correct musculoskeletal alignment through calibrated tension and structural reinforcement. Knee braces dominate volume due to high incidence of ligament injuries and osteoarthritis progression among aging populations. Ankle braces represent the fastest-growing product category as sports professionals and post-operative patients adopt prophylactic stabilization protocols. Fabric-based materials increasingly displace rigid metal constructs in rehabilitation settings where patient compliance and extended wear comfort determine clinical outcomes.
FDA 510(k) premarket notifications govern Class I and II brace commercialization in the United States, while the EU Medical Device Regulation mandates clinical evaluation reports and notified body oversight for European market access. ISO 13485 quality management certification has become a baseline procurement filter for hospital systems and distributor networks evaluating supplier qualifications. Stakeholders must monitor evolving reimbursement coding decisions by CMS and national health technology assessment bodies, as coverage determinations directly shape patient out-of-pocket exposure and category volume trajectories.
Market Dynamics
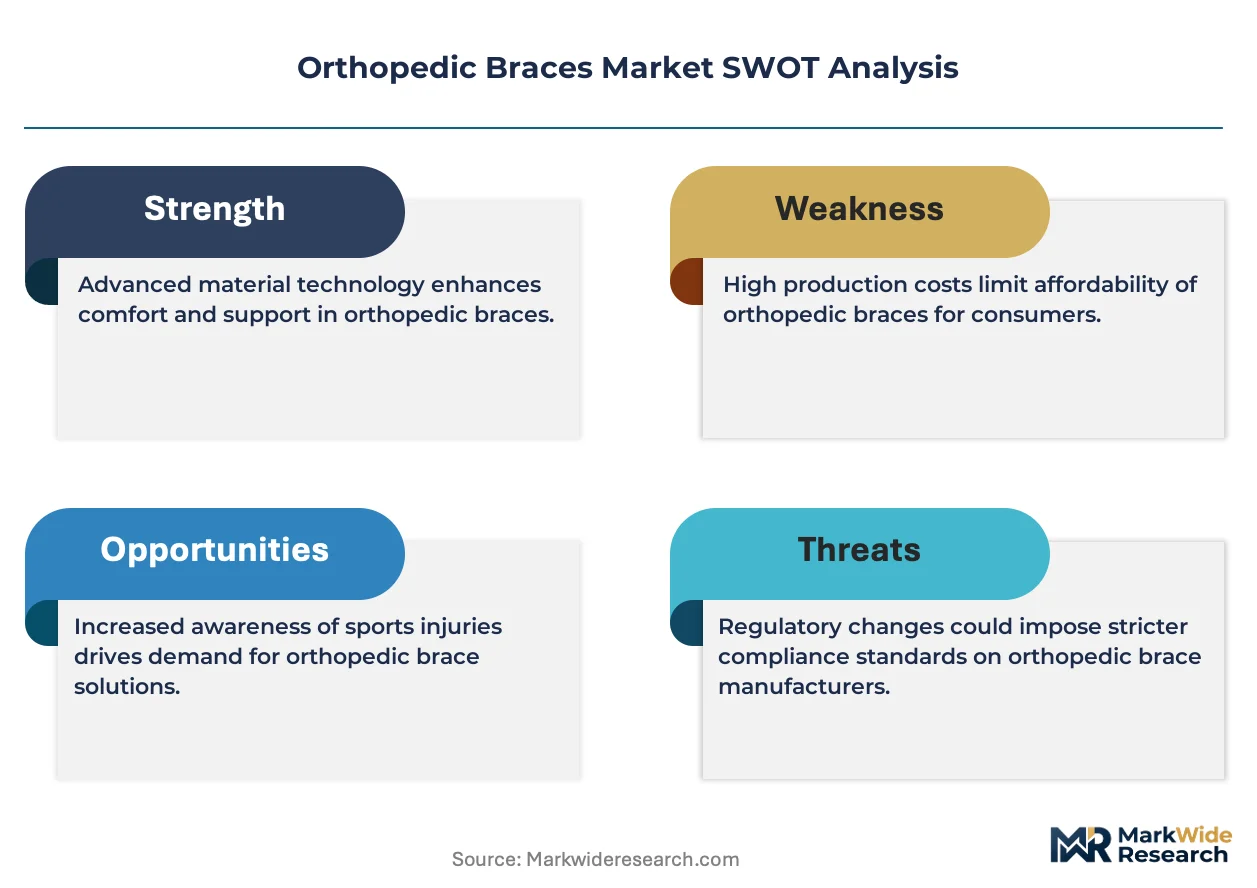
Medical device regulation bifurcation is compressing market access timelines for premium-grade orthopedic braces while accelerating commoditization pressure on unvalidated consumer alternatives. The EU MDR transition and FDA 510(k) pathway refinements are forcing manufacturers to front-load clinical evidence generation, reshaping competitive economics across all product tiers.
Growth Catalysts
- Aging demographics with osteoarthritis progression:Germany's statutory health insurance system expands reimbursement coverage for custom-fitted knee braces, channeling patient demand toward medical-grade solutions.
- EU MDR Article 10 clinical evaluation mandates:Manufacturers achieving notified body certification under strengthened performance documentation requirements capture hospital procurement preference.
- 3D scanning and additive manufacturing:Production facilities in Bavaria and North Rhine-Westphalia compress custom brace delivery cycles from weeks to days, unlocking sports medicine clinic volume.
Market Restraints
- Aluminum alloy and carbon fiber input volatility:Raw material price swings compress margin stability for mid-tier manufacturers dependent on Asian supply contracts.
- Notified body capacity bottlenecks:EU MDR designation delays for orthopedic device reviewers extend certification timelines 8-14 months beyond historical baselines.
- Consumer-grade elastic sleeve substitution:Unregulated compression garments priced at 15-20% of medical brace cost capture price-sensitive rehabilitation patients.
Strategic Opportunities
- Telehealth-integrated remote fitting protocols:Digital measurement applications paired with home delivery logistics unlock rural patient segments previously served only by urban orthotist clinics.
- Post-operative prophylactic ankle stabilization:Ambulatory surgery centers in Hesse and Baden-Württemberg are expanding brace dispensing protocols for ACL reconstruction patients.
- CSRD sustainability disclosure alignment:Early adopters of recycled neoprene and bio-based polymer sourcing secure ESG-mandated hospital system contracts.
Industry Challenges
- Orthotist technician workforce scarcity:German chambers of crafts report 23% vacancy rates for certified brace fitting specialists, constraining custom device throughput.
- Legacy ERP integration with MDR traceability systems:Small and mid-sized manufacturers face six-figure software upgrade costs to achieve Unique Device Identification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Braces Market |
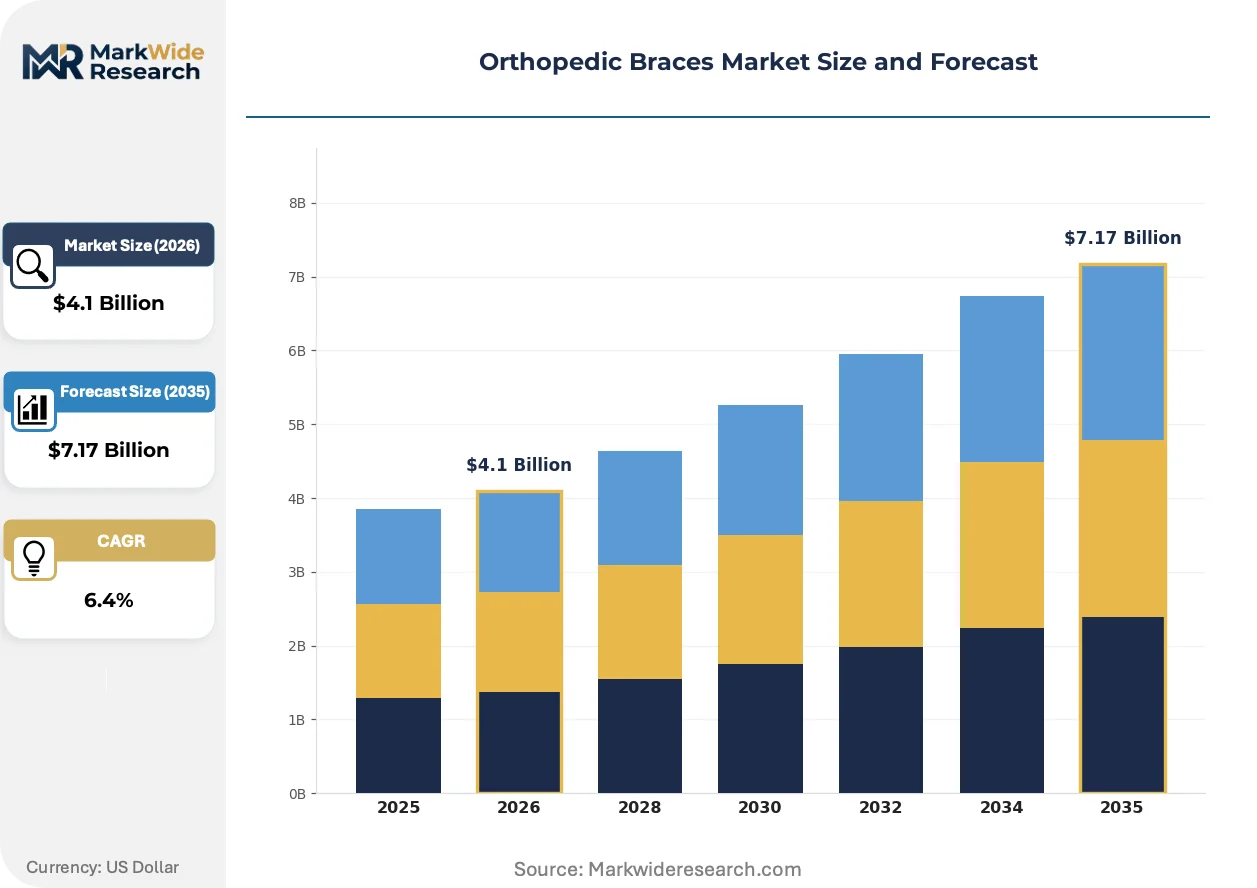
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Braces, Elbow Braces, Wrist Braces Material: Plastic, Metal, Neoprene, Fabric End User: Sports Professionals, Elderly Patients, Post-operative Patients, Rehabilitation Patients Application: Injury Prevention, Pain Relief, Post-surgery Support, Mobility Enhancement |
| Companies Covered | Össur, Breg, Inc., DJO LLC, Bauerfeind, Ottobock, DeRoyal Industries, Inc., 3M, Zimmer Biomet, Fillauer LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Braces Market Strategic Shifts & Innovations
Sensor-embedded brace systems are compressing the boundary between passive mechanical support and active rehabilitation monitoring, forcing manufacturers to develop firmware competencies alongside traditional orthotics expertise. This convergence is redistributing value capture toward data-integrated solution providers.
Carbon fiber composite layup automation is miniaturizing production cell footprints while maintaining structural performance specifications. German toolmaking suppliers in Stuttgart and Munich are deploying robotic fiber placement systems for knee brace frame manufacturing. Mid-sized orthopedic device producers are adopting these cells to reduce manual layup labor dependence and compress per-unit production costs without sacrificing customization flexibility.
EU MDR Annex XVI expansion to include products without intended medical purpose but similar risk profiles is capturing previously unregulated sports performance braces under clinical evaluation requirements. Manufacturers of prophylactic knee stabilizers previously marketed to recreational athletes must now compile post-market surveillance data. The transition is forcing portfolio rationalization decisions at firms with marginal European market exposure.
Athlete-directed purchasing through direct-to-consumer platforms is disintermediating traditional orthotist channels for non-prescription brace categories. Professional sports teams in Cologne and Frankfurt now maintain dedicated equipment procurement portals bypassing distributor markups. This channel compression is most visible in premium ankle brace segments where fit standardization allows self-measurement protocols.
Orthopedic Braces Market Segmentation
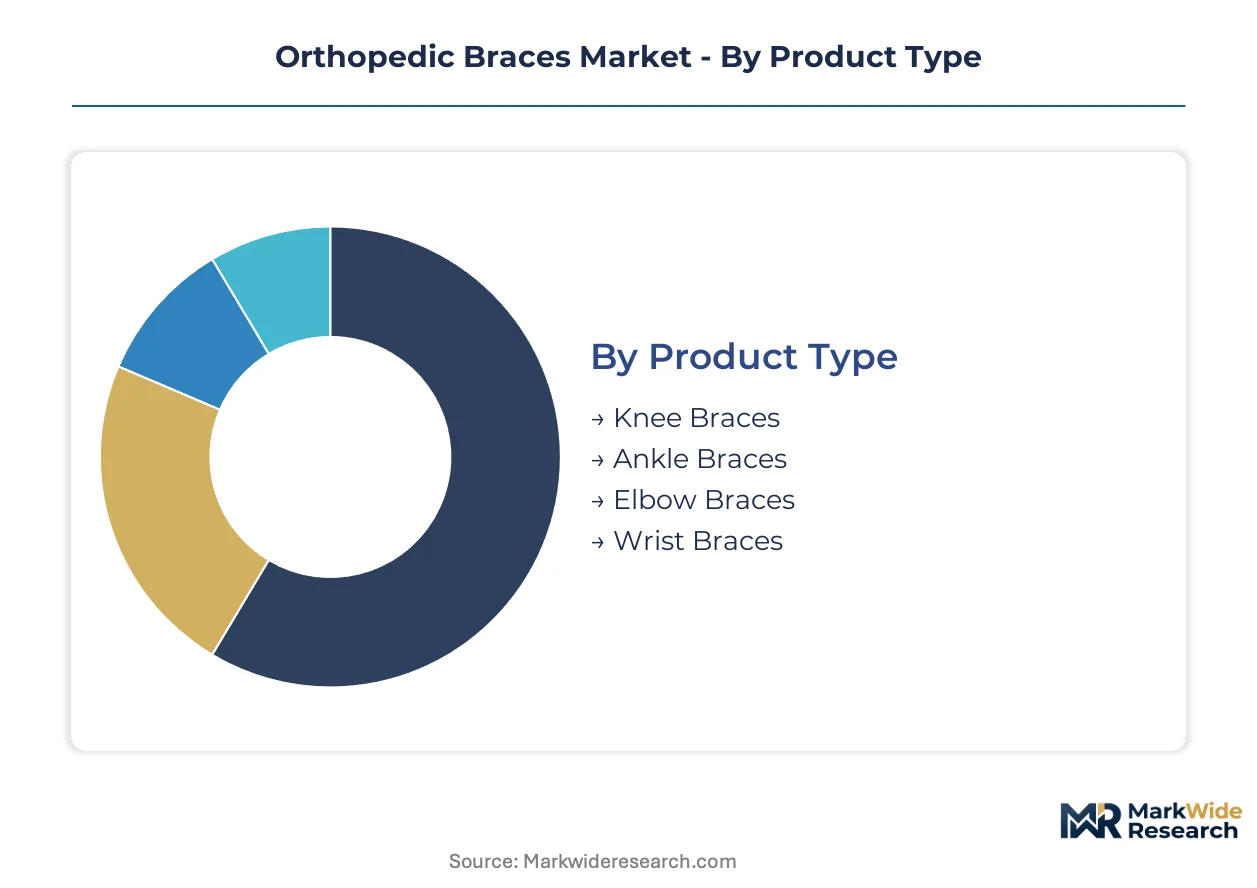
Orthopedic brace manufacturers configure product portfolios around distinct biomechanical requirements and reimbursement pathways. Channel strategy diverges sharply between hospital-procured medical devices and retail-accessible consumer support products.
Product Type:
Channel economics favor knee and ankle categories for institutional procurement, while wrist and elbow variants concentrate in direct-to-consumer and pharmacy distribution.
- Knee Braces:Hinged and compression designs incorporate aluminum alloy frames or molded polymer shells with adjustable tension straps. Germany's statutory health insurance system channels patient demand toward custom-fitted medical-grade solutions for osteoarthritis management.
- Ankle Braces:Lace-up and stirrup configurations utilize semi-rigid plastic shells or fabric-reinforced neoprene construction. Sports medicine clinics in Hesse and Baden-Württemberg are expanding prophylactic dispensing protocols for ACL reconstruction patients, accelerating volume expansion.
- Elbow Braces:Counterforce straps and hinged immobilizers target lateral epicondylitis and post-operative recovery.
- Wrist Braces:Dorsal splints and elastic wraps address carpal tunnel syndrome and fracture stabilization.
By volume, knee braces lead institutional procurement. By growth pace, ankle braces are expanding most quickly.
Material:
Cost tier stratification separates premium carbon-fiber composites from commodity elastic sleeves, with mid-tier manufacturers competing on hybrid fabric-metal constructions.
- Neoprene:Closed-cell synthetic rubber provides thermal retention and moisture-wicking properties for extended wear comfort. Rehabilitation settings prioritize patient compliance, displacing rigid metal constructs where extended daily use is prescribed.
- Fabric:Knit compression textiles with integrated silicone grip patterns enable breathable, low-profile stabilization. Bavarian production facilities deploy 3D scanning and additive manufacturing to compress custom brace delivery cycles.
- Plastic:Injection-molded polypropylene and polyethylene shells deliver structural rigidity at reduced unit cost.
- Metal:Aluminum alloy and stainless steel hinges provide calibrated motion restriction for post-surgical protocols.
Fabric-based materials are gaining share fastest in ambulatory settings. Metal constructs retain dominance in post-operative immobilization.
End User:
Customer type determines pricing power and certification requirements, with sports professionals and elderly patients representing opposite ends of the reimbursement spectrum.
- Sports Professionals:Teams in Cologne and Frankfurt maintain dedicated equipment procurement portals bypassing distributor markups, compressing channel margins.
- Elderly Patients:Osteoarthritis progression among aging populations drives statutory insurance coverage for custom-fitted devices in Germany.
- Post-operative Patients:Ambulatory surgery centers expand brace dispensing protocols as standard discharge procedures.
- Rehabilitation Patients:Long-term wear requirements prioritize comfort and compliance over maximum structural support.
Elderly patients generate the highest absolute volume. Sports professionals show the steepest expansion trajectory in premium ankle stabilization.
Application:
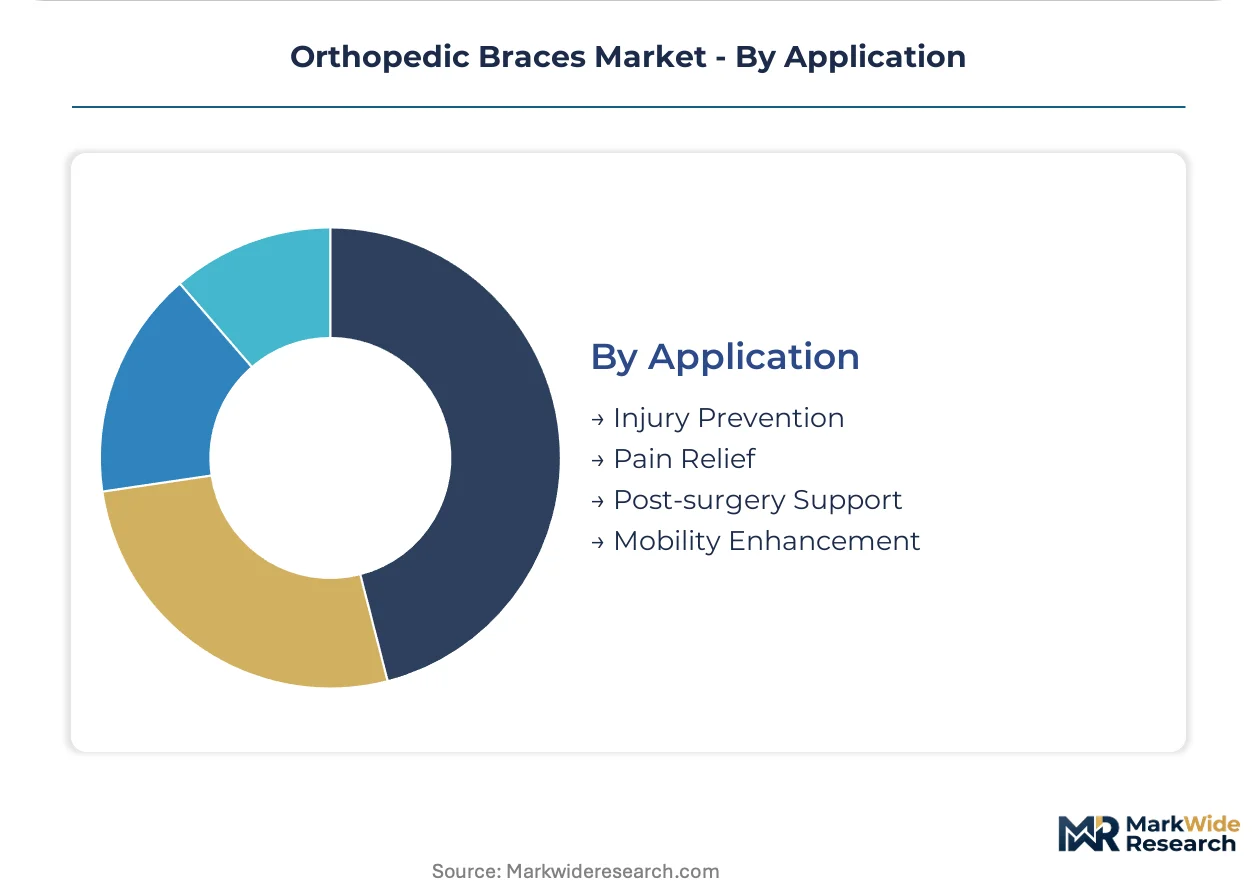
Reimbursement coding decisions by CMS and national health technology assessment bodies shape patient out-of-pocket exposure across functional use cases.
- Post-surgery Support:Rigid immobilization and graduated rehabilitation protocols require FDA 510(k) clearance and EU MDR notified body certification for hospital system access.
- Injury Prevention:Prophylactic knee stabilizers previously marketed to recreational athletes now fall under EU MDR Annex XVI clinical evaluation requirements.
- Pain Relief:Compression-based solutions compete with unregulated elastic sleeves priced at 15-20% of medical brace cost.
- Mobility Enhancement:Functional assistance devices for degenerative joint conditions integrate with physical therapy protocols.
Post-surgery support commands premium pricing tiers. Injury prevention is climbing the fastest as sports medicine protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export premium custom-fitted orthopedic braces to North American hospital systems and Asian sports medicine clinics, anchoring a trade corridor that channels EU MDR-certified devices into markets with divergent regulatory timelines.
United States
FDA 510(k) clearance pathways govern Class II brace commercialization, with rehabilitation clinic networks in Texas and Florida expanding procurement for post-operative knee stabilization. CMS reimbursement coding decisions shape patient out-of-pocket exposure, channeling demand toward medical-grade solutions over consumer alternatives.
Germany
Statutory health insurance expansion for osteoarthritis management drives custom-fitted knee brace volume, with Bavarian and North Rhine-Westphalian production clusters deploying 3D scanning and additive manufacturing to compress delivery cycles. KBA-regulated logistics infrastructure supports same-week distribution to Hesse and Baden-Württemberg ambulatory surgery centers.
China
NMPA medical device registration requirements are tightening performance documentation for imported orthopedic braces, with domestic manufacturers in Jiangsu and Zhejiang provinces scaling fabric-based production for rehabilitation settings. SAMR quality inspections are displacing unregulated elastic sleeve suppliers from hospital procurement channels.
Japan
PMDA premarket approval timelines extend 12-18 months for foreign-manufactured braces, incentivizing METI-supported joint ventures between German orthotics specialists and Osaka-based distributors. Kansai region rehabilitation hospitals prioritize patient compliance metrics, accelerating fabric-based material adoption over rigid metal constructs.
United Kingdom
MHRA post-Brexit regulatory divergence from EU MDR is creating parallel certification requirements for brace manufacturers, with London and Southeast England sports medicine clinics maintaining direct procurement relationships with German suppliers. NHS England coverage determinations for custom-fitted devices remain under technology assessment review.
Orthopedic Braces Market Key Industry Players
Listed leaders compete with private specialists across certification tier access, with publicly traded medical device conglomerates leveraging balance sheet capacity to absorb EU MDR compliance costs while family-owned orthotics firms defend niche positioning through orthotist technician relationships. Market structure consolidates around three archetypes: diversified medical device conglomerates with rehabilitation portfolios, specialized orthotics manufacturers with generational manufacturing heritage, and contract fabricators serving private-label distributors. Competitive moves concentrate on M&A absorption of notified body-certified product lines and backward integration into carbon fiber composite sourcing.
Among German-based specialists, Bauerfeind and Ottobock exemplify divergent archetype positioning within premium-tier orthopedic brace manufacturing. DJO LLC, operating as a Delaware-structured entity, represents the diversified conglomerate model with rehabilitation clinic channel dominance. Össur, with Icelandic corporate origins, occupies a position bridging prosthetics and orthotics manufacturing heritage with North American market access infrastructure.
| Leading Market Players |
|---|
| Össur |
| Breg, Inc. |
| DJO LLC |
| Bauerfeind |
| Ottobock |
| DeRoyal Industries, Inc. |
| 3M |
| Zimmer Biomet |
| Fillauer LLC |
| Others |
Cost & Logistics Intelligence
Fabric-based neoprene substitution for rigid aluminum and carbon fiber constructs is redrawing procurement geography toward Asian textile hubs while compressing per-unit production economics and enabling price competition against medical-grade alternatives.
Pricing Analysis
Current-generation sensor-embedded brace systems command substantial premiums over prior-generation passive mechanical designs, while next-generation AI-integrated rehabilitation monitors are entering limited pilot deployment. Three-tier pricing structure across premium FDA-cleared medical devices, mid-tier CE-marked clinical products, and economy consumer-grade sleeves dominates channel economics. Price differentiation rests on ISO 13485 certification tier and customization depth. Cost compression in the mid-tier is intensifying because notified body certification delays extend product launch timelines. Rehabilitation patients show highest price sensitivity, while sports professionals demonstrate lowest sensitivity due to equipment budget allowances.
Supply Chain Analysis
Inventory buffers for carbon fiber and aluminum alloy hinge components have compressed to 4-6 week cycles as manufacturers respond to raw material price volatility. Supply concentrates in Germany for precision-machined metal components, China for neoprene and knit textiles, and Vietnam for injection-molded plastic shells. Raw material dependencies span carbon fiber from Japanese Toray suppliers, medical-grade neoprene from Malaysian petrochemical complexes, and aluminum alloys from South Korean smelters. Single-source vulnerability in notified body certification capacity creates bottleneck risk for EU market access. Distribution runs through hospital procurement committees, orthotist clinic networks, and direct-to-consumer platforms serving sports professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified orthotist technician shortages in German production clusters constrain custom-fitted device throughput, creating a capability gap that manufacturers must address through automation investment or workforce development partnerships.
For Market Incumbents: Secure backward integration into carbon fiber composite sourcing to insulate margin stability from Asian supply contract volatility. Expand additive manufacturing capacity in Bavaria and North Rhine-Westphalia to compress custom brace delivery cycles and defend against telehealth-integrated remote fitting entrants. Prioritize EU MDR Annex XVI compliance investment for sports performance brace portfolios previously marketed outside medical device frameworks. For New Entrants and Emerging Players: Lead with telehealth-integrated remote fitting protocols targeting rural patient segments underserved by urban orthotist clinic networks. Exploit white-space opportunity in post-operative prophylactic ankle stabilization protocols at ambulatory surgery centers in Hesse and Baden-Württemberg. Pursue hospital system partnership go-to-market angle leveraging CSRD sustainability disclosure alignment for ESG-mandated contract eligibility. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors diversified medical device conglomerates with balance sheet capacity to absorb EU MDR compliance costs. Long-term viability across the analysis window favors acquisition targets with notified body-certified product lines and established rehabilitation clinic channel relationships. Monitor notified body designation expansion timelines as inflection indicator for competitive access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex XVI compliance unlocks hospital procurement preference in German statutory insurance system. |
| Hospital System Partnership | Direct GPO contracts with Hesse and Baden-Württemberg ambulatory surgery centers secure post-operative dispensing protocols. |
| Software Companion Development | Sensor-embedded firmware integration transforms passive braces into active rehabilitation monitoring platforms. |
| Reimbursement Strategy | CMS coding alignment and German statutory health insurance coverage determinations shape patient out-of-pocket exposure. |
| Backward Integration | Captive carbon fiber composite sourcing insulates production economics from Asian supply contract volatility. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body certification records, and German statutory health insurance reimbursement schedules preceded structured interviews with orthotist technicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from ISO 13485 audit registries, CMS Medicare coverage determinations, and customs trade data for orthopedic device imports. Bottom-up volume estimates triangulated against top-down market sizing from statutory insurance expenditure reports.
Variance decomposition across product type, material composition, end-user archetype, and application use case informed segment-level growth trajectories throughout the forecast period. CAGRs were derived from regression analysis of historical reimbursement expansion patterns and sports medicine protocol adoption curves. Modeled inputs incorporated 3D scanning penetration rates in Bavarian production clusters and telehealth-integrated remote fitting adoption among rural patient populations.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR notified body oversight frameworks; material policy shifts such as CMS reimbursement coding revisions or EU MDR Annex XVI expansion would require re-modeling. Commodity price volatility in carbon fiber and aluminum alloys, workforce scarcity in certified orthotist technicians, and notified body capacity bottlenecks represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Orthopaedic Cushions Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
3D Medical Implant Market