
 Esophageal Cancer Drugs Market | 2026-2036
Esophageal Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Cancer Drugs Market Analysis
The EU Green Deal's pharmaceutical sustainability criteria is rebalancing procurement standards across European oncology networks. Bristol-Myers Squibb Company leverages its integrated biologics manufacturing network to sustain supply continuity for checkpoint inhibitors. Merck & Co., Inc. anchors its position through deep investment in biomarker-driven patient stratification platforms.
Esophageal cancer drugs comprise systemic therapeutic agents designed to inhibit malignant cell proliferation in squamous cell carcinoma and adenocarcinoma of the esophagus, typically administered as monoclonal antibodies, small molecule inhibitors, or cytotoxic compounds requiring cold-chain distribution. These agents function by interrupting PD-1/PD-L1 signaling, VEGF-mediated angiogenesis, or microtubule assembly, with treatment protocols calibrated to histology subtype and staging. Immunotherapy now commands the dominant margin pool as anti-PD-1 agents displace first-line chemotherapy in HER2-negative populations. Intravenous administration remains the volume leader, though subcutaneous formulations are gaining traction in homecare settings where patient convenience drives formulary preference.
The FDA, EMA, and Japan's PMDA collectively govern approval pathways, with the FDA's Project Orbis enabling simultaneous multi-country review that compresses launch timelines across jurisdictions. REACH and the EU MDR impose escalating purity and traceability standards on active pharmaceutical ingredients, forcing contract manufacturers to upgrade analytical capabilities. Stakeholders must monitor how CDSCO's evolving oncology guidelines in India reshape clinical trial site selection and biosimilar entry strategy.
Market Dynamics
Checkpoint inhibitor dominance is restructuring esophageal cancer therapeutics as anti-PD-1 agents capture first-line positions previously held by platinum-doublet chemotherapy, forcing oncology networks to reconfigure infusion capacity and biomarker testing workflows.
Growth Catalysts
- FDA Project Orbis:Simultaneous multi-country review compresses launch timelines across the United States, Japan, and Australia, accelerating patient access to novel immunotherapies.
- Academic medical center expansion:Major oncology networks in the United States are scaling infusion chair capacity and hiring specialized nursing staff to handle rising immunotherapy volumes.
- Biomarker stratification platforms:PD-L1 combined positive score testing and HER2 amplification assays enable precision patient selection, improving response rates and justifying premium pricing.
Market Restraints
- Cold-chain distribution costs:Monoclonal antibodies require uninterrupted temperature control from manufacturing through infusion, elevating logistics spend and limiting rural site participation.
- API supply concentration:Active pharmaceutical ingredient production for checkpoint inhibitors clusters among a handful of contract manufacturers in India and China, creating vulnerability to export restrictions.
- Primary resistance mechanisms:Approximately half of esophageal adenocarcinoma patients fail to respond to anti-PD-1 monotherapy, capping addressable populations and requiring combination approaches.
Strategic Opportunities
- Subcutaneous formulation development:Self-administered injections for maintenance therapy could shift treatment from infusion centers to homecare settings, capturing convenience premiums.
- EU Green Deal procurement criteria:Sustainability-linked tender requirements create first-mover advantage for manufacturers with verified carbon-neutral biologics production.
- India CDSCO pathway evolution:Streamlined oncology approval guidelines and relaxed local clinical trial mandates open accelerated entry for biosimilar checkpoint inhibitors.
Industry Challenges
- Immuno-oncology nursing shortage:Specialized training for immune-related adverse event recognition and management lags behind infusion volume growth, constraining site expansion.
- Companion diagnostic co-development:Synchronized FDA approval for drug and test creates timeline risk when assay validation encounters analytical reproducibility issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Cancer Drugs Market |
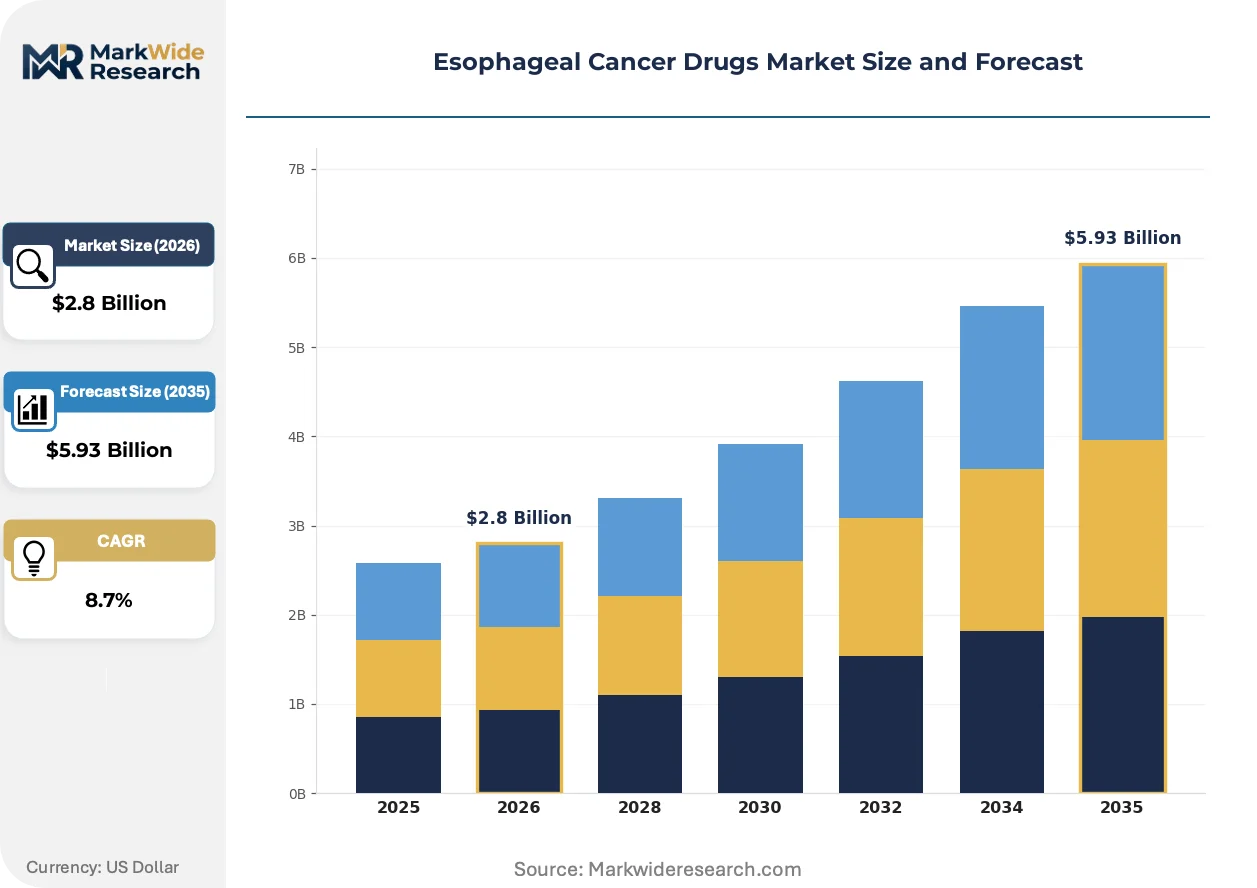
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy End User: Hospitals, Clinics, Homecare, Research Laboratories Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Therapy Area: Stage I, Stage II, Stage III, Palliative Care |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., Inc., Eli Lilly and Company, F. Hoffmann-La Roche Ltd, Amgen Inc., AstraZeneca, Novartis AG, Astellas Pharma Inc., Genentech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Cancer Drugs Market Emerging Trajectories
Biomarker-driven trial design is compressing development timelines while fragmenting addressable populations into molecularly defined subgroups, requiring manufacturers to maintain parallel pipeline investments across histologies and genomic alterations.
Subcutaneous checkpoint inhibitor delivery is rewriting treatment site economics by eliminating chair time and reducing nursing labor intensity. Community oncology practices in the United States are piloting take-home regimens for maintenance nivolumab, with early adoption concentrated in Medicare Advantage networks seeking total cost-of-care reduction. This shift threatens academic medical center infusion revenue while creating formulary leverage for payers demanding site-of-care neutral pricing.
REACH authorization requirements under the EU Green Deal are mandating mass balance accounting for pharmaceutical manufacturing waste streams. EMA's expanded environmental risk assessment guidelines now require biodegradation data prior to marketing authorization, forcing reformulation investments for cytotoxic agents. German oncology networks have begun incorporating carbon footprint metrics into tender evaluation criteria, disadvantaging suppliers without verified supply chain transparency.
Site-of-care migration from hospital outpatient departments to physician office infusion suites is accelerating among commercially insured populations in the United States. UnitedHealthcare and CVS Specialty have introduced home infusion options for stable maintenance immunotherapy, capturing patient preference for reduced travel burden. This channel shift concentrates volume with integrated delivery networks possessing ambulatory infrastructure, marginalizing standalone hospital-based practices.
Esophageal Cancer Drugs Market Segmentation
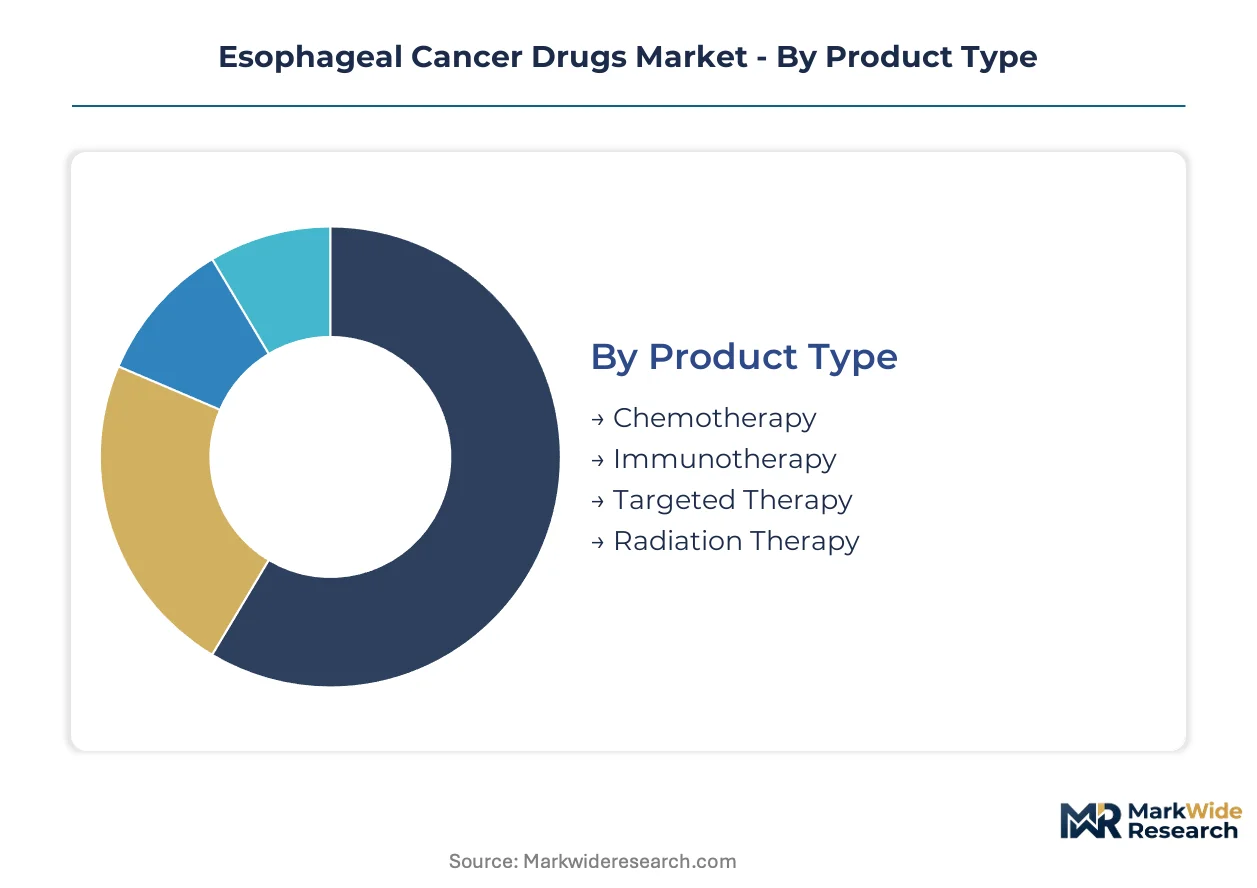
Esophageal cancer drug segmentation reveals how treatment protocols fragment across histology, staging, and care delivery settings. Manufacturers must align formulation development with specific biomarker profiles and site-of-care economics to capture addressable patient populations effectively.
Product Type:
Standardization dominates chemotherapy and radiation protocols, while immunotherapy and targeted agents require biomarker-driven customization for patient stratification.
- Immunotherapy:Anti-PD-1 and anti-PD-L1 monoclonal antibodies interrupt immune checkpoint signaling to restore T-cell-mediated tumor recognition. Demand concentrates in academic medical centers within the United States where PD-L1 combined positive score testing anchors first-line patient selection. The FDA's breakthrough therapy designation pathway accelerates approval timelines for novel checkpoint combinations.
- Targeted Therapy:HER2-directed agents and VEGF inhibitors address specific molecular alterations in adenocarcinoma subtypes. Oncology networks in Germany prioritize these agents for biomarker-positive populations under EMA's centralized marketing authorization framework.
- Chemotherapy:Platinum-doublet regimens retain utility in combination protocols and resource-constrained settings where immunotherapy access remains limited.
- Radiation Therapy:Concurrent chemoradiation serves as definitive treatment for locally advanced squamous cell carcinoma and neoadjuvant protocols.
Leading the category by volume: Chemotherapy. Growing fastest: Immunotherapy.
End User:
Site-of-care economics drive divergence between high-acuity hospital settings and emerging ambulatory channels seeking total cost reduction.
- Hospitals:Academic medical centers and comprehensive cancer centers manage complex Stage III cases, combination protocols, and immune-related adverse event monitoring. UnitedHealthcare's site-of-care policies increasingly steer stable patients toward lower-cost settings.
- Homecare:Subcutaneous immunotherapy formulations enable self-administered maintenance therapy, capturing Medicare Advantage network preference for reduced travel burden and chair-time elimination.
- Clinics:Community oncology practices handle routine infusion scheduling and monitoring for commercially insured populations.
- Research Laboratories:Biomarker testing facilities support clinical trial enrollment and companion diagnostic validation under FDA's co-development guidance.
Hospitals retain the dominant patient volume. Homecare is expanding most quickly as subcutaneous formulations penetrate maintenance therapy protocols.
Administration Route:
Route selection balances bioavailability requirements against patient convenience and site-of-care cost structures.
- Intravenous:Monoclonal antibody delivery requires controlled infusion environments with nursing supervision for hypersensitivity monitoring. Cold-chain logistics from manufacturing through administration elevate distribution complexity.
- Subcutaneous:Self-injection devices for checkpoint inhibitors reduce chair time and enable home-based maintenance, appealing to CVS Specialty and integrated delivery networks pursuing total cost-of-care reduction.
- Oral:Small molecule tyrosine kinase inhibitors offer patient convenience but require adherence monitoring and drug interaction management.
- Intramuscular:Limited application for supportive care agents and depot formulations in palliative settings.
Intravenous administration leads by procedure volume. Subcutaneous delivery is gaining share fastest as manufacturers reformulate established antibodies.
Therapy Area:
Staging segmentation aligns treatment intensity with curative intent versus palliation, with significant protocol variation between squamous cell carcinoma and adenocarcinoma histologies.
- Stage III:Multimodality protocols combining neoadjuvant chemoradiation with surgical resection dominate esophageal adenocarcinoma management. The University of Texas MD Anderson Cancer Center anchors clinical trial innovation for perioperative immunotherapy integration.
- Palliative Care:Symptom-focused regimens prioritize quality of life and dysphagia relief over survival extension, with checkpoint inhibitors displacing cytotoxic monotherapy in select populations.
- Stage II:Neoadjuvant approaches precede definitive local therapy with biomarker-directed agent selection.
- Stage I:Endoscopic resection and localized therapy minimize systemic exposure for early-detected lesions.
Stage III commands the largest addressable patient population. Palliative Care represents the steepest expansion trajectory as immunotherapy extends survival in refractory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients clusters in India and China, while clinical consumption and pricing power concentrate in the United States and Western Europe. This divergence shapes regulatory strategy, supply chain risk management, and market access negotiations across the value chain.
United States
Academic medical centers in Boston and Houston anchor Phase III trial enrollment for novel checkpoint inhibitors. FDA's Project Orbis enables simultaneous review with Japan and Australia, compressing launch timelines. The MD Anderson Cancer Center in Texas drives perioperative immunotherapy protocol innovation.
Germany
Oncology networks in Bavaria and North Rhine-Westphalia incorporate EU Green Deal carbon footprint metrics into tender evaluations. EMA's centralized marketing authorization framework streamlines biomarker-driven agent adoption. The Heidelberg University Hospital cluster advances precision stratification platforms.
India
Contract manufacturers in Hyderabad and Ahmedabad supply monoclonal antibody APIs to global innovators. CDSCO's evolving oncology guidelines streamline biosimilar checkpoint inhibitor pathways. The Genome Valley biotech corridor attracts multinational clinical trial site investment.
Japan
PMDA's participation in FDA Project Orbis accelerates patient access to breakthrough immunotherapies. METI's pharmaceutical competitiveness initiative subsidizes domestic biologics manufacturing capability. The Kanto region's university hospitals concentrate biomarker testing infrastructure.
United Kingdom
NHS England's Cancer Drugs Fund enables rapid access to novel agents pending NICE appraisal. MHRA's post-Brexit regulatory autonomy permits accelerated approval pathways for priority medicines. The Cambridge-London biotech corridor hosts immuno-oncology translational research.
Esophageal Cancer Drugs Market Vendor Landscape
The competitive structure tilts toward integrated biopharmaceutical conglomerates with manufacturing scale and biomarker platform depth. Patent-protected checkpoint inhibitors command premium pricing in first-line settings, while biosimilar entrants threaten margin compression in maintenance therapy. Three archetypes dominate: vertically integrated innovators with global manufacturing networks, precision medicine specialists with companion diagnostic capabilities, and emerging biosimilar manufacturers targeting emerging market access. Capacity expansion in subcutaneous formulation capacity and strategic partnerships for biomarker co-development represent the dominant competitive moves.
Within the integrated innovator tier, Bristol-Myers Squibb Company and Merck & Co., Inc. exemplify scale-driven checkpoint inhibitor leadership, while Eli Lilly and Company occupies a position emphasizing biomarker-driven combination strategies. These entities represent the archetype of manufacturers leveraging global biologics networks and deep investment in patient stratification infrastructure to sustain competitive position.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| AstraZeneca |
| Novartis AG |
| Astellas Pharma Inc. |
| Genentech, Inc. |
| Others |
Supply Flow & Price Mechanics
Oncology hospital networks in the United States and Germany anchor procurement volumes for checkpoint inhibitors, locking in value-based pricing calibrated to progression-free survival endpoints. This buyer concentration enables manufacturers to defend premium positioning through companion diagnostic bundling and biomarker stratification, while cold-chain logistics costs limit price competition in rural site access.
Pricing Analysis
Cost compression in platinum-doublet chemotherapy reflects biosimilar entry and displacement by anti-PD-1 agents in first-line protocols. Three-tier pricing structure across branded immunotherapy, biosimilar checkpoint inhibitors, and generic cytotoxic agents stratifies by FDA breakthrough designation status and PD-L1 testing integration. Pricing pressure stems from Medicare Advantage site-of-care policies steering stable patients toward lower-cost infusion settings. Community oncology practices exhibit highest price sensitivity; academic medical centers with research funding tolerate premium positioning for novel combinations.
Supply Chain Analysis
Return flows for temperature-deviated monoclonal antibody shipments and expired inventory create reverse-logistics complexity requiring specialized pharmaceutical waste handlers. Active pharmaceutical ingredient production clusters in India and China, with fill-finish operations concentrated in the United States and Germany. Supply chains draw from recombinant protein expression systems, single-use bioreactor components, and cold-chain packaging materials. Single-source vulnerability concentrates among contract manufacturers in Hyderabad and Ahmedabad for checkpoint inhibitor APIs. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with validated cold-chain integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity for monoclonal antibodies remains concentrated among a handful of contract manufacturers, constraining supply elasticity and propping pricing for innovators with secured manufacturing slots.
For Market Incumbents: Hedge against biosimilar margin compression by deepening captive supply control over fill-finish capacity in Germany and the United States, while accelerating subcutaneous formulation development to capture site-of-care migration toward homecare settings threatened by CVS Specialty and UnitedHealthcare channel shifts. For New Entrants and Emerging Players: Launch via CDSCO's streamlined oncology pathway in India, targeting biosimilar checkpoint inhibitor entry where local clinical trial mandates have relaxed and procurement by government hospital networks favors cost-effective alternatives to branded anti-PD-1 agents. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision medicine specialists with validated companion diagnostic platforms in the Cambridge-London biotech corridor, where MHRA post-Brexit autonomy enables accelerated approval pathways. Monitor EMA environmental risk assessment guideline enforcement as inflection indicator for reformulation investment requirements that favor acquirers with green manufacturing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables homecare maintenance therapy capture away from academic infusion centers. |
| Companion Diagnostic Co-Development | Synchronizes FDA approval timelines for PD-L1 testing with checkpoint inhibitor launch. |
| EU Green Deal Manufacturing Certification | Secures tender preference in German oncology networks with carbon-neutral biologics production. |
| CDSCO Biosimilar Pathway Navigation | Accelerates market entry in India where government procurement favors cost-effective alternatives. |
| Biomarker Stratification Platform Investment | Improves response rates and justifies premium pricing in HER2-negative adenocarcinoma populations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases supplied quantitative foundations. Bottom-up patient flow modeling and top-down pharmaceutical spending analysis provided triangulation checks across estimation approaches.
Granularity extended to treatment line, administration route, histology subtype, and regional regulatory cluster across the projection horizon. CAGRs derived from patient incidence projections, therapy penetration curves, and pricing elasticity assumptions tied to biosimilar entry timing. Modeled inputs included PD-L1 testing adoption rates, site-of-care migration patterns, and cold-chain logistics cost inflation.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous immunotherapy delivery would alter the outlook if nursing labor shortages accelerate homecare preference faster than anticipated. Practitioners should monitor CDSCO guideline evolution, EU Green Deal tender enforcement, and FDA Project Orbis expansion for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Bone Metastasis Market
Oncology
Metastatic Breast Cancer Market
Oncology
Radiation Therapy Software Market
Oncology
Internal Radiation Therapy Market
Oncology
Breast Cancer Therapy Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Stomach Cancer Treatment Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
US Radiation Oncology Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Sterile Oncology Injectable Market
Oncology
Angiosarcomas Treatment Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Thymus Cancer Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Oncology Market