
 Esophageal Cancer Market | 2026-2036
Esophageal Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Cancer Market Intelligence
ISO 14155 clinical trial certification is unwinding competitive access for esophageal cancer drug developers, raising the bar for investigational site qualification and data integrity. Bristol-Myers Squibb leverages its checkpoint inhibitor portfolio to sustain leadership in first-line settings. Merck & Co. anchors its position through broad PD-1 label expansion across gastrointestinal malignancies. AstraZeneca competes aggressively with antibody-drug conjugate programs targeting HER2-expressing tumors.
Esophageal cancer encompasses malignant neoplasms arising from the squamous epithelium or glandular mucosa of the esophagus, characterized by histological subtypes including esophageal squamous cell carcinoma and adenocarcinoma, with staging determined by TNM classification assessing tumor invasion depth, nodal involvement, and metastatic spread. Immunotherapy now commands the fastest expansion within product type segments as PD-1 and CTLA-4 inhibitors displace chemotherapy in frontline protocols. Metastatic treatment stage segments concentrate the largest revenue pool due to chronic dosing requirements and limited curative intent, while early stage segments remain underpenetrated despite surgical adjuvant opportunities.
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines and reshape payer negotiation leverage for novel esophageal cancer entrants. NMPA priority review channels in China accelerate domestic biosimilar and innovative molecule access, altering geographic launch sequencing for multinational sponsors. Stakeholders must monitor evolving biomarker-driven trial eligibility criteria and real-world evidence mandates that will determine reimbursement sustainability beyond initial regulatory approval.
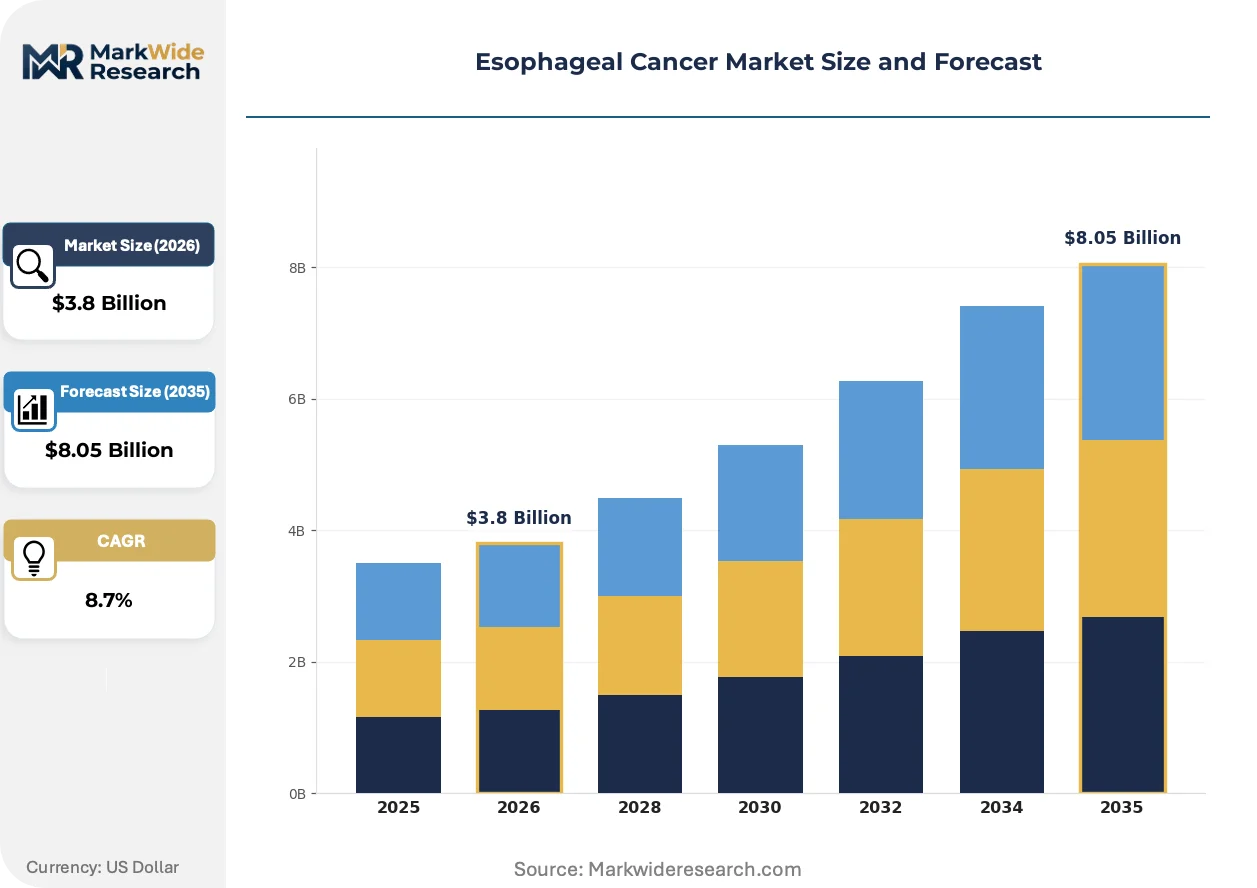
Market Dynamics
Checkpoint inhibitor displacement of chemotherapy in first-line esophageal cancer protocols is restructuring treatment hierarchies and redistributing revenue across immuno-oncology portfolios, with biomarker-driven patient selection becoming the decisive competitive filter.
Growth Catalysts
- FDA Breakthrough Therapy Designation:This pathway compresses development timelines for novel immuno-oncology agents, enabling earlier commercial access and accelerating site activation for pivotal trials in the United States.
- Biomarker-Driven Trial Eligibility:PD-L1 expression and HER2 amplification testing is expanding addressable populations for targeted therapies, pulling more patients into precision medicine protocols across oncology clinics.
- China NMPA Priority Review:Domestic sponsors and multinational partners leverage accelerated approval channels to shorten time-to-market for biosimilars and innovative molecules in the world's second-largest oncology market.
Market Restraints
- ISO 14155 Certification Burden:Enhanced clinical trial site qualification requirements are disqualifying smaller investigative sites, concentrating patient access in major academic medical centers and extending enrollment timelines.
- Platinum-Based Chemotherapy Input Cost Volatility:Supply constraints for cisplatin and oxaliplatin active pharmaceutical ingredients create dosing interruptions and protocol modifications that destabilize combination regimen delivery.
- Reimbursement Compression in European Markets:EMA conditional marketing authorization frameworks trigger aggressive health technology assessment negotiations that delay market access and constrain pricing power for novel entrants.
Strategic Opportunities
- Perioperative Immunotherapy Expansion:Underpenetrated adjuvant and neoadjuvant settings in early-stage esophageal cancer offer chronic dosing potential beyond metastatic maintenance, with surgical oncology networks in Germany and Japan piloting protocol integration.
- Antibody-Drug Conjugate Convergence:HER2-directed ADCs combined with checkpoint inhibitors are opening new combination development paths, with trastuzumab deruxtecan establishing proof-of-concept for tissue-agnostic approaches.
- Real-World Evidence Mandates:Post-approval evidence generation requirements from FDA and EMA create competitive differentiation for sponsors with robust patient registry infrastructure and digital health partnerships.
Industry Challenges
- Immuno-Oncology Site Activation Capacity:Qualified principal investigators with PD-1/CTLA-4 trial experience are concentrated in major metropolitan clusters, creating enrollment bottlenecks and site competition that delays study startup.
- Companion Diagnostic Co-Development Complexity:Synchronized validation of PD-L1 assays and HER2 testing platforms with therapeutic candidates extends regulatory timelines and increases program risk for synchronized approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Cancer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Treatment Stage: Early Stage, Locally Advanced, Metastatic, Recurrent Administration Route: Oral, Intravenous, Subcutaneous, Intra-arterial End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Homecare Settings |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., Inc., F. Hoffmann-La Roche Ltd, AstraZeneca plc, Novartis AG, Eli Lilly and Company, Amgen Inc., Pfizer Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Cancer Market Strategic Shifts & Innovations
Computational pathology and circulating tumor DNA monitoring are displacing traditional staging methodologies, while decentralized trial execution models are redrawing site selection criteria and patient access patterns across the esophageal cancer development landscape.
Artificial intelligence-powered histopathology analysis is fragmenting diagnostic workflows by enabling automated tumor-infiltrating lymphocyte quantification and PD-L1 scoring at scale. Community pathology laboratories in the United States and regional reference centers in France are adopting these platforms to reduce inter-observer variability and accelerate biomarker turnaround. This fragmentation is compressing the competitive advantage of centralized academic pathology services and redistributing diagnostic value toward algorithm developers and platform-integrated contract research organizations.
EMA's Clinical Trial Regulation and the associated Clinical Trials Information System are harmonizing protocol submission and safety reporting requirements across European member states, eliminating redundant national competent authority reviews that previously delayed multi-country study activation. Sponsors are consolidating European development strategies around fewer, larger countries with established investigator networks, with Spain and Italy gaining relative trial share as streamlined processes reduce operational friction. The regulation is compressing the historical gap between US and EU first-patient-in timelines for esophageal cancer studies.
Site selection criteria are tightening around digital enrollment capabilities and diverse patient access, with sponsors prioritizing investigative sites equipped with telemedicine infrastructure and community outreach programs. Traditional academic medical centers with limited geographic catchment are losing share to hybrid community-academic networks that combine clinical trial access with local care delivery, particularly visible in Texas and Florida where large integrated delivery systems are consolidating oncology trial portfolios. This behavioral shift is forcing contract research organizations to reconfigure site identification algorithms and investigator payment models.
Esophageal Cancer Market Segmentation
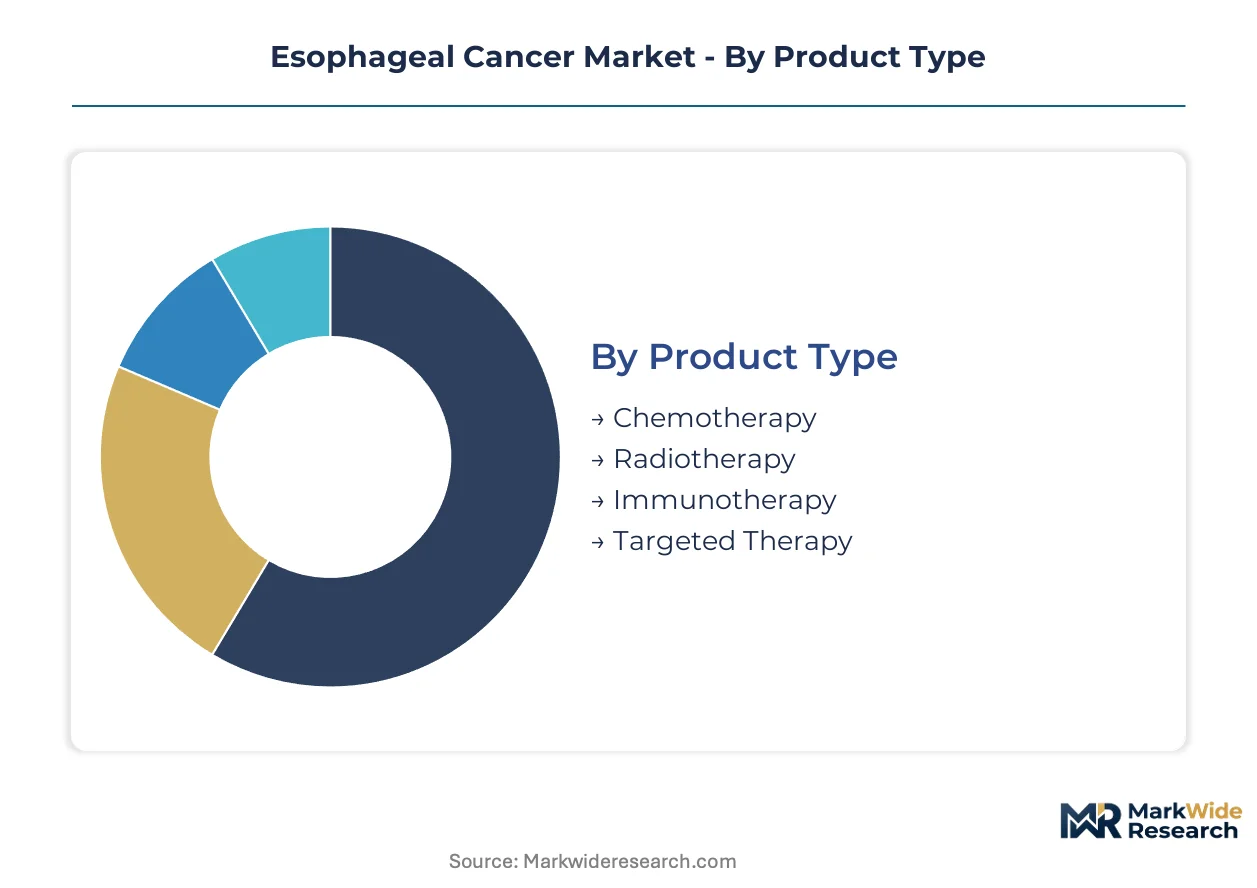
Esophageal cancer treatment modalities fragment across therapeutic mechanisms and care delivery settings, with each segment demanding distinct regulatory pathways and reimbursement architectures. Channel economics vary sharply between hospital-administered infusions and clinic-based oral regimens, reshaping how manufacturers configure their commercial infrastructure.
Product Type:
Channel-mix dynamics concentrate high-value immuno-oncology agents in hospital outpatient departments where buy-and-bill reimbursement sustains margin, while oral targeted therapies flow through specialty pharmacy networks with distinct prior authorization requirements.
- Immunotherapy:PD-1 and CTLA-4 inhibitors dominate first-line protocols for advanced disease, with pembrolizumab and nivolumab anchoring combination regimens in US oncology clinics and German university hospitals. Checkpoint inhibitor displacement of chemotherapy is redistributing revenue toward chronic maintenance dosing models.
- Targeted Therapy:HER2-directed agents and anti-VEGF molecules address biomarker-selected populations, with trastuzumab deruxtecan gaining traction in HER2-expressing adenocarcinoma through accelerated FDA and EMA pathways. Companion diagnostic co-development complexity constrains launch sequencing.
- Chemotherapy:Platinum-fluoropyrimidine backbones persist in perioperative and combination settings despite input cost volatility for cisplatin and oxaliplatin APIs.
- Radiotherapy:External beam and brachytherapy modalities concentrate in academic medical centers with integrated multidisciplinary tumor boards.
By volume, chemotherapy leads. By growth pace, immunotherapy is expanding most quickly.
Treatment Stage:
Cost tier stratification separates curative-intent surgical adjuvant protocols from chronic metastatic maintenance, with pricing power concentrating in settings where progression-free survival endpoints justify premium positioning.
- Metastatic:Chronic dosing requirements for immunotherapy and targeted agents generate the largest revenue pool, with US and China concentrating patient volume. Limited curative intent extends treatment duration and supports premium pricing for survival benefits.
- Locally Advanced:Definitive chemoradiation protocols dominate, with Germany and Japan piloting perioperative immunotherapy integration to improve pathological complete response rates.
- Early Stage:Surgical adjuvant opportunities remain underpenetrated despite checkpoint inhibitor trials in resected disease, constrained by smaller addressable populations and shorter treatment windows.
- Recurrent:Salvage regimens repurpose earlier-line agents with biomarker-driven selection, often in community oncology settings with compressed reimbursement timelines.
Metastatic settings capture the deepest revenue per patient. Early-stage adjuvant applications are climbing the fastest as perioperative immunotherapy evidence matures.
Administration Route:
Customer-type segmentation separates institutional infusion capacity from patient-administered oral regimens, with site-of-care economics driving manufacturer preference for hospital outpatient over clinic or home settings.
- Intravenous:Checkpoint inhibitors and cytotoxic combinations require infusion infrastructure concentrated in hospital outpatient departments and major oncology clinics, with US buy-and-bill reimbursement sustaining higher realized prices.
- Oral:Targeted small molecules enable community and home administration, though specialty pharmacy networks impose prior authorization burdens that delay therapy initiation.
- Subcutaneous:Emerging formulations seek to shift site of care toward ambulatory settings, with PD-1 subcutaneous developments targeting reduced infusion chair time.
- Intra-arterial:Regional chemotherapy delivery remains niche, concentrated in select interventional radiology programs for localized disease control.
Intravenous delivery dominates current revenue. Subcutaneous formulations are gaining share fastest through convenience-driven differentiation.
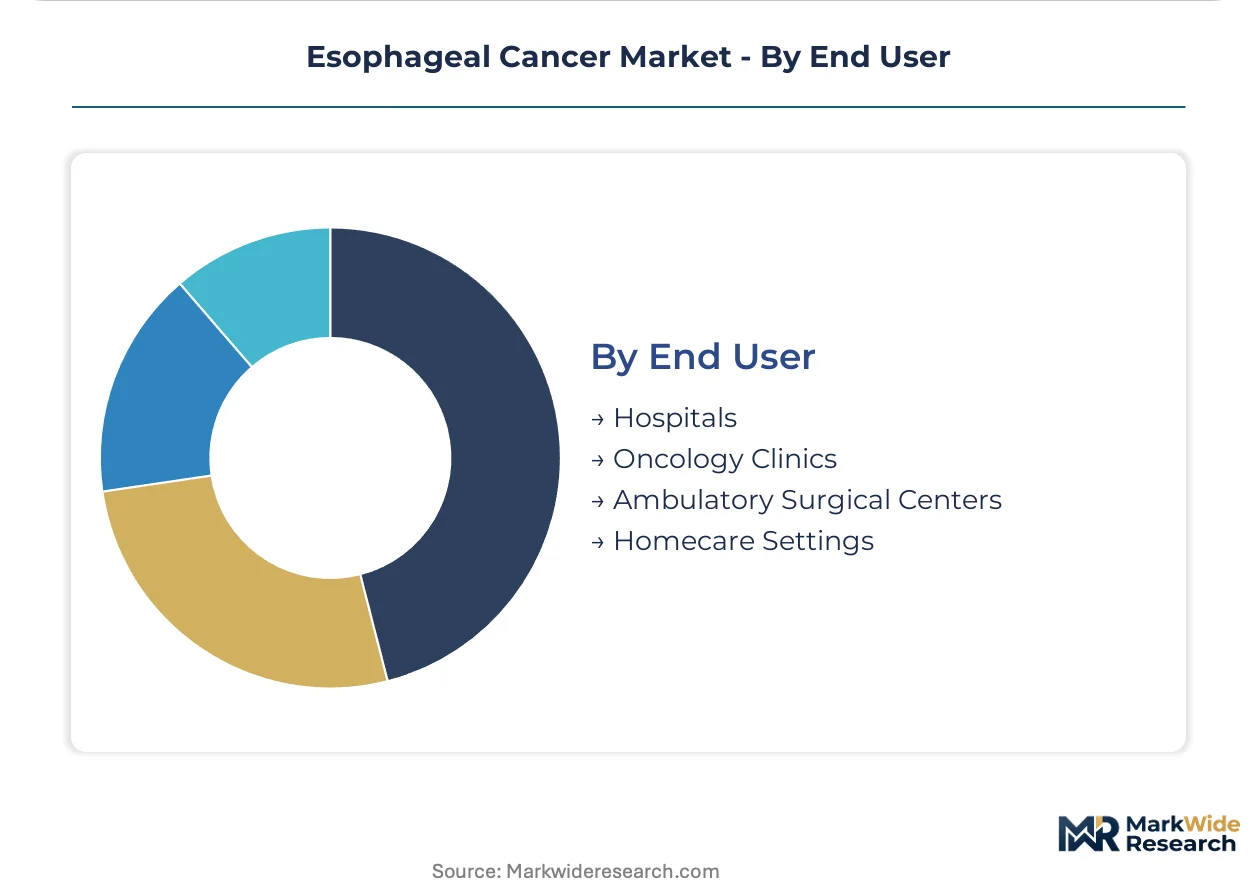
End User:
Geographic concentration of trial density and reimbursement access shapes end-user segmentation, with major metropolitan clusters capturing disproportionate novel therapy adoption.
- Hospitals:Academic medical centers in the United States, Germany, and China anchor pivotal trial enrollment and first-line immunotherapy adoption, with integrated pathology and biomarker testing capabilities enabling precision patient selection.
- Oncology Clinics:Community-based networks in Texas and Florida consolidate trial access through hybrid community-academic models, expanding patient reach beyond traditional academic catchments.
- Ambulatory Surgical Centers:Perioperative chemotherapy administration concentrates here for early-stage resectable disease, though immunotherapy infusion capacity remains limited.
- Homecare Settings:Oral targeted therapy administration expands here, supported by remote patient monitoring and telemedicine infrastructure adopted during decentralized trial execution models.
Hospitals lead by patient volume. Oncology clinics are expanding most quickly as site selection criteria tighten around diverse access and digital enrollment capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines and reshape payer negotiation leverage for novel esophageal cancer entrants. NMPA priority review channels in China accelerate domestic biosimilar and innovative molecule access, altering geographic launch sequencing for multinational sponsors.
United States
Oncology clinics in Texas and Florida consolidate trial access through hybrid community-academic models that expand patient reach beyond traditional academic catchments. FDA accelerated approval pathways enable earlier commercial access for checkpoint inhibitors in first-line settings. Major metropolitan clusters in Houston and Miami anchor pivotal trial enrollment for perioperative immunotherapy protocols.
China
Domestic sponsors and multinational partners leverage NMPA priority review to shorten time-to-market for biosimilars and innovative molecules. Shanghai and Beijing concentrate clinical trial density with integrated biomarker testing capabilities enabling precision patient selection. Yangtze River Delta medical centers pilot decentralized trial execution models that redraw site selection criteria.
Germany
EMA conditional marketing authorization triggers aggressive health technology assessment negotiations that delay market access for novel entrants. Bavaria and North Rhine-Westphalia anchor surgical oncology networks piloting perioperative immunotherapy integration to improve pathological complete response rates. German university hospitals lead European adoption of antibody-drug conjugate programs.
Japan
PMDA sakigake designation accelerates regulatory review for innovative oncology agents targeting unmet medical needs. Tokyo and Osaka metropolitan areas concentrate qualified principal investigators with PD-1/CTLA-4 trial experience. Kansai region medical centers adopt computational pathology platforms for automated tumor-infiltrating lymphocyte quantification.
United Kingdom
NICE technology appraisals constrain pricing power for novel esophageal cancer therapies through outcome-based reimbursement frameworks. London and Southeast England anchor early-phase trial enrollment with established investigator networks. Midlands region oncology clinics expand adoption of telemedicine infrastructure for decentralized patient monitoring.
Esophageal Cancer Market Key Industry Players
Listed leaders compete with private specialists across checkpoint inhibitor and targeted therapy development. The vendor base concentrates around immuno-oncology portfolios with established PD-1 label expansion strategies. Three archetypes dominate: multinational pharmaceutical conglomerates with broad oncology franchises, mid-cap biotechnology firms with antibody-drug conjugate specialization, and emerging biosimilar manufacturers leveraging NMPA priority review. Competitive moves center on companion diagnostic co-development partnerships and perioperative protocol expansion into surgical adjuvant settings.
Within the multinational conglomerate tier, Bristol-Myers Squibb Company and Merck & Co., Inc. occupy positions anchored by first-line checkpoint inhibitor leadership, while AstraZeneca plc exemplifies the antibody-drug conjugate convergence strategy through HER2-directed development programs. These three entities represent distinct competitive vectors: immunotherapy platform scale, gastrointestinal malignancy label breadth, and precision oncology tissue-agnostic approaches.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| Novartis AG |
| Eli Lilly and Company |
| Amgen Inc. |
| Pfizer Inc. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
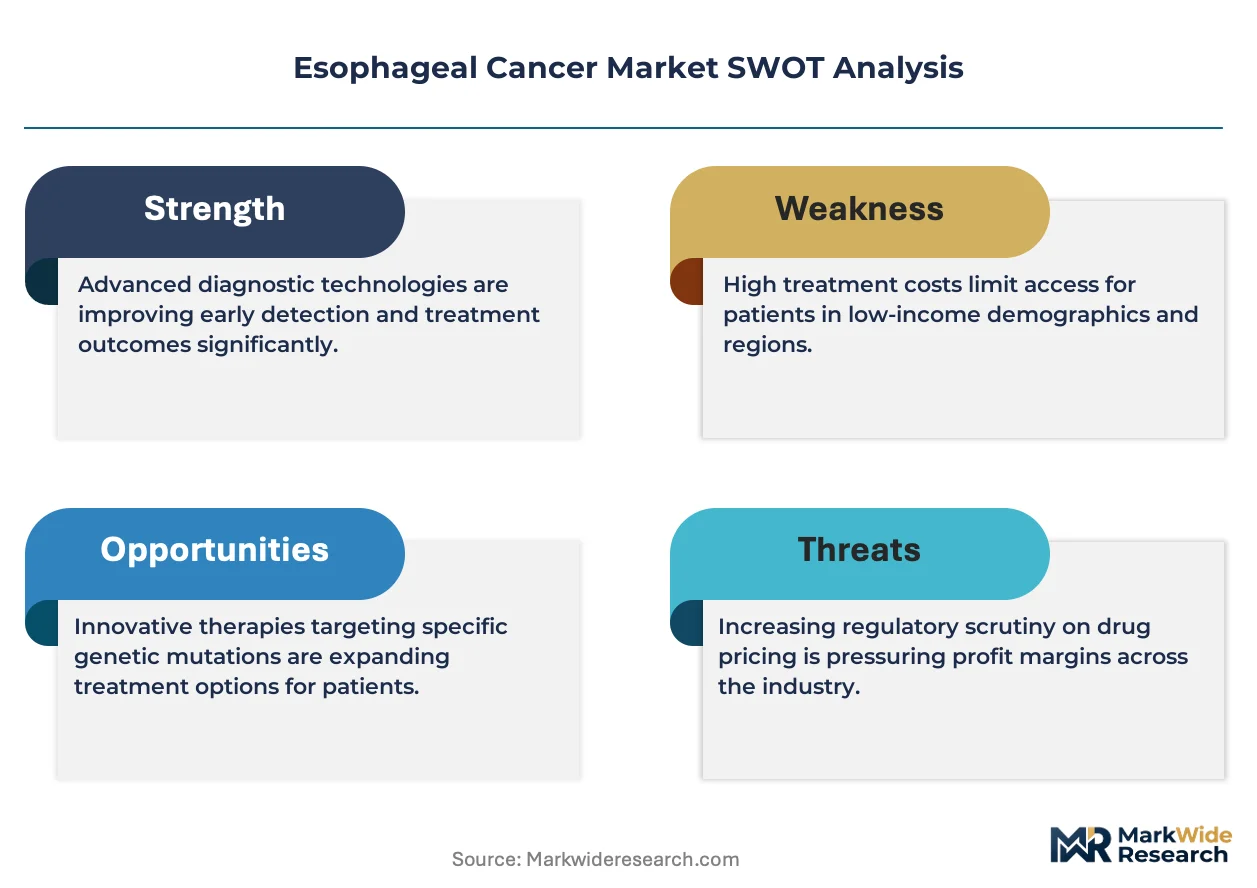
ISO 14155 certification requirements gate both investigative site qualification and price differentiation in esophageal cancer drug development, concentrating supply access in major academic medical centers while compressing margins for sponsors unable to absorb enhanced compliance costs. This regulatory threshold simultaneously restricts qualified manufacturing partners and segments pricing power across certification tiers.
Pricing Analysis
Certification level creates the primary spread between premium and standard positioning in esophageal cancer therapeutics. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough therapy designation status, companion diagnostic bundling, and perioperative label breadth. Pricing pressure stems from NMPA biosimilar acceleration in China and EMA conditional marketing authorization negotiations in Europe. Community oncology clinics exhibit highest price sensitivity due to buy-and-bill reimbursement compression, while German university hospitals sustain premium tolerance for pathological complete response data.
Supply Chain Analysis
Platinum-based API manufacturing concentrates in India and China, creating single-source vulnerability for cisplatin and oxaliplatin active pharmaceutical ingredients. Checkpoint inhibitor biologics production draws from contract manufacturing organizations in South Korea, Singapore, and Switzerland with established PD-1/CTLA-4 platform expertise. Supply chain risk centers on geopolitical trade restrictions affecting pharmaceutical precursor chemicals. Distribution runs through hospital outpatient departments in the United States and specialty pharmacy networks for oral targeted therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Esophageal cancer therapeutics enters a cyclical recovery phase as perioperative immunotherapy evidence matures and surgical adjuvant protocols expand addressable treatment windows beyond metastatic maintenance.
For Market Incumbents: Compound checkpoint inhibitor leadership through perioperative protocol expansion into resected disease settings. Deepen backward integration into companion diagnostic manufacturing to synchronize PD-L1 assay validation with therapeutic launches. Acquire computational pathology platforms to capture automated biomarker scoring revenue streams before algorithm developers consolidate market position. For New Entrants and Emerging Players: Telemedicine-enabled trial enrollment infrastructure represents the most penetrable service-layer gap where incumbents under-serve rural and community oncology networks. Target hybrid community-academic models in Texas and Florida with decentralized patient monitoring capabilities. Pursue NMPA priority review partnerships with domestic Chinese sponsors to accelerate biosimilar market entry ahead of multinational label expansion. For Investors and Strategic Acquirers: FDA breakthrough therapy designation density reshapes the acquisition landscape toward clinical-stage assets with accelerated approval pathways already secured. Five-to-ten year viability favors antibody-drug conjugate specialists with HER2-directed tissue-agnostic platforms over chemotherapy backbone manufacturers facing input cost volatility. Monitor EMA conditional marketing authorization negotiation outcomes as the critical signal for European pricing power sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Perioperative Immunotherapy Expansion | Captures surgical adjuvant revenue pools in Germany and Japan before competitors establish protocol dominance. |
| Companion Diagnostic Co-Development | Synchronizes PD-L1 assay validation with therapeutic candidates to compress regulatory timelines. |
| Decentralized Trial Execution | Enrolls diverse patient populations through telemedicine infrastructure in Texas and Florida hybrid networks. |
| Antibody-Drug Conjugate Convergence | Combines HER2-directed agents with checkpoint inhibitors for tissue-agnostic positioning. |
| Real-World Evidence Infrastructure | Builds patient registry partnerships to satisfy FDA and EMA post-approval evidence mandates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists inform competitive positioning assessments. Bottom-up patient population modeling triangulates against top-down revenue estimates across therapeutic mechanism and treatment stage segments.
Segmentation dimensions modeled include treatment line, administration route, biomarker selection criteria, and regional regulatory cluster across the analysis window. CAGRs derive from patient volume projections, dosing duration assumptions, and price evolution by certification tier. Forecast inputs incorporate clinical trial enrollment velocity, pathological complete response rates from perioperative studies, and companion diagnostic penetration curves.
Forecasts assume regulatory continuity in FDA breakthrough therapy and EMA conditional marketing authorization frameworks; material policy shifts would require re-modeling. Specific risks include ISO 14155 certification expansion disqualifying additional investigative sites, platinum API supply disruptions, and NICE technology appraisal outcomes constraining UK access. Practitioners should keep alternative scenarios live as perioperative immunotherapy evidence matures and China NMPA biosimilar acceleration timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Tumor Lysis Syndrome Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Immuno-Oncology Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Cancer API Market
Oncology
Metastatic Cancer Drug Market
Oncology
Europe Proton Therapy Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Pituitary Cancer Market
Oncology
Thyroid Cancer Market
Oncology
Particle Therapy Systems Market
Oncology
North America Bone Metastasis Market