
 North America Internet of Medical Things (Iomt) Market | 2026-2036
North America Internet of Medical Things (Iomt) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Internet of Medical Things (Iomt) Market Analytics
Remote patient monitoring revenue is rewriting profit allocation across the North America IoMT ecosystem. Medtronic plc leverages its deep cardiac device portfolio to anchor recurring subscription streams from implanted monitors. GE Healthcare competes through edge-computing infrastructure that sustains real-time telemetry in acute care settings.
The Internet of Medical Things denotes networked medical devices, sensors, and software platforms that collect, transmit, and analyze physiological data through embedded wireless modules operating at 2.4 GHz Bluetooth Low Energy or sub-6 GHz cellular bands, primarily to enable proactive clinical intervention outside traditional facility boundaries. Wearable devices and remote monitoring tools command the dominant installed base, though smart implants capture the highest per-unit margin pools due to surgical placement requirements and long-term data contracts. Bluetooth and Wi-Fi technologies lead connectivity shipments, while cellular-enabled devices represent the fastest-growing technology tier as 5G latency improvements support critical care applications.
FDA premarket review pathways and HIPAA security rule enforcement shape device design priorities and data governance architectures across the United States, while Health Canada and the Office of the National Coordinator for Health IT impose parallel interoperability and privacy constraints that vendors must satisfy for cross-border deployment. Stakeholders must monitor evolving FDA software-as-a-medical-device guidance and state-level biometric privacy statutes to determine compliance investment timing and partnership structures.
Market Dynamics
FDA software-as-a-medical-device guidance and HIPAA interoperability enforcement are compressing product development timelines while fragmenting vendor compliance costs across the North America IoMT landscape.
Growth Catalysts
- Bluetooth Low Energy penetration:Connected inhaler networks for asthma and COPD populations are expanding device-addressable markets through prescription-integrated digital therapeutics.
- 5G latency improvements:Cellular-enabled critical care telemetry is unlocking acute-care applications previously confined to wired infrastructure.
- California digital health corridor:Concentrated venture deployment and health system pilot partnerships are accelerating commercialization velocity for remote monitoring platforms.
Market Restraints
- Semiconductor supply concentration:Sub-6 GHz cellular module availability remains constrained by foundry capacity allocation to consumer electronics.
- HIPAA security rule friction:State-level biometric privacy statutes in Illinois, Texas, and Washington impose conflicting consent architectures that complicate cross-border data routing.
- Lithium-ion battery volatility:Implantable device power source costs fluctuate with raw material spot markets, compressing margin pools on long-term data contracts.
Strategic Opportunities
- Massachusetts medical device cluster:Surgical placement capabilities and FDA premarket review expertise concentrate talent for smart implant development.
- Edge-AI convergence:On-device inference engines combined with real-time telemetry are enabling predictive intervention without cloud dependency.
- Accountable care organization procurement:Risk-bearing health systems are unbundling device acquisition from longitudinal data subscriptions.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for 2.4 GHz wireless modules competes with consumer IoT for constrained talent pools.
- 510(k) clearance timeline variability:FDA premarket notification review periods for algorithm-enabled devices lack predictability, distorting capital deployment schedules.
- Legacy EHR integration complexity:Health system data architectures built on HL7 v2 messaging require expensive middleware development for IoMT connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Internet of Medical Things (Iomt) Market |
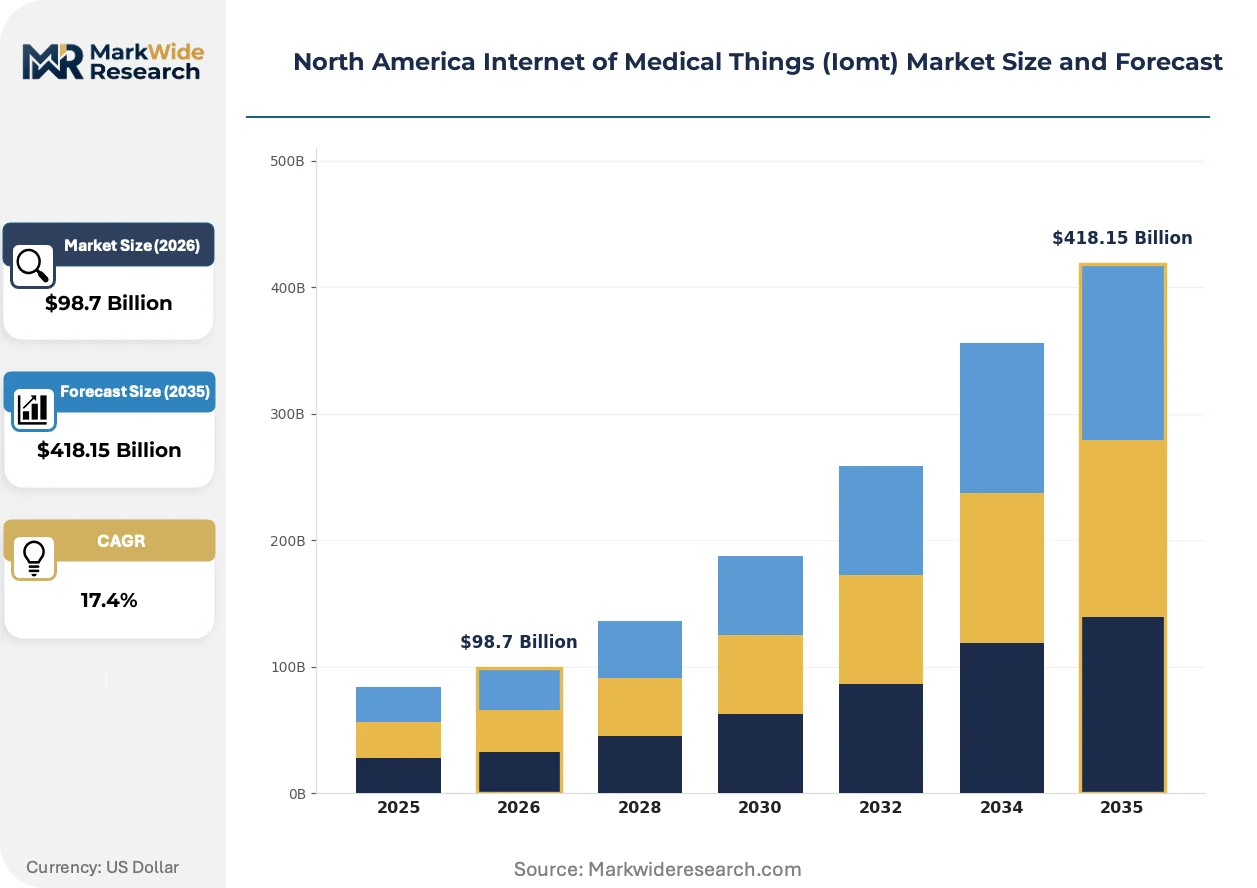
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $418.15 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Tools, Smart Implants, Connected Inhalers Technology: Bluetooth, Wi-Fi, Cellular, RFID Application: Smart Hospitals, Home Care, Chronic Disease Management, Emergency Care End User: Healthcare Providers, Patients, Research Institutions, Insurance Companies |
| Companies Covered | Medtronic plc, GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Boston Scientific Corporation, Johnson & Johnson, Abbott Laboratories, Cisco Systems Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Internet of Medical Things (Iomt) Market Evolving Landscape
Real-time physiological analytics are migrating from cloud infrastructure to device-edge compute, altering where value capture concentrates in the IoMT stack.
Edge-computing inference engines operating on sub-1 GHz ARM Cortex-M processors are enabling predictive cardiac event detection within implanted monitors. Cardiology service lines at integrated delivery networks are piloting these platforms to reduce false-positive alert burden. Periodic cloud synchronization is rendering obsolete the continuous connectivity models that dominated first-generation remote patient monitoring architectures.
FDA software-as-a-medical-device guidance issued in 2022 imposes predetermined change control plans on machine-learning-enabled diagnostics. Manufacturers must lock algorithm training protocols prior to 510(k) submission, constraining post-market model refinement. Continuous glucose monitor developers are responding by segmenting product lines into locked-algorithm and prescription-controlled-update tiers.
Hospital procurement committees are unbundling device capital expenditure from multi-year data subscription commitments. Health systems in Texas and Florida are piloting per-patient-per-month pricing for remote monitoring platforms. This consumption-pattern shift is most visible in cardiology and pulmonology service lines where episode-based reimbursement creates incentive alignment for outcome-linked device deployment.
North America Internet of Medical Things (Iomt) Market Segmentation
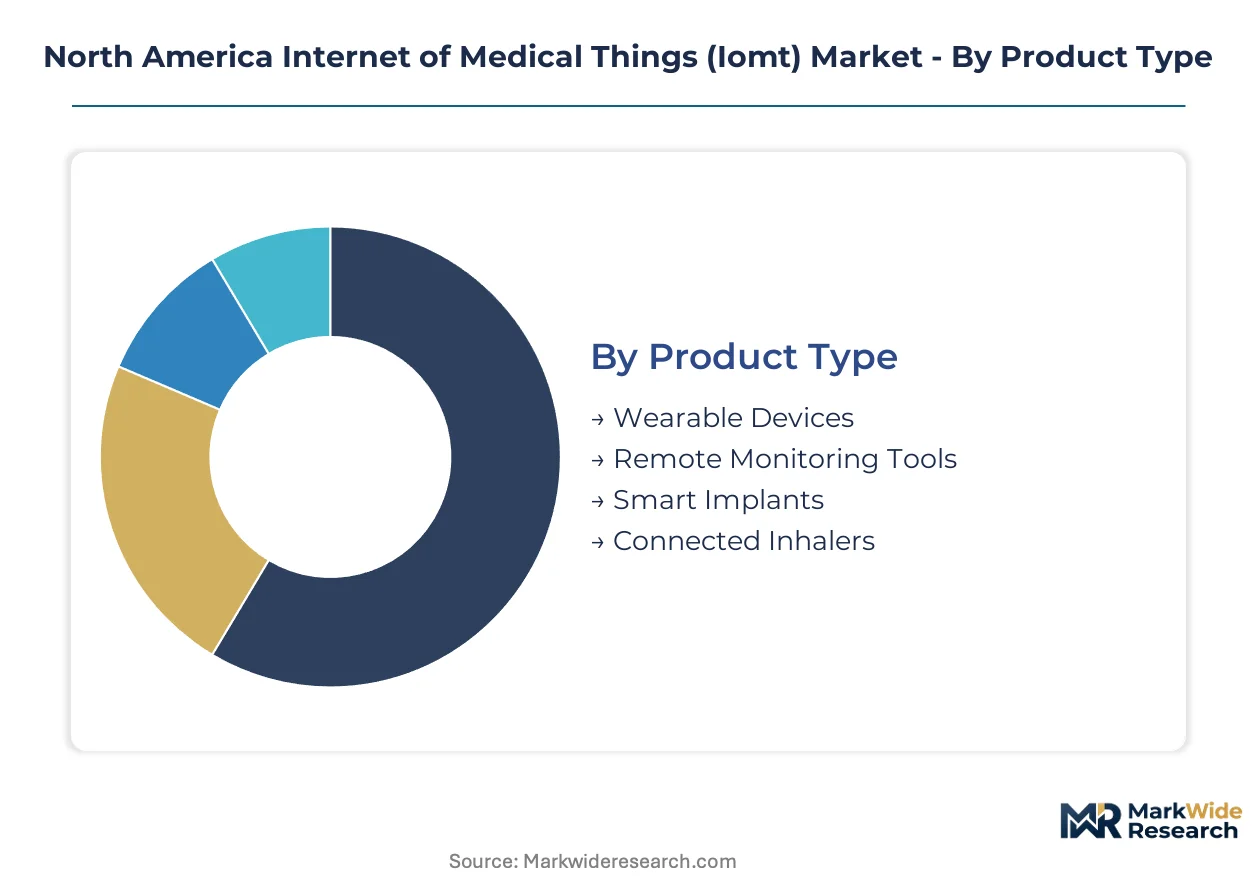
Segmentation in the North America IoMT market reveals how value pools concentrate across hardware tiers, connectivity protocols, and care delivery settings. Product architecture and reimbursement pathways determine which configurations achieve sustainable unit economics.
Product Type:
Cost tier stratification separates capital-intensive surgical placements from consumer-accessible peripherals.
- Wearable Devices:Wrist-worn and patch-based sensors transmit continuous vitals via Bluetooth Low Energy. Demand clusters in California's employer wellness programs and Texas-based Medicare Advantage plans seeking HEDIS gap closure.
- Remote Monitoring Tools:Hub-and-spoke architectures aggregate data from multiple peripheral sensors for cloud transmission. Health systems in Massachusetts and Illinois deploy these for post-acute episode management under bundled payment contracts.
- Smart Implants:Cardiac pacemakers and neurostimulators with embedded telemetry command premium pricing through long-term data subscriptions.
- Connected Inhalers:Prescription-integrated devices for asthma and COPD track adherence and trigger clinical outreach.
Wearable devices hold installed capacity. Connected inhalers are rotating up the share rankings.
Technology:
Maturity curves diverge sharply across wireless protocols, with legacy standards defending installed base against cellular insurgency.
- Bluetooth:Dominates peripheral-to-hub connectivity at 2.4 GHz with sub-10mW power budgets. California's digital health corridor drives specification evolution toward Bluetooth 5.3 mesh topologies for hospital asset tracking.
- Cellular:Sub-6 GHz LTE-M and 5G RedCap modules enable direct-to-cloud telemetry without intermediary hubs. Texas emergency medical services and Florida hospital-at-home programs are accelerating procurement of CAT-M1-enabled cardiac monitors.
- Wi-Fi:2.4/5 GHz infrastructure leverages existing hospital wireless LAN investments for stationary bedside devices.
- RFID:Passive and active radio-frequency identification supports inventory management and surgical instrument traceability.
Bluetooth holds installed capacity. Cellular is climbing the fastest.
Application:
Customer type determines procurement authority and reimbursement eligibility across care settings.
- Chronic Disease Management:Diabetes, heart failure, and COPD programs utilize connected glucometers, weight scales, and pulse oximeters. Medicare's remote patient monitoring billing codes sustain provider investment in Illinois and Pennsylvania health systems.
- Smart Hospitals:Real-time location systems and predictive maintenance platforms integrate IoMT data with building automation. Massachusetts General Brigham and Cleveland Clinic anchor demand for edge-computing infrastructure.
- Home Care:Post-acute discharge monitoring reduces readmission penalties under CMS Hospital Readmissions Reduction Program.
- Emergency Care:Pre-hospital telemetry streams ECG and vital signs during ambulance transport to receiving facilities.
Chronic disease management holds installed capacity. Smart hospitals are rotating up the share rankings.
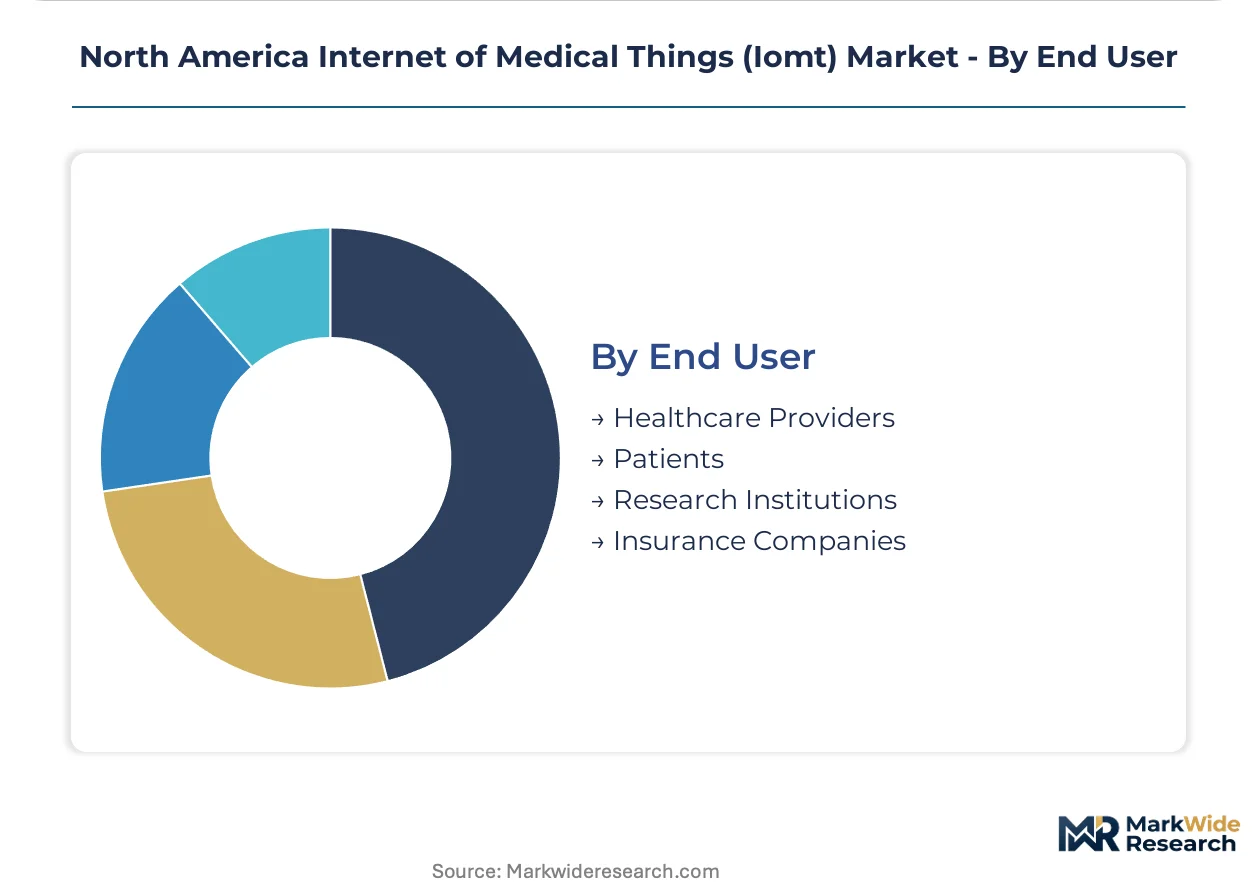
End User:
Volume concentration varies by decision-making authority and budget cycle timing.
- Healthcare Providers:Integrated delivery networks and accountable care organizations command procurement volume through centralized technology assessment committees. Kaiser Permanente and Intermountain Healthcare structure multi-year enterprise agreements spanning device categories.
- Patients:Direct-to-consumer channels bypass institutional procurement for fitness-adjacent devices and continuous glucose monitors with pharmacy fulfillment.
- Research Institutions:Academic medical centers deploy IoMT platforms for decentralized clinical trials and real-world evidence generation.
- Insurance Companies:Payers including UnitedHealth Group and CVS Health utilize device data for risk stratification and care management program enrollment.
Healthcare providers hold installed capacity. Insurance companies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for sub-6 GHz cellular modules concentrates in Taiwan and South Korea, creating supply dependencies that shape North American device procurement timelines. FDA premarket review expertise clusters in specific U.S. metropolitan corridors, while Health Canada imposes parallel interoperability requirements that vendors must satisfy for cross-border deployment.
United States
Medicare's remote patient monitoring billing codes sustain provider investment in Illinois and Pennsylvania health systems. FDA software-as-a-medical-device guidance issued in 2022 imposes predetermined change control plans on machine-learning-enabled diagnostics. California's digital health corridor anchors venture deployment and health system pilot partnerships for remote monitoring platforms.
Canada
Health Canada and the Office of the National Coordinator for Health IT impose interoperability and privacy constraints that vendors must satisfy for cross-border deployment. The country's national pharmaceutical regulator maintains parallel premarket review pathways for algorithm-enabled devices. Ontario's health technology assessment committees structure multi-year enterprise agreements spanning device categories.
Mexico
Nearshoring momentum for medical device manufacturing is accelerating facility investment in Baja California and Chihuahua to serve U.S. demand. The country's federal commission for protection against sanitary risk regulates device registration timelines that affect cross-border supply chain velocity. Guadalajara's electronics manufacturing cluster is expanding cleanroom capacity for Bluetooth Low Energy module assembly.
North America Internet of Medical Things (Iomt) Market Competitive Landscape
Device incumbents and infrastructure specialists split the market into distinct capability layers with limited overlap in customer relationships. Cardiac implant manufacturers leverage long-term data subscriptions to defend installed base positions against peripheral sensor entrants. Network equipment vendors and cloud infrastructure providers represent the two dominant strategic archetypes competing for telemetry platform dominance. Competitive moves concentrate on edge-computing partnerships and algorithm-enabled diagnostic clearances.
Within the cardiac implant tier, Medtronic plc and Boston Scientific Corporation exemplify the surgical placement-to-subscription model that commands premium pricing through embedded telemetry. Among diversified health technology conglomerates, GE Healthcare occupies a position bridging acute-care infrastructure with real-time telemetry platforms. Johnson & Johnson sits within the surgical device-to-digital therapeutics continuum through its orthopedics and consumer health divisions.
| Leading Market Players |
|---|
| Medtronic plc |
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Abbott Laboratories |
| Cisco Systems Inc. |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Foundry undercapacity for sub-6 GHz cellular modules in Taiwan and South Korea is compressing supplier pricing power while inflating procurement lead times for North American IoMT device manufacturers. This utilization squeeze forces buyers into long-term capacity reservations that reshape working capital requirements across the value chain.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across implantable and algorithm-enabled device categories. Premium pricing stratifies across FDA-cleared smart implants, prescription-controlled diagnostics, and consumer-grade wellness peripherals based on certification burden and clinical validation depth. Pricing pressure stems from Medicare's remote patient monitoring reimbursement compression, which tightens margins on hub-and-spoke monitoring architectures. Hospital procurement committees exhibit highest price sensitivity for capital-intensive stationary devices, while cardiac service lines retain pricing tolerance for long-term data subscriptions.
Supply Chain Analysis
Electronics manufacturing services concentration rests with Taiwan Semiconductor Manufacturing Company, Foxconn, and Jabil for Bluetooth Low Energy module assembly and cellular subsystem integration. Raw material dependencies center on lithium carbonate for implantable power cells, gallium arsenide for RF front-ends, and medical-grade silicon wafers for sensor substrates. Single-source vulnerability concentrates in sub-6 GHz cellular baseband chipsets from Qualcomm and MediaTek. Distribution runs through health system GPO contracts, direct-to-hospital agreements with integrated delivery networks, and pharmacy fulfillment channels for direct-to-consumer continuous glucose monitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in edge-AI inference engines where algorithm-enabled diagnostics create specialty niches outside incumbent cardiac portfolios. Unbundling of device capital expenditure from data subscriptions is fragmenting procurement authority and opening vendor entry points.
For Market Incumbents: Insulate recurring-revenue streams by locking hospital systems into multi-year data subscriptions before per-patient-per-month pricing spreads from Texas and Florida pilots. Secure captive supply of sub-6 GHz cellular modules through foundry partnerships in Taiwan to defend against semiconductor allocation shifts toward consumer electronics. FDA software-as-a-medical-device predetermined change control plans represent a regulatory moat; accelerate 510(k) submissions for locked-algorithm tiers to foreclose entrant refinement flexibility. For New Entrants and Emerging Players: Geographic underpenetration in Mexico's hospital-at-home programs and Canadian provincial health technology assessment pathways offers white-space expansion outside saturated U.S. cardiology service lines. Target connected inhaler networks for asthma and COPD populations where prescription-integrated digital therapeutics lack dominant platform incumbents. Pursue edge-AI partnerships with Massachusetts medical device cluster engineering talent to bypass cloud-dependent telemetry architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cardiac implant manufacturers with embedded telemetry and long-term data contracts spanning the projection horizon. Acquisition targets should display FDA premarket review expertise combined with edge-computing inference capabilities. Monitor Health Canada interoperability enforcement and Illinois biometric privacy statute expansion as inflection indicators for cross-border deployment complexity and consent architecture compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for algorithm-enabled diagnostics locks training protocols and constrains post-market refinement. |
| Hospital System Partnership | Multi-year enterprise agreements with Kaiser Permanente or Intermountain Healthcare secure procurement volume commitments. |
| Software Companion Development | Prescription-controlled-update tiers for continuous glucose monitors segment product lines around regulatory flexibility. |
| Reimbursement Strategy | Medicare remote patient monitoring billing code optimization sustains provider investment in Illinois and Pennsylvania. |
| CE Marking Pathway | Parallel Health Canada and European MDR pathways enable cross-border deployment beyond FDA jurisdiction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers at integrated delivery networks, GPO contracts managers, FDA regulatory affairs consultants, and cellular module procurement leads at device manufacturers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and foundry capacity disclosures. Bottom-up unit shipment estimates across wearable, implantable, and connected inhaler categories were triangulated against top-down market value reconstructions.
Calibration anchored installed base estimates on Bluetooth Low Energy shipment data and cellular module procurement patterns across the analysis window. Segmentation modeling spanned product architecture tiers, wireless protocol generations, care delivery settings, and end-user procurement authority. CAGRs were derived from logistic diffusion curves fitted to Medicare billing code utilization trajectories and health system pilot expansion timelines. Forecast inputs incorporated 5G RedCap latency specifications and edge-AI inference engine adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers into telemetry platform aggregation or foundry capacity reallocation toward automotive electronics would shift outcomes. Model boundaries exclude pure consumer fitness devices lacking clinical validation and pharmaceutical cold-chain logistics outside physiological monitoring scope. Quarterly review of FDA software-as-a-medical-device guidance updates and state-level biometric privacy statute proliferation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Accountable Care Solutions Market