
 Global Accountable Care Solutions Market | 2026-2036
Global Accountable Care Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accountable Care Solutions Market Foresight
Pay-per-performance contracting and subscription-based platform licensing is rewriting capital requirements for new entrants in accountable care technology. Epic Systems Corporation leverages its dominant installed base across integrated delivery networks to control upgrade cycles that embed population health modules. UnitedHealth Group sustains competitive density through Optum's captive provider relationships and in-house analytics infrastructure. Cerner Corporation navigates a complex transition under Oracle Health ownership while maintaining legacy hospital system commitments.
Accountable care solutions encompass software platforms, data integration tools, and care management workflows designed to align provider reimbursement with patient outcomes and cost containment targets. Population health management modules aggregate claims, clinical, and social determinants data to stratify risk across attributed patient panels. Care coordination solutions currently anchor revenue streams for incumbent vendors, while cloud-based deployment models represent the fastest-expanding segment as smaller physician groups abandon on-premises infrastructure. Risk adjustment technology concentrates margin pools where Medicare Advantage penetration drives documentation intensity requirements.
The CMS Medicare Shared Savings Program and HHS quality reporting mandates shape product roadmaps and certification requirements for vendors serving United States providers. FDA digital health guidance and ONC interoperability rules further constrain acceptable data exchange architectures. Stakeholders must weigh the pace of federal value-based payment expansion against state Medicaid program variation when allocating platform development resources.
Market Dynamics
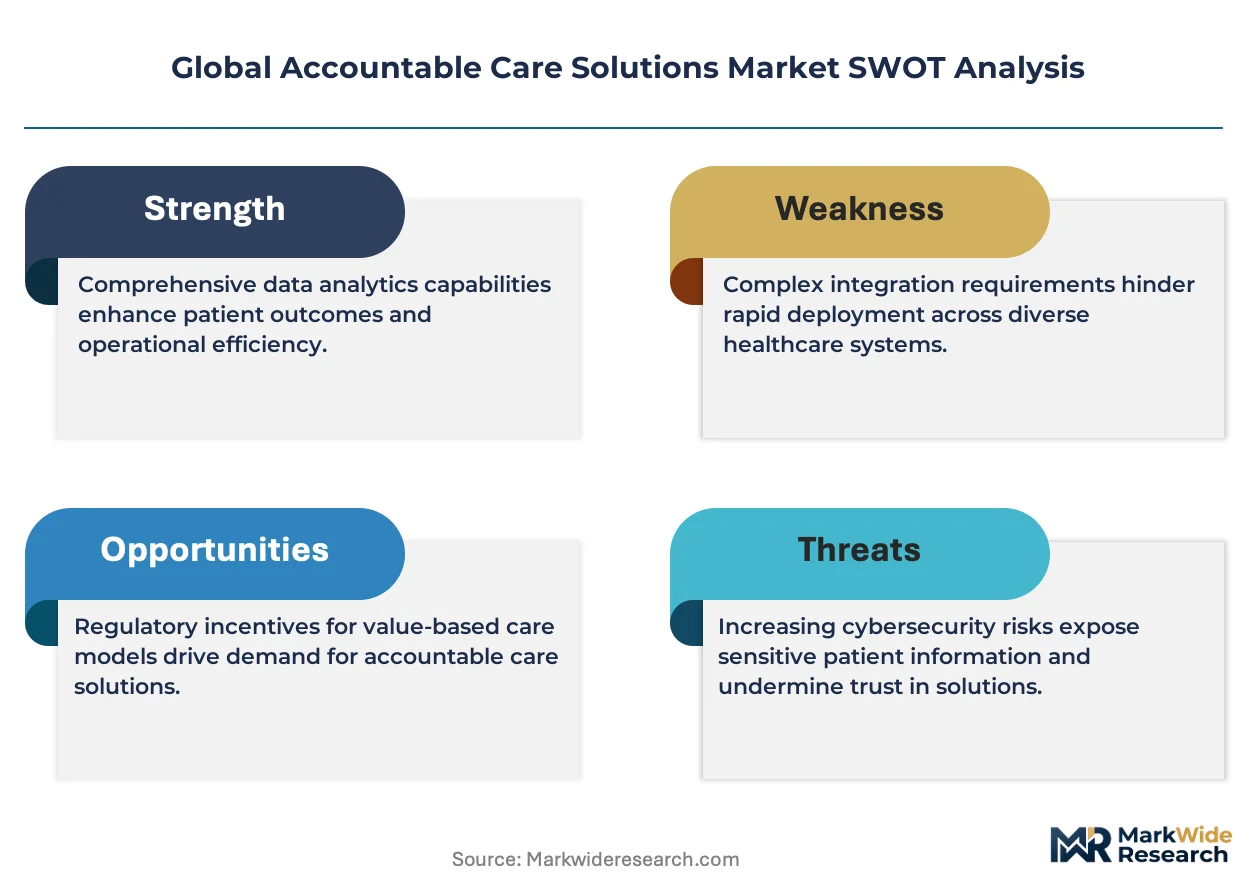
Federal value-based payment mandates are compressing implementation timelines for accountable care infrastructure, forcing physician groups and health systems to accelerate technology procurement cycles while simultaneously managing legacy system integration risks.
Growth Catalysts
- CMS Medicare Shared Savings Program:Quality reporting requirements under the MSSP are mandating population health analytics adoption across United States provider networks, creating immediate procurement pull for risk stratification platforms.
- Cloud-native architecture:Smaller physician groups are abandoning on-premises infrastructure in favor of scalable SaaS deployment models that eliminate capital expenditure barriers to entry.
- Medicare Advantage penetration:Documentation intensity requirements for risk adjustment are concentrating margin pools around technology vendors offering hierarchical condition category capture tools.
Market Restraints
- Interoperability friction:ONC certification requirements and disparate EHR data formats create persistent integration costs that disproportionately burden mid-sized physician practices lacking dedicated IT resources.
- Specialized talent scarcity:Health informaticists with dual clinical-technical training command premium compensation, constraining deployment velocity for new accountable care organizations.
- Legacy system lock-in:Dominant EHR vendors control upgrade cycles that bundle population health modules, limiting standalone solution penetration in integrated delivery networks.
Strategic Opportunities
- Medicaid program variation:State-level accountable care expansion creates white space for configurable platforms adaptable to divergent eligibility rules and quality metrics across United States jurisdictions.
- Social determinants integration:Convergence of clinical claims data with housing, transportation, and food security datasets enables predictive risk models that differentiate attribution performance.
- Direct-to-employer contracting:Self-insured employers are bypassing traditional payers to contract directly with accountable care entities, opening alternative channel pathways for platform vendors.
Industry Challenges
- Attribution methodology complexity:Patient assignment algorithms vary across Medicare, Medicaid, and commercial contracts, forcing vendors to maintain multiple calculation engines and audit trails.
- Quality measure proliferation:The expanding universe of HEDIS, Star Ratings, and custom payer metrics strains reporting infrastructure and requires continuous platform reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accountable Care Solutions Market |
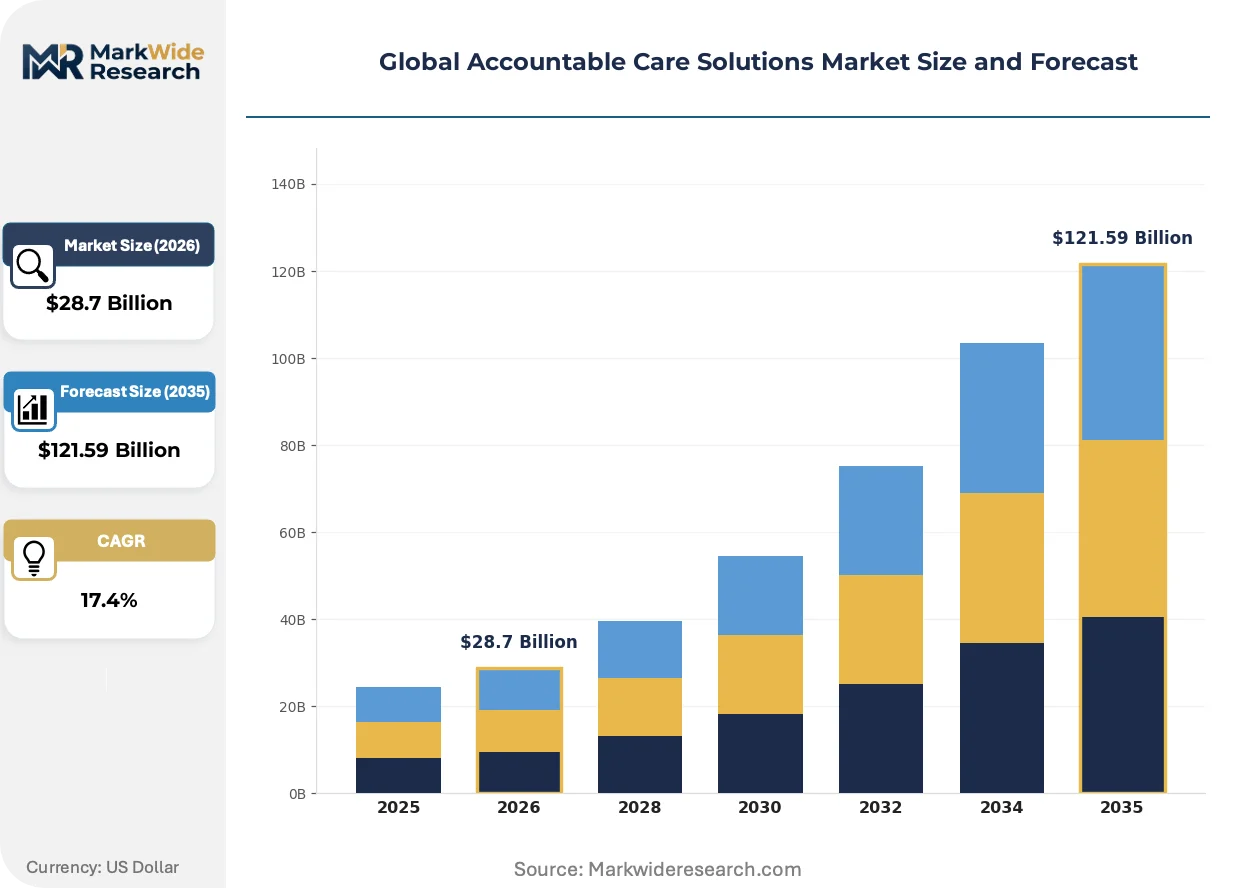
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $121.59 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Care Coordination, Population Health Management, Risk Adjustment, Data Analytics, Patient Engagement, Revenue Cycle Management Application: Chronic Disease Management, Preventive Care, Post-Acute Care, Behavioral Health, Care Transitions, Medication Management End User: Hospitals, Physician Groups, Health Plans, Post-Acute Providers, Skilled Nursing Facilities, Home Healthcare Agencies Deployment Model: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service, Managed Services |
| Companies Covered | Epic Systems Corporation, UnitedHealth Group, IBM Corporation, Cerner Corporation, McKesson Corporation, Aetna Inc., Oracle Health, Veradigm Inc., Allscripts Healthcare Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accountable Care Solutions Market Shifts & Advancements
Computational infrastructure for care coordination is migrating from institutional data centers to distributed cloud environments, enabling real-time analytics that were previously cost-prohibitive for smaller provider organizations.
Remote patient monitoring platforms are virtualizing chronic disease management workflows that historically required in-person encounters. Federally qualified health centers and rural health clinics are deploying cellular-connected biometric devices to extend care team reach. This virtualization is compressing geographic access barriers while generating continuous data streams for risk stratification algorithms.
EMA guidance on digital health evidence standards and FDA software-as-a-medical-device frameworks are converging toward unified clinical validation requirements. Vendors serving both European and United States markets must now maintain parallel quality management systems. Small-to-mid-size platform developers are responding by prioritizing FDA 510(k) clearance pathways that satisfy both regulatory regimes through mutual recognition principles.
Hospital systems are unbundling population health analytics from comprehensive EHR contracts and evaluating best-of-breed point solutions. Procurement committees now separate care coordination software from core clinical documentation platforms. This pattern is most visible in United States metropolitan markets where independent physician associations maintain sufficient scale to negotiate direct vendor relationships.
Global Accountable Care Solutions Market Segmentation
Accountable care solutions fragment across functional modules, clinical applications, and infrastructure models that dictate procurement priorities. Vendors must align platform architecture with specific reimbursement workflows and care delivery settings to capture contract value.
Solution Offering:
After-sales service intensity varies sharply across solution types, with care coordination platforms requiring ongoing clinical workflow optimization while risk adjustment tools demand periodic algorithm recalibration.
- Care Coordination:Workflow engines that synchronize multi-disciplinary care teams around shared patient plans through task routing and escalation protocols. Demand concentrates in United States metropolitan markets where independent physician associations negotiate direct vendor relationships, driven by CMS Medicare Shared Savings Program attribution requirements.
- Population Health Management:Analytics platforms aggregating claims, clinical, and social determinants data for risk stratification. United States health systems dominate procurement as they unbundle these capabilities from comprehensive EHR contracts, constrained by interoperability friction from disparate data formats.
- Risk Adjustment:Documentation capture tools for hierarchical condition category coding. Medicare Advantage penetration in Florida and Arizona drives concentrated demand.
- Data Analytics:Predictive models for utilization patterns and cost trajectory forecasting. Health plans deploy these for actuarial reserve calculations.
- Patient Engagement:Portal and mobile interfaces for care plan adherence and appointment scheduling. Federally qualified health centers prioritize these for Medicaid populations.
- Revenue Cycle Management:Claims processing and denial management workflows. Post-acute providers in Texas and California represent active procurement segments.
By volume, Care Coordination leads. By growth pace, Risk Adjustment is ahead.
Application:
Clinical use case segmentation tracks reimbursement incentive structures, with chronic disease management commanding premium pricing due to continuous monitoring requirements and behavioral health gaining traction through new CPT code reimbursement.
- Chronic Disease Management:Diabetes, heart failure, and COPD protocols with remote monitoring integration. United States Medicare Advantage plans in Pennsylvania and Ohio attribute substantial technology budgets here, driven by HEDIS measure performance bonuses.
- Preventive Care:Screening reminders and wellness outreach for attributed populations. Large physician groups in North Carolina deploy these for MSSP quality scoring.
- Post-Acute Care:Discharge planning and readmission reduction workflows. Skilled nursing facilities in Illinois and Michigan prioritize these for hospital partnership contracts.
- Behavioral Health:Integration of mental health screening into primary care encounters. Colorado and Washington state Medicaid programs drive procurement through value-based behavioral health carve-outs.
- Care Transitions:Handoff protocols between acute and post-acute settings. Arizona and Nevada health systems invest here for Medicare readmission penalty avoidance.
- Medication Management:Adherence tracking and polypharmacy alerts. Medicare Part D plans in California require these for Star Ratings improvement.
Chronic Disease Management captures the largest revenue pool, while Behavioral Health demonstrates the steepest expansion trajectory.
End User:
Customer type determines contract structure complexity, with hospitals demanding enterprise-wide integration and physician groups prioritizing rapid deployment without dedicated IT resources.
- Hospitals:Integrated delivery networks requiring enterprise population health infrastructure. United States health systems in Massachusetts and Minnesota lead procurement, constrained by legacy EHR upgrade cycle dependencies.
- Physician Groups:Independent practices and medical groups seeking scalable SaaS deployment. Texas and Florida groups favor cloud-native solutions to eliminate capital expenditure.
- Health Plans:Payers building proprietary analytics or sourcing third-party platforms. UnitedHealth Group and regional Blues plans maintain captive development.
- Post-Acute Providers:Long-term care hospitals and rehabilitation facilities. Georgia and Tennessee markets show concentrated demand.
- Skilled Nursing Facilities:Medicare ACO reach entities requiring quality reporting automation. California and Ohio facilities prioritize these capabilities.
- Home Healthcare Agencies:Mobile workforce coordination and remote patient monitoring integration. Medicare-certified agencies in Arizona and Colorado expand technology budgets.
Physician Groups represent the broadest addressable base, though Health Plans command the highest contract values per seat.
Deployment Model:
Infrastructure choice reflects capital availability and data sovereignty requirements, with cloud migration accelerating among smaller providers lacking on-premises maintenance capacity.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and elastic scaling. United States physician groups under 50 providers in Texas, Florida, and Arizona dominate adoption, driven by zero capital expenditure requirements and rapid MSSP compliance timelines.
- On-Premises:Installed software within institutional data centers. Large health systems in Massachusetts and Minnesota retain these for data residency control, constrained by specialized talent scarcity for infrastructure management.
- Hybrid:Split architectures with sensitive data on-premises and analytics in cloud. Mid-sized hospitals in Illinois and Ohio favor this model.
- Software-as-a-Service:Subscription licensing with vendor-managed infrastructure. Independent physician associations in North Carolina and Georgia standardize here.
- Managed Services:Outsourced platform operation with clinical informaticist staffing. Rural health clinics in Montana and Idaho procure these to overcome talent gaps.
Cloud-Based deployment holds the dominant volume position, while Managed Services is climbing the fastest among underserved rural markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains substantial trade surplus in accountable care technology exports, while Germany and Japan rely on imported cloud infrastructure to support domestic health system modernization. Import dependency concentrates in analytics engines and population health platforms where vendor ecosystems remain concentrated in North American markets.
United States
Medicare Shared Savings Program attribution requirements drive procurement across independent physician associations in Texas and Florida. CMS quality reporting mandates tighten annually, forcing mid-sized practices toward SaaS deployment models. The Dallas-Fort Worth metroplex anchors concentrated demand for risk adjustment technology serving Medicare Advantage plans.
Germany
Statutory health insurance funds pilot value-based contracting frameworks modeled on U.S. accountable care structures. EMA digital health guidance shapes platform certification requirements for vendors entering European markets. The Rhine-Ruhr industrial corridor hosts emerging health informatics clusters developing interoperability standards for cross-border patient data exchange.
United Kingdom
NHS Integrated Care Systems absorb population health management tools to manage capitated budgets across primary care networks. NICE technology appraisal frameworks evaluate clinical and cost-effectiveness of care coordination platforms. Greater Manchester and London health systems lead procurement velocity for predictive analytics targeting chronic disease prevention.
Japan
Ministry of Health, Labour and Welfare reforms accelerate community-based integrated care system deployment. METI industrial policy channels subsidies toward health IT infrastructure supporting aging demographics. The Kanto region surrounding Tokyo concentrates vendor activity for remote patient monitoring platforms serving rural prefectures.
Australia
Primary Health Networks expand value-based commissioning pilots requiring risk stratification capabilities. TGA software-as-a-medical-device frameworks regulate clinical decision support modules. New South Wales and Victoria health systems drive demand for cloud-native care coordination tools connecting metropolitan hospitals with regional primary care.
Global Accountable Care Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying risk adjustment algorithms and care coordination modules. Market structure concentrates around three to five vertically integrated health technology conglomerates controlling EHR-to-analytics upgrade cycles, while mid-tier vendors compete on configurable Medicaid program adaptation. Dominant strategic moves include captive provider network formation through payer-owned delivery assets, and cloud infrastructure partnerships eliminating capital barriers for physician group customers.
Within the integrated platform tier, Epic Systems Corporation and Cerner Corporation exemplify archetypes leveraging installed base density to bundle population health capabilities. UnitedHealth Group occupies a distinct position through Optum's captive provider relationships and in-house analytics infrastructure. IBM Corporation and Oracle Health represent technology conglomerates navigating healthcare vertical specialization through acquired assets and cloud infrastructure investment.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| UnitedHealth Group |
| IBM Corporation |
| Cerner Corporation |
| McKesson Corporation |
| Aetna Inc. |
| Oracle Health |
| Veradigm Inc. |
| Allscripts Healthcare Solutions Inc. |
| Others |
Supply & Pricing Matrix
The Dallas-Fort Worth metroplex concentrates cloud infrastructure capacity serving Medicare Advantage plans, and this geographic density grants regional data centers disproportionate leverage over SaaS pricing for physician groups seeking rapid MSSP compliance.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across accountable care platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise health systems with dedicated IT staff from mid-sized physician groups and rural clinics. Pricing pressure stems from cloud-native entrants undercutting legacy EHR bundles with zero-capital-deployment models. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with captive analytics infrastructure show lowest.
Supply Chain Analysis
Extended payment terms from health system procurement committees now stretch vendor cash conversion cycles beyond ninety days, forcing platform developers toward supply-chain finance facilities. Component sourcing draws from United States cloud infrastructure providers, Indian software engineering services, and Irish data residency facilities. Dependencies center on HIPAA-compliant hosting, FHIR interoperability modules, and clinical informaticist labor pools. Single-source vulnerability concentrates in Epic Systems upgrade cycles controlling population health module distribution. Distribution runs through direct enterprise sales teams for health systems and channel partners for physician group segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through health system consolidation and independent physician association scale aggregation, fragmenting vendor pricing leverage across contracting tables.
For Market Incumbents: Harden defensive moats by deepening backward integration into cloud infrastructure ownership and accelerating FDA 510(k) clearance pipelines for risk adjustment modules. Threat from best-of-breed point solutions unbundling population health analytics demands preemptive certification investment in ONC interoperability standards. For New Entrants and Emerging Players: Build out configurable Medicaid program adaptation engines targeting state-level accountable care expansion in Texas and Florida. Rural health clinics in Montana and Idaho represent most penetrable addressable market. Go-to-market through managed services partnerships overcoming specialized talent scarcity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platforms with demonstrated MSSP attribution algorithm accuracy. Long-term viability hinges on convergence toward unified FDA-EMA digital health evidence standards. Acquisition target archetype: risk adjustment technology vendors with hierarchical condition category capture tools. Signal to watch: Medicare Advantage penetration rates in Florida and Arizona as demand inflection proxy.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Eliminates capital barriers for Texas physician groups seeking SaaS deployment. |
| FDA 510(k) Clearance Pathway | Unlocks mutual recognition with EMA for European market entry acceleration. |
| Medicaid Program Configuration | Captures white space from state-level eligibility rule variation across jurisdictions. |
| Social Determinants Data Integration | Enables predictive risk models differentiating attribution performance for CMS. |
| Direct-to-Employer Channel Development | Bypasses traditional payer intermediaries for self-insured employer contracting. |
Research Methodology
Desk research of FDA 510(k) filings, CMS Medicare Shared Savings Program rulemaking archives, and hospital procurement databases preceded structured interviews with health system CIOs, accountable care organization executives, clinical informaticists, and GPO contracts managers. Primary fieldwork combined with secondary validation from ONC interoperability certification records and health plan technology RFP documents. Bottom-up sizing of vendor contract values triangulated against top-down health IT spending forecasts.
Assumptions held fixed include CMS quality reporting mandate timelines and Medicare Advantage penetration trajectories; variables stress-tested encompass cloud infrastructure cost curves and health informaticist wage inflation. Segmentation modeling spanned deployment model, end-user type, solution functionality, and regional regulatory cluster dimensions. CAGRs derived from logistic adoption curves fitted to historical EHR transition patterns and projected value-based payment expansion rates.
Stress conditions across federal value-based payment acceleration, state Medicaid program volatility, and cloud vendor market concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Femtech Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Clinical Healthcare IT Market