
 Global Computerized Physician Order Entry (CPOE) Systems Market | 2026-2036
Global Computerized Physician Order Entry (CPOE) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computerized Physician Order Entry (CPOE) Systems Market Foresight
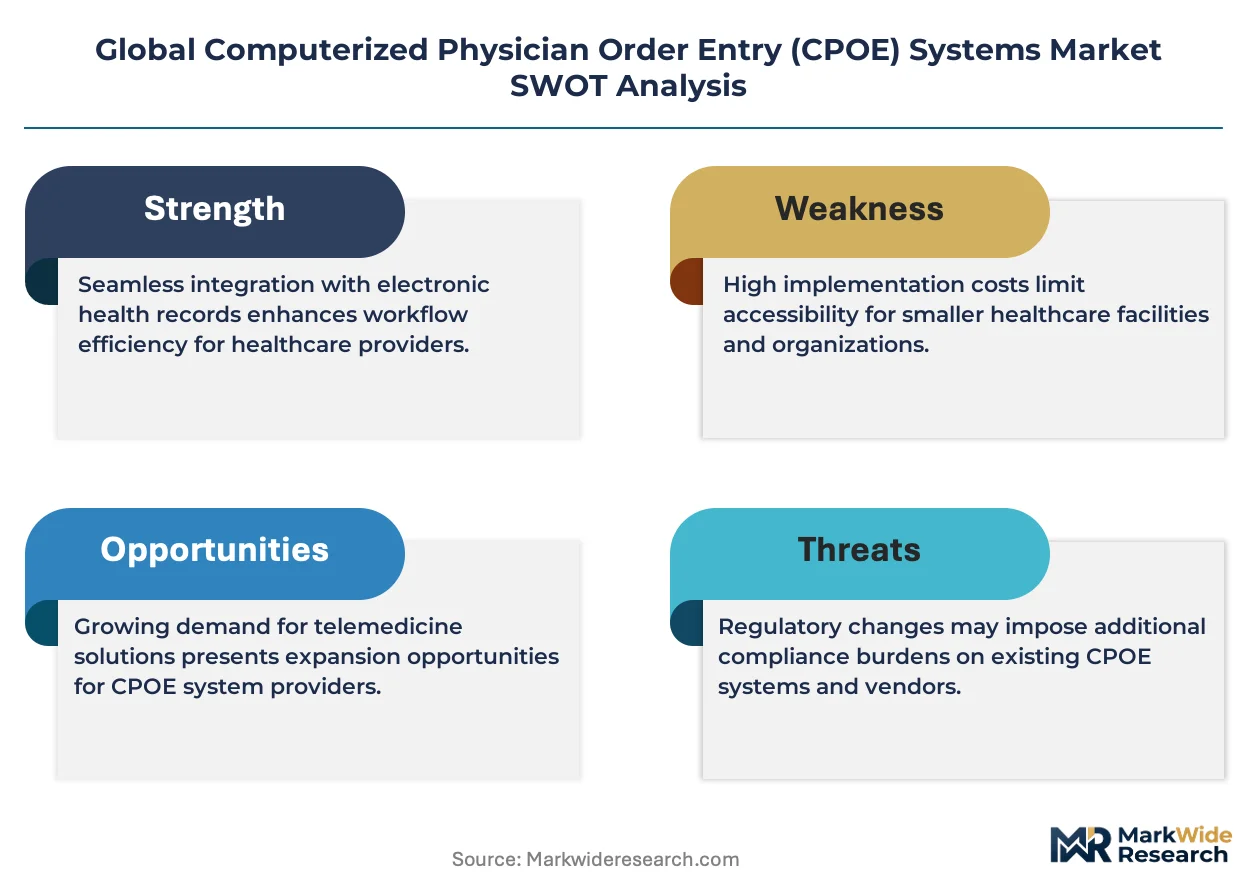
The divergence between premium integrated CPOE suites and commodity standalone modules is repositioning procurement dynamics across health systems. Epic Systems Corporation dominates the high-reliability segment with deep EHR integration, while MEDITECH competes aggressively on total cost of ownership for mid-size hospitals. Oracle Health leverages its cloud infrastructure to extend platform stickiness, and Athenahealth anchors ambulatory market share through subscription pricing.
Computerized Physician Order Entry systems are clinical software platforms that capture, process, and transmit physician instructions for medications, laboratory tests, and radiology procedures through structured digital interfaces with embedded clinical decision support algorithms. These systems eliminate transcription errors, enforce formulary compliance, and generate audit trails for quality reporting. Integrated Systems lead enterprise deployments because hospitals prioritize unified data architectures over fragmented point solutions. Cloud-Based Systems represent the fastest-expanding technology category as health systems shed on-premise maintenance burdens. Medication Management remains the core application driver, though Surgical Scheduling modules are gaining traction in perioperative optimization.
The FDA oversees CPOE safety through its health IT pre-certification framework, while HIPAA mandates audit controls that shape system design requirements. The EU MDR and GDPR impose cross-border data residency and clinical evidence standards that complicate vendor expansion. Stakeholders must monitor how ONC interoperability rules and emerging AI governance frameworks will reshape certification criteria and competitive barriers.
Market Dynamics
The interoperability mandates embedded in the 21st Century Cures Act are forcing health systems to retire legacy CPOE architectures and consolidate vendor relationships around unified data models.
Growth Catalysts
- Interoperability Mandates:The ONC 21st Century Cures Act Final Rule requires standardized APIs for patient data exchange, compelling hospital networks to upgrade CPOE systems with FHIR-compliant interfaces.
- Perioperative Optimization:Surgical departments are expanding CPOE modules beyond medication ordering to encompass anesthesia workflows, instrument tracking, and block scheduling efficiency.
- German Hospital Digitization:The country's Hospital Future Act allocates federal funding for integrated clinical information systems, accelerating CPOE procurement in university hospitals and municipal networks.
Market Restraints
- Implementation Cost Burden:Mid-size community hospitals face capital constraints when migrating from basic e-prescribing to full enterprise CPOE suites with embedded clinical decision support.
- Legacy System Entrenchment:Proprietary data formats in decades-old hospital information systems create technical debt that resists standardized migration pathways.
- EU MDR Compliance Friction:Cross-border data residency requirements and clinical evidence standards for software-as-medical-device classification complicate vendor expansion timelines.
Strategic Opportunities
- Cloud-Native Ambulatory Expansion:Federally qualified health centers and specialty clinics represent underpenetrated deployment targets for lightweight, subscription-based CPOE platforms.
- AI-Augmented Decision Support:Machine learning models for drug-drug interaction prediction and dosing optimization are converging with CPOE workflows to reduce alert fatigue.
- India's Digital Health Mission:The country's national health stack and ABHA identifier system create infrastructure for CPOE adoption in tier-2 and tier-3 city hospital networks.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems struggle to recruit physician informaticists capable of bridging workflow design with technical configuration.
- Alert Configuration Complexity:Tuning clinical decision support rules to minimize alert fatigue while maintaining patient safety requires iterative refinement that strains IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computerized Physician Order Entry (CPOE) Systems Market |
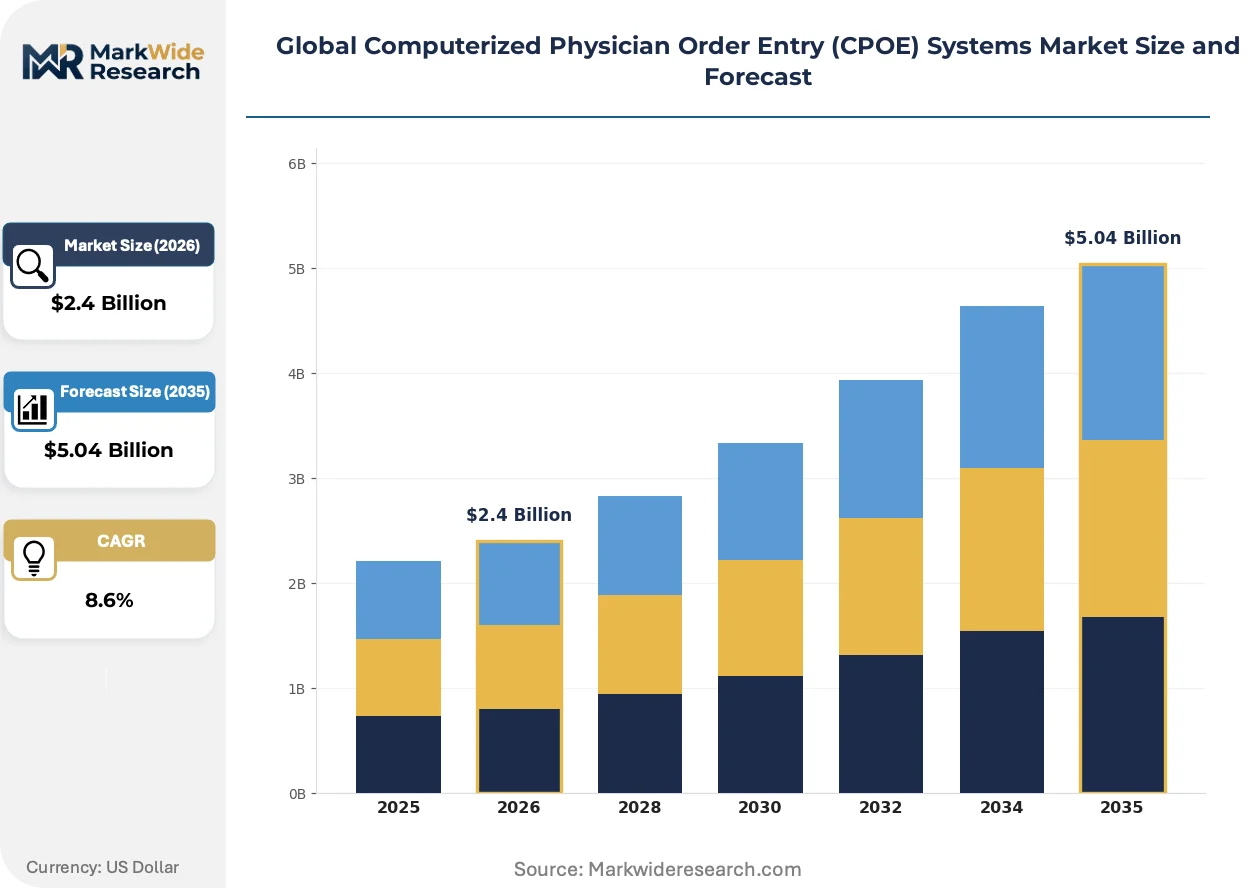
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Cloud-Based Systems, On-Premise Systems Technology: Decision Support, Barcode Medication Administration, Electronic Prescribing, Mobile Accessibility Application: Medication Management, Laboratory Orders, Radiology Requests, Surgical Scheduling End User: Hospitals, Ambulatory Care, Specialty Clinics, Diagnostic Centers |
| Companies Covered | MEDITECH, McKesson Corporation, Epic Systems Corporation, Philips Healthcare, Siemens Healthineers, Oracle Health, GE Healthcare, Athenahealth, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computerized Physician Order Entry (CPOE) Systems Market Shifts & Advancements
Generative AI capabilities are embedding into CPOE interfaces, reshaping how physicians interact with order sets and clinical documentation. Voice-enabled ordering and predictive order suggestions are compressing interaction times.
Natural language processing for clinical documentation is absorbing unstructured physician dictation into structured CPOE order sets. Academic medical centers in the United States are piloting ambient listening tools that convert conversational patient encounters into discrete orders. This capability is compressing documentation burden and reducing click fatigue in high-volume emergency departments.
GDPR's algorithmic accountability requirements are reshaping how European hospitals deploy AI-enhanced CPOE modules. The regulation mandates explainability for clinical decision support recommendations that influence prescribing behavior. German and French hospital networks are responding by demanding vendor transparency into model training data and confidence scoring methodologies.
Subscription pricing models are displacing perpetual license structures in ambulatory CPOE procurement. Primary care networks and specialty practices favor predictable operating expenditures over capital-intensive deployments. This shift is most visible in United States multi-site physician groups consolidating vendor relationships under enterprise agreements with usage-based scaling provisions.
Global Computerized Physician Order Entry (CPOE) Systems Market Segmentation
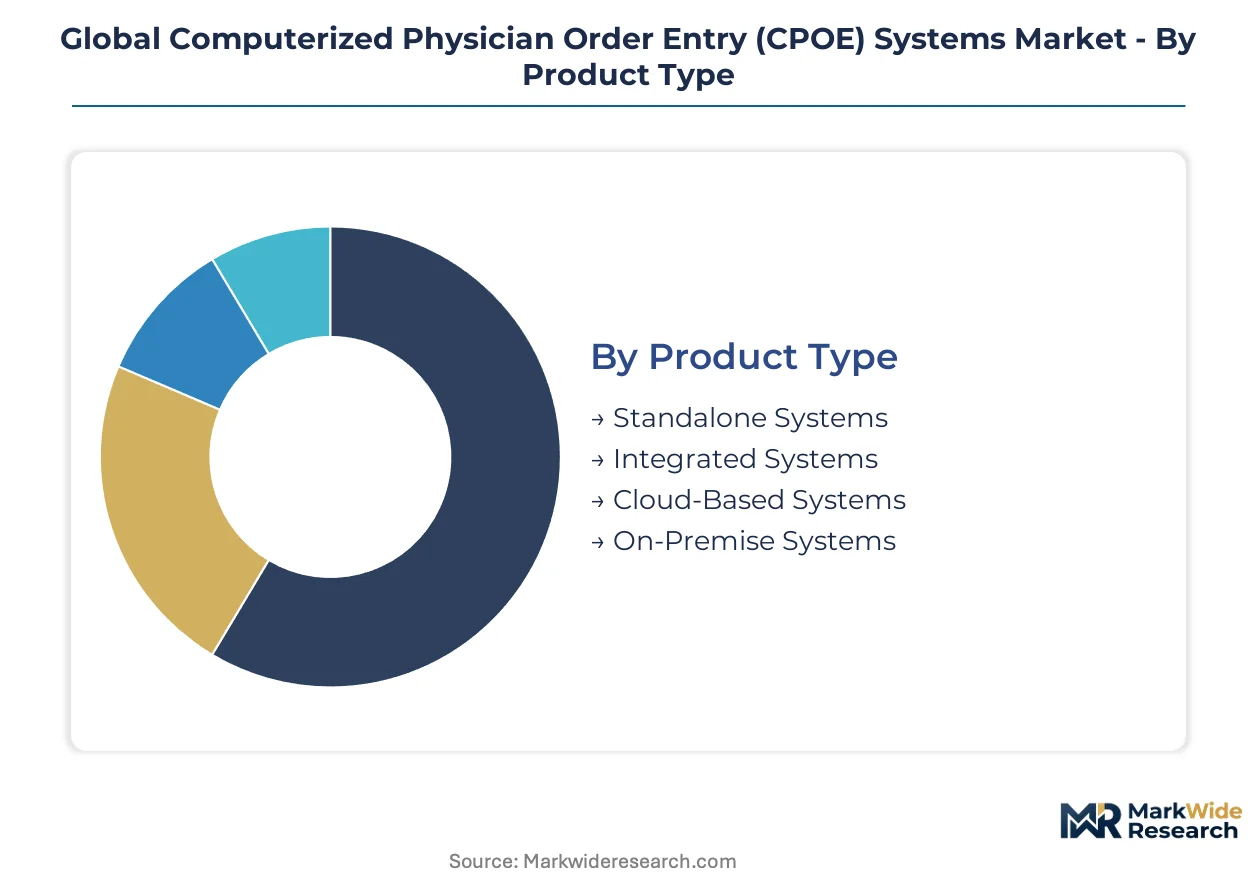
CPOE procurement patterns diverge sharply across technology architectures and care settings. Hospital IT leaders weigh integration depth against deployment flexibility when selecting system configurations.
Product Type:
Technology architecture determines total cost of ownership and interoperability potential.
- Integrated Systems:These platforms embed CPOE functionality within comprehensive electronic health record suites, sharing unified patient data repositories across clinical modules. Academic medical centers in the United States prioritize these deployments to satisfy ONC interoperability mandates and eliminate interface maintenance between disparate systems.
- Cloud-Based Systems:Vendor-hosted infrastructure shifts capital expenditure to operational budgets while enabling remote accessibility for distributed care teams. German hospital networks under the Hospital Future Act are accelerating migration to these platforms to modernize municipal and university hospital IT estates without on-premise hardware refresh cycles.
- Standalone Systems:Modular point solutions address specific ordering workflows without full EHR replacement.
- On-Premise Systems:Self-hosted deployments persist in highly regulated environments with strict data residency requirements.
Integrated Systems lead on scale; Cloud-Based Systems lead on momentum.
Technology:
Functional capabilities differentiate vendor offerings across clinical safety and workflow efficiency dimensions.
- Decision Support:Embedded clinical algorithms flag drug-drug interactions, allergy contraindications, and dosing errors at the point of order entry. Alert fatigue mitigation drives configuration investment from hospital informatics teams seeking to preserve physician workflow acceptance.
- Electronic Prescribing:Direct transmission of medication orders to retail and mail-order pharmacies eliminates transcription errors and accelerates prescription fulfillment. Ambulatory care networks in the United States deploy this capability to meet Medicare quality reporting requirements and controlled substance prescription tracking mandates.
- Barcode Medication Administration:Bedside scanning verification closes the loop between ordered and administered medications.
- Mobile Accessibility:Smartphone and tablet interfaces extend ordering capability beyond fixed workstation locations.
Electronic Prescribing dominates ambulatory penetration; Decision Support commands premium pricing in enterprise tenders.
Application:
Clinical domain specialization shapes module selection and implementation sequencing.
- Medication Management:The foundational CPOE use case encompasses formulary enforcement, allergy checking, and therapeutic duplication alerts. Hospital pharmacy departments anchor procurement decisions for this segment based on inventory integration and controlled substance tracking requirements.
- Surgical Scheduling:Perioperative optimization modules coordinate operating room block allocation, anesthesia workflows, and instrument sterilization tracking. United States health systems are expanding these deployments to recover pandemic-deferred surgical volumes through efficiency gains.
- Laboratory Orders:Structured test requisition with appropriateness criteria reduces unnecessary diagnostic utilization.
- Radiology Requests:Imaging order entry with clinical decision support for modality selection and contrast protocol guidance.
Medication Management leads on installed base; Surgical Scheduling climbs the fastest on perioperative investment priorities.
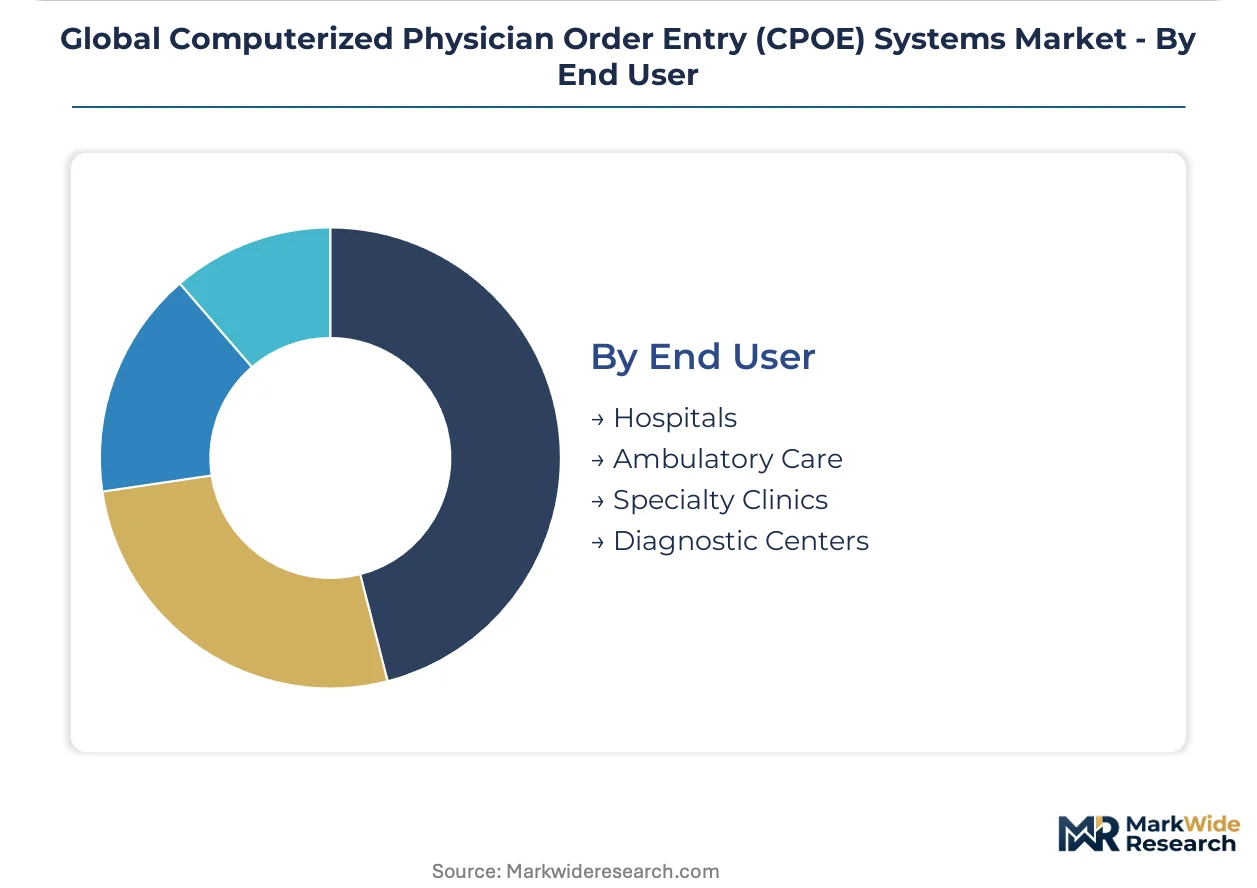
End User:
Care setting characteristics dictate system complexity requirements and deployment economics.
- Hospitals:Enterprise-grade CPOE deployments support high-acuity workflows across emergency, inpatient, and perioperative environments. Multi-hospital health systems in Germany consolidate vendor relationships around unified platforms to achieve economies of scale in implementation and training.
- Ambulatory Care:Federally qualified health centers and multi-site primary care groups favor subscription-priced platforms with rapid deployment timelines. These settings prioritize e-prescribing and referral management over the deep clinical decision support required in acute care.
- Specialty Clinics:Disease-specific workflow templates address oncology infusion centers, dialysis units, and behavioral health settings.
- Diagnostic Centers:Standalone imaging and laboratory facilities require order intake interfaces without full clinical documentation capability.
Hospitals lead on revenue concentration; Ambulatory Care expands most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical informaticists cluster in metropolitan hospital networks across the United States, Germany, India, Japan, and the United Kingdom, anchoring CPOE deployment capacity and vendor technical support infrastructure.
United States
Academic medical centers in Boston and the Research Triangle drive enterprise CPOE adoption for perioperative optimization. The 21st Century Cures Act mandates ONC-certified FHIR APIs, forcing health system consolidation around unified platforms. Stanford Health Care and Mayo Clinic anchor interoperability pilot programs in California and Minnesota.
Germany
University hospitals in Munich and Berlin prioritize integrated clinical workflows under the Hospital Future Act federal funding program. The EU MDR imposes software-as-medical-device classification requirements that reshape vendor certification timelines. Baden-Württemberg's municipal hospital networks accelerate cloud migration to modernize IT estates.
India
Tier-2 city hospital networks in Karnataka and Telangana expand CPOE procurement through the national health stack and ABHA identifier infrastructure. The country's pharmaceutical regulator enforces digital prescription standards for controlled substances. Apollo Hospitals and Max Healthcare anchor private-sector deployment in Chennai and Delhi-NCR.
Japan
Metropolitan general hospitals in Tokyo and Osaka integrate CPOE modules with existing hospital information systems. METI's healthcare digitization subsidies reduce capital barriers for mid-size facilities. The Kansai region's medical device cluster supports localized vendor technical partnerships.
United Kingdom
NHS Trusts in London and Greater Manchester consolidate electronic prescribing systems under national interoperability frameworks. Health England's clinical safety standards mandate embedded decision support for medication management. The Cambridge-Oxford corridor anchors academic health science center pilot programs.
Global Computerized Physician Order Entry (CPOE) Systems Market Competitive Landscape
Capital-heavy EHR suite producers compete with asset-light ambulatory specialists for CPOE market positioning. The vendor base stratifies across three tiers: premium integrated platforms commanding enterprise health systems, mid-market solutions competing on total cost of ownership, and subscription-based cloud offerings penetrating outpatient networks. Strategic archetypes include deep EHR integrators, cloud-native disruptors, and legacy infrastructure modernizers. M&A consolidation and cloud infrastructure partnerships represent the dominant competitive moves reshaping vendor relationships.
Among integrated-suite specialists, Epic Systems Corporation and Oracle Health exemplify contrasting architectural philosophies for enterprise deployment. MEDITECH occupies a position within the mid-market tier, competing aggressively on implementation timelines for community hospital networks. Athenahealth anchors the subscription-model vector, representing asset-light penetration of ambulatory care settings through predictable operating expenditure structures.
| Leading Market Players |
|---|
| MEDITECH |
| McKesson Corporation |
| Epic Systems Corporation |
| Philips Healthcare |
| Siemens Healthineers |
| Oracle Health |
| GE Healthcare |
| Athenahealth |
| Allscripts Healthcare Solutions |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure integration anchors supply positioning and pricing power for enterprise CPOE vendors, while subscription-based delivery models compress upfront revenue recognition and shift buyer leverage toward ongoing service performance. Oracle Health's data center investments and Epic Systems Corporation's self-hosted architecture exemplify how vertical control over compute resources buffers margin pressure from third-party hosting fees.
Pricing Analysis
Bundled EHR-CPOE suites command premium positioning against unbundled standalone modules. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center deployments from community hospital configurations and ambulatory clinic subscriptions. Cost compression in mid-market tiers intensifies because MEDITECH and Allscripts Healthcare Solutions compete aggressively on total cost of ownership. Federally qualified health centers exhibit highest price sensitivity due to constrained capital budgets, while German university hospitals under Hospital Future Act funding show lowest sensitivity.
Supply Chain Analysis
Reverse-logistics flows for on-premise hardware refreshes and cloud data center decommissioning shape vendor asset management strategies in the United States, Germany, and India. CPOE platform development draws from specialized health informatics talent pools, FHIR-compliant API middleware, and AI/ML inference accelerators. Single-source vulnerability concentrates in cloud infrastructure providers serving hospital networks. Distribution runs through direct enterprise sales teams for integrated suites and channel partners for ambulatory subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CPOE systems rests on cloud-native delivery cost-down trajectories and premium-tier AI-augmented decision support modules that justify subscription uplift.
For Market Incumbents: To counter cloud-native disruptors and alert-fatigue-driven switching, Epic Systems Corporation and Oracle Health should deepen FHIR API standardization investments and anchor hospital loyalty through embedded clinical decision support that resists modular disaggregation. Certification investment in EU MDR software-as-medical-device pathways preserves European expansion optionality. For New Entrants and Emerging Players: Direct-to-clinic digital channels offer the fastest penetration vector for lightweight CPOE platforms targeting India's tier-2 city hospital networks and United States federally qualified health centers. White-space concentration in perioperative optimization modules for mid-size German municipal hospitals enables specialty positioning against suite incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud infrastructure costs and clinical informatics talent scarcity simultaneously squeeze mid-tier vendor margins. Acquisition target archetypes include ambulatory-focused SaaS platforms with proven FHIR interoperability and established German Hospital Future Act procurement relationships. Monitor ONC interoperability rule enforcement intensity as inflection indicator for suite consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Standardization | ONC certification requirements force vendor alignment around unified data exchange protocols. |
| AI-Augmented Decision Support | Machine learning integration reduces alert fatigue while justifying premium subscription tiers. |
| Cloud-Native Platform Migration | German hospital networks shed on-premise maintenance burdens under Hospital Future Act modernization. |
| Ambulatory Subscription Expansion | United States multi-site physician groups favor predictable operating expenditures over capital deployment. |
| EU MDR Compliance Investment | Software-as-medical-device classification reshapes vendor certification timelines for European market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with hospital CIOs, clinical informaticists, health system procurement directors, and EHR implementation specialists with secondary validation against FDA health IT pre-certification filings, ONC interoperability rulemaking dockets, CMS Medicare hospital data, and German Hospital Future Act funding disbursement records. Bottom-up vendor shipment estimates and top-down health IT expenditure aggregates were cross-referenced for triangulation.
Comparable-period anchoring linked projection models to historical CPOE adoption waves following 21st Century Cures Act implementation and German federal digitization program launches. Segmentation dimensions spanned deployment architecture, care setting acuity, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to hospital capital expenditure cycles and ambulatory clinic subscription renewal patterns.
Regulatory enforcement delays, cloud infrastructure cost volatility, and clinical informatics talent scarcity are the dominant revision risks to forecast assumptions. Practitioners should monitor ONC rulemaking velocity, hyperscaler pricing announcements, and health system hiring data for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Femtech Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Veterinary Dental Software Market