
 Healthcare Enterprise Software Market | 2026-2036
Healthcare Enterprise Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Enterprise Software Market Outlook
Health informatics talent scarcity is rotating strategic priority toward platforms that reduce manual workflow dependency. Epic Systems Corporation dominates academic medical centers through deep clinical content specialization. Oracle Health leverages cloud infrastructure scale to compete for multi-hospital contracts. athenahealth anchors ambulatory market share with network-enabled revenue cycle services.
Healthcare enterprise software denotes integrated information systems that manage clinical, operational, and financial workflows across provider organizations, typically built on HL7 FHIR interoperability standards and ISO 27001-certified security architectures. These platforms aggregate patient data, automate administrative processes, and enable real-time decision support across care continuums. Cloud-based deployments now lead new installations as hospitals exit capital-intensive on-premise data centers. Artificial Intelligence and Machine Learning segments attract disproportionate R&D allocation where diagnostic decision support and predictive analytics command premium pricing. Revenue Cycle Management retains mature margin pools despite slower growth as providers prioritize claims optimization.
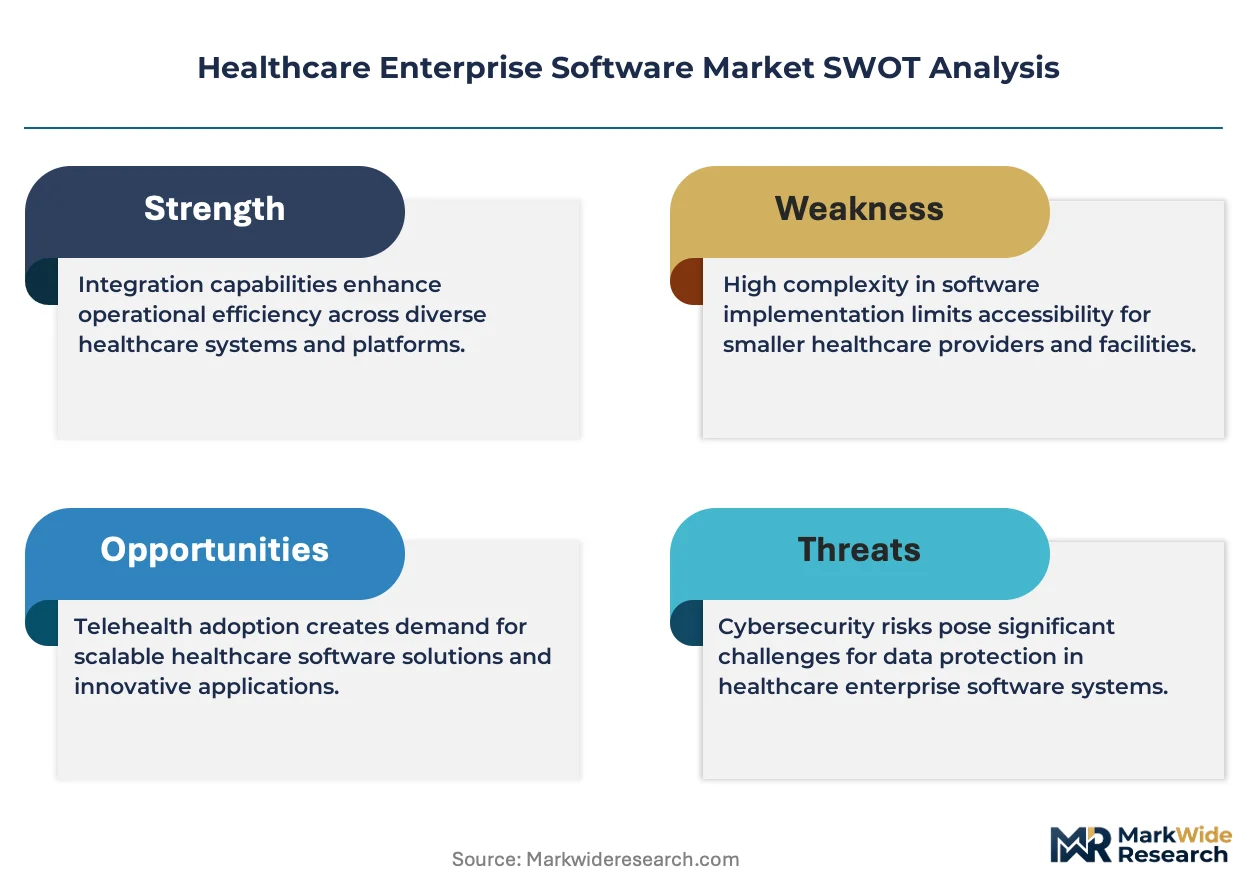
FDA oversight of clinical decision support algorithms, HIPAA security rule enforcement by HHS Office for Civil Rights, and ONC certification requirements under the 21st Century Cures Act collectively elevate compliance costs and barrier to entry. These frameworks compel vendors to maintain continuous audit readiness and interoperability certification, reshaping product roadmaps toward regulatory-first design. Stakeholders must evaluate whether emerging AI modules will require new FDA premarket pathways before committing capital to next-generation platforms.
Market Dynamics
Hospital consolidation into mega-systems is compressing vendor count and mandating unified data architectures that span dozens of care sites under single governance.
Growth Catalysts
- HIPAA Security Rule enforcement:HHS Office for Civil Rights audit expansion is accelerating cloud migration timelines among mid-size hospital networks seeking compliance automation.
- Interoperability mandates:ONC certification requirements under the 21st Century Cures Act are forcing EHR replacement cycles and opening procurement windows for integrated platform vendors.
- Clinical AI module demand:Diagnostic decision support algorithms are attracting capital allocation from academic medical centers pursuing predictive analytics capabilities.
Market Restraints
- Implementation cost structure:Multi-year EHR deployments require substantial clinical workflow redesign and change management investment that strains hospital operating margins.
- Technical debt accumulation:Decades of on-premise server infrastructure and custom interface engines create migration friction that extends cloud transition timelines.
- Regulatory pathway uncertainty:FDA premarket review requirements for clinical decision support algorithms remain undefined, freezing R&D commitment for some vendors.
Strategic Opportunities
- Rural health network penetration:Critical access hospitals and community health centers remain underpenetrated by enterprise-grade platforms, creating white space for cloud-native solutions.
- Revenue cycle automation:Claims optimization and prior authorization workflows represent adjacent expansion vectors for clinical platform vendors with existing provider relationships.
- API-first architectures:HL7 FHIR R4 implementation is enabling third-party application marketplaces that transform vendor business models toward platform economics.
Industry Challenges
- Health informatics talent scarcity:Shortages of clinical informaticists and interface engineers are extending implementation timelines and elevating professional services costs.
- Legacy system integration complexity:Proprietary data formats and undocumented customizations in aging EHR instances require expensive middleware development.
- Continuous certification maintenance:ONC and state-level Medicaid certification cycles demand dedicated compliance teams that smaller vendors struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Enterprise Software Market |
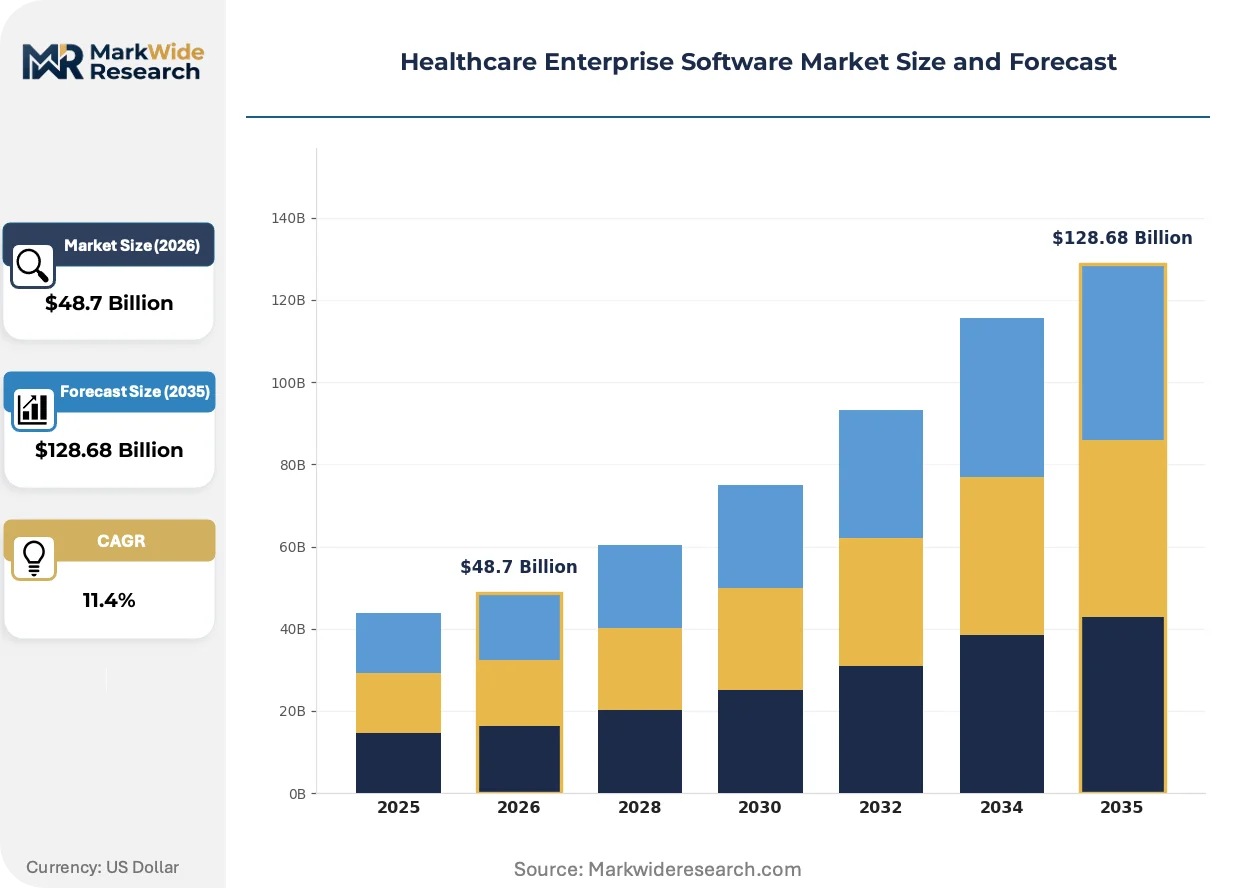
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, EMR, Practice Management, Revenue Cycle Management Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Hospitals, Clinics, Diagnostic Labs, Private Practices Technology: Artificial Intelligence, Machine Learning, Blockchain, Data Analytics |
| Companies Covered | Epic Systems Corporation, Oracle Health, athenahealth, GE HealthCare, Philips Healthcare, Allscripts Healthcare Solutions, NextGen Healthcare, eClinicalWorks, OptumHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Enterprise Software Market Strategic Shifts
Clinical workflow automation is advancing through embedded intelligence that reduces documentation burden and surfaces actionable patient insights at point of care.
Generative AI documentation assistants are supplanting manual charting workflows in emergency departments and ambulatory settings. Health systems in the United States are piloting these tools at scale during 2024 contracting cycles. The technology is compressing physician administrative time and redirecting vendor R&D toward ambient clinical intelligence.
The FDA Software as a Medical Device framework is expanding oversight to clinical decision support algorithms that drive diagnostic or treatment recommendations. This regulatory expansion is elevating quality management system requirements for EHR vendors. Academic medical centers are prioritizing vendors with established FDA premarket submission track records.
Subscription-based platform economics are displacing perpetual license arrangements in hospital procurement negotiations. Integrated delivery networks are consolidating vendor relationships around full-stack clinical and financial solutions. This preference shift concentrates contract value with fewer suppliers and extends average relationship tenures.
Healthcare Enterprise Software Market Segmentation
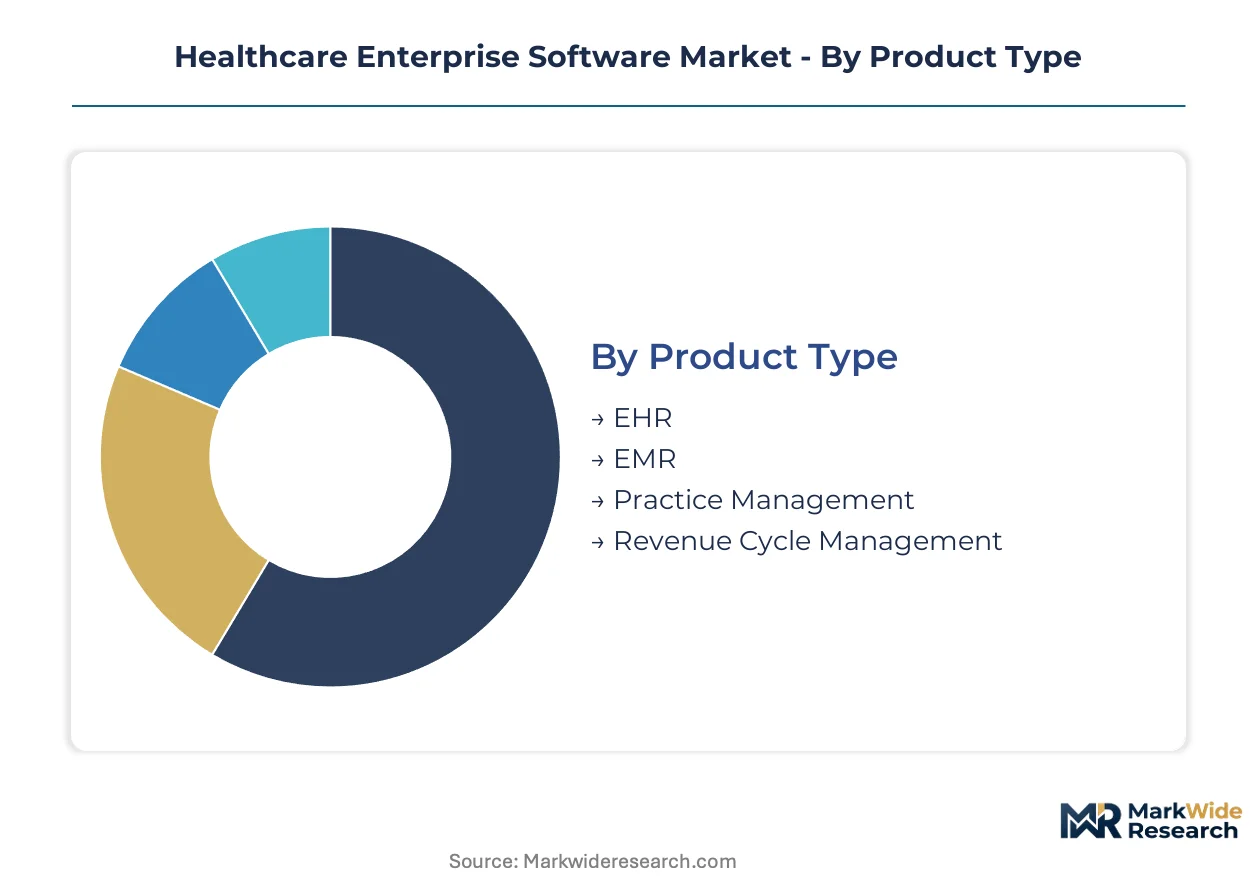
Segmentation in healthcare enterprise software reveals how procurement channels, compliance requirements, and clinical workflows shape vendor positioning. Hospital systems route purchasing through distinct decision-making units for clinical versus financial applications. Understanding these pathways clarifies where platform consolidation opportunities concentrate.
Product Type:
EHR and EMR platforms flow through health system IT procurement committees with multi-year capital cycles, while revenue cycle solutions increasingly route through CFO-led SaaS evaluations.
- EHR:Comprehensive electronic health record systems integrate clinical documentation, order entry, and medication management across inpatient and ambulatory settings. Academic medical centers in the United States drive demand for specialized modules supporting complex specialty workflows. ONC certification requirements under the 21st Century Cures Act mandate continuous interoperability upgrades.
- Revenue Cycle Management:Claims processing, prior authorization, and denial management platforms automate financial workflows from patient registration through payment posting. Large integrated delivery networks prioritize vendors with established clearinghouse relationships and real-time eligibility verification.
- EMR:Electronic medical record systems serve smaller provider organizations with streamlined clinical documentation and basic interoperability capabilities.
- Practice Management:Scheduling, billing, and patient portal solutions target ambulatory practices with lighter technical infrastructure requirements.
By volume, EHR leads hospital procurement pipelines. By growth pace, Revenue Cycle Management is expanding most quickly as providers prioritize margin protection.
Deployment:
Cost tier structures separate capital-intensive on-premise installations from operating-expense SaaS arrangements favored by mid-size health systems.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance burdens and enable automatic security patching demanded by HIPAA enforcement. Hospital networks exiting owned data centers favor this model for disaster recovery and scalability.
- SaaS:Subscription pricing aligns vendor incentives with customer outcomes through continuous feature delivery. Private equity-backed physician groups prefer this model for predictable budgeting and rapid deployment.
- On-Premise:Legacy installations persist in organizations with specialized latency requirements or restrictive data residency policies.
- Hybrid:Split configurations maintain sensitive workloads on-premise while leveraging cloud elasticity for analytics and development environments.
By volume, Cloud-Based deployments dominate new installations. By margin structure, SaaS commands premium recurring revenue multiples.
End User:
Customer type determines implementation complexity, with hospitals requiring enterprise-wide change management versus clinics prioritizing rapid onboarding.
- Hospitals:Inpatient facilities demand integrated platforms spanning emergency departments, surgical suites, and intensive care units with 24/7 uptime requirements. Mega-system consolidation in the United States is compressing vendor counts and mandating unified data architectures.
- Clinics:Outpatient facilities prioritize interoperability with hospital affiliates and streamlined referral workflows. Federally qualified health centers represent underpenetrated demand for cloud-native solutions.
- Diagnostic Labs:High-volume testing operations require bidirectional interfaces with ordering systems and automated result distribution capabilities.
- Private Practices:Solo and small group physicians favor lightweight solutions with minimal IT overhead and network-enabled referral management.
By contract value, Hospitals anchor vendor revenue. By expansion opportunity, Clinics show the steepest adoption trajectory.
Technology:
Maturity stages separate production-grade implementations from experimental pilots, with regulatory clarity determining commercial deployment timelines.
- Artificial Intelligence:Diagnostic decision support and predictive analytics modules attract disproportionate R&D allocation from academic medical centers. FDA premarket pathway uncertainty for clinical algorithms is freezing some vendor commitments.
- Machine Learning:Pattern recognition for sepsis detection, readmission risk stratification, and imaging interpretation is gaining clinical validation. Health systems pilot these tools during annual contracting cycles.
- Data Analytics:Population health dashboards and operational performance metrics support value-based care contracts.
- Blockchain:Distributed ledger applications for credentialing and supply chain traceability remain in proof-of-concept phases.
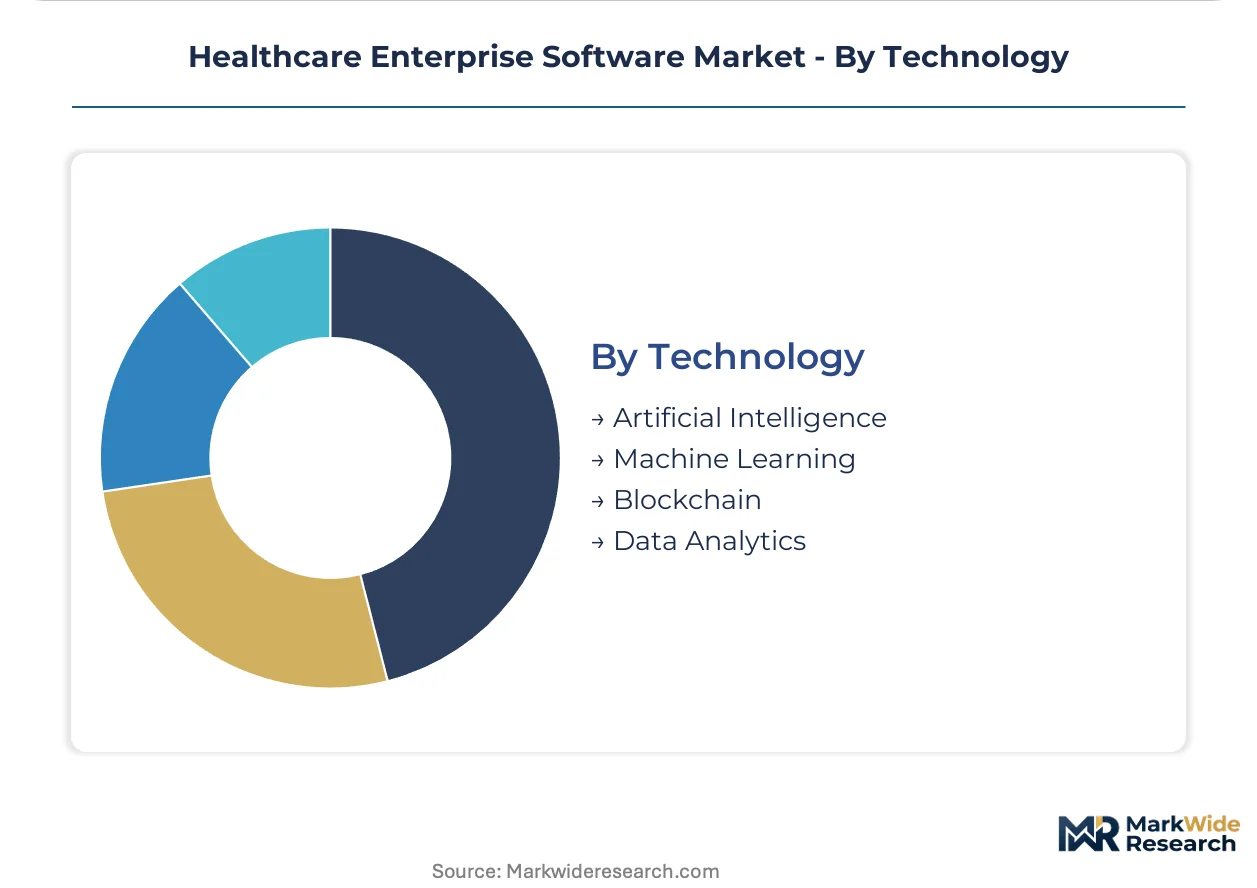
By deployment scale, Data Analytics leads operational implementations. By investment intensity, Artificial Intelligence is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare enterprise software procurement patterns diverge sharply across geographies. United States health systems prioritize integrated clinical-financial platforms under federal interoperability mandates. European providers emphasize GDPR-compliant cloud architectures with national sovereignty requirements. Asian markets concentrate investment in scalable SaaS models for rapidly digitizing hospital networks.
United States
Hospital consolidation into mega-systems drives demand for unified EHR platforms spanning multi-state networks. HIPAA Security Rule enforcement by HHS Office for Civil Rights accelerates cloud migration timelines among mid-size providers. The Boston-Cambridge corridor anchors health informatics talent concentration, with academic medical centers piloting FDA-regulated clinical AI modules.
Germany
Hospital digitization funds under the Hospital Future Act channel investment into interoperable clinical systems. BfArM and DIMDI regulations mandate CE-marked medical device software certification for diagnostic algorithms. The Rhine-Ruhr metropolitan region concentrates EHR implementation activity as university hospitals consolidate procurement around ISO 27001-certified vendors.
United Kingdom
NHS Long Term Plan targets federated data architectures linking acute trusts with primary care networks. NHSX interoperability standards and UK GDPR compliance requirements shape vendor selection criteria. London's health tech cluster attracts cloud-native platform providers targeting integrated care system procurement frameworks.
Japan
Super-aged society demographics elevate demand for predictive analytics and remote patient monitoring integration. PMDA software as medical device guidelines create regulatory pathways for clinical decision support algorithms. Tokyo-Osaka medical corridor hospitals prioritize HL7 FHIR-compliant platforms for cross-institutional data exchange.
India
Ayushman Bharat Digital Mission infrastructure investment expands addressable market for cloud-based hospital information systems. CDSCO medical device rules and MeitY data localization requirements influence vendor compliance strategies. Bangalore-Hyderabad health tech corridor emerges as domestic platform development hub serving Southeast Asian export markets.
Healthcare Enterprise Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in healthcare enterprise software. Epic Systems Corporation and Oracle Health occupy the consolidated upper tier through multi-hospital contract concentration. Mid-scale specialists anchor ambulatory and revenue cycle segments with network-enabled service models. Competitive dynamics center on cloud infrastructure scale and regulatory certification maintenance rather than price-based rivalry.
Among United States-based platform vendors, Epic Systems Corporation, Oracle Health, and athenahealth exemplify three distinct competitive archetypes. Epic Systems Corporation represents deep clinical content specialization through academic medical center penetration. Oracle Health occupies cloud infrastructure leverage positioning for multi-site health system consolidation. athenahealth anchors network-centric SaaS delivery for ambulatory revenue cycle automation. These three vendors collectively illustrate how regulatory compliance scale, interoperability certification depth, and service delivery model differentiation segment competitive positioning in hospital procurement cycles.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| athenahealth |
| GE HealthCare |
| Philips Healthcare |
| Allscripts Healthcare Solutions |
| NextGen Healthcare |
| eClinicalWorks |
| OptumHealth |
| Others |
Value Chain & Pricing Dynamics
Cloud-native infrastructure substitution for on-premise server farms simultaneously redistributes supply geography toward hyperscaler data center regions and compresses pricing economics through subscription standardization. HIPAA Security Rule enforcement by HHS Office for Civil Rights accelerates this displacement, as mid-size hospital networks abandon capital-intensive owned infrastructure for operating-expense SaaS arrangements.
Pricing Analysis
Long-term subscription contracts dominate hospital procurement, with multi-year SaaS agreements displacing perpetual license structures. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center deployments with FDA premarket pathway requirements from community hospital configurations and critical access hospital bundles. Cost compression in the economy tier is intensifying because rural health networks negotiate as aggregated purchasing cooperatives. Federally qualified health centers exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-seat metrics.
Supply Chain Analysis
Health informatics talent scarcity in the Boston-Cambridge corridor creates a chokepoint that extends implementation timelines and elevates professional services costs. Software development draws from India, Ireland, and the United States for engineering capacity, while cloud infrastructure feeds from hyperscaler regions in Virginia, Oregon, and Frankfurt. Single-source vulnerability concentrates in Epic Systems Corporation's proprietary interoperability protocols, which anchor academic medical center ecosystems. Distribution runs through health system IT procurement committees with multi-year capital cycles for EHR platforms and CFO-led SaaS evaluations for revenue cycle solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare enterprise software sits at a platform-economics inflection where HL7 FHIR R4 implementation enables third-party application marketplaces, transforming vendor business models from monolithic suites toward extensible ecosystems.
For Market Incumbents: Shield installed base relationships through continuous ONC certification maintenance and embedded AI module development. Consolidate procurement influence by acquiring revenue cycle specialists with established clearinghouse relationships. Oracle Health and Epic Systems Corporation face emerging cloud-native entrants targeting API-first architectures as the primary threat vector.
For New Entrants and Emerging Players: Lead with ambient clinical intelligence tools that compress physician documentation burden, targeting emergency departments and ambulatory settings where administrative burnout drives technology procurement. Critical access hospitals and community health centers represent the most penetrable geography, with network-enabled referral management as the decisive go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with FDA premarket submission track records and established hospital system relationships. Viability over the coming decade hinges on regulatory certification depth rather than feature breadth. Watch FDA Software as a Medical Device framework expansion for clinical decision support algorithms as the inflection signal determining R&D allocation returns.
| Strategic Initiative | Industry Significance |
|---|---|
| HL7 FHIR R4 Platform Integration | Enables third-party application marketplaces that transform vendor economics toward platform models. |
| FDA Premarket Submission Pathway | Establishes quality management credentials required by academic medical centers piloting clinical AI modules. |
| Hospital System Partnership | Secures multi-year subscription contracts through integrated delivery network consolidation mandates. |
| Revenue Cycle Specialist Acquisition | Captures claims optimization margin pools adjacent to core clinical platform relationships. |
| Ambient Clinical Intelligence Development | Addresses physician administrative burden reduction prioritized in 2024 contracting cycles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, CMS Medicare reimbursement filings, GPO contract repositories, and FDA 510(k) submission records. Interviews with health system CIOs, clinical informaticists, biomedical engineers, and GPO contracts managers inform demand-side validation. SEC 10-K disclosures from Oracle Health and athenahealth parent entities, alongside ONC certification databases, anchor supply-side triangulation through bottom-up and top-down reconciliation.
Segmentation dimensions modeled span deployment architecture, organization scale by bed count, clinical versus financial application vertical, integration complexity tier, and regional HIPAA enforcement intensity. CAGRs derive from annual contracting velocity analysis across academic medical centers, community hospitals, and ambulatory networks. Forecast inputs incorporate cloud migration timeline assumptions and FDA regulatory pathway clarity scenarios.
Underlying assumptions cover interoperability mandate compliance timelines and health informatics labor market elasticity, with deviation risk concentrated in FDA premarket review requirement finalization for clinical decision support algorithms. Practitioners should keep alternative scenarios live as 21st Century Cures Act enforcement priorities and AI module reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Femtech Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market