
 United States Pharmacy Management System Market | 2026-2036
United States Pharmacy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pharmacy Management System Market Analytics
Buyer concentration among hospital networks is pivoting as regional health systems merge pharmacy operations under single enterprise licenses. McKesson Corporation leverages its wholesale infrastructure to bundle distribution with management software, locking in integrated supply chain relationships. Cerner Corporation anchors hospital-centric deployments through EHR-native pharmacy modules that reduce interface complexity. Omnicell Inc. specializes in automated dispensing hardware paired with inventory control solutions, occupying the acute-care automation niche.
A pharmacy management system orchestrates medication dispensing, inventory tracking, prescription validation, and regulatory reporting through software platforms that interface with barcode verification and robotic dispensing hardware. These systems serve primarily to reduce dispensing errors, optimize drug inventory turns, and maintain compliance with controlled-substance tracking requirements. Cloud-based deployment is capturing the fastest expansion as independent pharmacies abandon server maintenance burdens, while hospital pharmacy management commands the deepest margin pools due to complex integration requirements with EHR Integration workflows. Retail pharmacy software remains the most mature segment, though pharmacy chains are now demanding mobile platforms for remote inventory oversight.
FDA DSCSA serialization deadlines and HIPAA privacy rules shape product roadmaps, forcing vendors to embed track-and-trace capabilities and audit-grade access controls as standard features. State boards of pharmacy in Texas, California, and New York impose supplemental reporting requirements that fragment compliance templates across jurisdictions. Stakeholders must monitor whether federal interoperability mandates from the Office of the National Coordinator for Health IT will force open-architecture standards that erode vendor lock-in advantages.
Market Dynamics
Hospital consolidation across the southeastern United States is forcing pharmacy management system vendors to rearchitect enterprise platforms for multi-facility deployments, while FDA DSCSA serialization deadlines compress implementation timelines for track-and-trace infrastructure.
Growth Catalysts
- FDA DSCSA Mandates:The Drug Supply Chain Security Act requires unit-level serialization by 2024, compelling health systems to upgrade pharmacy management infrastructure for automated verification workflows.
- Cloud Migration:Independent pharmacies in Florida and Georgia are abandoning on-premise servers for SaaS deployments, reducing capital barriers and accelerating vendor switching cycles.
- EHR Integration Imperatives:Hospital pharmacy departments demand native interoperability with Cerner and Epic systems to eliminate manual reconciliation between medication orders and dispensing records.
Market Restraints
- Implementation Cost Burden:Mid-sized hospital networks face prohibitive upfront capital requirements for automated dispensing cabinets and barcode verification hardware.
- Vendor Concentration Risk:Wholesale distributors McKesson and AmerisourceBergen control bundled software-distribution contracts, limiting competitive entry for standalone platform vendors.
- Interoperability Friction:Proprietary data formats between competing EHR and pharmacy management systems force expensive custom interface development.
Strategic Opportunities
- Specialty Pharmacy Expansion:Oncology and infusion therapy clinics in Texas and California require temperature-controlled inventory tracking modules that extend platform functionality.
- Mobile Workforce Enablement:Chain pharmacies demand smartphone-based inventory oversight applications for district managers supervising multiple retail locations.
- State-Level Compliance Arbitrage:New York and California supplemental reporting requirements create premium pricing tiers for vendors offering jurisdiction-specific compliance templates.
Industry Challenges
- Pharmacy Informatics Talent Scarcity:Health systems struggle to recruit clinicians with dual competencies in pharmacology and health information technology system administration.
- Legacy System Migration Complexity:Decades-old pharmacy databases in established hospital networks resist clean extraction into modern cloud architectures without data integrity risks.
- Multi-State Licensing Coordination:Telepharmacy platforms must navigate divergent state board of pharmacy regulations governing remote dispensing supervision across practice jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pharmacy Management System Market |
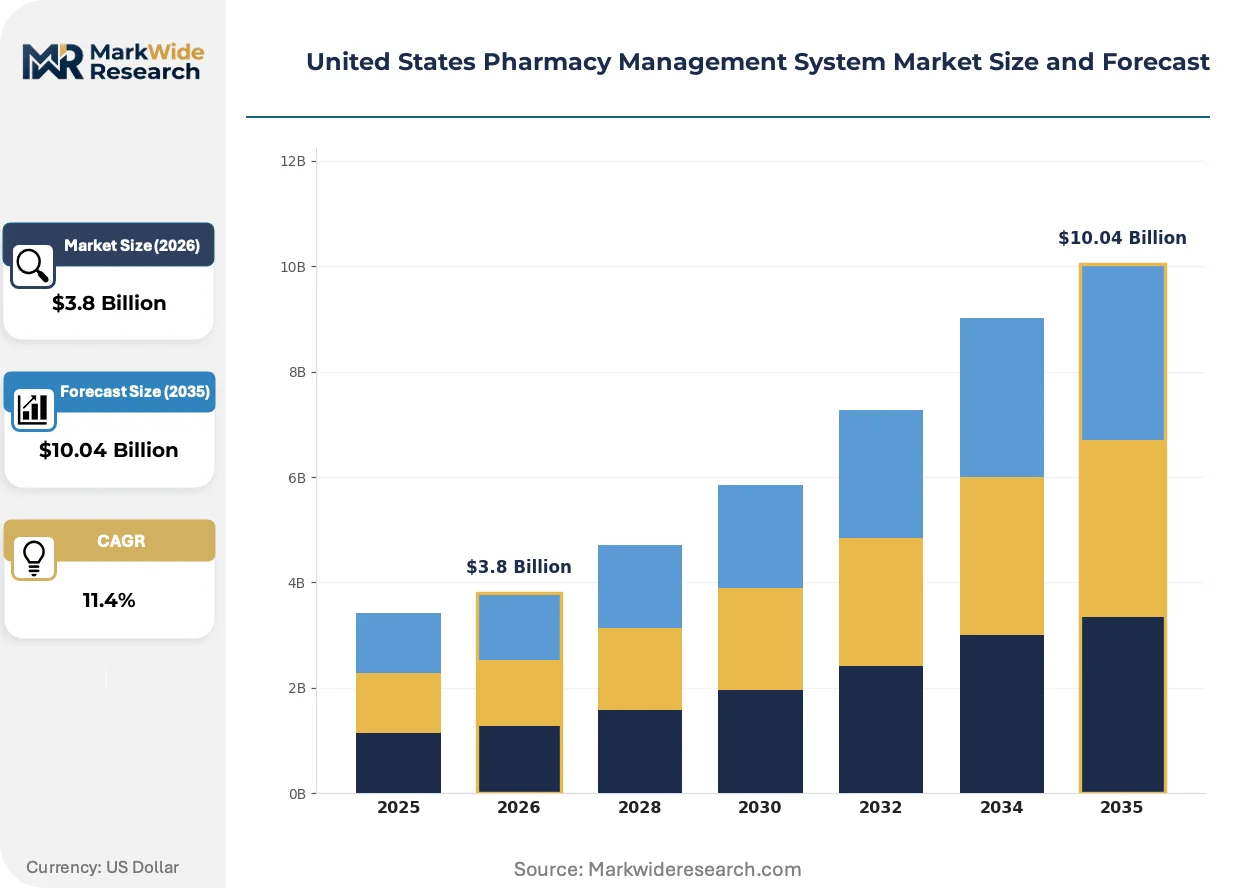
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
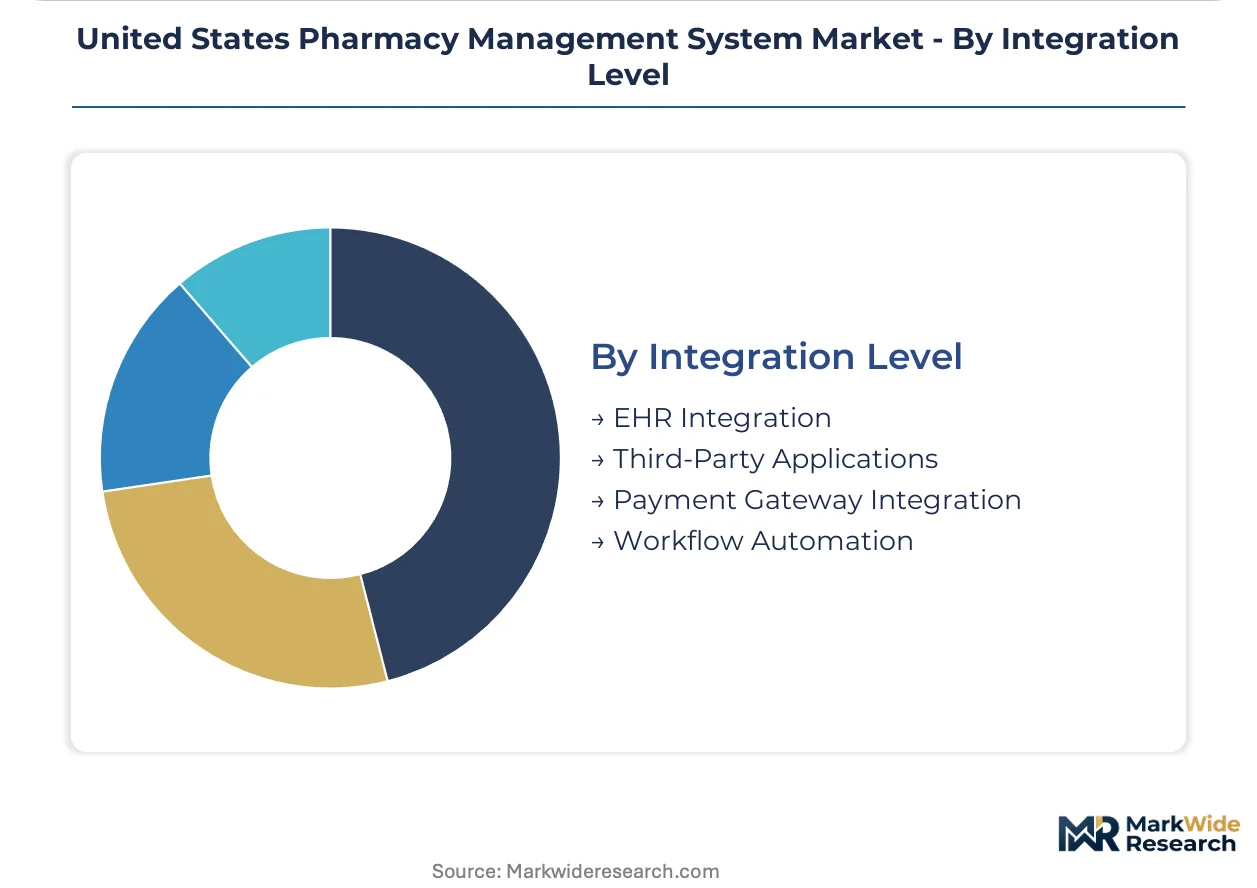
| Segmentation | Product Type: Retail Pharmacy Software, Hospital Pharmacy Management, Prescription Management, Inventory Control Solutions Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Platforms End User: Independent Pharmacies, Hospital Pharmacies, Pharmacy Chains, Long-Term Care Facilities Integration Level: EHR Integration, Third-Party Applications, Payment Gateway Integration, Workflow Automation |
| Companies Covered | GE Healthcare Inc., Allscripts Healthcare Solution Inc., McKesson Corporation, Epicor Software Corporation, Omnicell Inc., Cerner Corporation, Talyst LLC, Datascan, Becton Dickinson and Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pharmacy Management System Market Evolving Landscape
Artificial intelligence is penetrating medication error detection workflows, while regulatory pressure for supply chain transparency accelerates hardware-software convergence in acute care settings.
Robotic dispensing systems equipped with machine vision verification are electrifying hospital pharmacy automation, replacing manual counting and labeling tasks. Large integrated delivery networks in Florida and Georgia are deploying these systems across consolidated pharmacy operations. The technology is electrifying vendor competition around throughput metrics and error-rate guarantees as procurement committees prioritize capital efficiency.
FDA serialization deadlines for the Drug Supply Chain Security Act are forcing wholesale distributors to mandate interoperable track-and-trace modules from their pharmacy management software partners. Hospital pharmacies must demonstrate unit-level pedigree documentation for controlled substances and high-value biologics. Acute-care facilities in Texas are responding by accelerating enterprise platform upgrades ahead of federal enforcement phases.
Consolidated purchasing committees at merged health systems are unbundling pharmacy management decisions from historical EHR vendor relationships. Independent pharmacy directors now evaluate standalone platforms on specialty pharmacy capabilities rather than legacy integration convenience. This behavioral shift is most visible in Georgia, where recent hospital network mergers have created centralized pharmacy oversight functions with autonomous technology procurement authority.
United States Pharmacy Management System Market Segmentation
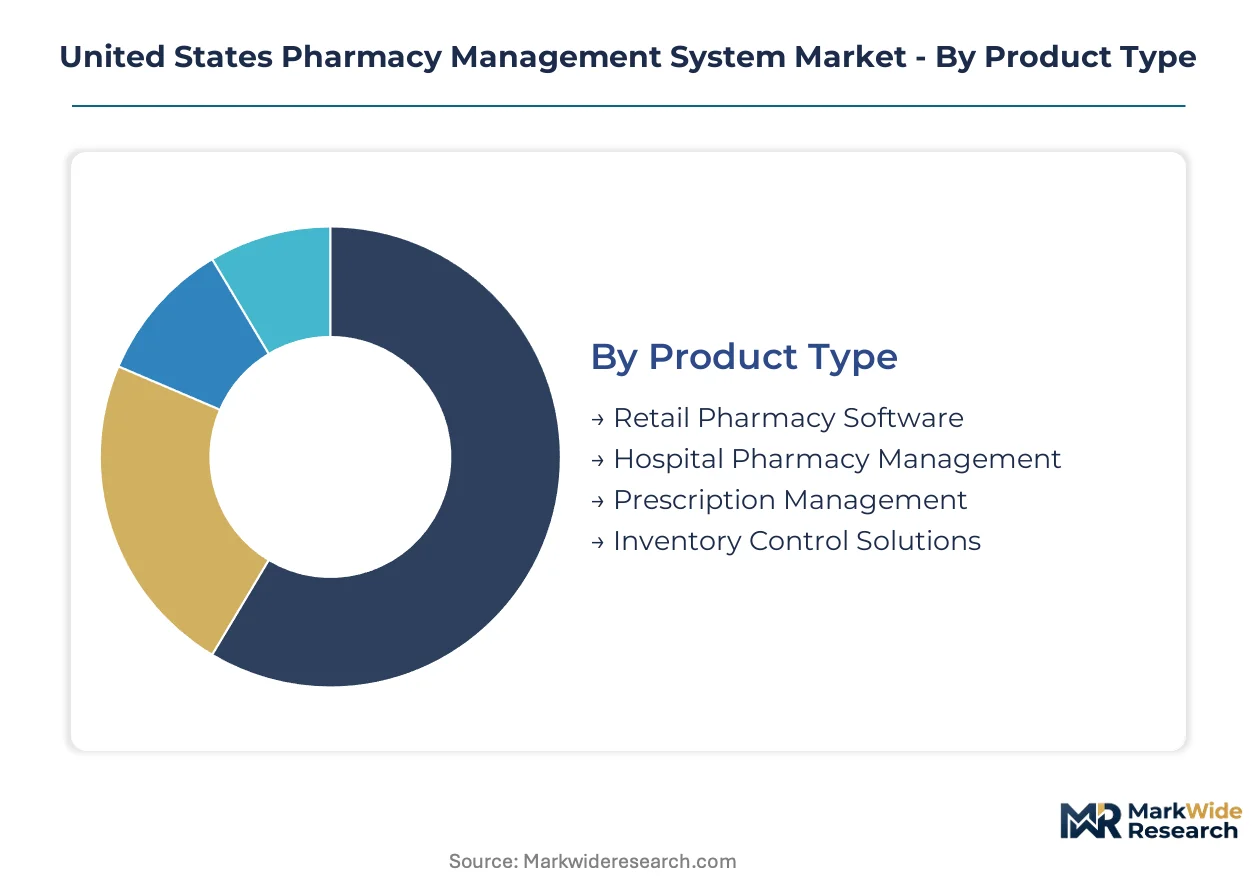
Pharmacy management system procurement patterns diverge sharply across facility types, with upgrade cycles driven by regulatory deadlines rather than organic technology refresh. Vendors must architect modular platforms that accommodate both legacy hospital infrastructure and cloud-native independent pharmacy deployments.
Product Type:
Replacement cycles vary dramatically by product category, with hospital systems facing compressed timelines due to FDA DSCSA mandates while retail software refresh rates follow competitive pressure rather than compliance.
- Hospital Pharmacy Management:Enterprise-grade platforms orchestrate medication dispensing, inventory tracking, and regulatory reporting across acute-care networks. Demand concentrates in southeastern health systems consolidating multi-facility operations under unified licenses, driven by FDA track-and-trace mandates under DSCSA.
- Retail Pharmacy Software:Mature solutions emphasizing prescription processing, insurance adjudication, and customer relationship management. Florida and Georgia independent pharmacies dominate procurement volumes, constrained by wholesale distributor bundling contracts that limit vendor switching flexibility.
- Prescription Management:Workflow modules for order validation, drug interaction screening, and prescriber authentication.
- Inventory Control Solutions:Stock optimization tools with barcode verification and automated reorder triggers.
Hospital pharmacy management sits at the top of the volume ranking, with inventory control solutions climbing the fastest as automation hardware converges with software platforms.
Deployment:
Cost tier structures separate capital-intensive on-premise installations from subscription-based cloud alternatives, with hybrid architectures capturing mid-market hospitals seeking phased migration paths.
- Cloud-Based:SaaS delivery eliminates server maintenance burdens and accelerates feature deployment through vendor-managed updates. Independent pharmacies in Florida and Georgia lead adoption, attracted by reduced upfront capital requirements and faster implementation timelines.
- Mobile Platforms:Smartphone applications enabling remote inventory oversight and district-level pharmacy chain management. Texas and California pharmacy chains drive demand, responding to workforce mobility requirements for multi-location supervision.
- On-Premises:Server-based installations retaining data sovereignty for security-sensitive hospital networks.
- Hybrid Solutions:Mixed architectures preserving critical functions locally while offloading analytics to cloud infrastructure.
Cloud-based deployment commands the steepest expansion trajectory, though on-premise retains dominance in hospital networks with legacy infrastructure investments.
End User:
Customer type segmentation reveals divergent purchasing authority patterns, with consolidated health systems centralizing procurement while independent operators retain individual decision autonomy.
- Pharmacy Chains:Multi-location retail networks requiring standardized platforms across hundreds of sites. Georgia and Florida regional chains are consolidating vendor relationships, driven by enterprise purchasing committees seeking volume-based pricing leverage.
- Independent Pharmacies:Single-location operators prioritizing affordability and rapid deployment. SaaS migration accelerates among Florida independents abandoning server maintenance, constrained by limited technical staffing for complex integrations.
- Hospital Pharmacies:Acute-care and integrated delivery network pharmacy departments with complex EHR interoperability requirements.
- Long-Term Care Facilities:Skilled nursing and assisted living pharmacies with specialized medication administration tracking needs.
Hospital pharmacies generate the deepest margin pools, with pharmacy chains gaining share fastest as enterprise standardization initiatives accelerate.
Integration Level:
Application architecture choices determine competitive positioning, with native EHR interoperability commanding premium pricing against modular third-party alternatives.
- EHR Integration:Native connectivity with Cerner and Epic systems eliminating manual reconciliation between medication orders and dispensing records. Hospital networks in Texas and Georgia prioritize this capability, driven by clinical workflow efficiency mandates and error reduction targets.
- Workflow Automation:Robotic process automation for prescription routing, prior authorization, and inventory replenishment. Large southeastern health systems deploy these modules across consolidated pharmacy operations, responding to labor cost pressures and throughput optimization requirements.
- Third-Party Applications:API-based connectivity with specialty pharmacy, compounding, and clinical decision support tools.
- Payment Gateway Integration:Embedded insurance adjudication and patient payment processing capabilities.
EHR integration captures the highest priority ranking among hospital purchasers, with workflow automation expanding most quickly as robotic dispensing hardware proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Canada in pharmacy automation investment intensity, while Mexico's retail pharmacy digitization lags both neighbors by a significant margin. Regional procurement patterns diverge sharply between hospital-centric health systems and independent retail operators.
Southeastern United States
Florida and Georgia health systems are consolidating pharmacy operations under unified enterprise licenses, driving demand for multi-facility management platforms. FDA DSCSA track-and-trace mandates compress implementation timelines for automated verification workflows. Atlanta and Miami metropolitan clusters anchor the region's acute-care automation investments.
Texas
Oncology and infusion therapy clinics in Houston and Dallas require temperature-controlled inventory tracking modules for specialty pharmacy expansion. State board of pharmacy regulations impose supplemental reporting requirements beyond federal baselines. The Texas Medical Center in Houston represents the nation's largest concentration of automated dispensing cabinet deployments.
California
Supplemental state-level compliance requirements create premium pricing tiers for vendors offering jurisdiction-specific reporting templates. Northern California integrated delivery networks prioritize EHR-native pharmacy modules that reduce interface complexity. The Los Angeles basin concentrates retail chain demand for mobile workforce enablement platforms.
New York Metro
Hospital networks in the tristate area face compressed upgrade cycles due to overlapping federal and state regulatory deadlines. The region's pharmacy informatics talent scarcity forces health systems to outsource system administration to managed service providers. Manhattan and Long Island anchor enterprise platform procurement for consolidated health systems.
United States Pharmacy Management System Market Competitive Landscape
Southeastern health systems anchor one tier of demand concentration; West Coast specialty pharmacy specialists hold differentiated positions in oncology and infusion segments. The vendor structure fragments across wholesale distributor bundling arrangements, EHR-native module providers, and standalone automation hardware specialists. Three archetypes dominate: wholesale-integrated platforms, EHR-embedded solutions, and acute-care automation hardware bundlers. Competitive moves center on unbundling procurement decisions from legacy EHR relationships and consolidating multi-facility enterprise licenses.
Within the wholesale-integrated tier, McKesson Corporation anchors bundled software-distribution contracts that lock in supply chain relationships. Cerner Corporation occupies the EHR-native position, representing hospital-centric deployments that reduce interface complexity through embedded pharmacy modules. Omnicell Inc. exemplifies the acute-care automation archetype, specializing in automated dispensing hardware paired with inventory control solutions for consolidated health system operations.
| Leading Market Players |
|---|
| GE Healthcare Inc. |
| Allscripts Healthcare Solution Inc. |
| McKesson Corporation |
| Epicor Software Corporation |
| Omnicell Inc. |
| Cerner Corporation |
| Talyst LLC |
| Datascan |
| Becton Dickinson and Co. |
| Others |
Value Network & Pricing Analysis
FDA DSCSA serialization mandates gate qualified supply access for pharmacy management system vendors, with compliance-certified platforms commanding premium-tier pricing while non-compliant alternatives face exclusion from hospital procurement shortlists.
Pricing Analysis
Capacity additions in cloud infrastructure across Texas and California are reshaping price floors for SaaS-delivered pharmacy platforms, compressing margins for legacy on-premise vendors. Three-tier pricing structure across premium, standard, and economy levels separates EHR-native enterprise deployments from modular third-party alternatives and basic retail prescription processing. Price differentiation rests on certification grade and customization level, with DSCSA-compliant modules extracting premiums. Cost compression in the independent pharmacy tier is intensifying because wholesale distributor bundling limits vendor switching. Mid-sized hospital networks demonstrate highest price sensitivity due to capital constraints for automated dispensing hardware.
Supply Chain Analysis
Freight and logistics costs for automated dispensing cabinets and robotic hardware concentrate manufacturing dependencies in the United States, Mexico, and Germany. Component sourcing draws from semiconductor foundries in Taiwan, precision motors from Japan, and steel enclosures from domestic fabricators. Single-source vulnerability around machine vision sensors creates procurement risk for hardware-integrated platforms. Distribution runs through wholesale distributor networks that bundle software licensing with pharmaceutical supply contracts, locking hospital systems into vertically integrated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States pharmacy management system procurement has shifted toward premium specifications as FDA DSCSA deadlines eliminate non-compliant vendors from hospital shortlists, making this a late-cycle quality story where certification investments determine competitive survival.
For Market Incumbents: Deepen EHR-native integration capabilities to defend against unbundling trends as consolidated health systems centralize pharmacy procurement authority outside legacy vendor relationships. Expand automated dispensing hardware production capacity in southeastern manufacturing clusters to capture multi-facility enterprise deployments. Certification investment in state-specific compliance modules represents the critical lever for premium pricing retention. For New Entrants and Emerging Players: AI-powered medication error detection offers a technology-first wedge into hospital pharmacy departments seeking differentiated automation beyond incumbent robotic dispensing. Specialty pharmacy temperature-controlled inventory tracking in Texas and California oncology clinics represents the most penetrable white-space segment. SaaS-native deployment with rapid implementation timelines provides the essential go-to-market angle against legacy on-premise incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmacy software specialists because hospital consolidation across Florida and Georgia is fragmenting procurement decisions and creating acquisition targets with captive customer bases. Platform consolidation plays targeting SaaS-native vendors with DSCSA-compliant modules demonstrate strongest long-term viability. Watch FDA enforcement phase transitions as the signal indicating pricing power inflection for compliance-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Epic and Cerner connectivity eliminates manual reconciliation for hospital pharmacy workflows. |
| Acquisition of Specialist Firm | Specialty pharmacy module vendors in Texas oncology segments extend temperature-controlled tracking capabilities. |
| Strategic Partnership | Wholesale distributor alliances with McKesson and AmerisourceBergen lock in bundled software-distribution relationships. |
| Geographic Expansion | Southeastern health system consolidation in Florida and Georgia demands multi-facility enterprise license architectures. |
| Product Launch | Mobile workforce applications for Georgia and Florida pharmacy chains enable remote district-level inventory oversight. |
Research Methodology
Coverage spans the southeastern United States, Texas, California, and the New York metropolitan area, with primary inputs from each region combined with secondary validation. Interviews with hospital pharmacy directors, health system procurement committees, pharmacy informatics specialists, and wholesale distributor account managers anchored demand-side intelligence. Secondary sources included FDA DSCSA guidance documents, state board of pharmacy regulations, hospital procurement databases, and GPO contract filings. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue segmentation.
Rate-of-change decomposition across the analysis window separated volume expansion from pricing dynamics and mix shifts toward premium EHR-integrated deployments. Segmentation dimensions modeled encompass deployment model, facility type, integration complexity, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for automation hardware adoption and S-curve penetration for cloud migration. Forecast inputs incorporated FDA enforcement phase timelines and hospital merger completion schedules.
The model holds under continued DSCSA compliance deadlines and stable hospital consolidation velocity; deviation in federal interoperability mandates or wholesale distributor bundling enforcement would shift competitive dynamics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Patient Access Solutions Market