
 ECG Management Systems Market | 2026-2036
ECG Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
ECG Management Systems Market Analysis
Cloud-based subscription licensing is realigning how ECG management capabilities reach end users, shifting capital expenditure to recurring operational budgets across hospital networks. GE Healthcare leverages its installed base of diagnostic hardware to extend software attach rates, while Philips Healthcare anchors its position through integrated informatics platforms that span acute and ambulatory settings. Nihon Kohden Corporation specializes in high-fidelity ECG acquisition devices that compete on signal precision in critical care environments.
An ECG management system comprises hardware and software infrastructure for acquiring, storing, analyzing, and distributing electrocardiographic data, typically supporting sampling rates of 500–1000 Hz with 12-lead standard configurations to enable diagnostic-grade rhythm and morphology assessment. The primary commercial purpose centers on streamlining cardiac diagnostic workflows while ensuring traceable, audit-ready records for clinical decision support and reimbursement documentation. Holter monitors and event monitors represent mature hardware segments where margin pools have compressed, whereas cloud-based solutions and wearable devices constitute the fastest-expanding technology categories as ambulatory monitoring extends beyond traditional clinical boundaries. Remote patient monitoring as an end-user segment is attracting disproportionate investment as payers restructure reimbursement around episodic and longitudinal cardiac surveillance.
The FDA's software-as-medical-device framework and HIPAA security rule collectively shape product development roadmaps, mandating algorithm transparency and encrypted data transmission for systems handling diagnostic interpretations. FDA premarket notification requirements for AI-enabled ECG classifiers are lengthening development cycles but simultaneously raising barriers against unvalidated entrants. Stakeholders must monitor evolving FDA guidance on continuous learning algorithms, where adaptive ECG models risk regulatory recategorization upon each substantive update.
Market Dynamics
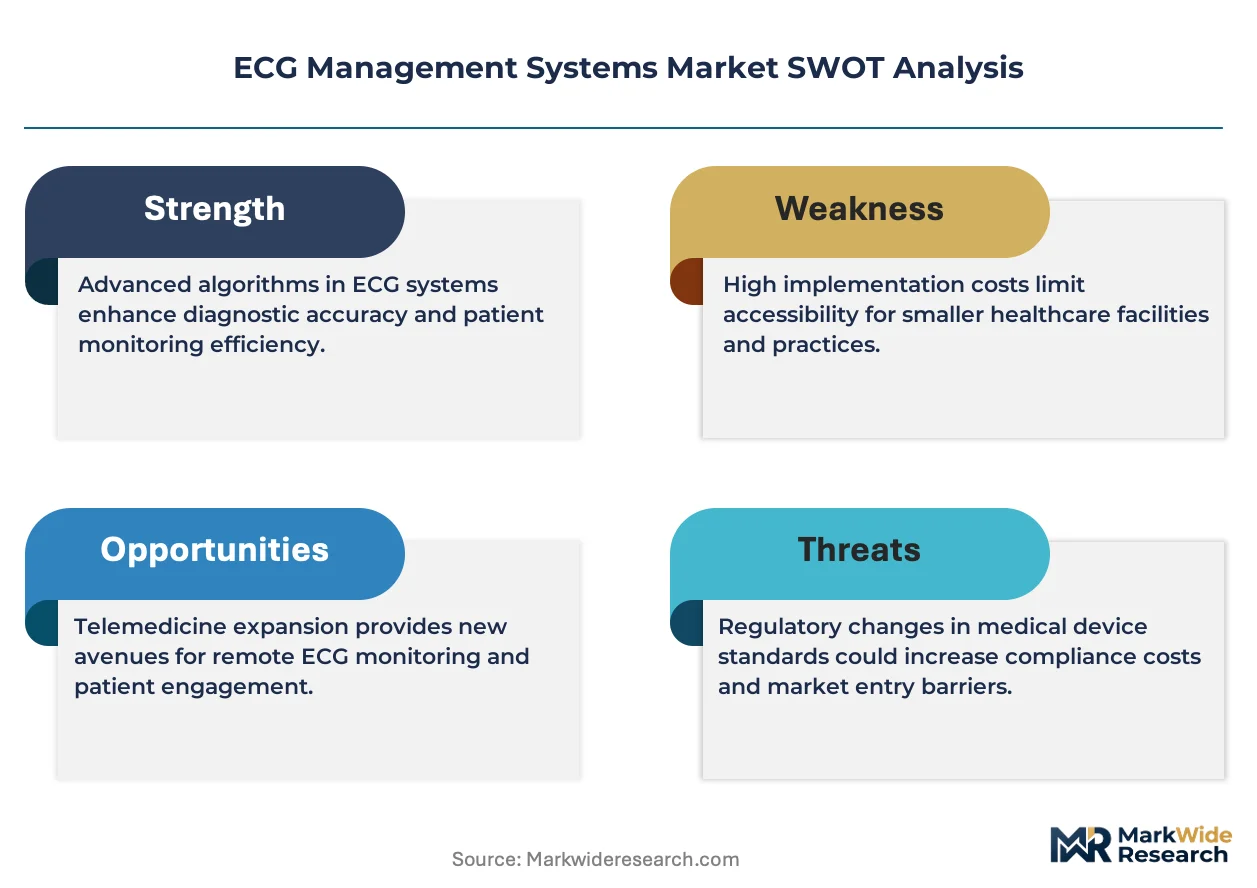
Cloud-based subscription licensing is compressing traditional capital expenditure cycles while FDA software-as-medical-device guidance forces algorithm transparency mandates that lengthen validation timelines for AI-enabled ECG classifiers.
Growth Catalysts
- HIPAA Security Rule encryption mandates:Healthcare networks accelerate procurement of cloud-native ECG platforms that embed end-to-end data protection as a default architectural feature.
- Remote patient monitoring reimbursement restructuring:Payers in the United States now reimburse longitudinal cardiac surveillance, pulling ambulatory monitoring beyond hospital walls into home-based settings.
- Health system consolidation waves:Enterprise-wide ECG data consolidation projects across merged hospital networks create demand for interoperable platforms spanning acute and ambulatory environments.
Market Restraints
- Semiconductor supply concentration:High-fidelity analog-to-digital converters for 500–1000 Hz ECG acquisition face sourcing bottlenecks concentrated in East Asian foundry capacity.
- FDA premarket notification timelines:AI-enabled ECG classifiers encounter extended 510(k) review cycles that compress development runway for algorithm-driven diagnostic platforms.
- Legacy hardware margin compression:Holter monitors and event recorders face commoditization pressure as hardware differentiation erodes against software-centric value propositions.
Strategic Opportunities
- Underpenetrated cardiology clinics in India:Diagnostic infrastructure gaps in tier-2 and tier-3 cities create first-mover positioning for cloud-delivered ECG interpretation services.
- Wearable ECG convergence with consumer electronics:Integration of single-lead ECG sensors into smartwatches and fitness bands opens ambulatory monitoring to non-clinical user bases.
- EU MDR cybersecurity annex requirements:Stricter conformity assessment pathways for networked medical devices favor vendors with pre-validated secure-by-design architectures.
Industry Challenges
- Interoperability engineering talent scarcity:Health Level Seven and DICOM integration specialists command premium compensation as health systems demand seamless EHR connectivity.
- Continuous learning algorithm recertification:Adaptive ECG models risk FDA recategorization upon each substantive update, forcing governance frameworks that freeze model improvement cycles.
- Legacy on-premise system migration complexity:Decades of siloed ECG archives in proprietary formats resist standardized extraction without costly manual curation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Management Systems Market |
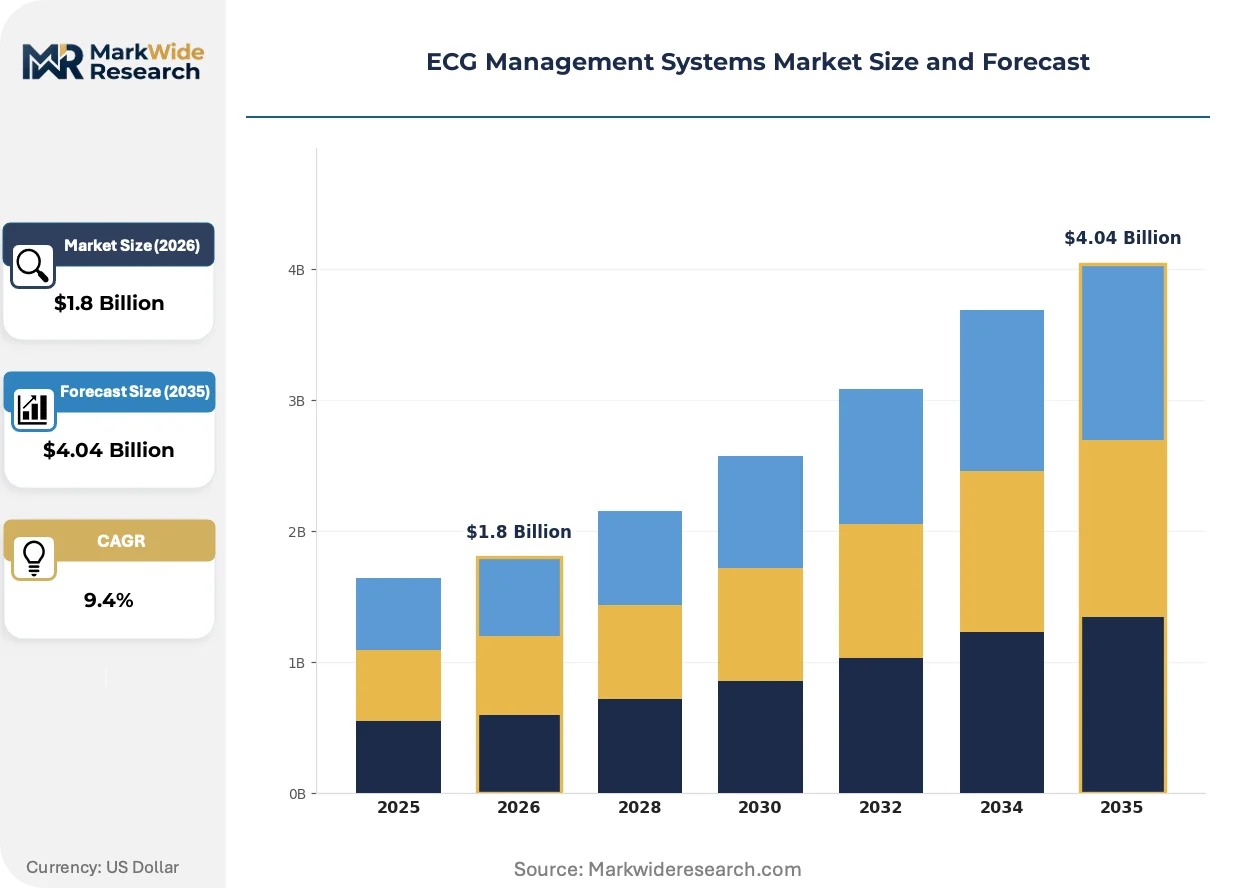
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Stress Test Systems, Event Monitors, Cardiac Rhythm Management End User: Hospitals, Cardiology Clinics, Diagnostic Centers, Remote Patient Monitoring Technology: Wireless, Cloud-based Solutions, Wearable Devices, ECG Sensors Application: Arrhythmia Detection, Cardiac Rehabilitation, Remote Monitoring, Diagnostic Testing |
| Companies Covered | GE Healthcare, Philips Healthcare, Nihon Kohden Corporation, Schiller AG, Mindray Medical, Hill-Rom Holdings, Inc., CompuMed, Inc., McKesson Corporation, Fukuda Denshi Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Management Systems Market Emerging Trajectories
Algorithmic interpretation and decentralized acquisition architectures are redistributing diagnostic authority from centralized cardiology departments toward point-of-care and patient-operated endpoints.
Artificial intelligence-based ECG interpretation is expanding into emergency department triage workflows and primary care screening protocols. Rural health systems and urgent care chains adopt FDA-cleared classifiers to reduce cardiology referral bottlenecks. This diffusion is compressing the traditional specialist gatekeeper role while elevating software licensing revenue above hardware replacement cycles.
REACH chemical substance restrictions and EU MDR cybersecurity annexes are forcing component-level material disclosures and secure development lifecycle documentation for ECG devices sold in European markets. Manufacturers must now trace conflict minerals in circuit boards and validate encryption protocols through notified body assessment. High-compliance vendors are capturing hospital procurement preference as liability frameworks tighten.
Subscription-based platform licensing is displacing perpetual software ownership across integrated delivery networks. Hospital procurement departments favor operational expenditure models that align ECG management costs with utilization volume rather than capital depreciation schedules. This shift is most visible in United States health systems undergoing Medicare Advantage risk-contract transitions, where technology spend flexibility supports value-based care infrastructure investments.
ECG Management Systems Market Segmentation
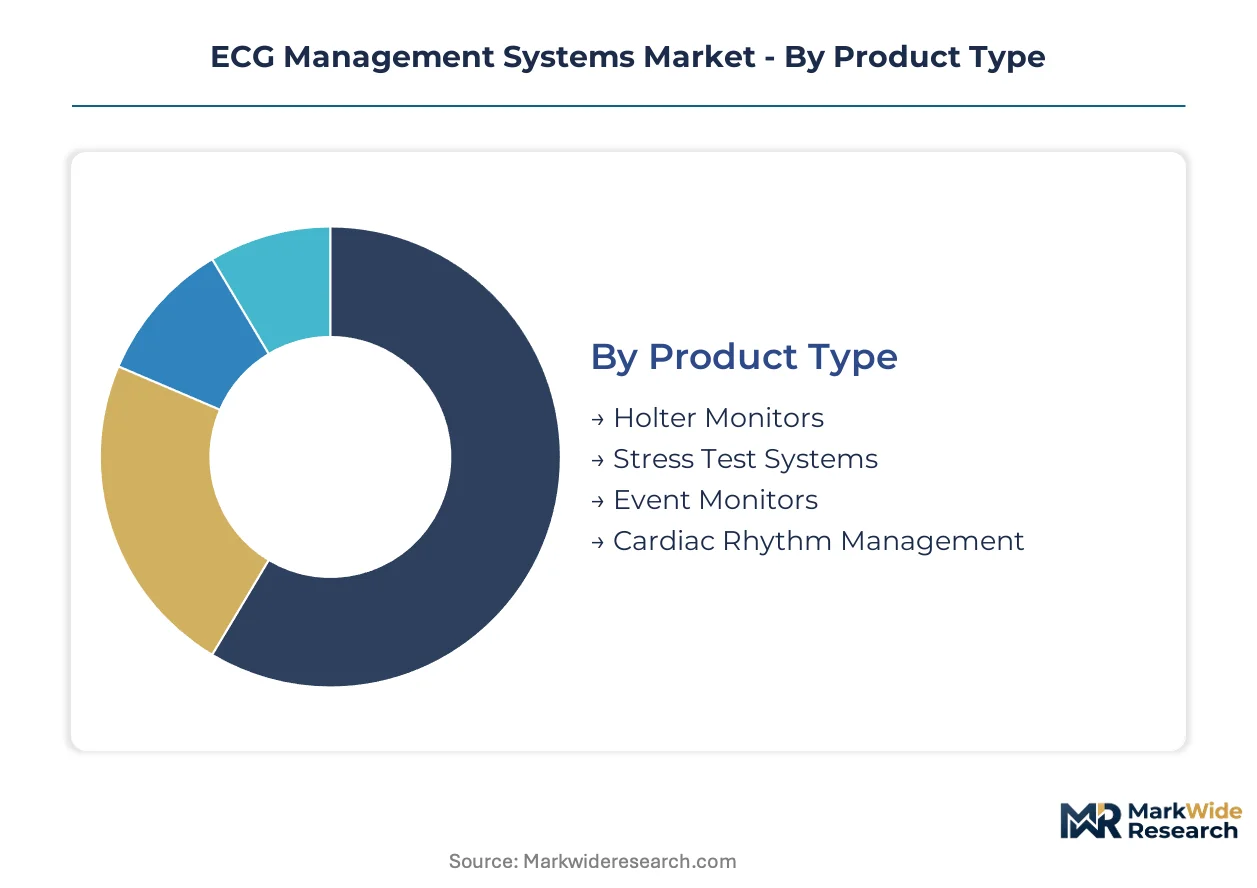
ECG management systems fragment across hardware maturity curves and software deployment models, with cloud-native architectures displacing capital-intensive equipment purchases. Understanding segment boundaries clarifies where margin pools concentrate versus where commoditization pressures intensify.
Product Type:
Holter monitors and stress test systems anchor revenue concentration through established hospital procurement channels, while event monitors and cardiac rhythm management systems diverge on portability versus implantable complexity.
- Holter Monitors:Portable 24–48 hour ambulatory recorders sample at 500–1000 Hz with 12-lead configurations, capturing transient arrhythmias outside clinical settings. Demand clusters in United States diagnostic centers where Medicare reimbursement codes support extended monitoring protocols.
- Stress Test Systems:Integrated treadmill-ECG platforms combine exercise physiology with real-time ST-segment analysis for ischemia detection. Cardiology clinics in Germany and Japan prioritize these systems for pre-surgical cardiac clearance workflows.
- Event Monitors:Patient-activated or auto-triggered devices record symptomatic episodes across weeks-long wear periods.
- Cardiac Rhythm Management:Implantable pacemakers and defibrillators with telemetric ECG transmission capabilities.
Mature deployment sits with Holter Monitors. Newer deployment is concentrated in Cardiac Rhythm Management.
End User:
Hospital networks command procurement volume through enterprise-wide standardization mandates, whereas remote patient monitoring represents the steepest expansion trajectory as reimbursement shifts toward longitudinal care models.
- Hospitals:Acute care facilities require centralized ECG data repositories with HL7 FHIR interoperability for emergency department triage and inpatient telemetry. United States health system consolidation is forcing multi-hospital network deployments across merged entities.
- Remote Patient Monitoring:Home-based cardiac surveillance leverages cellular-connected wearables and cloud analytics platforms. CMS reimbursement restructuring in the United States now covers RPM for chronic heart failure, accelerating vendor investment in patient-facing dashboards.
- Cardiology Clinics:Outpatient specialty practices seeking cloud-based subscription models to avoid capital expenditure.
- Diagnostic Centers:Independent testing facilities processing high-volume ECG interpretations for referring physicians.
Volume procurement dominates Hospitals. Margin expansion is fastest in Remote Patient Monitoring.
Technology:
Cloud-based solutions and wearable devices are climbing the fastest as software-centric value propositions displace hardware differentiation, while wireless transmission protocols and discrete ECG sensors serve as enabling infrastructure layers.
- Cloud-based Solutions:Subscription platforms aggregate multi-site ECG data with automated algorithmic interpretation and EHR integration. FDA software-as-medical-device guidance is lengthening validation timelines for AI-enabled classifiers deployed across United States health systems.
- Wearable Devices:Consumer-grade smartwatches with single-lead ECG sensors extend monitoring to non-clinical populations. Apple and Samsung device penetration is creating de facto screening infrastructure that cardiology practices must reconcile with diagnostic workflows.
- Wireless:Bluetooth and cellular transmission protocols enabling real-time data relay from acquisition devices to analysis platforms.
- ECG Sensors:Dry electrode and capacitive sensing technologies reducing skin preparation requirements.
Regulatory scrutiny concentrates on Cloud-based Solutions. Consumer electronics integration is accelerating fastest in Wearable Devices.
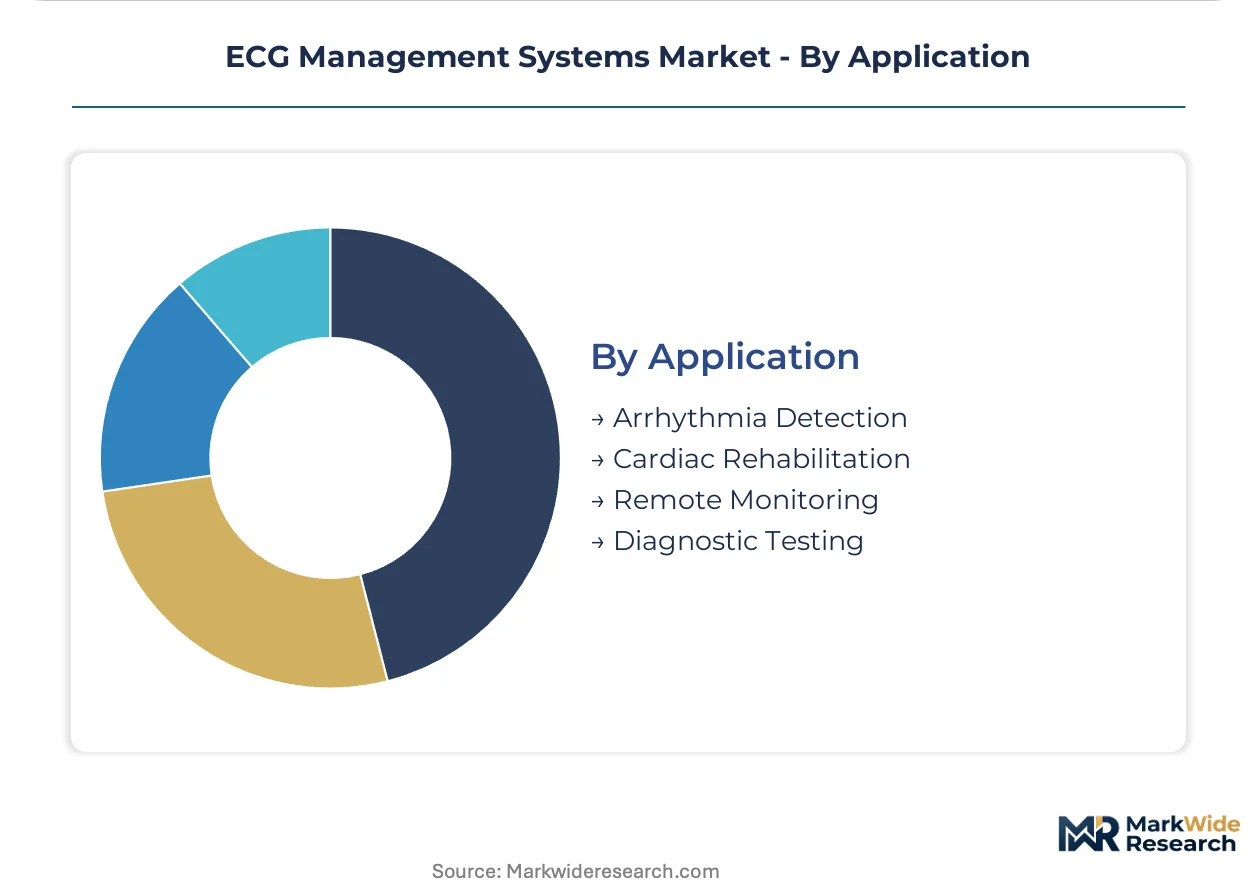
Application:
Arrhythmia detection commands the largest addressable need state, while remote monitoring applications are gaining share fastest as care delivery decentralizes beyond traditional clinical boundaries.
- Arrhythmia Detection:Algorithmic identification of atrial fibrillation, ventricular tachycardia, and conduction abnormalities from rhythm strip analysis. Emergency departments in the United States and France are deploying FDA-cleared and CE-marked AI classifiers to reduce cardiology consultation bottlenecks.
- Remote Monitoring:Longitudinal cardiac surveillance spanning implantable device telemetry and patient-operated wearables. United Kingdom NHS long-term plan targets heart failure mortality reduction through community-based RPM deployment.
- Cardiac Rehabilitation:Exercise prescription and risk stratification for post-MI and post-surgical patients.
- Diagnostic Testing:Resting 12-lead ECG acquisition for acute chest pain and routine screening protocols.
Established reimbursement supports Arrhythmia Detection. Care model innovation is concentrated in Remote Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors enterprise ECG data consolidation activity as Massachusetts General Hospital and Brigham and Women's Hospital merge diagnostic infrastructure under unified cloud platforms.
United States
Medicare Advantage risk-contract transitions pull ECG management spending toward operational expenditure models. FDA software-as-medical-device guidance forces algorithm transparency for AI-enabled classifiers deployed across Cleveland Clinic and Mayo Clinic networks. The Research Triangle in North Carolina concentrates interoperability engineering talent for HL7 FHIR integration projects.
Germany
Cardiology clinics in Bavaria and Baden-Württemberg prioritize integrated stress test systems for pre-surgical cardiac clearance workflows. EU MDR cybersecurity annex requirements mandate secure-by-design validation through notified body assessment. Berlin's Charité university hospital network drives enterprise-wide ECG archive migration from proprietary legacy formats.
Japan
Super-aging demographics expand demand for home-based cardiac telemetry in Tokyo and Osaka metropolitan corridors. METI medical device reimbursement frameworks favor high-fidelity signal acquisition systems for critical care environments. Nagoya's medical device manufacturing cluster concentrates precision analog-to-digital converter sourcing for 500–1000 Hz sampling rates.
India
Tier-2 and tier-3 cities present diagnostic infrastructure gaps for cloud-delivered ECG interpretation services. CDSCO medical device registration pathways are streamlining for software-as-medical-device platforms. Bangalore's health technology corridor attracts venture investment in ambulatory monitoring platforms targeting cardiology clinic networks.
United Kingdom
NHS long-term plan targets heart failure mortality reduction through community-based remote patient monitoring deployment. Care Quality Commission oversight mandates encrypted data transmission for diagnostic-grade rhythm analysis. London's Imperial College Health Partners consortium pilots AI-enabled ECG classifiers in emergency department triage workflows.
ECG Management Systems Market Vendor Landscape
Capital-heavy diagnostic hardware producers compete with asset-light software platform designers for ECG management revenue pools. Market structure tilts toward consolidated enterprise vendors serving integrated delivery networks alongside specialized component suppliers. Three archetypes dominate: diversified medtech conglomerates leveraging installed hardware bases, pure-play informatics vendors anchoring cloud-native workflows, and precision acquisition device specialists competing on signal fidelity. Competitive moves center on strategic partnerships for EHR interoperability and portfolio diversification into wearable form factors.
Among diversified conglomerates, GE Healthcare and Philips Healthcare exemplify hardware-to-software extension strategies, while Nihon Kohden Corporation occupies a position within the precision acquisition specialist tier. These three entities represent contrasting pathways for capturing ECG management value: GE Healthcare through diagnostic equipment attach rates, Philips Healthcare through integrated informatics spanning acute and ambulatory settings, and Nihon Kohden Corporation through critical care signal precision.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden Corporation |
| Schiller AG |
| Mindray Medical |
| Hill-Rom Holdings, Inc. |
| CompuMed, Inc. |
| McKesson Corporation |
| Fukuda Denshi Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Cloud-native software deployment is compressing capital expenditure cycles while concentrating procurement power among integrated delivery networks that negotiate enterprise-wide subscription terms. This shift simultaneously reduces per-unit hardware margins and elevates pricing leverage for vendors with validated algorithmic interpretation capabilities.
Pricing Analysis
Outcome-linked subscription tiers anchor pricing structures, with United States health systems paying premium rates for FDA-cleared AI classifiers that demonstrate reduced cardiology consultation bottlenecks. Price differentiation separates cloud-native platforms with embedded HIPAA encryption from on-premise legacy installations requiring costly security retrofits. Pricing pressure stems from consumer electronics manufacturers bundling single-lead ECG sensors at negligible incremental cost. Hospital procurement committees exhibit highest price sensitivity, while critical care facilities prioritize signal fidelity over cost optimization.
Supply Chain Analysis
High-fidelity analog-to-digital converter supply rests on Japanese and Taiwanese semiconductor foundries specializing in medical-grade precision components. Raw material dependencies span conflict-mineral-laden circuit boards, lithium-ion cells for wearable power systems, and biocompatible polymers for electrode interfaces. Single-source vulnerability concentrates in East Asian foundry capacity for 500–1000 Hz sampling rate chips. Distribution runs through specialized medical device distributors serving hospital networks and direct-to-clinic cloud platform provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECG management sector sits at a technology-transition inflection point where cloud-based algorithmic interpretation displaces capital-intensive hardware refresh cycles. Legacy Holter monitor manufacturers face margin compression as software-centric value propositions capture diagnostic workflow revenue.
For Market Incumbents: Hedge hardware margin erosion by embedding software attach rates through diagnostic equipment leasing programs that bundle algorithmic interpretation subscriptions. Accelerate backward integration into cloud infrastructure to reduce third-party hosting dependencies that compress gross margins. Prioritize FDA software-as-medical-device certification investments to maintain regulatory moats against unvalidated AI entrants.
For New Entrants and Emerging Players: CDSCO streamlined registration pathways in India open a window for cloud-delivered ECG interpretation services targeting tier-2 and tier-3 city cardiology clinics lacking diagnostic infrastructure. White-space concentration sits in ambulatory monitoring for chronic heart failure patients eligible for United States CMS reimbursement codes. Pursue hospital-at-home partnership models that bypass capital-intensive acute care procurement committees.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking software capabilities to extend hardware installed bases. Long-term viability favors vendors with validated secure-by-design architectures that preempt EU MDR cybersecurity annex compliance costs. Monitor FDA guidance on continuous learning algorithm recertification as an inflection trigger that could reclassify adaptive model updates as new premarket submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates market access for AI-enabled ECG classifiers across United States health systems. |
| Hospital System Partnership | Locks in enterprise-wide data consolidation contracts with merged integrated delivery networks. |
| CE Marking Pathway | Enables European market entry under EU MDR cybersecurity annex requirements. |
| Software Companion Development | Extends wearable device ecosystems with diagnostic-grade interpretation capabilities. |
| Reimbursement Strategy | Aligns platform economics with CMS remote patient monitoring coverage expansion. |
Methodological Framework
Independent corroboration across hospital procurement databases, GPO contracts, and CMS reimbursement filings underwrites the qualitative findings in this study. Primary interviews with cardiology department heads, biomedical engineers, health system CIOs, and GPO contracts managers combined with secondary validation from FDA 510(k) clearances, CE marking databases, and hospital capital expenditure disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked cloud platform subscription volumes against hardware shipment data.
Comparable-period anchoring to historical ECG equipment replacement cycles and software licensing transitions structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, deployment architecture, and regional regulatory cluster. CAGRs derived from growth rate reconciliation across hardware maturity curves and software adoption S-curves. Forecast inputs incorporated health system consolidation velocity and AI classifier validation timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for cloud-native algorithmic interpretation would alter the outlook if hospital procurement committees revert to capital expenditure preference. Forecasts reflect assumptions regarding FDA software-as-medical-device guidance stability and semiconductor foundry capacity expansion. A small set of triggers—continuous learning algorithm recategorization, REACH substance restriction expansion, and Medicare Advantage risk-contract penetration rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Epharmacy Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Global Cancer Registry Software Market