
 Healthcare Workforce Management Systems Market | 2026-2036
Healthcare Workforce Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Workforce Management Systems Market Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD), with its focus on social metrics, is pivoting healthcare providers toward systems that ensure transparent and equitable staff deployment. UKG leverages its broad HR software expertise to offer integrated workforce suites for large enterprises. AMN Healthcare specializes in combining staffing services with predictive analytics technology. HealthStream differentiates with its focus on credentialing and continuous education platforms integrated into workforce management.
Healthcare workforce management systems are software platforms designed to automate and optimize staff scheduling, time tracking, and credentialing. These systems often integrate with electronic health records and payroll applications to ensure seamless data flow. Their primary purpose is to balance labor costs with patient care quality and regulatory compliance. Cloud-based solutions are displacing legacy on-premise software due to superior scalability. Within applications, staff scheduling and compliance management represent critical functionalities for hospital end-users.
In the United States, compliance with HIPAA is critical for protecting employee health data managed by these systems. Across Europe, GDPR imposes strict data privacy and consent requirements on all workforce management platforms. Regulations from bodies like Australia's TGA, when medical device integration is involved, also influence system design for data security. Stakeholder decisions will center on selecting platforms that can adapt to evolving labor laws and integrate advanced analytics for predictive staffing.
Market Dynamics
The central dynamic in the healthcare workforce management systems market is the tension between acute labor cost-containment pressures and non-negotiable regulatory mandates for safe staffing and quality of care. This forces healthcare providers to seek sophisticated software solutions.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) and similar social governance pressures require transparent reporting on labor practices, compelling providers to adopt systems that can track and validate equitable staff deployment.
- Technology Shift to Cloud:The transition from on-premise software to scalable, cloud-based SaaS platforms lowers the total cost of ownership and provides greater flexibility, accelerating adoption among mid-sized hospitals and specialty clinic networks.
- Healthcare System Consolidation:Ongoing mergers and acquisitions, particularly in the United States, create large, multi-site hospital networks that require centralized, enterprise-grade systems to manage complex, cross-facility staffing and credentialing.
Market Restraints
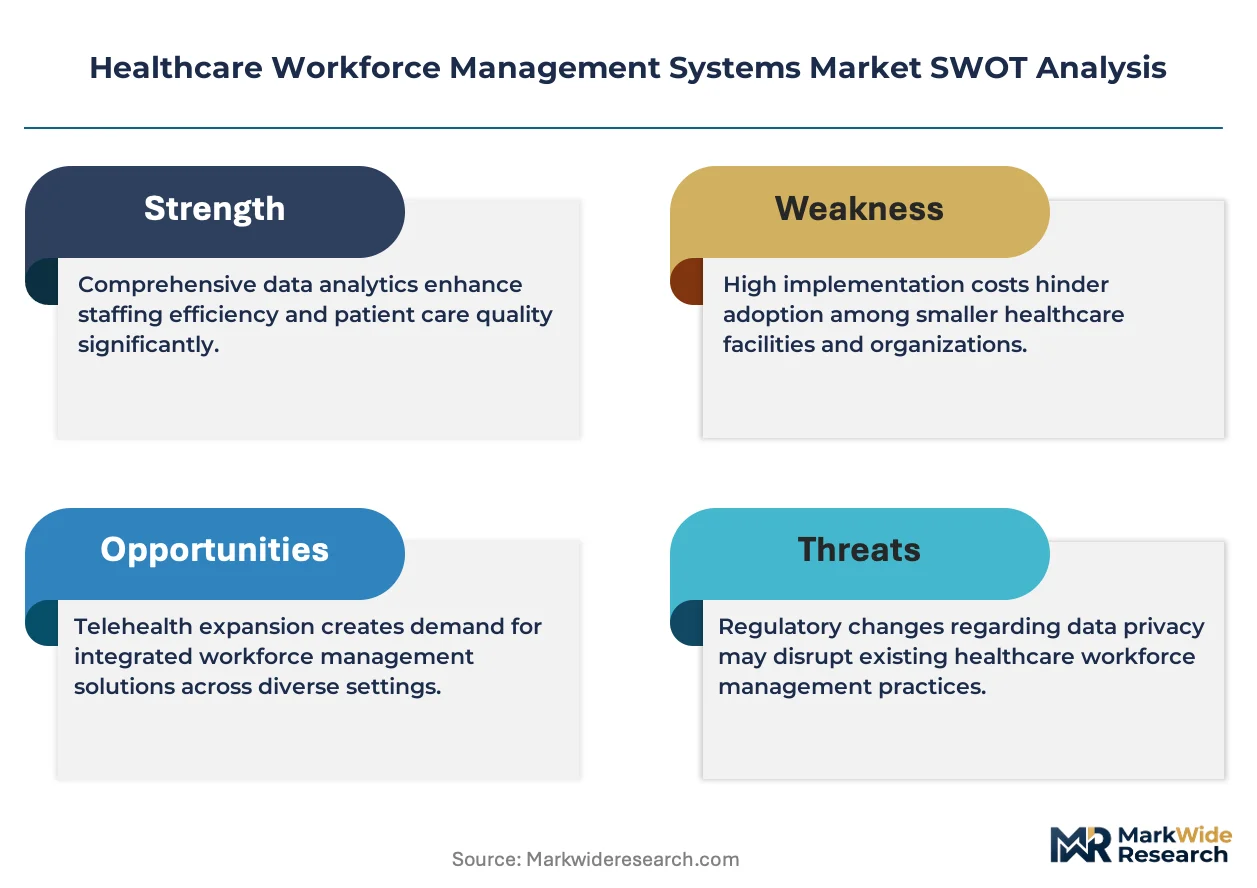
- High Implementation Costs:The significant upfront investment for software licensing, system integration with legacy EHRs, and staff training remains a primary barrier for smaller, independent hospitals and rural healthcare facilities with limited capital budgets.
- Data Interoperability Hurdles:A lack of standardization among different health IT systems creates persistent challenges in achieving seamless data flow between workforce management platforms, payroll applications, and electronic health records, limiting functionality.
- Data Privacy Compliance:Strict regulations like GDPR in Europe and HIPAA in the US impose significant development and operational burdens on vendors, requiring robust security features that increase system complexity and cost.
Strategic Opportunities
- Predictive Analytics Integration:Incorporating artificial intelligence and machine learning to forecast patient census fluctuations and predict staffing needs allows for proactive scheduling, representing a significant value-add for providers focused on operational efficiency.
- Expansion in Emerging Economies:Healthcare systems across Southeast Asia and Latin America are in the early stages of digital transformation, presenting a large, underpenetrated market for workforce management vendors as providers modernize their operations.
- Adjacent Market Penetration:Extending system functionalities to serve the specific needs of adjacent sectors like the long-term care, home healthcare, and behavioral health industries offers a substantial avenue for market growth beyond traditional hospitals.
Industry Challenges
- Complex Systems Integration:The operational challenge of integrating new workforce platforms with a hospital's existing, often fragmented and outdated, IT infrastructure is a major source of implementation delays, cost overruns, and user dissatisfaction.
- Clinical Staff Change Management:Overcoming resistance from nurses and other clinical staff accustomed to established, manual scheduling processes requires extensive training, clear communication, and demonstrated workflow benefits to ensure successful system adoption.
- Specialized Talent Shortage:A scarcity of IT professionals with dual expertise in both clinical healthcare workflows and complex enterprise software implementation creates bottlenecks for both vendors deploying systems and hospitals managing them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Workforce Management Systems Market |
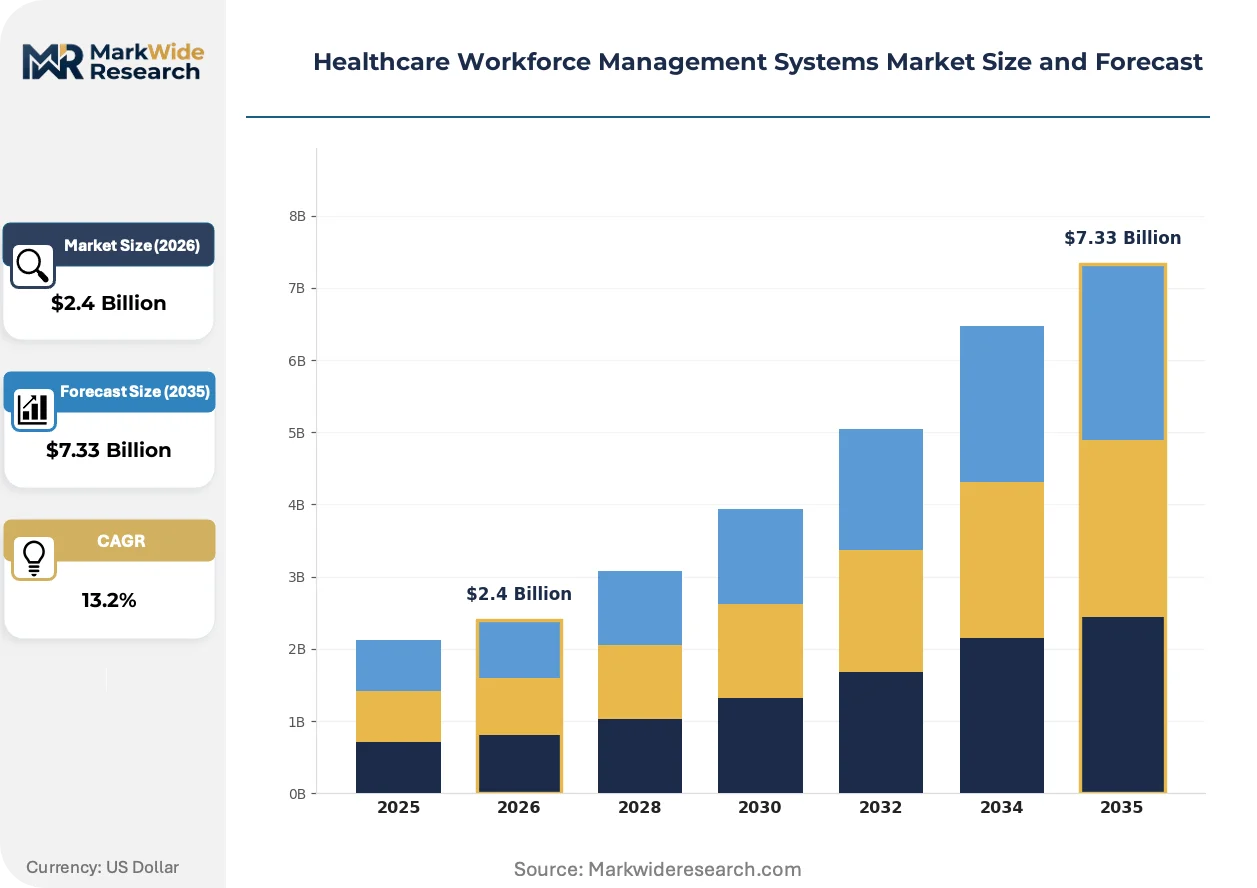
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.33 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Applications Application: Staff Scheduling, Time & Attendance, Credentialing, Labor Analytics, Compliance Management End User: Hospitals, Ambulatory Clinics, Long-Term Care Facilities, Diagnostic Laboratories, Home Care Providers Deployment Model: Software as a Service, Managed Services, Enterprise Licensing, Subscription Licensing |
| Companies Covered | BlueSky Medical Staffing, QGenda, AMN Healthcare, ShiftMed, HealthStream, Aya Healthcare, UKG, Kimedics, Atlas Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Workforce Management Systems Market Strategic Shifts & Innovations
The market is evolving from providing simple administrative scheduling tools to delivering strategic platforms for optimizing labor as a core component of financial health and patient safety. This transformation is driven by the convergence of data analytics with core human resource functions to address complex operational demands.
Predictive analytics modules are a key technological evolution. These tools use historical data and AI algorithms to forecast patient demand, staff availability, and potential scheduling gaps. Large hospital networks are the primary adopters, seeking to minimize their reliance on high-cost agency nurses, and the core scheduling function is expanding into proactive resource planning and financial modeling.
State-level safe staffing laws in the United States, such as nurse-to-patient ratio mandates, are a powerful regulatory driver. These regulations impose strict compliance requirements that are difficult to manage with manual or outdated systems, forcing hospital administrators to invest in modern platforms. The need for auditable proof of compliance particularly affects acute care hospitals in states like California and Massachusetts.
A definitive behavioral shift is the move away from large, one-time capital investments in on-premise software. Buyers now strongly prefer subscription-based Software-as-a-Service (SaaS) models that offer greater scalability and predictable operational expenses. This trend is most visible among mid-sized hospital systems and large physician groups in North America and Europe looking to preserve capital for clinical investments.
Healthcare Workforce Management Systems Market Segmentation
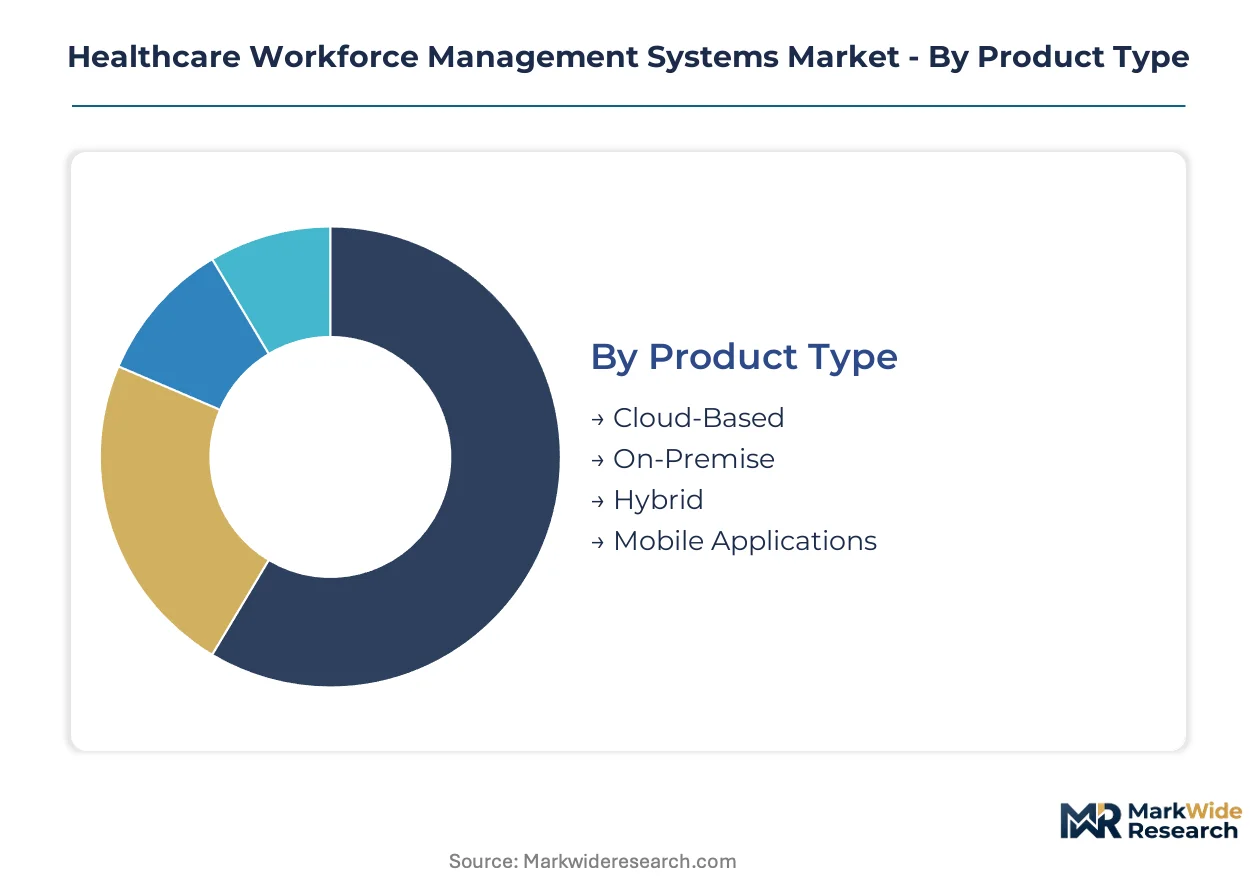
The healthcare workforce management systems market is segmented to reflect the diverse technological offerings and operational needs of healthcare providers. Understanding these distinctions is critical for vendors to tailor solutions and for healthcare organizations to select platforms that align with their strategic objectives for labor optimization and patient care.
Product Type:
The upgrade and replacement cycles in healthcare IT are heavily influenced by the adoption of new product types, with providers often replacing legacy systems with modern solutions.
- Cloud-Based:These platforms are hosted on remote servers and accessed via the internet, offering scalability and reduced infrastructure costs. Demand is concentrating in mid-sized hospital systems and large physician groups across North America and Europe due to their preference for predictable operational expenses.
- On-Premise:Software installed and run directly on a healthcare organization's local servers and infrastructure, providing complete control over data. Large, established hospital networks in regions with stringent data residency requirements, such as Germany, often prioritize these systems for their perceived security.
- Hybrid:These solutions combine elements of both cloud-based and on-premise deployments, allowing organizations to maintain sensitive data locally while leveraging cloud flexibility for other functions. This model is gaining traction among healthcare systems balancing legacy infrastructure with modernization initiatives.
- Mobile Applications:Dedicated applications designed for smartphones and tablets, enabling staff to manage schedules, track time, and access information remotely. Nurses and allied health professionals increasingly use these tools for on-the-go access and improved workflow efficiency.
Cloud-Based solutions sit at the top of the volume ranking, with Mobile Applications climbing the fastest.
Application:
The functional utility of healthcare workforce management systems varies significantly by application, addressing specific operational pain points within clinical and administrative workflows.
- Staff Scheduling:This core functionality automates the creation and management of employee work shifts, optimizing coverage and reducing manual administrative effort. Hospitals and large clinic networks in the United States rely on advanced scheduling to manage complex staffing patterns and comply with safe staffing mandates.
- Compliance Management:These modules track and verify staff credentials, licenses, certifications, and training requirements to ensure adherence to regulatory standards. Acute care hospitals in states like California use these systems to provide auditable proof of nurse-to-patient ratio compliance.
- Time & Attendance:Systems for accurately recording employee work hours, breaks, and overtime, which directly integrate with payroll processes. Long-term care facilities in the UK utilize these applications to ensure fair compensation and accurate labor cost tracking.
- Credentialing:The process of verifying the qualifications, licensure, and professional background of healthcare practitioners. This is critical for hospitals and ambulatory surgical centers globally to ensure patient safety and meet accreditation standards.
- Labor Analytics:These tools use data to analyze staffing patterns, predict future needs, and identify cost-saving opportunities. Large hospital networks leverage predictive analytics to forecast patient census fluctuations and optimize resource allocation.
Staff Scheduling represents the largest segment by adoption, while Labor Analytics exhibits the steepest expansion trajectory.
End User:
The specific operational environments and scale of different healthcare end-users drive varied requirements for workforce management solutions.
- Hospitals:Large, complex healthcare facilities requiring comprehensive systems to manage a diverse workforce across multiple departments and shifts. These institutions often need enterprise-grade solutions that integrate with electronic health records.
- Ambulatory Clinics:Outpatient facilities providing diagnostic, treatment, and preventive services, needing flexible scheduling and time tracking for smaller teams. These clinics prioritize ease of use and rapid implementation for efficient patient flow.
- Long-Term Care Facilities:Institutions providing ongoing medical and personal care for individuals with chronic illnesses or disabilities, where consistent staffing is paramount. These facilities often seek systems that can manage complex shift patterns and compliance with care mandates.
- Diagnostic Laboratories:Facilities performing medical tests and analyses, requiring precise scheduling for specialized technicians and equipment. Data privacy compliance, such as HIPAA in the US, is a critical concern for these labs.
- Home Care Providers:Organizations delivering healthcare services to patients in their homes, needing mobile-friendly solutions for remote staff management and visit verification. These providers prioritize efficiency in field staff deployment and communication.
Hospitals constitute the largest end-user group, with Home Care Providers demonstrating significant growth potential.
Deployment Model:
The choice of deployment model significantly impacts a healthcare organization's IT infrastructure, cost structure, and operational flexibility.
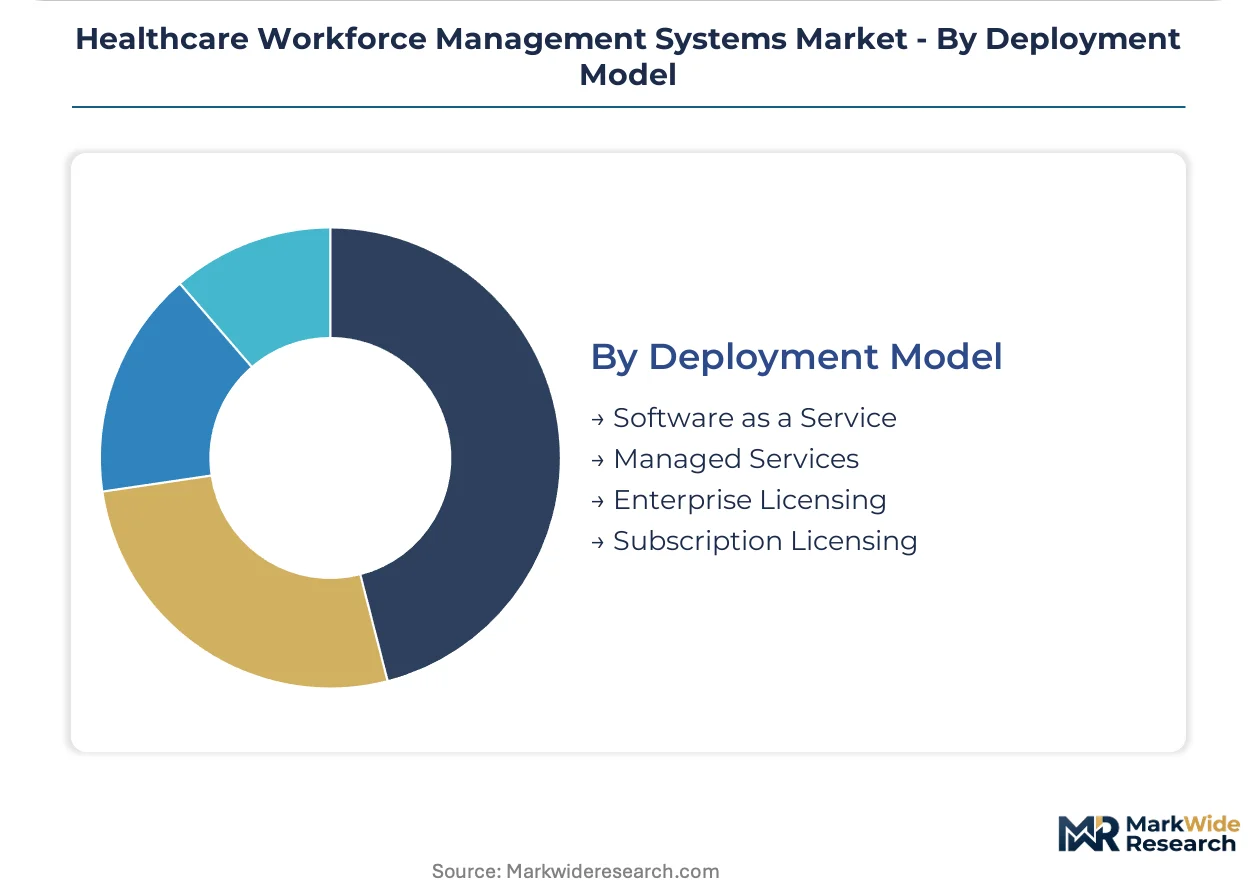
- Software as a Service:A subscription-based model where software is centrally hosted by the vendor and accessed over the internet. This model is preferred by mid-sized hospitals and specialty clinic networks in North America for its lower upfront costs and scalability.
- Managed Services:The vendor manages and maintains the software and associated IT infrastructure, allowing the healthcare provider to focus on core operations. This model appeals to organizations with limited internal IT resources or those seeking to offload complex system management.
- Enterprise Licensing:A traditional model where a healthcare organization purchases a perpetual license to use the software, typically installed on-premise. Large hospital systems with significant capital budgets and specific customization needs often opt for this model.
- Subscription Licensing:Users pay a recurring fee to use the software for a specified period, without owning the software itself. This model is widely adopted across Europe, offering predictable operational expenses and access to continuous updates.
Software as a Service commands the largest market share, while Managed Services are gaining share fastest among resource-constrained providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare workforce management systems market scaled significantly with the advent of digital health technologies and complex hospital operations. Early adoption concentrated in developed economies with advanced healthcare infrastructures. These systems became crucial for managing diverse clinical staff and optimizing resource allocation.
United States
The United States market exhibits robust demand, driven by ongoing healthcare system consolidation and stringent safe staffing mandates. Compliance with HIPAA is critical for protecting employee health data within these management platforms. Major hospital networks in metropolitan areas like Chicago are integrating advanced analytics to optimize labor allocation and control costs.
Germany
Germany's market for workforce management systems emphasizes data control, particularly for large public hospital networks. GDPR imposes strict data privacy and consent requirements on all platforms operating within the country. Healthcare providers in regions such as Bavaria are adopting hybrid solutions to balance legacy infrastructure with modernization initiatives.
United Kingdom
United Kingdom healthcare providers seek transparent staff deployment, driven by pressures for social metric reporting and efficient labor cost tracking. The Care Quality Commission (CQC) mandates robust staffing levels, necessitating advanced time and attendance applications. NHS trusts in urban centers such as Manchester are increasingly adopting cloud-based platforms for improved scalability and operational flexibility.
Australia
Australian healthcare systems are modernizing operations, with a strong focus on credentialing and continuous education platforms. Regulations from the Therapeutic Goods Administration (TGA) influence system design for data security when medical device integration occurs. Hospitals in major cities like Sydney are adopting advanced workforce solutions to ensure compliance and enhance staff qualifications.
Healthcare Workforce Management Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the healthcare workforce management systems market, reflecting a tiered competitive structure. The market sees large enterprise HR software providers offering broad integrated suites alongside specialized vendors focused on niche functionalities. Strategic archetypes include comprehensive platform providers, analytics-focused innovators, and compliance solution specialists. Companies pursue strategic partnerships and portfolio diversification to enhance their market reach.
Within the comprehensive platform provider tier, UKG, Inc. represents a major player leveraging broad HR software expertise to deliver integrated workforce suites for large enterprises. AMN Healthcare, Inc. occupies a position as an analytics-focused innovator, combining staffing services with predictive technology to optimize labor allocation. HealthStream, Inc. exemplifies a specialized vendor, anchoring its offerings around credentialing and continuous education platforms integrated into workforce management systems. These companies highlight the market's differentiation across scale, technological depth, and functional specialization.
| Leading Market Players |
|---|
| BlueSky Medical Staffing |
| QGenda |
| AMN Healthcare |
| ShiftMed |
| HealthStream |
| Aya Healthcare |
| UKG |
| Kimedics |
| Atlas Systems |
| Others |
Cost & Logistics Intelligence
Large hospital networks, with their complex enterprise needs, anchor demand for subscription-based Software-as-a-Service (SaaS) models. This preference reflects a strategic shift towards predictable operational expenses over capital outlays.
Pricing Analysis
Subscription-based Software-as-a-Service (SaaS) is the prevailing pricing model in the healthcare workforce management systems market. Price differentiation emerges from customization levels required for integration with existing electronic health records and the breadth of integrated functionalities, particularly advanced analytics. Pricing pressure stems from the competitive landscape and healthcare providers' acute need for cost-containment. Smaller, independent hospitals demonstrate the highest price sensitivity, whereas large enterprise systems prioritize comprehensive feature sets and robust vendor support.
Supply Chain Analysis
Dual-sourcing requirements are less prevalent in software, but vendors often rely on diverse cloud infrastructure providers to ensure service resilience. Core development and hosting infrastructure concentrate in the United States and major European data centers. Supply chain dependencies include access to high-skilled software developers and robust cloud computing services. Data privacy compliance across varied regulatory regimes like GDPR and HIPAA represents a significant structural risk. Distribution runs through direct sales channels from software vendors to healthcare organizations, often augmented by strategic partnerships with health IT consulting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a clear margin-expansion story, driven by the shift towards high-value predictive analytics modules that optimize labor allocation and reduce reliance on expensive agency staff. Providers are increasingly willing to invest in solutions that deliver tangible cost savings and compliance benefits.
For Market Incumbents: Deploy advanced AI integration to maintain a technological edge against emerging specialized analytics startups. Incumbents should deepen integration with existing electronic health record systems to enhance data flow and acquire niche analytics firms to expand their predictive capabilities. This strategy addresses the threat of new entrants offering point solutions and reinforces market leadership in comprehensive workforce management.
For New Entrants and Emerging Players: Begin with a focus on underpenetrated adjacent sectors like long-term care and home healthcare, where existing solutions are often rudimentary. The most penetrable segment for new entrants remains mid-sized specialty clinic networks seeking scalable, cost-effective solutions. A go-to-market strategy emphasizing cloud-native, mobile-first platforms with rapid implementation timelines will resonate with resource-constrained providers.
For Investors and Strategic Acquirers: Large enterprise HR software providers are the most active acquirers in this space, seeking to expand their healthcare vertical offerings. The market's long-term viability remains strong over the next decade, driven by persistent labor challenges and regulatory pressures in healthcare. Acquisition targets should include SaaS providers with proprietary AI algorithms or deep vertical expertise in specific care settings. Consolidation of smaller point solution vendors by larger HR tech players serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Predictive Staffing Module | This enhances proactive resource planning for hospitals, reducing reliance on expensive temporary staff. |
| Strategic Partnership: EHR System Integration | Seamless data flow with electronic health records improves operational efficiency and clinical decision-making. |
| Acquisition of Specialist Firm: AI-driven Credentialing | This strengthens compliance capabilities and automates complex verification processes for healthcare providers. |
| Geographic Expansion: Southeast Asia Market Entry | Tapping into emerging economies offers significant growth potential as healthcare digitalization accelerates. |
| Platform Integration: Telehealth Workforce Management | This addresses the evolving needs of remote care delivery, optimizing scheduling for virtual consultations. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. The methodology combines in-depth primary interviews with industry stakeholders, including hospital administrators, Chief Nursing Officers, and IT directors, with robust secondary validation. This approach integrates insights from industry association reports, government health statistics, and vendor financial disclosures, triangulating findings through both bottom-up and top-down data modeling.
Market volume and value were modeled at a granular level across product type, application, end-user, and deployment model throughout the forecast period. Compound annual growth rates were derived from historical growth trajectories, competitive intensity, and anticipated technological advancements in AI. Key industry-specific forecast inputs included healthcare spending projections, evolving regulatory mandates for staffing levels, and the accelerating adoption rates of cloud-based solutions.
Several conditions sit outside the modeled scope, including specific individual hospital procurement budgets and micro-level regional labor strikes. Forecasts reflect assumptions regarding stable macroeconomic conditions and the current regulatory environment. Unforeseen global health crises or rapid shifts in healthcare policy represent risk factors that could revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Epharmacy Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Patient Referral Management Software Market