
 Power Scraper Market | 2026-2036
Power Scraper Market Size, Share, and Industry Trends Forecast 2026-2036
Power Scraper Market Analytics
ISO 14001 environmental management certification is bifurcating the competitive landscape between compliant and non-compliant suppliers. Caterpillar Inc. leverages its global dealer network to sustain aftermarket parts revenue across mining and construction verticals. Komatsu anchors its position through in-house production of proprietary hydraulic systems for heavy scraper platforms. Sany Heavy Industry competes aggressively on delivered cost in Belt and Road corridor projects across Central Asia.
A power scraper is a motorized earthmoving machine equipped with a vertically adjustable bowl or blade for cutting, loading, hauling, and dumping soil or aggregate over distances up to several kilometers, with bowl capacities typically spanning 15 to 40 cubic meters depending on application class. The machine combines the functions of excavator, haul truck, and grader into a single unit optimized for bulk material stripping in open-pit mining and highway construction. Hydraulic scrapers dominate fleet procurement among mining contractors due to superior breakout force and bowl penetration in abrasive rock conditions, while electric variants gain traction in underground operations where ventilation constraints limit diesel exhaust exposure. Smart technology integration represents the fastest-expanding segment as OEMs embed telematics, automated grade control, and predictive maintenance algorithms to reduce operator skill requirements and unplanned downtime.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe mandate particulate matter and nitrogen oxide reductions that increase engine cost and complexity, effectively raising barriers for smaller manufacturers lacking emissions engineering capability. China's MEE enforces National VI-equivalent standards in non-road mobile machinery that align with but diverge from European test cycles, complicating platform standardization for multinational OEMs. OSHA trenching and excavation safety directives in the United States indirectly stimulate scraper demand by accelerating mechanical surface preparation ahead of confined digging operations. Stakeholders must monitor the divergence between regional emissions compliance pathways and assess whether modular powertrain architectures can amortize development costs across fragmented regulatory markets.
Market Dynamics
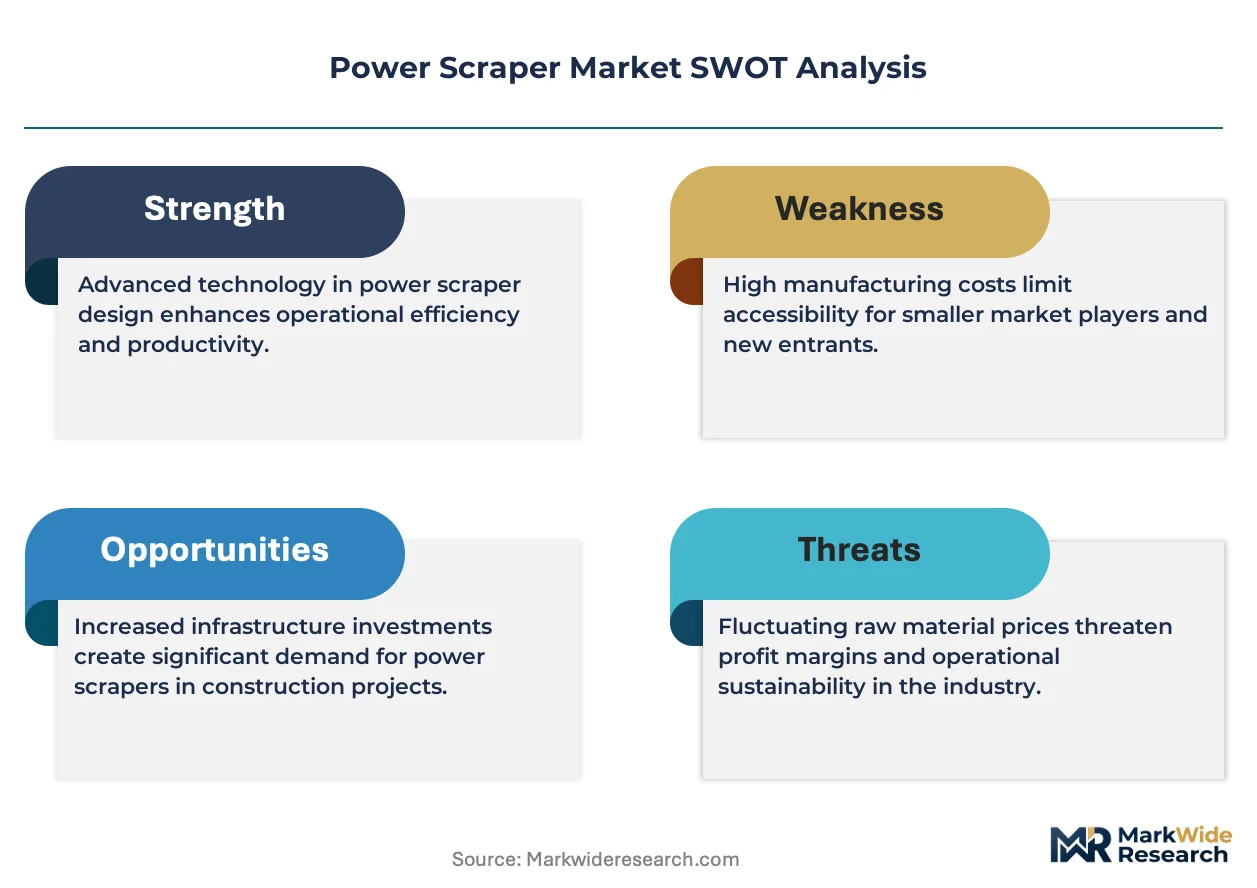
Hybrid drivetrain development is bifurcating the power scraper market between Tier 4 Final-compliant hydraulic platforms and emerging electric variants, forcing OEMs to amortize R&D across dual powertrain architectures while mining contractors recalibrate fleet procurement strategies.
Growth Catalysts
- EPA Tier 4 Final:The EPA's particulate matter and nitrogen oxide mandates in the United States are accelerating hybrid engine retrofits among surface mining contractors seeking compliance without sacrificing bowl penetration force.
- Underground ventilation constraints:Electric scraper variants are gaining specification in confined tunneling operations where diesel exhaust exposure creates occupational safety liabilities.
- Western China infrastructure corridors:Belt and Road Initiative earthworks in Xinjiang and Sichuan provinces are concentrating fleet orders for high-capacity bowl configurations in abrasive rock conditions.
Market Restraints
- Emissions engineering capability scarcity:EPA Tier 4 Final and EU Stage V compliance requirements raise development barriers for smaller manufacturers lacking in-house catalytic reduction expertise.
- Proprietary hydraulic system concentration:Komatsu's captive production of heavy scraper hydraulics limits third-party component availability and extends lead times for non-integrated OEMs.
- Autonomous haul truck substitution:Open-pit mining operators are piloting driverless truck fleets for bulk material movement over distances exceeding scraper economic range.
Strategic Opportunities
- Telematics integration white space:Predictive maintenance algorithms and automated grade control systems represent underpenetrated value-add layers for rental fleet operators in Australia's Pilbara region.
- Central Asian corridor projects:Kazakhstan and Uzbekistan infrastructure tenders are specifying delivered-cost competitive equipment, favoring OEMs with regional assembly partnerships.
- China National VI-equivalent alignment:The MEE's non-road mobile machinery standards create regulatory tailwinds for domestic manufacturers with test-cycle optimization capabilities.
Industry Challenges
- Operator skill compression:Smart technology integration reduces manual control requirements but creates training gaps for legacy equipment technicians transitioning to algorithm-dependent diagnostics.
- Modular powertrain validation timelines:Dual-certification pathways for EPA and MEE test cycles extend product launch schedules and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Scraper Market |
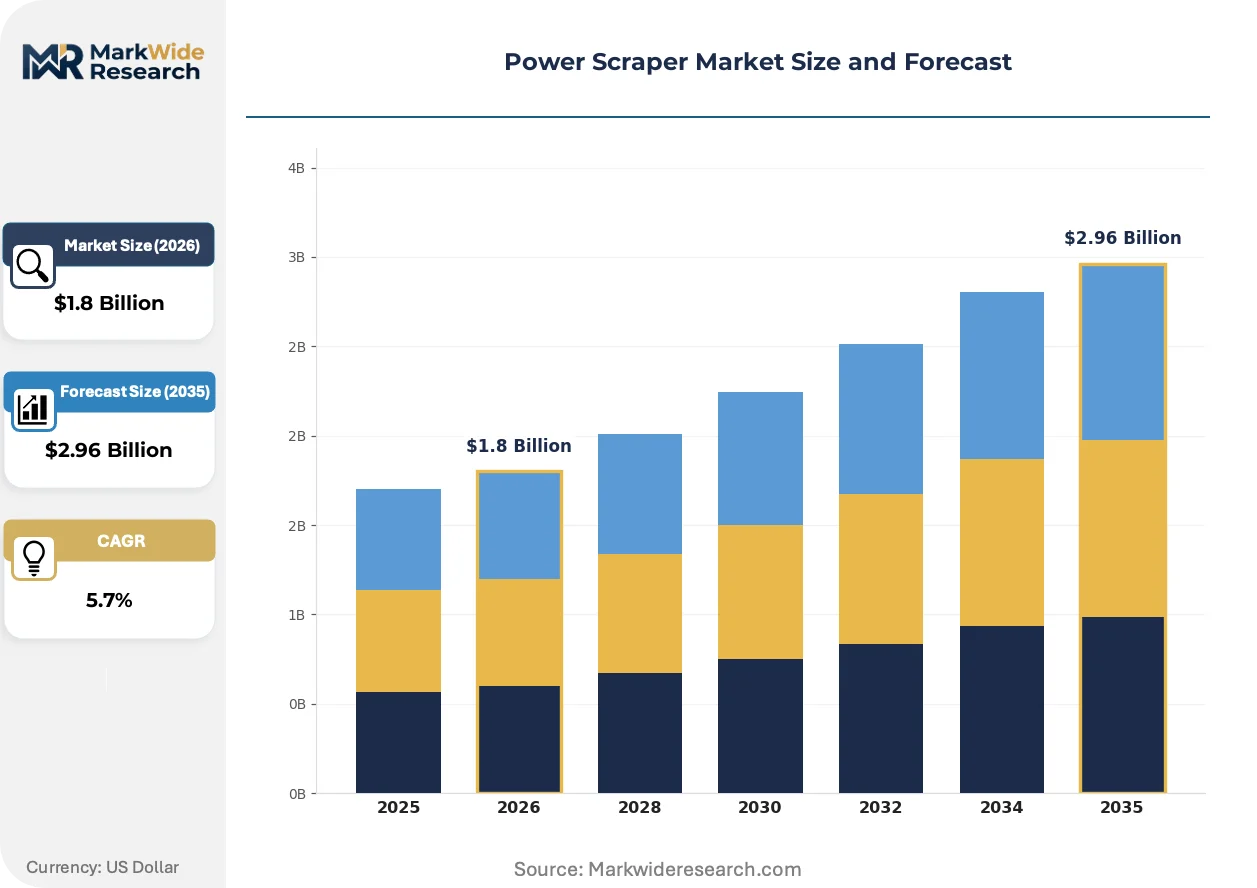
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scrapers, Hydraulic Scrapers, Pneumatic Scrapers, Manual Scrapers Application: Construction, Road Maintenance, Industrial Cleaning, Demolition End User: Contractors, Facility Managers, Municipalities, DIY Users Technology: Conventional, Robotics, Smart Technology, Hybrid |
| Companies Covered | Caterpillar Inc., Komatsu, AB Volvo, Makita Corporation, Schmid & Wezel, BIAX, Sany Heavy Industry, Hitachi Construction, SKIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Scraper Market Evolving Landscape
Telematics and automation are compressing the traditional operator skill premium while regulatory divergence between North American and Chinese test cycles forces platform architecture decisions.
Automated grade control systems are bifurcating the scraper operator labor pool between high-skill legacy technicians and technology-assisted generalists. Mining contractors in Western Australia's iron ore districts are specifying these systems for 24-hour continuous operations. The technology is bifurcating aftermarket service revenue streams toward software diagnostics and away from mechanical overhaul.
EU Stage V regulations are mandating real-driving emissions monitoring for non-road mobile machinery, adding sensor hardware costs and data governance obligations. European quarry operators are responding by extending replacement cycles for pre-Stage V equipment. Underground construction segments in Germany and Austria are accelerating electric variant trials to preempt compliance-driven operating restrictions.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier mining contractors facing balance sheet constraints. Rental fleet operators in Chile's copper belt are unbundling maintenance from machine provision, capturing margin through uptime guarantees rather than hourly rates. This shift concentrates procurement authority with finance functions rather than site engineering teams.
Power Scraper Market Segmentation
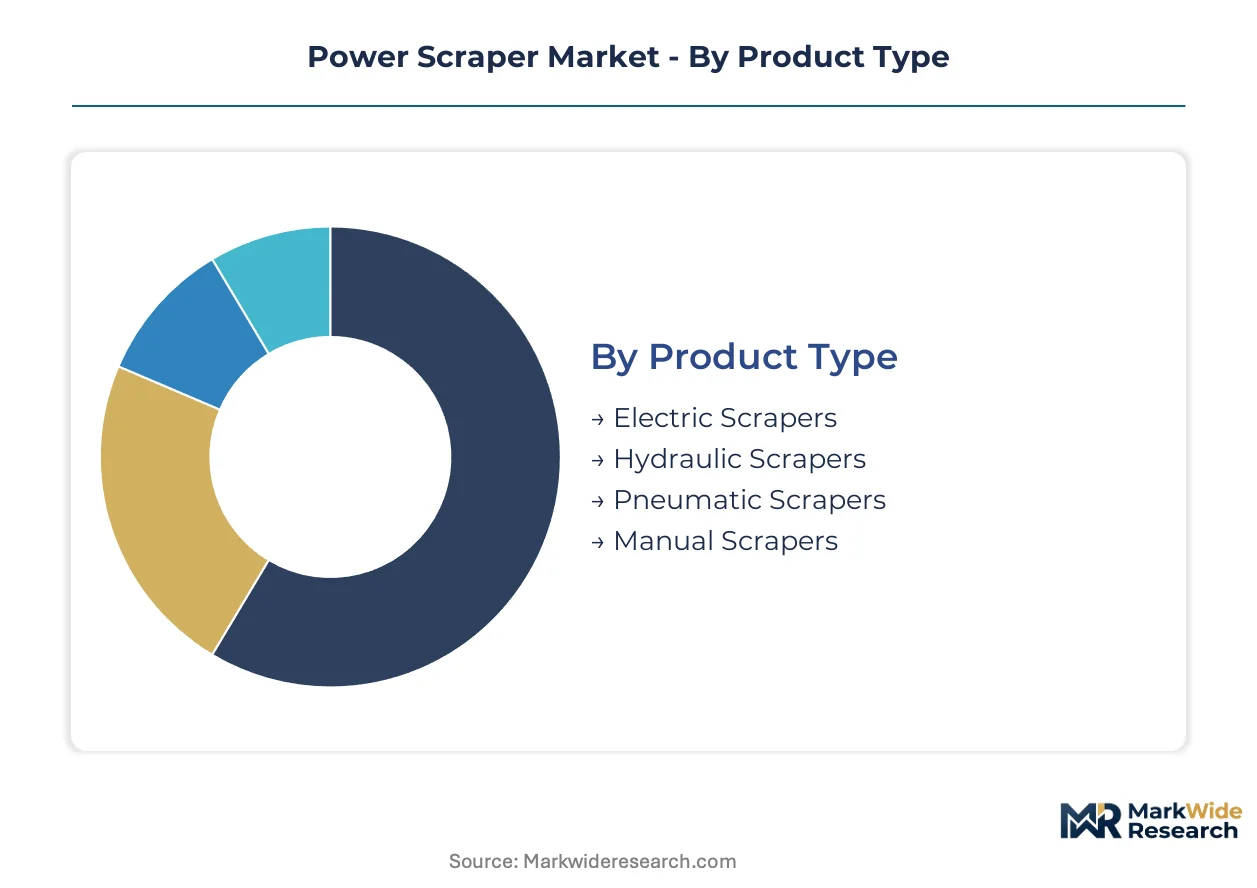
Power scraper procurement channels diverge sharply across product categories, with mining contractors favoring direct OEM relationships for high-capacity hydraulic units while municipal fleets increasingly source electric variants through regional distributors. Understanding these channel-segment pairings reveals where margin pools concentrate and which specifications drive specification authority.
Product Type:
Channel mix varies by powertrain complexity, with hydraulic platforms flowing through dealer networks requiring service attachment and electric variants penetrating via direct rental channels.
- Electric Scrapers:Battery-powered drivetrains with regenerative braking systems and zero tailpipe emissions. Demand is concentrating in Germany's underground tunneling sector where the country's Federal Institute for Occupational Safety and Health enforces strict diesel particulate exposure limits, accelerating fleet replacement cycles.
- Hydraulic Scrapers:Diesel-hydraulic systems delivering breakout force exceeding 400 kN for abrasive rock penetration. Australia's Pilbara iron ore contractors specify these units through Caterpillar and Komatsu dealer networks, bundling maintenance contracts to secure parts availability in remote operating environments.
- Pneumatic Scrapers:Compressed-air powered units for explosive atmosphere operations.
- Manual Scrapers:Human-powered tools for precision finishing work.
By volume, Hydraulic Scrapers lead. By growth pace, Electric Scrapers are expanding most quickly.
Application:
Cost tier stratification separates premium-specification mining applications from price-sensitive municipal maintenance contracts.
- Construction:Bulk earthmoving for highway embankments, airport runways, and dam foundations requiring continuous loading-hauling-dumping cycles. Western China's Sichuan province infrastructure corridors specify high-capacity bowl configurations for Belt and Road Initiative earthworks in mountainous terrain.
- Road Maintenance:Surface rehabilitation and shoulder grading operations. Kazakhstan's national highway authority sources mid-tier hydraulic units through centralized procurement tenders, prioritizing delivered cost over telematics integration.
- Industrial Cleaning:Slag removal and stockpile management in steel and cement plants.
- Demolition:Site preparation and debris clearing for urban redevelopment projects.
By revenue concentration, Construction dominates. By margin expansion, Road Maintenance is gaining share fastest.
End User:
Customer type determines specification complexity, with large contractors demanding predictive maintenance integration and municipalities prioritizing capital efficiency.
- Contractors:Mining and earthmoving specialists operating fleets exceeding 50 units. Chile's copper belt contractors are unbundling equipment-as-a-service contracts, shifting procurement authority from site engineers to finance functions seeking uptime guarantees.
- Facility Managers:Industrial site operators managing captive maintenance fleets. Uzbekistan's cement plants specify pneumatic scrapers for kiln area cleaning where explosive dust atmospheres prohibit diesel equipment.
- Municipalities:Local government bodies with constrained capital budgets.
- DIY Users:Small-scale operators and rental customers.
By fleet scale, Contractors command the largest average order values. By procurement velocity, Facility Managers are accelerating replacement cycles.
Technology:
Maturity stage separates legacy conventional platforms from emerging smart systems requiring software-enabled service architectures.
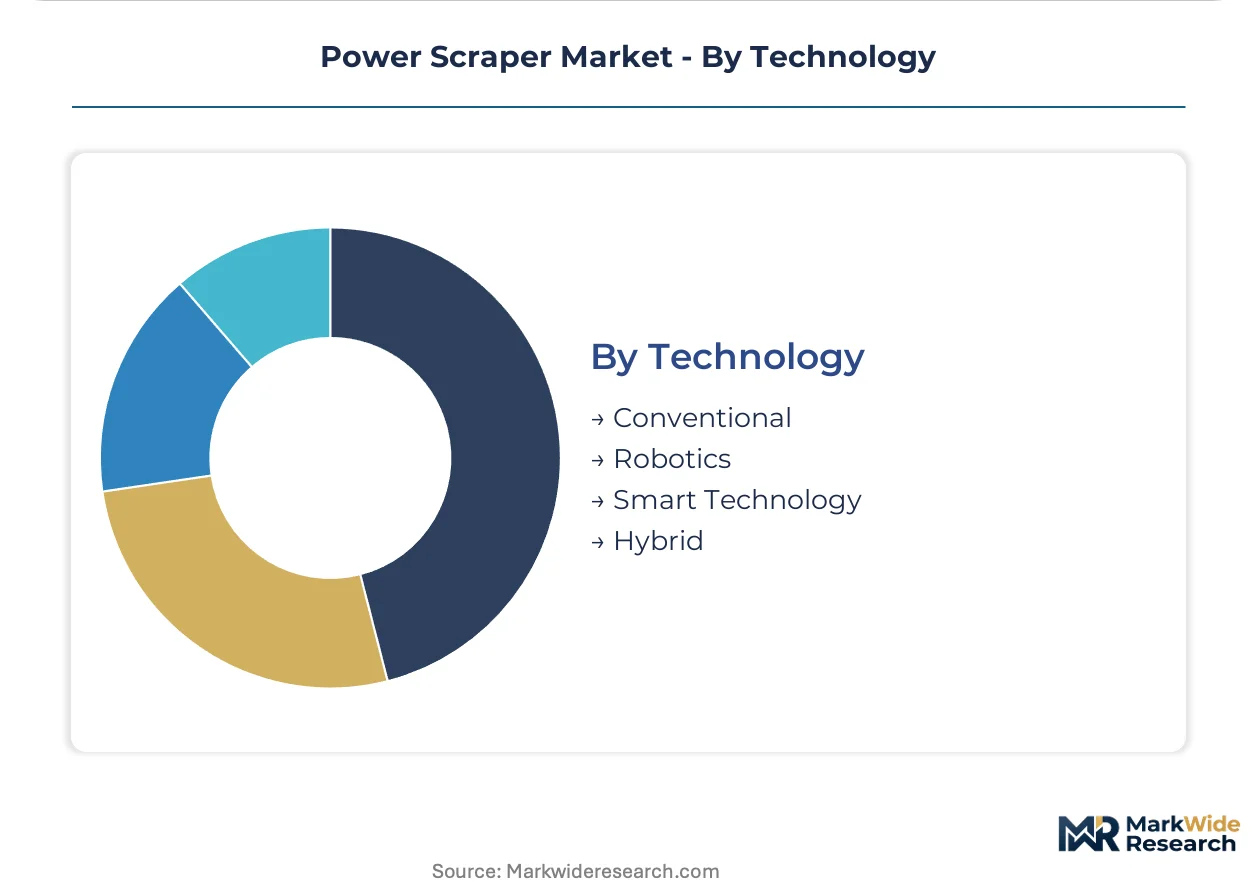
- Smart Technology:Telematics-enabled platforms with automated grade control, predictive maintenance algorithms, and remote diagnostics. Western Australia's iron ore districts specify these systems for 24-hour continuous operations, compressing operator skill requirements while shifting aftermarket revenue toward software subscriptions.
- Hybrid:Dual-powertrain architectures combining diesel prime movers with electric boost systems for EPA Tier 4 Final compliance. North American surface mining operators pilot these units to maintain bowl penetration force while meeting particulate matter mandates.
- Conventional:Mechanical-hydraulic platforms without integrated electronics.
- Robotics:Autonomous or semi-autonomous operation systems.
By installed base, Conventional technology retains the largest footprint. By development investment, Smart Technology commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining contractors in Australia and construction operators in Western China dominate procurement volumes for high-capacity hydraulic units, while European tunneling specialists accelerate electric variant trials under strict occupational exposure limits.
Australia
Pilbara iron ore mining contractors specify Caterpillar and Komatsu dealer networks for fleet procurement exceeding fifty units per order. EPA-equivalent state regulations in Western Australia enforce diesel particulate monitoring for surface operations. Perth-based rental operators bundle maintenance contracts with machine provision to secure parts availability in remote sites.
China
Belt and Road Initiative earthworks in Xinjiang and Sichuan provinces concentrate demand for high-capacity bowl configurations in abrasive rock terrain. MEE National VI-equivalent standards for non-road mobile machinery diverge from European test cycles, complicating platform standardization. Chongqing manufacturing clusters supply regional assembly partnerships for Central Asian corridor projects.
Germany
Underground tunneling contractors in the Ruhr district accelerate electric scraper trials under Federal Institute for Occupational Safety and Health diesel exposure limits. EU Stage V regulations mandate real-driving emissions monitoring with sensor hardware obligations. Bavarian quarry operators extend replacement cycles for pre-Stage V equipment to defer compliance costs.
United States
Surface mining contractors in Wyoming's Powder River Basin pilot hybrid drivetrain retrofits to maintain bowl penetration force under EPA Tier 4 Final mandates. OSHA trenching safety directives stimulate mechanical surface preparation ahead of confined digging operations. Texas-based equipment-as-a-service providers unbundle maintenance from machine provision for mid-tier contractors.
Chile
Copper belt mining contractors shift procurement authority from site engineers to finance functions through uptime-guarantee contracting models. National mining regulator SERNAGEOMIN enforces ventilation standards that indirectly favor fleet renewal. Antofagasta regional distributors capture margin through telematics-enabled rental fleets rather than hourly rate structures.
Power Scraper Market Competitive Landscape
Player mix skews toward integrated full-line manufacturers with captive hydraulic production and regional specialists competing on delivered cost in corridor projects. The vendor base separates into three strategic archetypes: diversified construction equipment conglomerates with global dealer networks, national champions leveraging domestic regulatory alignment, and component-focused specialists supplying niche pneumatic and electric variants. Competitive moves concentrate on dual-powertrain architecture development and regional assembly partnerships to amortize certification costs across fragmented regulatory markets.
Among diversified full-line manufacturers, Caterpillar Inc., Komatsu, and Sany Heavy Industry exemplify contrasting geographic anchoring strategies. Caterpillar leverages its North American dealer infrastructure to sustain aftermarket parts revenue across mining verticals. Komatsu represents Japanese integrated production models with in-house hydraulic system manufacturing. Sany Heavy Industry occupies a position within Chinese domestic champions competing aggressively on delivered cost in Belt and Road corridor tenders across Central Asia.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu |
| AB Volvo |
| Makita Corporation |
| Schmid & Wezel |
| BIAX |
| Sany Heavy Industry |
| Hitachi Construction |
| SKIL |
| Others |
Value Network & Pricing Analysis
Hybrid drivetrain substitution for conventional diesel-hydraulic platforms is redrawing supplier geography toward battery cell manufacturing clusters while compressing margins on legacy engine components. Tier 4 Final compliance costs are concentrating pricing power with integrated OEMs possessing captive emissions engineering capability.
Pricing Analysis
Cost-plus contracts with steel and rare earth indexation dominate fleet procurement agreements for mining contractors in Australia's Pilbara region. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified suppliers from non-compliant competitors, with after-sales service bundling commanding additional margin. Pricing pressure stems from Sany Heavy Industry's delivered-cost aggression in Central Asian corridor tenders. Municipal fleet operators exhibit highest price sensitivity, while integrated mining contractors prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of hydraulic pumps and high-grade steel plate characterizes procurement patterns among Australian dealer networks facing extended lead times from Komatsu's captive production facilities. Component sourcing draws from Japan for precision hydraulics, China for structural steel and battery cells, and Germany for emissions control modules. Single-source vulnerability concentrates in proprietary hydraulic system supply. Distribution runs through OEM-authorized dealer networks for hydraulic platforms and direct rental channels for electric variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power scraper market is recovering from a cyclical trough driven by mining capital expenditure restocking in Australia's iron ore districts and Belt and Road infrastructure acceleration in Western China.
For Market Incumbents: Fortify aftermarket revenue streams by embedding predictive maintenance algorithms into telematics-enabled fleets, compressing third-party service provider margins. Deepen backward integration into battery pack assembly for hybrid architectures to offset supplier concentration risk from Chinese cell manufacturers. Prioritize dual-certification engineering bandwidth for EPA Tier 4 Final and MEE National VI-equivalent alignment. For New Entrants and Emerging Players: EPA Tier 4 Final certification fast-track through partnership with established engine suppliers offers the most penetrable entry vector for North American surface mining contracts. Target Chilean copper belt equipment-as-a-service providers with unbundled maintenance offerings that shift procurement authority toward finance functions. Pursue regional assembly partnerships in Kazakhstan and Uzbekistan to capture Belt and Road corridor demand on delivered-cost terms. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier OEMs with modular powertrain architectures capable of amortizing development costs across fragmented regulatory markets. Long-term viability hinges on software-enabled service revenue expansion rather than unit sales volume. Watch autonomous haul truck substitution rates in open-pit mining as the critical inflection signal for scraper demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Powertrain Development | Modular architectures reduce compliance costs across EPA Tier 4 Final and MEE National VI-equivalent test cycles. |
| Telematics Platform Integration | Predictive maintenance algorithms shift aftermarket revenue toward software subscriptions in Western Australian iron ore districts. |
| Regional Assembly Partnership | Local production in Chongqing manufacturing clusters captures Belt and Road corridor tenders in Central Asia. |
| Equipment-as-a-Service Contracting | Uptime guarantee models concentrate procurement authority with finance functions in Chile's copper belt. |
| Electric Variant Certification Program | Zero-emission platforms penetrate Germany's underground tunneling sector under Federal Institute for Occupational Safety and Health limits. |
Research Methodology
The analysis maps hydraulic scraper, electric scraper, smart technology, and hybrid powertrain sub-sectors, each validated through maintenance directors at mining contractors, OEM procurement teams, aftermarket service heads, and rental fleet operators. Primary interview data triangulates against customs records for heavy equipment imports, SEC filings from diversified manufacturers, MEE non-road mobile machinery certification databases, and Association of Equipment Manufacturers trade statistics. Bottom-up unit demand estimates reconcile with top-down market value reconstruction.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include powertrain architecture, bowl capacity tier, application intensity, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, fleet expansion rates, and technology substitution curves. Forecast inputs incorporate mining commodity price trajectories and infrastructure investment disbursement schedules.
Underlying assumptions cover emissions compliance pathway convergence, battery cost decline curves, and mining contractor capital availability, with deviation risk concentrated in autonomous haul truck substitution velocity and regional regulatory divergence. Revision becomes warranted when electric variant penetration in underground operations crosses threshold levels that restructure OEM R&D allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Smart Motors Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Power Stacker Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Explosion-Proof Motor Casting Market