

Roll Cooling and Lubrication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Cooling and Lubrication Systems Market Insights
Capital-intensity divergence between integrated system builders and component suppliers is reorganizing competitive tiers in roll cooling and lubrication. Primetals Technologies leverages full-line metallurgical integration to bundle cooling systems with rolling mill overhauls, capturing captive demand from major steel producers. SMS group anchors its position through proprietary nozzle design and hydrodynamic control algorithms that reduce coolant consumption. Lechler specializes in precision spray technology, competing on droplet size consistency across high-speed aluminum tandem mills.
Roll cooling and lubrication systems deliver controlled thermal management and friction reduction to rotating cylinders in continuous forming processes, typically operating at coolant pressures of 5-40 bar and flow rates calibrated to strip surface temperatures exceeding 900°C in hot rolling. Their primary purpose is preventing roll surface degradation, maintaining dimensional tolerances, and extending campaign life between regrinds. Direct cooling systems dominate steel hot rolling installations where heat flux densities demand maximum thermal extraction, while active control systems represent the fastest-expanding technology segment as mills retrofit for variable product mixes. Flood lubrication retains mature share in paper manufacturing calendering lines where lower operating temperatures reduce system complexity.
EPA effluent guidelines under the Clean Water Act constrain coolant discharge chemistry for US metal fabricators, while REACH registration requirements govern biocide and corrosion inhibitor formulations across European supply chains. China's GB standards for industrial water reuse, enforced by MEE provincial bureaus, mandate minimum recycling ratios that favor closed-loop system architectures. Stakeholders must evaluate whether to prioritize sensor-driven predictive maintenance platforms or consolidated coolant chemistry management as the primary axis of differentiation in aftermarket service contracts.
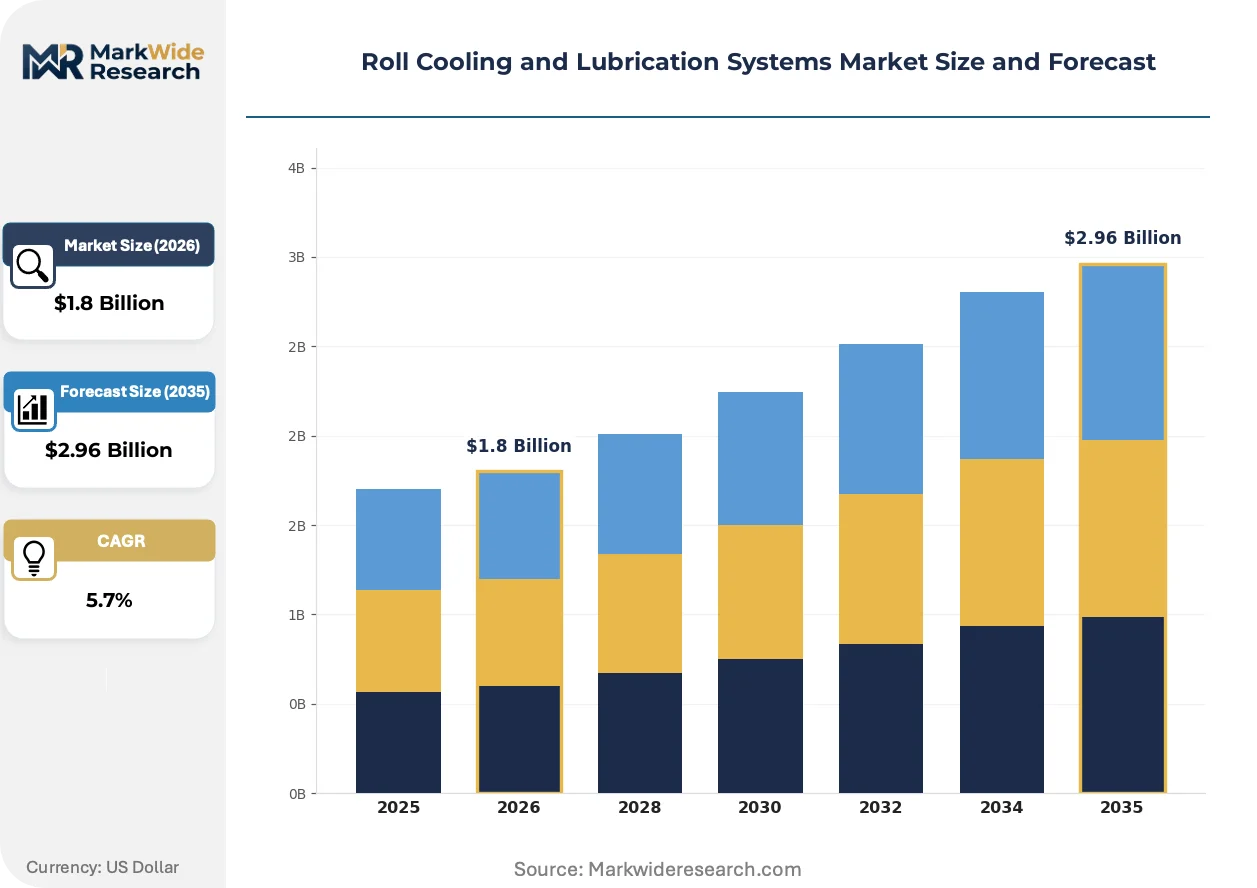
Market Dynamics
Precision cooling technology is compressing maintenance intervals and forcing capital redeployment toward sensor-integrated architectures that predict thermal stress before roll surface degradation occurs.
Growth Catalysts
- China's GB water reuse standards:MEE provincial enforcement mandates minimum recycling ratios that favor closed-loop cooling architectures in integrated steel plants.
- Aluminum tandem mill expansion:High-speed cold rolling lines require droplet-size consistency below 50 microns, driving precision nozzle retrofits.
- Ruhr industrial cluster concentration:Germany's dense supplier ecosystem accelerates technology diffusion through localized engineering services.
Market Restraints
- Specialized alloy supply concentration:Tungsten carbide nozzle substrates face sourcing bottlenecks from limited powder metallurgy suppliers in Central Europe.
- REACH biocide registration costs:ECHA compliance timelines extend 18-24 months for new corrosion inhibitor formulations, freezing product pipelines.
- Direct cooling system lock-in:Steel hot rolling installations face high retrofit costs when shifting to active control architectures.
Strategic Opportunities
- India's PLI scheme for specialty steel:Government production-linked incentives fund greenfield mill construction requiring integrated cooling packages.
- Predictive maintenance convergence:Vibration sensors married to thermal imaging enable campaign-life extension contracts as a service revenue stream.
- EU Industrial Emissions Directive retrofit wave:2025 compliance deadlines force coolant chemistry upgrades across aging flat-rolling lines.
Industry Challenges
- Hydrodynamic simulation expertise scarcity:Computational fluid dynamics specialists command premium wages, constraining OEM engineering capacity.
- Legacy DCS integration complexity:Siemens S7 and Allen-Bradley PLC architectures require custom gateway development for IoT sensor deployment.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Cooling and Lubrication Systems Market Trends and Innovations
Active control architectures are compressing the technology lifecycle for fixed-orifice cooling systems as mills demand real-time thermal mapping across variable product schedules.
Electromagnetic flow control valves is supplanting mechanical needle valves in high-pressure coolant circuits. European aluminum producers are retrofitting tandem mills with these actuators to enable strip-width-dependent flow modulation. The technology is supplanting fixed-zone cooling banks that waste coolant during narrow-strip campaigns.
EPA effluent guidelines under the Clean Water Act are constraining discharge chemistry for US metal fabricators. The regulations force zero-liquid-discharge system investments or third-party waste hauling contracts. California and Ohio fabricators face the steepest compliance costs due to regional water scarcity premiums.
Steel producers are unbundling aftermarket service contracts from original equipment supply. Major integrated mills now separately procure coolant chemistry management, nozzle refurbishment, and predictive maintenance platforms. This fragmentation is most advanced in Germany and Japan where multi-vendor technical audits have become standard procurement practice.
Roll Cooling and Lubrication Systems Market Segmentation
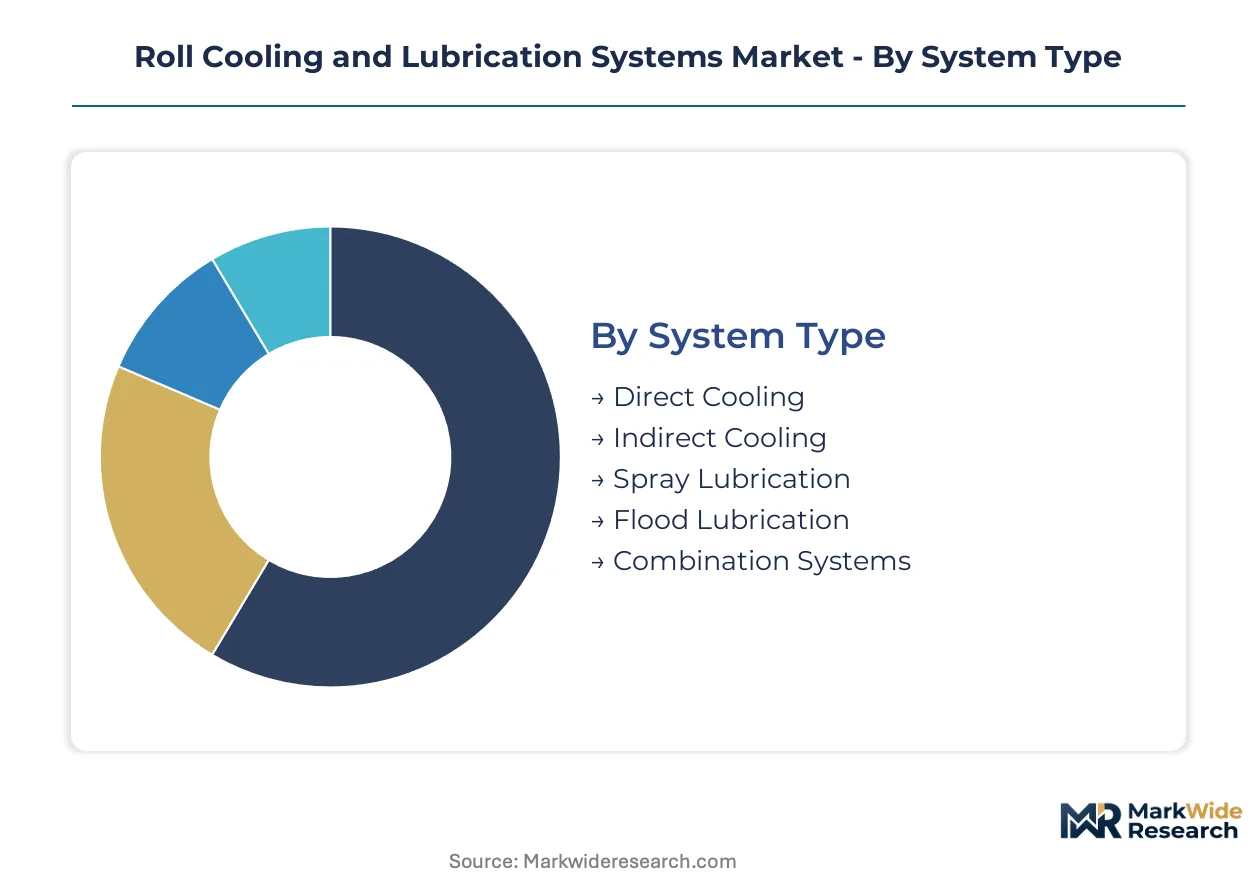
Roll cooling and lubrication systems fragment across four dimensions that determine procurement economics. System type governs capital outlay and thermal performance ceilings. Technology selection locks in operational flexibility and regulatory compliance pathways.
System Type:
Margin pools concentrate in combination architectures that bundle cooling and lubrication into single capital contracts.
- Direct Cooling:High-pressure coolant impinges directly on roll surfaces at 5-40 bar, extracting maximum thermal flux in steel hot rolling where strip temperatures exceed 900°C. Demand clusters in integrated steel plants across China's Hebei province and Germany's Ruhr industrial cluster as producers chase tighter surface quality tolerances.
- Active Control Systems:Real-time thermal mapping and variable flow modulation enable strip-width-dependent cooling, reducing coolant waste during narrow-strip campaigns. European aluminum tandem mills in Belgium and Norway are retrofitting fixed-zone banks with electromagnetic valve architectures.
- Indirect Cooling:Heat exchangers isolate coolant from roll surfaces, suiting applications requiring precise temperature stability without contamination risk.
- Spray Lubrication:Precision nozzles deliver droplet sizes below 50 microns for friction control in high-speed cold rolling lines.
- Flood Lubrication:Submersion-based systems dominate paper manufacturing calendering where lower operating temperatures reduce complexity.
- Combination Systems:Integrated cooling-lubrication packages capture premium pricing from greenfield mill construction in India under PLI scheme incentives.
Direct cooling holds installed capacity. Active control systems are rotating up the share rankings.
Technology:
Technology selection pivots on water reuse mandates that favor closed-loop architectures over once-through designs.
- Closed Loop:Recycling systems with filtration and chemical treatment meet China's GB water reuse standards enforced by MEE provincial bureaus. Integrated steel plants face minimum recycling ratio mandates that render open systems economically unviable.
- Hydrodynamic:Proprietary nozzle designs with computational fluid dynamics optimization reduce coolant consumption through controlled turbulence patterns. SMS group anchors this segment with algorithmic flow control.
- Hydrostatic:Pressure-balanced bearing cooling extends roll campaign life in heavy-plate mills.
- Air Cooling:Eliminates water treatment costs for low-heat-flux applications in specialty steel finishing.
- Active Control Systems:Sensor-integrated architectures with predictive thermal stress algorithms command aftermarket service premiums.
Closed loop dominates new installations. Active control systems are climbing the fastest.
Application:
Application mix shifts with base metal demand cycles and regional industrial policy.
- Steel Rolling:Hot and cold rolling lines consume the largest coolant volumes, with flat-rolling mills driving precision cooling retrofits for automotive-grade surface finishes.
- Aluminum Processing:High-speed tandem cold rolling requires droplet-size consistency below 50 microns, concentrating demand for precision spray technology.
- Paper Manufacturing:Calendering lines favor flood lubrication due to lower thermal loads and reduced system complexity.
- Plastic Extrusion:Profile and sheet cooling systems manage lower temperatures but require corrosion-resistant materials for polymer compatibility.
- Textile Finishing:Calender rolls for fabric pressing operate at moderate speeds with specialized lubricant formulations.
Steel rolling maintains volume leadership. Aluminum processing is gaining share fastest.
End User:
End user procurement sophistication determines service contract fragmentation and aftermarket revenue capture.
- Metal Fabricators:US EPA effluent guidelines under the Clean Water Act constrain discharge chemistry, forcing zero-liquid-discharge investments or third-party waste hauling contracts in California and Ohio.
- Paper Mills:Mature installed base with long replacement cycles favors consumables and refurbishment over new system sales.
- Chemical Processors:Corrosion-resistant system specifications dominate procurement for aggressive coolant chemistries.
- Plastic Manufacturers:Temperature control precision requirements vary by polymer type and extrusion speed.
- Textile Plants:Regional concentration in Turkey and Bangladesh drives localized supplier relationships.
Metal fabricators anchor technology adoption. Chemical processors are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Ruhr industrial cluster while Chinese producers compete on system cost under MEE water reuse mandates. This asymmetry shapes procurement patterns across steel and aluminum rolling installations.
Germany
Ruhr industrial cluster density anchors precision cooling demand from SMS group and Primetals Technologies engineering services. EU Industrial Emissions Directive compliance deadlines force coolant chemistry upgrades across aging flat-rolling lines. Düsseldorf and Dortmund host concentrated supplier ecosystems accelerating technology diffusion.
China
Hebei province integrated steel plants drive closed-loop system adoption under GB water reuse standards enforced by MEE provincial bureaus. Minimum recycling ratio mandates render open cooling architectures economically unviable. Beijing-Tianjin-Hebei corridor concentrates retrofit demand from state-owned steel producers.
United States
EPA effluent guidelines under the Clean Water Act constrain coolant discharge chemistry for metal fabricators in California and Ohio. Zero-liquid-discharge system investments dominate compliance strategies where regional water scarcity premiums apply. Great Lakes manufacturing belt faces steepest upgrade costs from legacy direct cooling installations.
India
PLI scheme production-linked incentives fund greenfield specialty steel mill construction requiring integrated cooling packages. Government capital subsidies compress payback periods for precision control architectures. Gujarat and Maharashtra industrial corridors concentrate new capacity announcements from JSW Steel and Tata Steel.
Belgium
European aluminum tandem mills in Genk and Liège retrofit fixed-zone cooling banks with electromagnetic valve architectures for strip-width-dependent flow modulation. REACH biocide registration costs through ECHA freeze alternative corrosion inhibitor pipelines. Flanders region hosts concentrated demand for droplet-size consistency below 50 microns.
Roll Cooling and Lubrication Systems Market Competitive Landscape
Concentration sits with integrated metallurgical equipment builders who bundle cooling systems with rolling mill overhauls. Full-line suppliers capture captive demand through capital-project packaging while component specialists compete on precision spray technology. Three archetypes dominate: integrated system builders, precision nozzle specialists, and hydrodynamic control algorithm developers. Competitive moves center on aftermarket service contract unbundling and predictive maintenance platform deployment.
Within the integrated system builder tier, Primetals Technologies and SMS group exemplify full-line metallurgical positioning. Lechler occupies a position among precision spray technology specialists serving high-speed aluminum tandem mills. These three anchors represent divergent capital-intensity strategies: bundled capital projects, proprietary nozzle design with algorithmic flow control, and droplet-size consistency specialization.
| Leading Market Players |
|---|
| Primetals Technologies |
| Lechler |
| SMS group |
| Danieli |
| ANDRITZ |
| Butech Bliss |
| Spraying Systems Co. |
| TMEIC |
| Fives Group |
| Others |
Pricing and Supply Chain Analysis
Ninety-day tungsten carbide powder inventory cycles concentrate pricing power with Central European powder metallurgy suppliers, forcing cooling system OEMs to absorb raw material volatility or pass through cost escalations to steel mill procurement teams. This lead-time exposure tightens margins for component specialists while integrated full-line builders buffer through captive project bundling.
Pricing Analysis
Configured-to-order pricing commands 25-40% premiums over standard catalog configurations for active control architectures with electromagnetic valve retrofits. Project-based long-term contracting dominates greenfield mill construction, with pricing stratifying across premium precision-cooling tiers, standard direct-cooling packages, and economy flood-lubrication lines. Cost compression in standard direct cooling intensifies as Chinese system builders compete on capital cost under MEE water reuse mandates. Metal fabricators in water-scarce US regions exhibit highest price sensitivity, while European aluminum tandem mills prioritize droplet-size consistency over unit economics.
Supply Chain Analysis
Strait of Malacca transit routes underpin tungsten carbide powder flows from Chinese rare earth processors to German nozzle manufacturers. Supply concentrates in China for rare earth processing, Germany for precision nozzle finishing, and Austria for powder metallurgy substrates. Raw material dependencies span tungsten carbide substrates, corrosion-resistant stainless steels, and high-pressure pump castings. Single-source vulnerability sits with limited Central European powder metallurgy suppliers capable of aerospace-grade tungsten carbide tolerances. Distribution runs through OEM direct sales for integrated mill projects and specialized distributors for aftermarket nozzle refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat anchored in regulatory entrenchment: MEE water reuse mandates and EU Industrial Emissions Directive deadlines create captive upgrade cycles that lock in incumbent relationships through compliance-driven procurement.
For Market Incumbents: Secure aftermarket service contract consolidation through predictive maintenance platform deployment, capturing fragmented coolant chemistry and nozzle refurbishment spend that mills currently unbundle. Deepen backward integration into tungsten carbide powder supply through offtake agreements with Austrian metallurgy specialists, insulating against single-source chokepoint risk from emerging Chinese rare earth processors. For New Entrants and Emerging Players: ECHA REACH biocide registration fast-tracks open white-space opportunities in alternative corrosion inhibitor formulations, where 18-24 month compliance timelines freeze incumbent product pipelines. Target India's PLI scheme greenfield mill construction as the most penetrable geography, where government capital subsidies compress payback periods for precision control architectures and local engineering partnerships overcome SMS group and Primetals Technologies relationship density. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned precision spray technology divisions lacking metallurgical integration scale. Long-term viability centers on sensor-integrated active control architectures displacing fixed-orifice installed base. Watch electromagnetic valve retrofit penetration rates in European aluminum tandem mills as the inflection signal for technology lifecycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Captures unbundled aftermarket service spend from JSW Steel and Tata Steel maintenance contracts. |
| Backward Integration into Tungsten Carbide Supply | Secures nozzle substrate supply against Austrian powder metallurgy bottlenecks. |
| REACH-Compliant Corrosion Inhibitor Development | Exploits ECHA registration freeze to displace incumbent biocide formulations. |
| PLI Scheme Greenfield Partnership | Locks in integrated cooling packages for Gujarat and Maharashtra specialty steel capacity. |
| Electromagnetic Valve Retrofit Programs | Enables strip-width-dependent flow modulation for Genk and Liège aluminum tandem mills. |
Research Methodology
A spread of perspectives from rolling mill maintenance directors, OEM aftermarket service heads, powder metallurgy procurement leads, and MEE provincial enforcement officers converged on the working assumptions for water reuse mandate impact. Primary interviews with plant engineers at Hebei province integrated steel mills and Belgian aluminum tandem operations combined with secondary validation through customs trade data, SEC filings from listed metallurgical equipment suppliers, and EU Industrial Emissions Directive compliance databases. Bottom-up installation counts triangulated against top-down capital expenditure flows from steel industry association reports.
Segmentation dimensions modeled span system type, technology architecture, base metal application, and end-user procurement sophistication across the projection horizon. CAGRs derived from weighted average of historical capacity expansion announcements, regulatory deadline clustering, and technology substitution curves. Industry-specific forecast inputs incorporate MEE provincial enforcement intensity variation and electromagnetic valve retrofit adoption rates in European aluminum cold rolling.
Underlying assumptions cover sustained MEE enforcement of GB water reuse standards and REACH biocide registration timeline stability, with deviation risk concentrated in China industrial policy pivot toward carbon reduction targets that could accelerate or delay steel mill capital cycles. Practitioners should keep alternative scenarios live as EU Industrial Emissions Directive compliance deadline enforcement rigor evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.