
 Europe Tank Insulation Market | 2026-2036
Europe Tank Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tank Insulation Market Insights
The EU Green Deal's industrial decarbonization targets are pivoting procurement criteria toward low-emission insulation systems across European process industries. ROCKWOOL International A/S leverages its stone wool expertise to dominate high-temperature petrochemical installations. BASF SE anchors the polyurethane segment through captive raw material integration and formulation leadership. Saint-Gobain competes across multiple material platforms, extending its glass wool capabilities into specialized tank applications.
Tank insulation comprises engineered thermal barriers applied to storage vessels for liquids, gases, and chemicals, typically specified by thermal conductivity values below 0.040 W/m·K and designed to minimize heat transfer across operating temperatures from cryogenic to above 500°C. Its primary purpose is energy conservation, process stability, and safety compliance in industrial fluid handling. Rigid insulation occupies the largest value share due to structural durability in outdoor petrochemical installations, while spray foam captures fastest growth through rapid application on complex tank geometries. The oil and gas end-user segment sustains the deepest volume base, though pharmaceuticals generates premium margin pools driven by validated cleanroom installation protocols.
EMA's construction product regulations, REACH chemical safety frameworks, and the EU F-Gas Regulation collectively mandate material transparency and phase down high-global-warming-potential blowing agents in polyurethane systems. CE marking requirements enforce consistent thermal performance testing across member states, shaping product development roadmaps and cross-border market access conditions. Stakeholders must monitor evolving ECHA substance restriction proposals and national building codes to anticipate material substitution timelines and certification burdens.
Market Dynamics
The EU F-Gas Regulation phase-down is forcing chemical storage operators across Germany and France to replace legacy blowing agents with low-global-warming-potential polyurethane formulations, compressing material substitution timelines and reshaping supplier qualification criteria.
Growth Catalysts
- REACH chemical safety frameworks:Mandatory substance transparency is accelerating specification of pre-certified insulation systems in pharmaceutical tank installations, reducing procurement cycle friction for validated cleanroom protocols.
- Cryogenic LNG infrastructure:Expanding regasification terminal capacity across Belgium and the Netherlands is pulling demand for vacuum-insulated panel systems with lambda values below 0.020 W/m·K.
- Stone wool thermal barriers:High-temperature petrochemical applications above 400°C are pivoting toward non-combustible mineral fiber solutions as CE marking enforcement tightens on fire safety performance.
Market Restraints
- Polyol feedstock volatility:Propylene oxide price swings directly compress margin stability for polyurethane foam manufacturers serving tank insulation contracts.
- Specialized applicator concentration:Certified spray foam installation capacity clusters in Germany's Rhine-Ruhr corridor, creating bottleneck risk for project timelines elsewhere.
- Technical thickness limitations:Rigid cellular plastics face maximum dimension constraints in large-diameter storage vessels above 50 meters, restricting single-layer application efficiency.
Strategic Opportunities
- Eastern European chemical corridor:Poland and Czech Republic process industries remain underpenetrated for high-performance cryogenic insulation relative to Western European specification intensity.
- Digital thermal monitoring integration:IoT sensor-embedded insulation systems are converging with predictive maintenance platforms to create outcome-based thermal performance contracts.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms are incentivizing energy-efficient tank retrofits as scope 1 emission accounting tightens for process industries.
Industry Challenges
- Certified installer scarcity:ATEX-qualified spray foam applicators for explosive atmosphere tank environments remain concentrated in legacy industrial regions, constraining project scaling.
- Multi-material system integration:Hybrid insulation designs combining rigid board with flexible jacketing require specialized engineering coordination that extends design-phase timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tank Insulation Market |
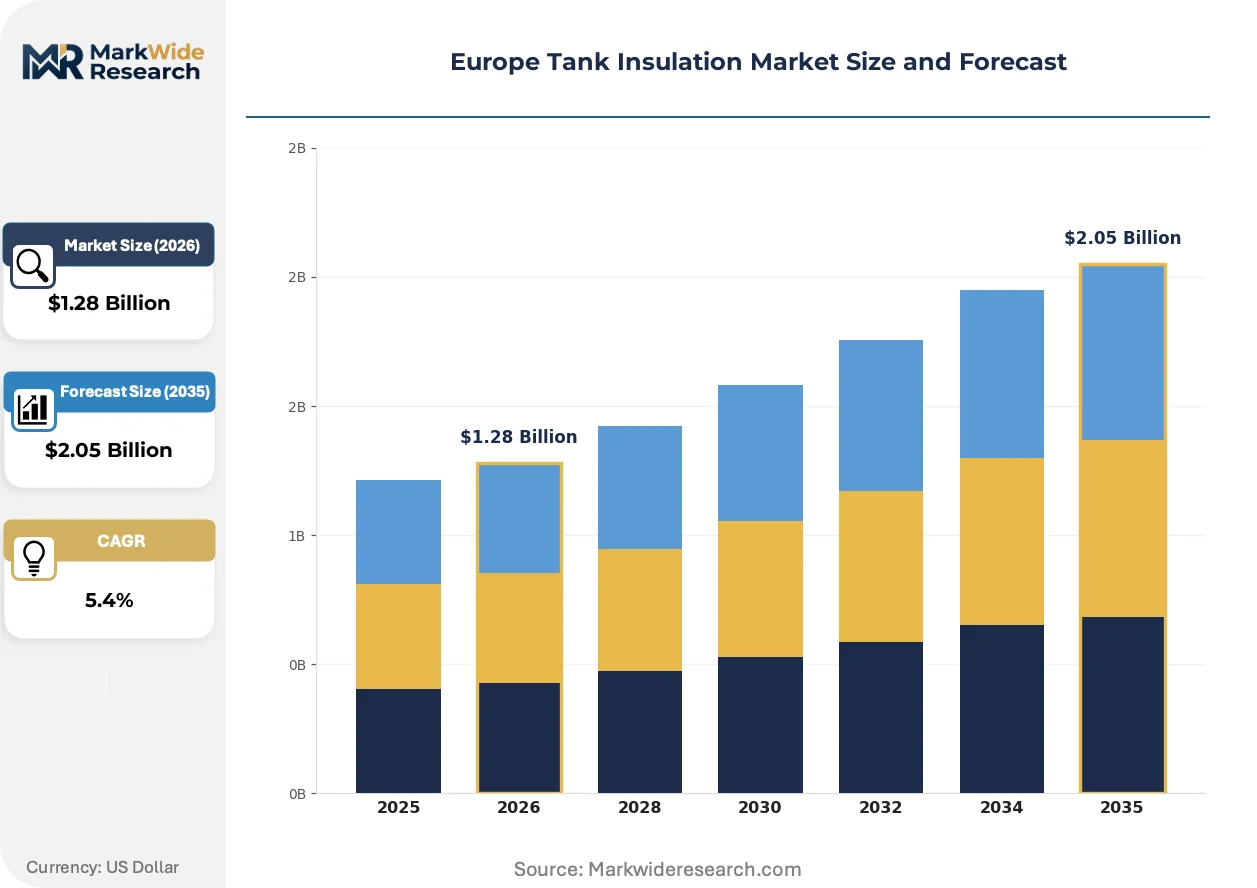
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Insulation, Rigid Insulation, Spray Foam, Blanket Insulation End User: Oil & Gas, Chemicals, Food & Beverage, Pharmaceuticals Installation Type: Onsite Installation, Prefabricated Installation, Modular Installation, Custom Installation Material: Fiberglass, Polystyrene, Polyurethane, Mineral Wool |
| Companies Covered | Kingspan Group, ARMACELL, ROCKWOOL International A/S, Saint-Gobain, BASF SE, Owens Corning, Knauf Insulation, Covestro AG, Johns Manville, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tank Insulation Market Trends and Innovations
Automation of thermal performance verification and material traceability is compressing quality assurance cycles across European tank insulation procurement. Digital tools now penetrate specification, installation monitoring, and long-term asset management phases simultaneously.
Robotic spray application systems are automating complex tank geometry coverage that previously required extensive manual scaffolding and rework. Petrochemical terminal operators in Rotterdam and Antwerp are piloting these platforms for spherical storage vessels. The technology is automating thickness consistency control while reducing labor exposure in confined-space installations.
EMA construction product regulations now mandate digital performance declarations through centralized EU databases, replacing paper-based technical documentation. Manufacturers must upload lambda value test results and fire reaction classifications to market access portals before CE marking issuance. Small and mid-sized insulation contractors in Southern Europe face adaptation costs that favor larger integrated system providers with dedicated compliance functions.
Buyers are consolidating specification authority at the engineering-procurement-construction contractor level, displacing fragmented owner-operator material selection. Multi-site chemical companies now delegate insulation standards to EPC firms with framework agreements spanning multiple countries. This concentration is most visible in Germany's chemical triangle, where BASF and Covestro have standardized thermal performance tiers across their maintenance portfolios.
Europe Tank Insulation Market Segmentation
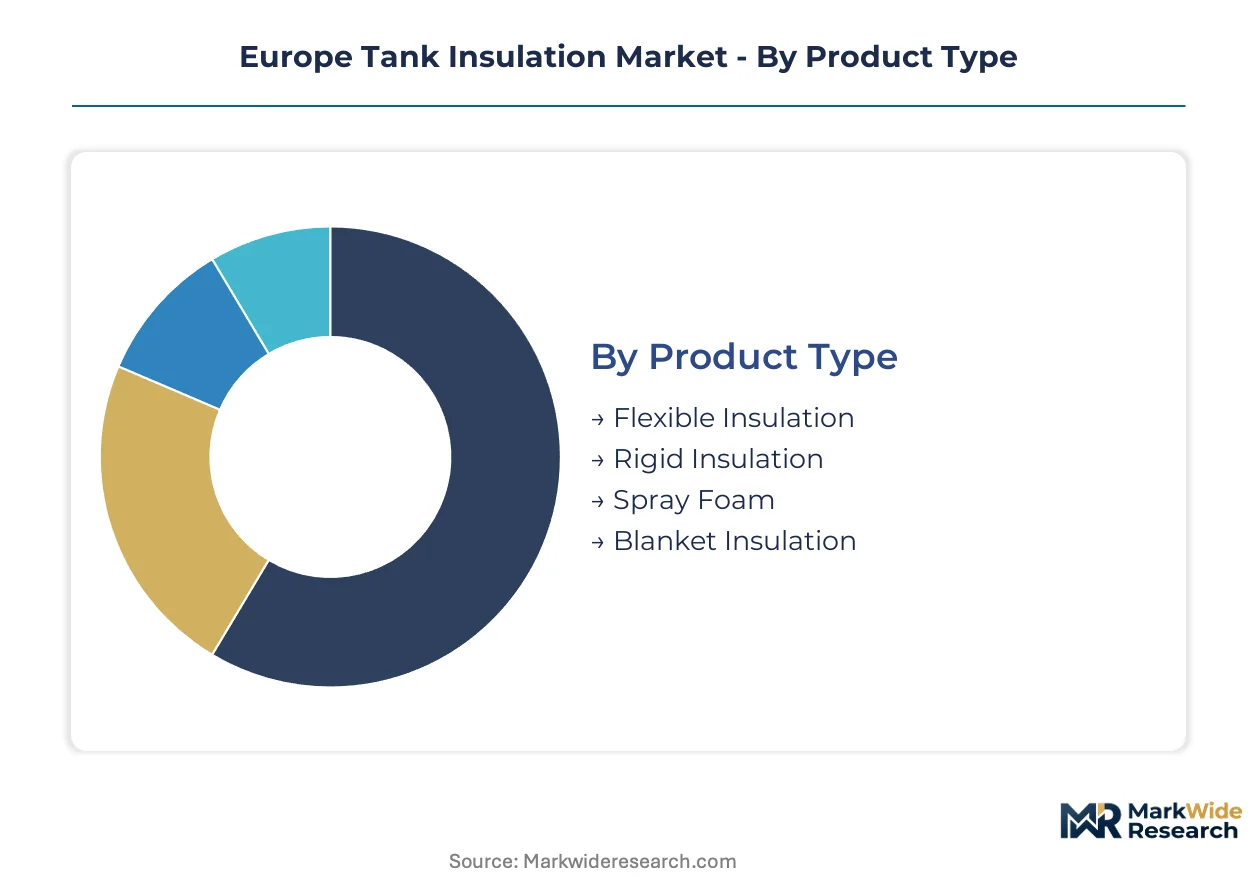
Tank insulation procurement in Europe hinges on matching thermal performance specifications to operating environment constraints. Engineers specify across four intersecting dimensions—product form, end-use application, installation method, and base material—each carrying distinct regulatory and cost implications under EU construction product regulations.
Product Type:
Buyers prioritize structural durability versus application speed when selecting insulation form factors for outdoor petrochemical installations.
- Rigid Insulation:Pre-formed cellular plastic or mineral fiber boards deliver dimensional stability in large-diameter storage vessels exposed to mechanical stress. German chemical corridor operators specify rigid systems for BASF and Covestro tank farms where thermal cycling resistance outweighs installation labor costs.
- Spray Foam:Polyurethane formulations adapt to complex spherical and cylindrical geometries without prefabrication lead times. Rotterdam terminal operators deploy robotic spray platforms for regasification infrastructure where manual scaffolding access proves prohibitive.
- Flexible Insulation:Jacketing materials accommodate thermal expansion in piping connections and irregular tank appendages.
- Blanket Insulation:Roll-format mineral wool serves high-temperature applications above 400°C where non-combustibility mandates dominate specification.
Rigid Insulation leads on scale; Spray Foam leads on momentum.
End User:
Process temperature requirements and regulatory scrutiny intensity differentiate sector procurement patterns across European industrial clusters.
- Oil & Gas:Cryogenic LNG storage and refined product terminals demand lambda values below 0.020 W/m·K for energy conservation at scale. Belgium and Netherlands regasification capacity expansions pull vacuum-insulated panel specifications for sub-zero containment.
- Chemicals:Continuous thermal management for reactive intermediates drives replacement cycles tied to EU F-Gas Regulation phase-down schedules. French and German storage operators accelerate polyurethane system upgrades to meet blowing agent transition deadlines.
- Pharmaceuticals:Validated cleanroom installation protocols command premium pricing for thermal barriers in biologics storage.
- Food & Beverage:Temperature-controlled liquid storage for dairy and brewing applications emphasizes hygiene-certifiable surface finishes.
Oil & Gas anchors volume throughput; Pharmaceuticals captures margin concentration.
Installation Type:
Project timeline compression and labor availability constraints shape method selection across European construction markets.
- Onsite Installation:Conventional application of prefabricated panels or spray systems at existing facilities dominates retrofit demand. Rhine-Ruhr corridor contractors concentrate certified ATEX-qualified applicator capacity for explosive atmosphere environments.
- Prefabricated Installation:Factory-assembled insulation modules reduce field labor exposure and accelerate turnaround for turnaround maintenance windows.
- Modular Installation:Standardized panel systems for repeatable tank geometries streamline procurement for multi-site chemical operators with framework agreements.
- Custom Installation:Engineered solutions for non-standard vessel dimensions or extreme temperature differentials extend design-phase coordination timelines.
Onsite Installation dominates retrofit activity; Prefabricated Installation gains share in greenfield chemical investments.
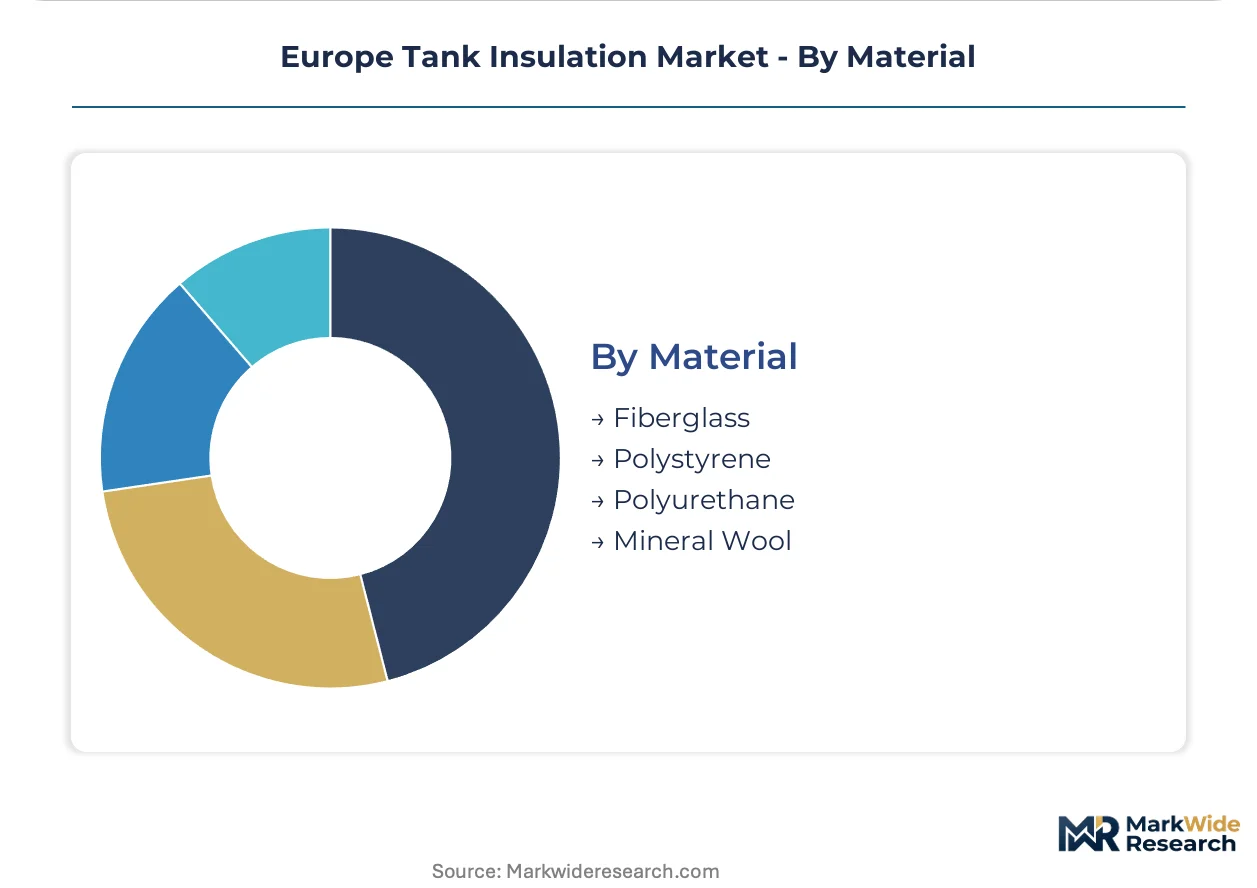
Material:
REACH chemical safety frameworks and CE marking fire performance classifications constrain material substitution pathways.
- Polyurethane:Closed-cell foam formulations with enhanced lambda values displace legacy materials in cryogenic applications. Raw material integration at BASF SE anchors supply security for high-performance blowing agent transitions.
- Mineral Wool:Stone wool and glass wool barriers satisfy non-combustibility mandates for high-temperature petrochemical installations above 400°C. ROCKWOOL International A/S leverages CE marking enforcement to defend specification share.
- Fiberglass:Glass fiber composites serve moderate-temperature chemical storage with cost-efficient thermal conductivity performance.
- Polystyrene:Expanded and extruded cellular plastics retain position in ambient-temperature liquid storage where fire safety requirements permit.
Polyurethane commands technology investment intensity; Mineral Wool holds regulatory-defended positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tank insulation technology first scaled within Germany's chemical corridor during the post-war industrial expansion, establishing thermal management protocols that subsequently diffused across European process industries. This historical foundation continues to shape specification standards and supplier relationships throughout the continent.
Germany
BASF SE and Covestro AG operate integrated chemical complexes in the Rhine-Ruhr corridor requiring continuous thermal management upgrades. The EU F-Gas Regulation phase-down is compressing material substitution timelines for polyurethane blowing agents. Ludwigshafen and Leverkusen anchor the continent's densest concentration of cryogenic storage infrastructure.
France
Chemical storage operators accelerate specification of high-performance insulation systems to meet tightening environmental compliance schedules. REACH chemical safety frameworks mandate substance transparency for pharmaceutical tank installations. The Lyon-Grenoble industrial arc concentrates validated cleanroom thermal barrier demand for biologics storage.
Netherlands
Expanding regasification terminal capacity pulls demand for vacuum-insulated panel systems with lambda values below 0.020 W/m·K. Rotterdam terminal operators pilot robotic spray application platforms for spherical storage vessels. The Port of Rotterdam complex hosts Europe's largest concentration of LNG infrastructure thermal management projects.
Belgium
Cryogenic LNG infrastructure investments drive specification of ultra-low thermal conductivity systems for sub-zero containment. CE marking enforcement tightens on fire safety performance for petrochemical installations. Antwerp's chemical cluster concentrates demand for high-temperature mineral fiber solutions above 400°C.
Poland
Process industries remain underpenetrated for high-performance cryogenic insulation relative to Western European specification intensity. EU Green Deal industrial decarbonization targets are pivoting procurement criteria toward low-emission systems. The Upper Silesian industrial region is emerging as a retrofit opportunity zone for chemical storage thermal upgrades.
Europe Tank Insulation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European tank insulation market. Integrated chemical conglomerates with captive raw material positions battle specialized insulation fabricators focused on application technology. Three archetypes dominate: multinational material science conglomerates with backward integration into polyol feedstocks, dedicated mineral fiber specialists leveraging fire safety regulatory tailwinds, and regional system integrators bundling installation services. Consolidation pressure is accelerating through framework agreement concentration at EPC contractors, while technology licensing partnerships proliferate for robotic spray application platforms.
Among material science conglomerates, BASF SE anchors the polyurethane segment through upstream control over formulation chemistry. ROCKWOOL International A/S exemplifies the mineral fiber specialist archetype, defending specification share through CE marking enforcement on non-combustibility mandates. Saint-Gobain occupies a diversified position spanning multiple material platforms including glass wool capabilities. These three entities represent distinct competitive vectors: feedstock-integrated chemistry, regulatory-defended mineral solutions, and multi-technology portfolio breadth.
| Leading Market Players |
|---|
| Kingspan Group |
| ARMACELL |
| ROCKWOOL International A/S |
| Saint-Gobain |
| BASF SE |
| Owens Corning |
| Knauf Insulation |
| Covestro AG |
| Johns Manville |
| Others |
Pricing and Supply Chain Analysis
Robotic spray application platforms are compressing labor cost structures while concentrating procurement power among EPC contractors with multi-site framework agreements across Germany and France. This technology shift simultaneously reduces field installation hours and elevates volume discount leverage for integrated chemical operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated cleanroom installations from conventional petrochemical retrofits and ambient liquid storage. Price differentiation hinges on CE marking certification grade and blowing agent compliance tier under EU F-Gas Regulation schedules. Cost compression in standard-grade polyurethane systems is intensifying because propylene oxide feedstock volatility transmits directly into contract margin pressure. Chemical storage operators in the Rhine-Ruhr corridor exhibit lowest price sensitivity due to captive maintenance budgets, while Polish process industries remain most price-sensitive given specification lag versus Western European benchmarks.
Supply Chain Analysis
Regional distribution centers in Germany, Belgium, and the Netherlands anchor hub-and-spoke patterns for rigid insulation boards and spray foam chemical kits. Polyol feedstocks draw from integrated petrochemical complexes at BASF Ludwigshafen and Covestro Leverkusen, while stone wool production rests on mineral fiber processing in Denmark and Germany. Single-source vulnerability concentrates in ATEX-qualified applicator capacity clustered around the Rhine-Ruhr corridor. Distribution runs through EPC contractor channel partners with multi-country framework agreements rather than direct owner-operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU F-Gas Regulation compliance deadlines pivot procurement toward premium low-GWP polyurethane formulations with validated lambda performance.
For Market Incumbents: Anticipate margin compression in conventional blowing agent formulations by accelerating backward integration into next-generation hydrofluoroolefin chemistry. Defend specification share through preemptive CE marking investment for robotic spray application platforms before Antwerp and Rotterdam terminal operators consolidate contractor panels. Threat substitution from vacuum-insulated panel systems in sub-zero LNG infrastructure demands formulation leadership in lambda values below 0.020 W/m·K. For New Entrants and Emerging Players: Begin with Poland's Upper Silesian chemical corridor where cryogenic insulation specification intensity trails Western European benchmarks by several compliance cycles. Target pharmaceutical validated cleanroom installations in the Lyon-Grenoble arc where premium pricing tolerates new entrant qualification timelines. Go-to-market angle should bundle IoT thermal monitoring sensors with insulation contracts to differentiate from commodity material suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with installation service revenue but without captive polyol feedstock positions. Long-term viability favors acquisition targets with ATEX-certified applicator networks and EPC framework agreement access spanning multiple EU member states. Signal to watch is acceleration of EU Green Deal carbon border adjustment mechanism implementation tightening scope 1 emission accounting for chemical storage operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-GWP Blowing Agents | Secures formulation leadership as EU F-Gas Regulation phase-down compresses substitution timelines for polyurethane systems. |
| Robotic Spray Application Deployment | Antwerp and Rotterdam terminal operators pilot automated platforms for spherical vessel coverage with thickness consistency control. |
| CE Marking Pre-Certification Investment | EMA construction product regulations mandate digital performance declarations uploaded before market access portal issuance. |
| IoT Thermal Monitoring Integration | Sensor-embedded insulation converges with predictive maintenance platforms for outcome-based thermal performance contracts. |
| Eastern European Distribution Expansion | Poland and Czech Republic process industries remain underpenetrated for high-performance cryogenic insulation specification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with plant managers at BASF and Covestro complexes, procurement leads at Rotterdam terminal operators, EPC contractors with multi-site framework agreements, and technical R&D directors at mineral fiber specialists. Secondary validation drew from ECHA substance restriction proposals, CE marking databases, EU F-Gas Regulation implementation schedules, and customs trade data for polyol and isocyanate flows. Bottom-up project pipeline analysis triangulated against top-down chemical sector capital expenditure patterns.
Segment-weighting approaches distributed value across product form, end-use application, installation method, and base material dimensions with additional granularity for EU regulatory compliance tier. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and replacement cycle assumptions. Forecast inputs incorporated REACH chemical safety framework substance restriction trajectories and EU Green Deal industrial decarbonization procurement pivot timing.
Several conditions sit outside the modeled scope, including potential suspension of EU F-Gas Regulation timelines, breakthrough vacuum insulation panel cost reductions, and geopolitical disruption of propylene oxide feedstock flows. Forecasts reflect documented assumptions around regulatory enforcement consistency and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
AC Motor Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Gear Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Explosion Proof Motor Market