
 United Kingdom DC Motor Market | 2026-2036
United Kingdom DC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom DC Motor Market Insights
Aftermarket predictive maintenance contracts is realigning how DC motor vendors capture lifetime value from UK industrial buyers. ABB Limited leverages its service network to lock in long-term maintenance agreements across Yorkshire manufacturing plants. Siemens AG anchors its position through integrated drive-motor-service bundles that reduce unplanned downtime for automotive clients. Parvalux specializes in bespoke motor assemblies for medical and mobility applications where technical support contracts command premium pricing.
A DC motor converts direct current electrical energy into mechanical rotation through electromagnetic interaction between stator windings and a rotor, with brushless variants employing electronic commutation via Hall-effect sensors to eliminate friction losses and extend operational life beyond twenty thousand hours. Brushless DC Motors dominate value capture due to their superior efficiency profiles and compatibility with variable-speed drives in precision applications. Brushed DC Motors retain volume leadership in cost-sensitive segments such as consumer appliances and basic automotive actuators where simplicity outweighs efficiency premiums. Stepper Motors occupy a specialized niche in robotics and CNC positioning equipment where discrete angular control determines system performance.
The UK's BEIS enforces MEES regulations that mandate minimum efficiency ratings for motors deployed in commercial and industrial buildings, directly filtering non-compliant equipment from retrofit opportunities. BSI certification under IEC 60034 efficiency classes shapes procurement specifications for OEMs supplying electric vehicle and medical device manufacturers. The Environment Agency's industrial emissions framework indirectly drives motor replacement cycles by linking permit compliance to energy intensity reductions. Stakeholders must monitor how post-Brexit divergence from EU ecodesign regulations alters testing protocols and market access requirements for imported motor assemblies.
Market Dynamics
The United Kingdom DC Motor Market is experiencing structural pressure from MEES efficiency mandates that filter non-compliant equipment from retrofit opportunities while electric vehicle procurement accelerates demand for brushless variants in drivetrain applications.
Growth Catalysts
- Net Zero Strategy:The UK's legally binding carbon reduction targets are forcing industrial estate operators to replace legacy motors with IE4-rated brushless units across Midlands manufacturing corridors.
- Electric vehicle drivetrain demand:Automotive OEMs are specifying high-torque brushless DC motors for auxiliary systems and power steering modules in battery-electric platforms.
- Logistics automation:Greater London distribution hubs are deploying precision DC motor arrays in automated guided vehicles and conveyor systems to meet same-day fulfillment requirements.
Market Restraints
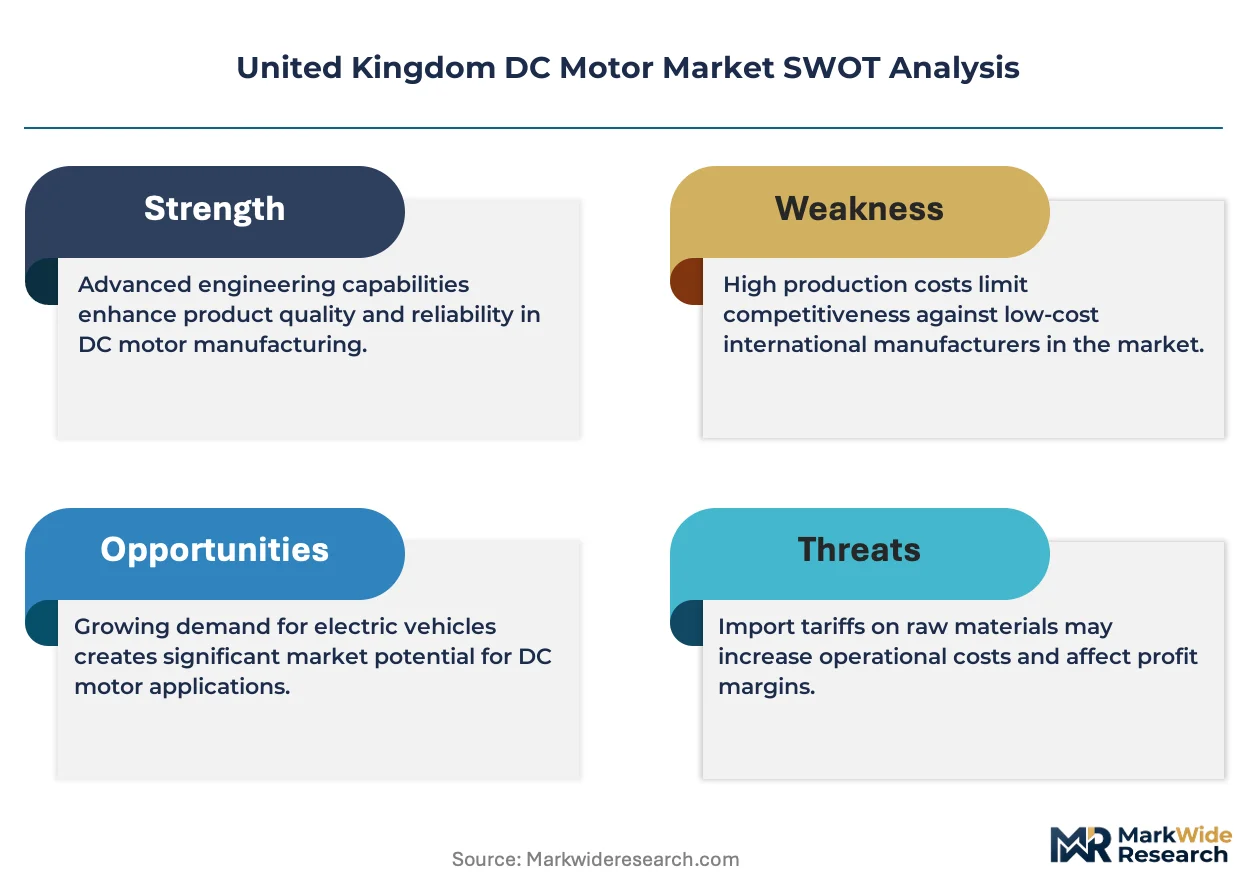
- Rare earth magnet dependency:Neodymium and dysprosium supply concentration in Chinese processing facilities exposes UK motor assemblers to price volatility and export restriction risk.
- Copper winding cost exposure:LME copper price fluctuations directly compress margin on custom wound stator assemblies for medical device OEMs.
- Post-Brexit certification divergence:Potential misalignment between UKCA marking requirements and retained EU ecodesign rules creates testing duplication for imported motor assemblies.
Strategic Opportunities
- Scotland offshore wind servicing:Aberdeen and Dundee port infrastructure investments are creating demand for marine-grade brushless motors in turbine maintenance vessels and jack-up platforms.
- Predictive maintenance bundling:Industrial buyers in Yorkshire are accepting ten-year service contracts that lock in motor replacement cycles and sensor-based condition monitoring.
- Medical mobility expansion:NHS procurement frameworks for powered wheelchairs and patient lifts are specifying British-manufactured motor assemblies with localized technical support.
Industry Challenges
- Electromagnetic compatibility certification:BS EN 55014 testing timelines for variable-speed drive integration are extending product launch cycles by four to six months for SME motor vendors.
- Legacy system integration:Food processing plants in the West Midlands face control architecture mismatches when retrofitting modern brushless units onto 1990s-era PLC networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom DC Motor Market |
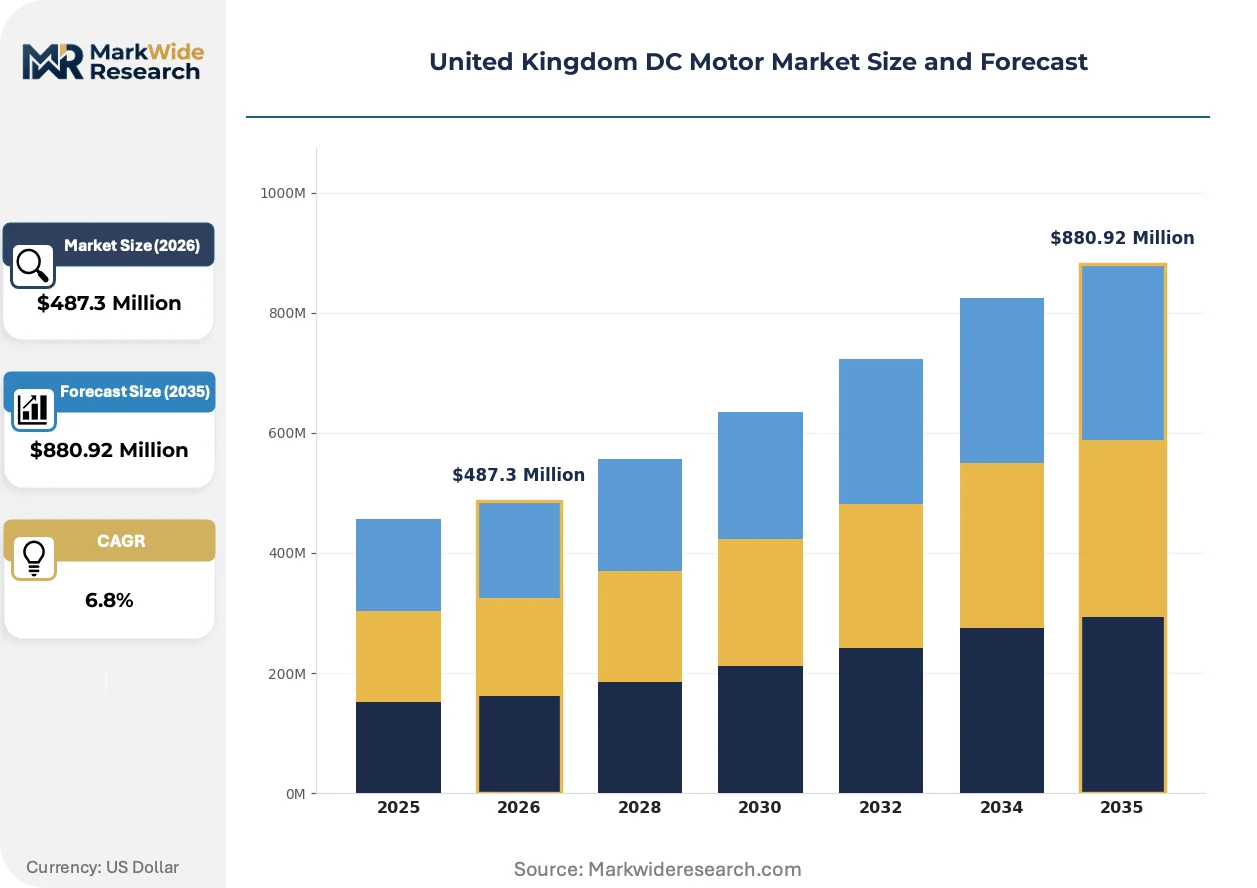
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless DC Motors, Brushed DC Motors, Stepper Motors, Coreless Motors End User: Automotive, Consumer Electronics, Robotics, Industrial Machinery Application: Electric Vehicles, Home Appliances, HVAC Systems, Medical Devices Technology: Permanent Magnet, Shunt, Series, Compound |
| Companies Covered | Nidec Corporation, Oriental Motor (UK) Ltd, ABB Limited, Faulhaber Group, Maxon, AMETEK Inc, Siemens AG, Parvalux, Johnson Electric Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom DC Motor Market Trends and Innovations
Integrated sensor architectures and digital twin commissioning are compressing deployment timelines for precision motion systems across UK manufacturing and healthcare infrastructure.
Sensor-integrated brushless DC motors with embedded torque and temperature monitoring are automating condition-based maintenance scheduling for automotive tier-one suppliers in the West Midlands. BMW Group and Jaguar Land Rover procurement teams are specifying these smart motor variants for assembly line robotics. The technology is automating the transition from calendar-based replacement to predictive failure detection, reducing unplanned downtime in high-volume production environments.
BEIS enforcement of tightened MEES standards for motors above 0.75kW is mandating IE4 efficiency minimums in commercial building HVAC retrofits across England and Wales. The regulation is disqualifying brushed motor inventories from public sector procurement frameworks. Hospital estates in Manchester and Birmingham are accelerating replacement cycles to avoid penalty clauses under the Environment Agency's emissions reporting requirements.
Industrial buyers are consolidating vendor relationships around integrated drive-motor-service bundles that transfer operational risk to equipment suppliers. Automotive and logistics operators in the East Midlands are rejecting component-only procurement in favor of performance-guaranteed contracts. This consolidation is most visible among warehouse automation deployers in the Milton Keynes logistics cluster, where uptime penalties now exceed equipment capital costs in contract valuation.
United Kingdom DC Motor Market Segmentation
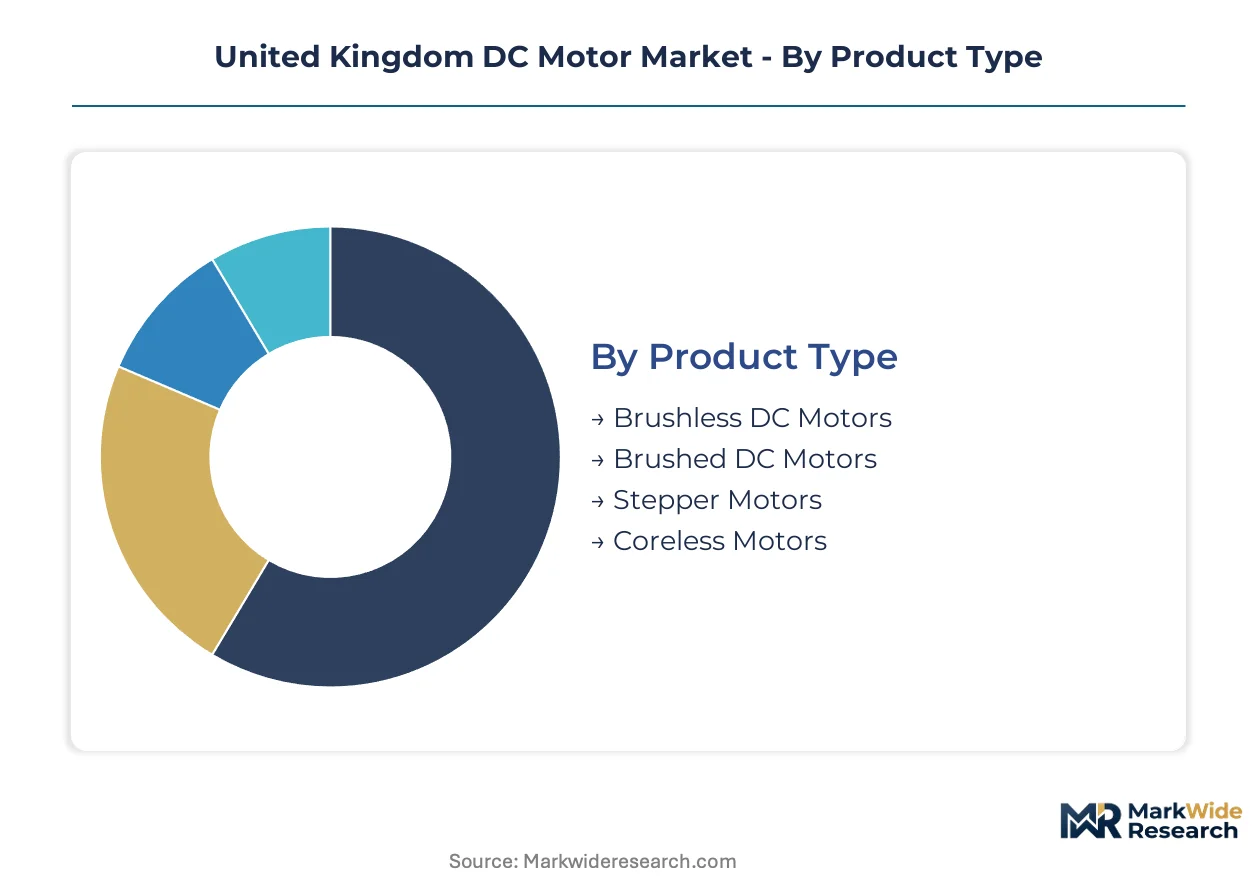
Segmentation in the United Kingdom DC Motor Market reveals how capital intensity and technical specifications fragment procurement patterns across automotive, industrial, and healthcare verticals. Buyers prioritize efficiency ratings and integration complexity differently depending on end-use criticality and regulatory exposure.
Product Type:
Capital intensity varies sharply across motor architectures, with permanent magnet rotor assemblies and electronic commutation systems demanding substantially higher upfront tooling investment than conventional wound-field designs.
- Brushless DC Motors:Electronic commutation via Hall-effect sensors eliminates mechanical brush wear, enabling operational lifespans exceeding twenty thousand hours in continuous-duty applications. Demand concentrates in West Midlands automotive tier-one suppliers specifying these units for electric power steering and thermal management pumps, driven by OEM mandates for reduced warranty exposure.
- Brushed DC Motors:Mechanical commutation through carbon brushes delivers cost-optimized torque in intermittent-duty cycles where maintenance access is routine. Greater London logistics operators deploy these in conveyor actuators and sortation equipment, constrained by MEES efficiency thresholds that now exclude sub-IE3 rated units from public sector retrofit frameworks.
- Stepper Motors:Discrete angular positioning via toothed rotors and pulsed stator excitation serves CNC machining centers in Sheffield manufacturing clusters.
- Coreless Motors:Cylindrical coil rotors without iron cores minimize inertia for high-acceleration medical pump and diagnostic equipment in Cambridge biotech corridors.
Brushless DC Motors absorb the bulk of installed capacity in new-build industrial automation; Coreless Motors are expanding most quickly in precision medical device manufacturing.
End User:
Application-specific performance requirements reshape procurement criteria, with automotive and robotics buyers prioritizing torque density while industrial machinery operators emphasize retrofit compatibility.
- Automotive:Battery-electric platform proliferation is accelerating specification of high-torque brushless units for drivetrain cooling, brake-by-wire actuation, and active suspension systems. Jaguar Land Rover and BMW Group procurement teams in the Midlands are mandating integrated sensor architectures for predictive maintenance integration.
- Robotics:Collaborative and industrial robot OEMs demand precision motion control with harmonic drive compatibility for assembly and material handling applications. Oxfordshire and Bristol automation clusters are driving specification of compact frameless motor geometries that maximize torque-to-weight ratios in articulated arm designs.
- Consumer Electronics:Miniaturized brushed and coreless variants serve personal care appliances and smart home devices where cost thresholds dominate technical performance.
- Industrial Machinery:Legacy equipment retrofit cycles in Yorkshire manufacturing estates favor drop-in brushed motor replacements compatible with existing variable-frequency drive infrastructure.
Automotive commands the largest share of premium motor procurement value; Robotics is climbing the fastest as UK automation density converges toward German and Japanese benchmarks.
Application:
Regulatory pressure and lifecycle cost accounting are diverging procurement patterns between electrification applications subject to vehicle-type approval and building systems governed by MEES efficiency mandates.
- Electric Vehicles:Auxiliary system electrification—thermal management, steering assistance, braking—requires brushless architectures rated for automotive temperature and vibration profiles. Nissan Sunderland and Vauxhall Ellesmere Port assembly operations are localizing motor sourcing to reduce supply chain exposure.
- Medical Devices:Powered wheelchairs, patient lifts, and surgical equipment demand British-manufactured assemblies with localized technical support under NHS procurement frameworks. Manchester and Birmingham hospital estates are specifying IE4-rated brushless units for HVAC-linked equipment to satisfy Environment Agency emissions reporting.
- HVAC Systems:Commercial building retrofits across England and Wales are replacing legacy induction motors with electronically commutated brushless variants to meet tightened MEES standards for motors above 0.75kW.
- Home Appliances:White goods manufacturers specify cost-optimized brushed motors for washing machine drums and refrigerator compressors where efficiency premiums do not recover within product replacement cycles.
Electric Vehicles anchors volume demand for high-performance brushless architectures; Medical Devices is gaining share fastest as NHS localization mandates reshape supplier qualification criteria.
Technology:
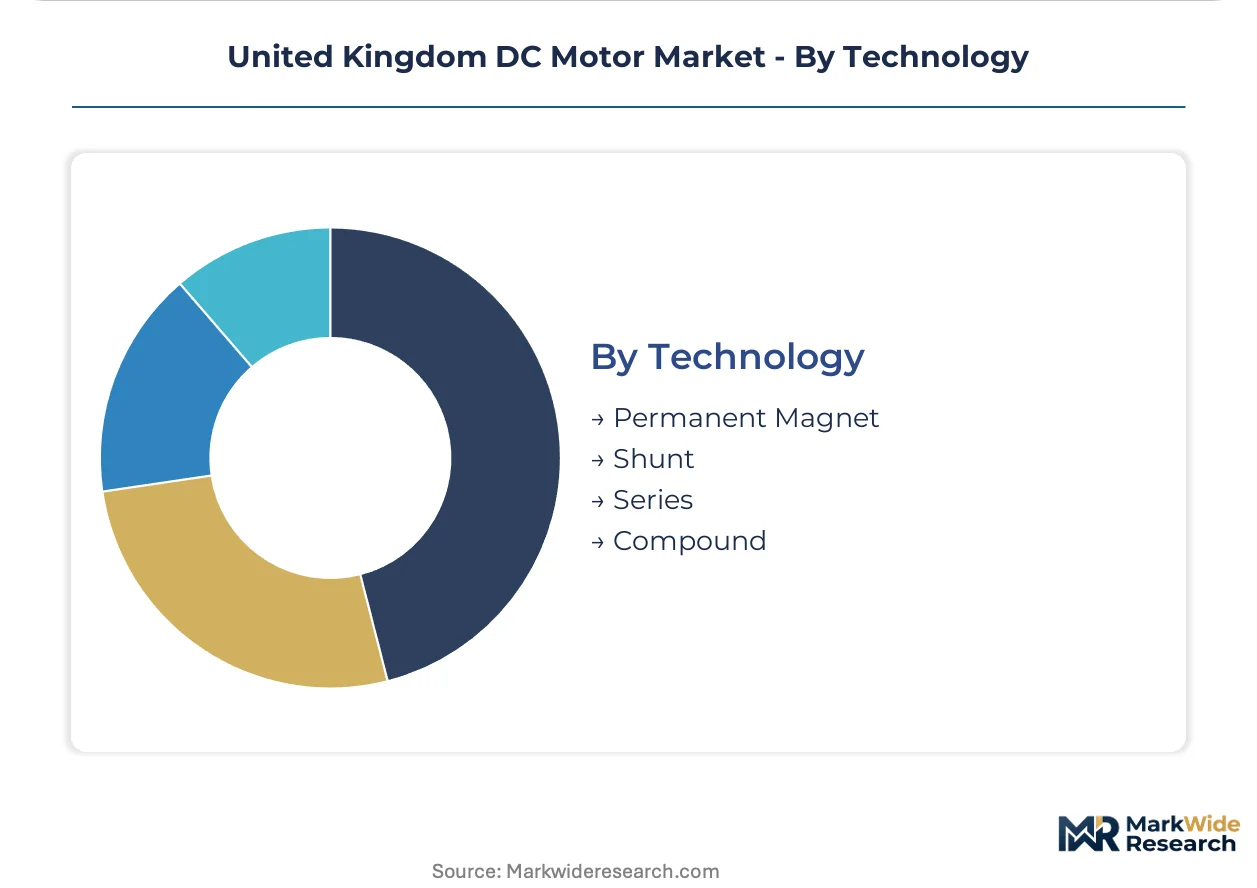
Field winding configuration determines efficiency profiles and control complexity, with permanent magnet designs commanding premium positioning despite rare earth material cost volatility.
- Permanent Magnet:Neodymium-iron-boron rotor excitation delivers superior torque density and efficiency in compact footprints. Brushless implementations dominate electric vehicle auxiliary systems and precision robotics, though Chinese rare earth processing concentration exposes UK assemblers to supply disruption risk.
- Shunt:Parallel field and armature winding configuration enables stable speed regulation under varying load conditions for machine tool spindle drives in Midlands manufacturing corridors.
- Series:High starting torque characteristics serve traction applications and crane hoists where load-lifting demands exceed continuous-duty ratings.
- Compound:Combined series and shunt winding properties balance starting torque with speed stability in printing presses and rolling mill equipment requiring controlled acceleration profiles.
Permanent Magnet technology carries the greatest installed base value; Compound winding configurations are expanding most quickly in heavy industrial equipment requiring both torque and precision control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK DC motor production concentrates in Midlands manufacturing corridors while consumption spreads across industrial estates and logistics hubs nationwide. Regional demand patterns diverge sharply between legacy manufacturing centers and emerging electrification clusters.
Midlands
Automotive tier-one suppliers in Birmingham and Coventry are procuring high-torque brushless units for electric power steering and thermal management systems. BEIS MEES regulations mandate IE4 efficiency minimums for motors above 0.75kW in commercial building retrofits across the West Midlands. Jaguar Land Rover and BMW Group procurement teams in Solihull are specifying integrated sensor architectures for predictive maintenance integration.
Greater London
Distribution hubs in Milton Keynes and Slough are deploying precision DC motor arrays in automated guided vehicles and conveyor systems for same-day fulfillment. The Environment Agency's industrial emissions framework links permit compliance to energy intensity reductions in logistics estates. Heathrow and Gatwick cargo zones are accelerating motor replacement cycles to avoid penalty clauses under tightening emissions reporting requirements.
Yorkshire
Manufacturing plants in Sheffield and Leeds are accepting ten-year predictive maintenance contracts that lock in motor replacement cycles and sensor-based condition monitoring. ABB Limited leverages its service network to capture long-term maintenance agreements across the region's industrial estates. Food processing facilities in Bradford face control architecture mismatches when retrofitting modern brushless units onto legacy PLC networks.
Scotland
Aberdeen and Dundee port infrastructure investments are creating demand for marine-grade brushless motors in offshore wind turbine maintenance vessels and jack-up platforms. The Scottish Government's net zero targets are forcing industrial operators to replace legacy motors with IE4-rated units across North Sea servicing operations. NHS Scotland procurement frameworks for powered wheelchairs are specifying British-manufactured motor assemblies with localized technical support.
North West England
Hospital estates in Manchester and Birmingham are accelerating replacement cycles to satisfy Environment Agency emissions reporting requirements. Manchester's biotech corridor is driving specification of coreless motors for high-acceleration medical pump and diagnostic equipment. Parvalux specializes in bespoke motor assemblies for medical and mobility applications where technical support contracts command premium pricing in the region.
United Kingdom DC Motor Market Competitive Landscape
Top-tier vendors anchor integrated drive-motor-service bundles, while mid-tier specialists compete on bespoke assemblies for medical and mobility niches. Siemens AG and ABB Limited dominate through performance-guaranteed contracts that transfer operational risk to equipment suppliers. Two strategic archetypes define the landscape: diversified industrial conglomerates leveraging service networks, and focused specialists capturing premium pricing in regulated medical segments. Competitive moves concentrate on predictive maintenance bundling and geographic localization to satisfy NHS and automotive procurement frameworks.
Within the diversified industrial tier, Siemens AG and ABB Limited exemplify the integrated service model that Yorkshire manufacturing plants and Midlands automotive clients now demand. Parvalux occupies a specialist position where bespoke motor assemblies for medical and mobility applications command premium pricing under NHS procurement frameworks. These three companies represent the competitive spectrum from scale-driven bundled offerings to precision-focused technical support contracts.
| Leading Market Players |
|---|
| Nidec Corporation |
| Oriental Motor (UK) Ltd |
| ABB Limited |
| Faulhaber Group |
| Maxon |
| AMETEK Inc |
| Siemens AG |
| Parvalux |
| Johnson Electric Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Electronic commutation adoption in brushless DC architectures is simultaneously compressing per-unit manufacturing costs and concentrating procurement leverage among vertically integrated motor assemblers serving UK automotive and medical device OEMs. This dual restructuring forces mid-tier vendors to absorb rare earth magnet price volatility or cede share to suppliers with captive neodymium sourcing arrangements.
Pricing Analysis
Margin tightening in standard-efficiency brushed motors reflects copper winding cost exposure and MEES-driven demand collapse for sub-IE3 rated units. Three-tier pricing structure across premium IE4 brushless, standard IE3 variants, and economy brushed units separates procurement pools by regulatory compliance burden. Pricing pressure stems from Chinese rare earth export restrictions inflating permanent magnet rotor costs. Logistics operators in Greater London exhibit highest price sensitivity, while NHS procurement frameworks for powered wheelchairs tolerate premium pricing for localized technical support.
Supply Chain Analysis
Freight cost volatility on Asia-Europe routes is forcing UK motor assemblers to reevaluate just-in-time magnet procurement from Chinese processing facilities. Neodymium-iron-boron permanent magnets, copper wire, and silicon steel laminations draw from concentrated Chinese, Chilean, and German supply bases respectively. Single-source vulnerability in rare earth magnet refining exposes assemblers to export license delays. Distribution runs through Midlands-based tier-one suppliers and direct OEM contracts rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom DC Motor Market operates as a cost-of-compliance arena where BEIS MEES regulations erect certification barriers that favor incumbents with established IE4 testing infrastructure and BSI approval pathways.
For Market Incumbents: Anticipate margin compression in brushed motor segments by accelerating predictive maintenance bundling across Yorkshire manufacturing estates. Lock in ten-year service contracts with sensor-based condition monitoring to defend against low-cost Eastern European entrants. Prioritize backward integration into permanent magnet sourcing to offset Chinese rare earth price volatility. For New Entrants and Emerging Players: NHS procurement frameworks for powered wheelchairs and patient lifts represent the most penetrable white-space channel, as localization mandates disqualify non-UK assemblers from technical support contracts. Target Scotland's offshore wind servicing corridor where Aberdeen port infrastructure investments outpace established vendor coverage. Lead with marine-grade brushless architectures for turbine maintenance vessels as the differentiated entry wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking predictive maintenance capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor post-Brexit divergence between UKCA marking requirements and retained EU ecodesign rules as the critical inflection signal for asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Bundling | Ten-year service contracts with ABB and Siemens lock in replacement cycles across Midlands automotive plants. |
| Permanent Magnet Backward Integration | Captive neodymium sourcing insulates assemblers from Chinese export restriction risk on rare earth processing. |
| IE4 Efficiency Certification Investment | BSI approval under tightened MEES standards qualifies vendors for public sector HVAC retrofit frameworks. |
| NHS Localization Partnership | British-manufactured motor assemblies with localized technical support command premium pricing in Manchester procurement. |
| Marine-Grade Brushless Development | Aberdeen and Dundee port investments create first-mover advantage in offshore wind turbine maintenance vessel motors. |
Research Methodology
Multi-period observation of BEIS MEES enforcement patterns, NHS procurement framework amendments, and automotive OEM supplier qualification criteria anchored the trend analysis, supplemented by interviews with plant engineers at West Midlands tier-one suppliers, maintenance directors across Yorkshire manufacturing estates, NHS biomedical equipment procurement managers, and aftermarket service heads at integrated drive-motor vendors. Secondary validation drew from BSI certification registries, Environment Agency emissions reporting databases, UK trade customs records for motor and magnet imports, and SEC filings of listed motor component suppliers. Bottom-up segment sizing triangulated against top-down industrial automation capex forecasts.
Segment-weighting across product type, end user, application, and technology dimensions shaped the analytical framework over the projection horizon. Modeled categories included brushless versus brushed architectures, automotive versus medical versus industrial verticals, electric vehicle auxiliary systems versus HVAC retrofits, and permanent magnet versus wound-field configurations. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and OEM platform electrification roadmaps. Forecast inputs incorporated rare earth magnet price trajectory assumptions and post-Brexit certification divergence scenarios.
Caveats apply where Chinese rare earth export restrictions, LME copper price spikes, or UK-EU regulatory misalignment on ecodesign testing protocols could materially shift the outlook. Forecasts reflect documented assumptions on automotive electrification penetration and NHS localization enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Japan AC Motor Market