
 US Residential HVAC Systems Market | 2026-2036
US Residential HVAC Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential HVAC Systems Market Insights
The Inflation Reduction Act is repositioning the cost-of-entry calculus for residential HVAC manufacturers and installers. Carrier leverages its manufacturing scale to navigate the new efficiency threshold requirements, while Trane Technologies sustains technology leadership in variable refrigerant flow systems. Rheem Manufacturing Company anchors its competitive stance through backward integration into heat pump compressors.
US Residential HVAC Systems encompass climate control equipment designed to regulate temperature, humidity, and air quality within single-family homes and multi-unit dwellings, typically operating on vapor-compression refrigeration cycles with seasonal energy efficiency ratio ratings of 14-25 SEER for cooling and 80-98% AFUE for heating. Their primary purpose centers on occupant comfort, indoor air quality management, and energy expenditure optimization across diverse climate zones. Heat pumps command the fastest-expanding product category as electrification mandates displace fossil fuel furnaces, while smart thermostat integration creates margin concentration at the technology layer rather than the equipment base. Ductless systems capture disproportionate share in retrofit installations where existing forced-air infrastructure proves incompatible.
EPA refrigerant phase-down rules under the AIM Act, DOE appliance efficiency standards, and state-level building electrification codes collectively reshape product portfolios and certification requirements for market participants. NHTSA-uncovered transport emissions benchmarks indirectly pressure residential energy budgets, tightening the linkage between automotive and home efficiency regulatory frameworks. Stakeholders must monitor the trajectory of state-level gas hookup bans and their amplification through utility rebate programs.
Market Dynamics
The Inflation Reduction Act's tax credit architecture is compressing payback periods for high-efficiency heat pump installations, forcing manufacturers to reconfigure product portfolios around electrification-ready specifications while installers retool workforce capabilities for refrigerant transitions.
Growth Catalysts
- Electrification mandates:State-level gas hookup bans in California, New York, and Washington are accelerating furnace-to-heat pump replacement cycles among single-family homeowners.
- DOE efficiency standards:The 2023 SEER2 testing protocol is disqualifying legacy inventory and stimulating demand for 16+ SEER equipment across Sun Belt cooling markets.
- Utility rebate stacking:Mid-Atlantic and Northeastern utilities are layering federal IRA credits with state incentives, reducing net installed costs for cold-climate heat pumps.
Market Restraints
- Copper and aluminum volatility:Coil and tubing input costs swing with commodity markets, compressing margins for equipment OEMs unable to pass through price adjustments.
- Compressor supply concentration:Asian-manufactured rotary and scroll compressors dominate the mid-tier segment, exposing distributors to ocean freight and tariff exposure.
- Refrigerant transition friction:EPA AIM Act phase-down schedules for R-410A are creating inventory stranding risk for contractors holding pre-2025 equipment.
Strategic Opportunities
- Ductless mini-split penetration:Retrofit installations in older Northeast housing stock bypass incompatible forced-air infrastructure entirely.
- Smart thermostat integration:Utility demand-response programs are creating recurring revenue attachment points for HVAC-as-a-service models.
- Cold-climate heat pump performance:Minnesota and Wisconsin regulatory thresholds for sub-zero operation are opening premium product tiers previously served by dual-fuel systems.
Industry Challenges
- EPA Section 608 certification backlog:Technician credentialing delays are constraining installation capacity during peak seasonal demand windows.
- Refrigerant handling infrastructure:R-454B and R-32 conversion requires shop-level equipment retooling and transport container modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential HVAC Systems Market |
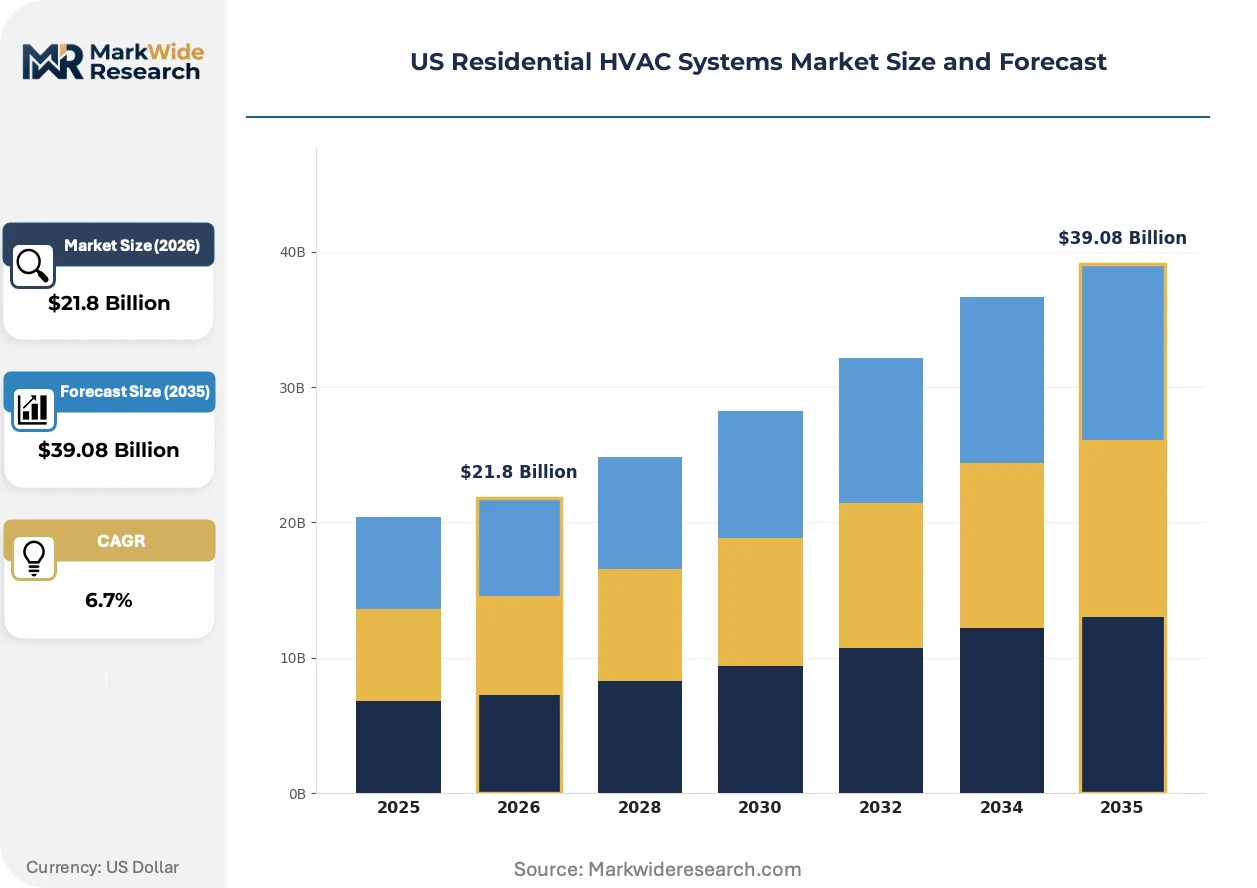
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $39.08 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Air Conditioners, Heat Pumps, Furnaces, Ductless Systems Technology: Smart Thermostats, Variable Refrigerant Flow, Solar-Integrated, Geothermal End User: Homeowners, Landlords, Property Managers, Builders Installation Type: Retrofit, New Construction, Replacement, Modular |
| Companies Covered | Carrier, Lennox International, Trane Technologies, Rheem Manufacturing Company, Daikin Industries, Johnson Controls, Mitsubishi Electric, Emerson Electric, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential HVAC Systems Market Trends and Innovations
Equipment intelligence and refrigerant chemistry are converging to redefine performance benchmarking, with manufacturers racing to certify systems under stricter testing protocols while embedding connectivity layers that shift value capture toward software-enabled efficiency optimization.
Variable refrigerant flow technology is overtaking fixed-capacity systems in new construction specifications. Multi-zone VRF architectures allow simultaneous heating and cooling across residential zones, cutting energy consumption by matching output to load rather than cycling on-off. Sun Belt builders are specifying VRF as standard in luxury subdivisions, compressing market share for conventional split systems in the premium tier.
EPA refrigerant regulations under the AIM Act are forcing product redesign cycles. The mandated reduction in hydrofluorocarbon production is pushing manufacturers toward mildly flammable A2L alternatives like R-454B and R-32, requiring redesigned safety systems and technician training protocols. Southern states with longer cooling seasons face compressed transition timelines as 2025 production limits approach.
Homeowner purchasing patterns are fragmenting across channel types. Big-box retailers are capturing replacement demand through financing-integrated online platforms, while traditional HVAC contractors defend position through maintenance-contract bundling. Texas and Florida markets show the sharpest channel divergence, with digital-native buyers accepting remote diagnostics and contractor-matching algorithms over established dealer relationships.
US Residential HVAC Systems Market Segmentation
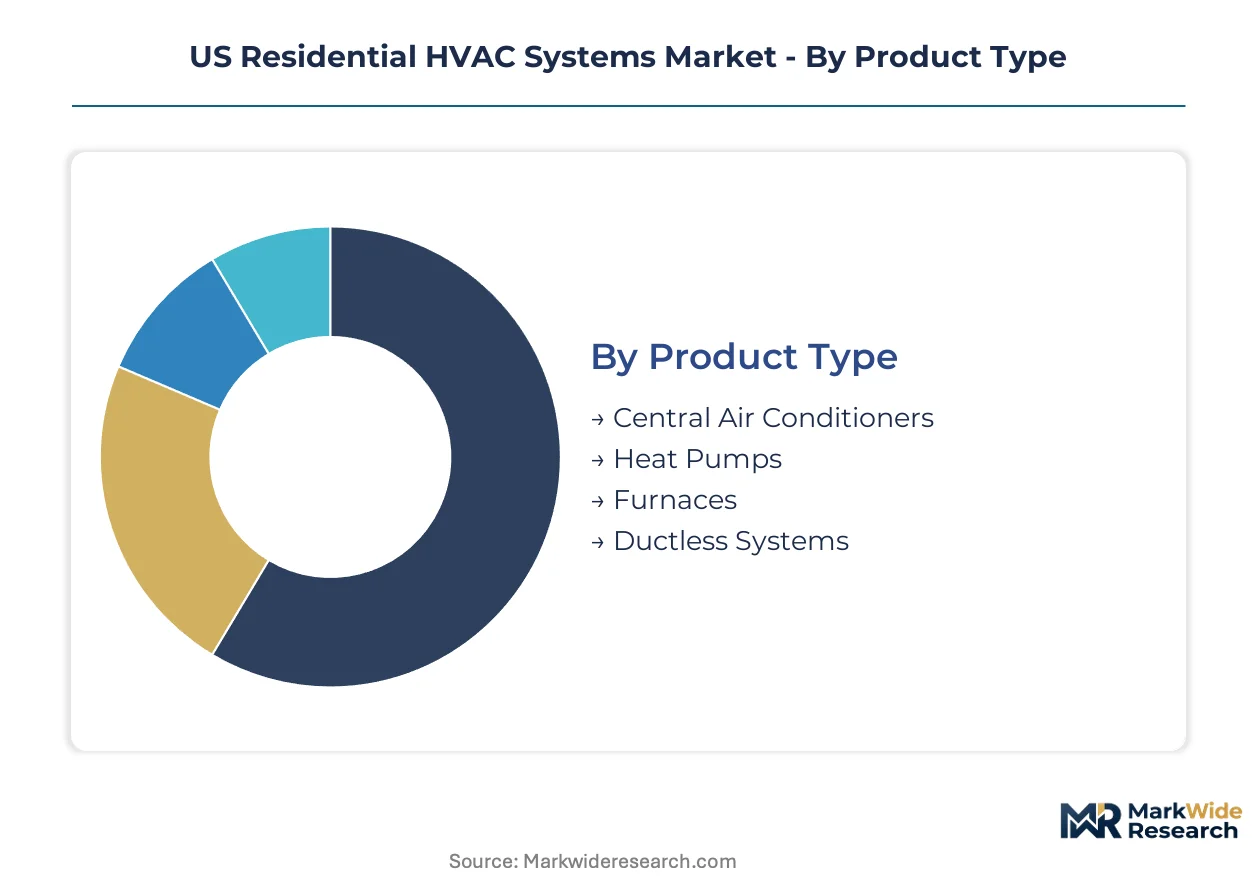
Segmentation in US residential HVAC reveals how electrification mandates, refrigerant transitions, and channel fragmentation create divergent profit pools across equipment categories and buyer types. Understanding these fault lines shapes portfolio allocation and go-to-market execution.
Product Type:
Equipment selection hinges on regional climate severity, existing infrastructure compatibility, and the economics of fuel-switching under IRA tax credits.
- Central Air Conditioners:Split-system architectures dominate Sun Belt cooling loads with SEER2 ratings now baseline at 16+. Texas and Florida replacement cycles accelerate as legacy 14-SEER inventory phases out under DOE enforcement.
- Heat Pumps:Air-source and cold-climate variants displace fossil fuel furnaces in electrification-mandate states. California and Washington single-family retrofits drive demand for dual-stage compressors rated to 5°F ambient operation.
- Furnaces:Natural gas and propane-fired units retain share in northern-tier states lacking cold-climate heat pump performance thresholds. Minnesota and Wisconsin dual-fuel configurations persist where sub-zero heating dominates.
- Ductless Systems:Mini-split and multi-zone configurations bypass forced-air infrastructure in Northeast housing stock. Massachusetts and New York brownstone retrofits favor wall-mounted cassettes with independent zone control.
Volume sits with central air conditioners; growth tilts toward heat pumps.
Technology:
Margin capture shifts upstream from commodity hardware to control layers and renewable integration, with certification requirements fragmenting addressable markets.
- Smart Thermostats:Wi-Fi-enabled learning algorithms and utility demand-response integration create recurring revenue attachment. Mid-Atlantic grid operators compensate homeowners for peak-load curtailment through automated setpoint adjustment.
- Variable Refrigerant Flow:Multi-zone inverter-driven compressors modulate capacity to match real-time load rather than cycling on-off. Arizona and Nevada luxury subdivisions specify VRF as standard, compressing conventional split-system share at the premium tier.
- Solar-Integrated:Photovoltaic-to-thermal coupling and DC-powered heat pumps reduce grid dependency. Hawaii and California self-generation mandates accelerate adoption where time-of-use rates penalize evening cooling loads.
- Geothermal:Ground-source heat pumps exploit stable subsurface temperatures for coefficient-of-performance advantages. Rural Midwest installations with available land outperform air-source alternatives in Iowa and Illinois heating-degree-day markets.
Smart thermostats command installed base dominance; VRF climbs fastest on new construction specifications.
End User:
Purchasing authority and holding period expectations drive equipment specification tiers and service contract attachment rates.
- Homeowners:Owner-occupiers prioritize comfort optimization and energy cost reduction over 15-20 year horizons. IRA credit awareness campaigns by Northeast utilities accelerate high-efficiency upgrade decisions among single-family detached households.
- Landlords:Multi-unit property owners minimize capital outlay and maintenance liability across tenant turnover cycles. Texas and Florida rental markets favor lowest-first-cost replacements with minimal smart feature integration.
- Property Managers:Professional management firms standardize fleet specifications across dispersed portfolios for technician training efficiency. National operators in the Sun Belt negotiate volume rebates with distributors for SEER2-compliant inventory.
- Builders:Production and custom home constructors face code-mandated efficiency minimums and buyer expectation management. California Title 24 compliance forces all-electric specifications in jurisdictions with gas hookup prohibitions.
Builders drive new equipment volume; homeowners generate replacement demand expansion.
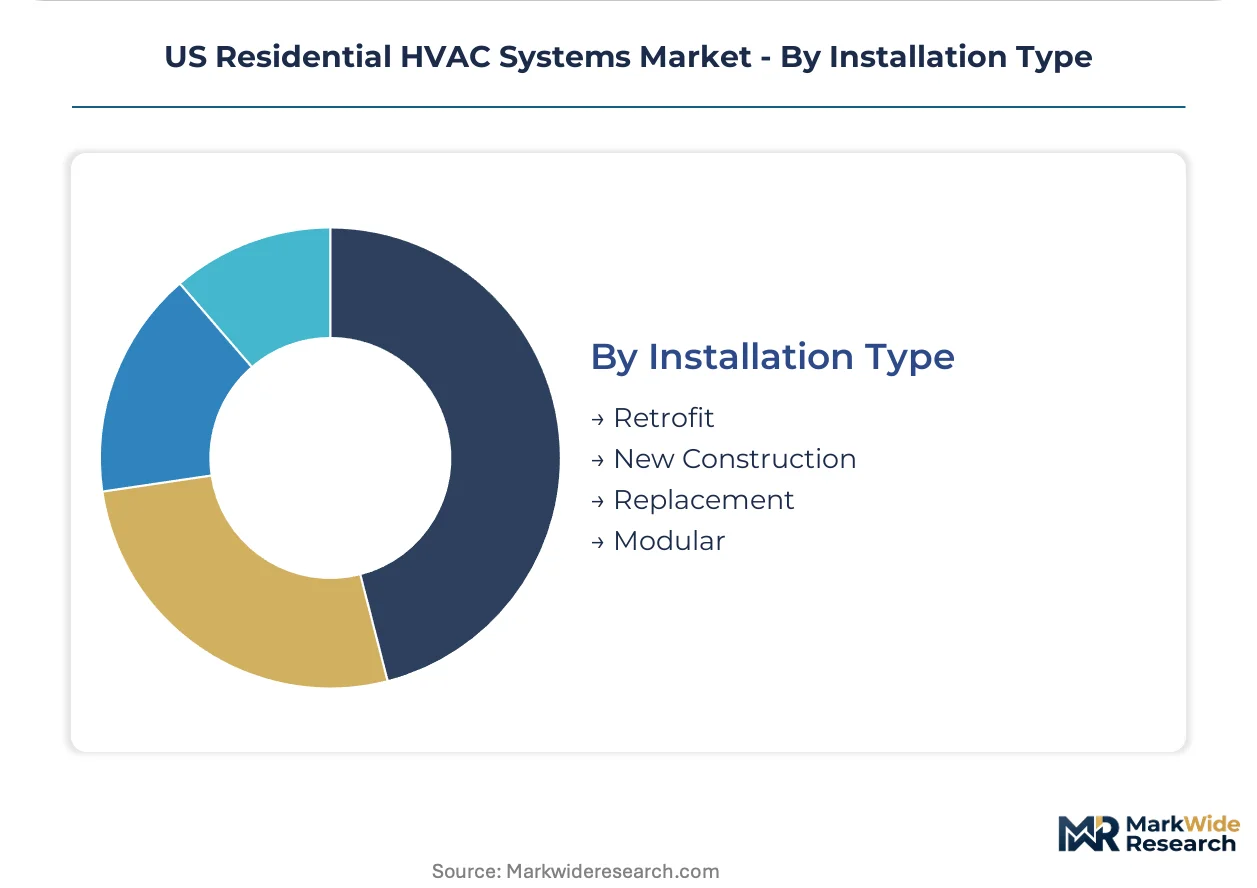
Installation Type:
Project origination determines labor intensity, margin structure, and the competitive set of channel participants vying for contract award.
- Retrofit:Existing structure modifications accommodate equipment upgrades without full system replacement. Northeast masonry construction with inaccessible ductwork favors ductless mini-split penetration over central system retrofit.
- New Construction:Greenfield installations allow integrated design of envelope, ductwork, and equipment sizing. Texas master-planned communities specify heat pump readiness for future electrification compliance.
- Replacement:Like-for-like equipment swaps during failure events compress decision windows and favor incumbent contractor relationships. Florida hurricane-season compressor failures spike emergency replacement demand through August-October.
- Modular:Prefabricated mechanical penthouses and packaged rooftop units serve multi-family and manufactured housing applications. Arizona retirement community developers specify modular heat pump skids for accelerated construction schedules.
Replacement commands transaction frequency; new construction offers specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Residential HVAC Systems Market demand concentrates in the Sun Belt states where cooling loads dominate and electrification mandates accelerate replacement cycles. Texas and Florida alone account for disproportionate replacement volume during peak summer failure windows. The Inflation Reduction Act's tax credit geography reshapes where high-efficiency upgrades pencil out economically.
Southeast (Florida/Georgia)
Hurricane-season compressor failures spike emergency replacement demand through August-October, compressing decision windows for single-family homeowners. Florida building codes mandate wind-load ratings that filter equipment eligibility. Miami-Dade and Broward counties concentrate distributor inventory staging for rapid deployment.
Southwest (Texas/Arizona)
Triple-digit summer temperatures drive 14-16 SEER replacement cycles at accelerated frequency compared to national averages. Texas master-planned communities specify heat pump readiness for future electrification compliance. Phoenix metropolitan area contractors report highest per-capita installation density for ductless mini-splits in retirement community retrofits.
California
Title 24 building standards and municipal gas hookup bans in Berkeley, San Jose, and San Francisco force all-electric specifications in new construction. CARB refrigerant regulations run ahead of federal EPA AIM Act timelines. Los Angeles and San Diego metro areas anchor West Coast distribution infrastructure for cold-climate heat pump imports.
Pacific Northwest (Washington/Oregon)
State-level building electrification codes in Washington accelerate furnace-to-heat pump displacement in single-family retrofits. Seattle and Portland metropolitan areas exhibit highest utility rebate stacking density, layering federal IRA credits with state incentives. Puget Sound region contractors specialize in cold-climate heat pump performance certification for sub-20°F operation.
Northeast Corridor (New York/Massachusetts)
Masonry construction with inaccessible ductwork favors ductless mini-split penetration over central system retrofit in brownstone housing stock. New York City Local Law 97 carbon caps pressure multi-family building owners toward electrification. Boston metropolitan area HVAC contractors report longest lead times for EPA Section 608 certified technicians during seasonal demand peaks.
US Residential HVAC Systems Market Competitive Landscape
US-based producers anchor the mass-market equipment tier; Japanese and European specialists hold premium positions in variable refrigerant flow and ductless architectures. The vendor base separates into three distinct tiers: integrated conglomerates with captive distribution, regional assemblers serving contractor networks, and import-dependent distributors. Strategic archetypes include efficiency-focused portfolio reconfigurers, refrigerant-transition specialists, and software-enabled service bundlers. Competitive moves concentrate on backward integration into compressor supply and utility partnership programs for demand-response integration.
Within the integrated conglomerate tier, Carrier and Trane Technologies exemplify scale-driven positioning across residential and commercial equipment portfolios. Rheem Manufacturing Company anchors a position through upstream control over heat pump compressor production. These three names illustrate how manufacturing depth, distribution reach, and regulatory compliance bandwidth separate sustainable participants from margin-compressed assemblers in the electrification transition.
| Leading Market Players |
|---|
| Carrier |
| Lennox International |
| Trane Technologies |
| Rheem Manufacturing Company |
| Daikin Industries |
| Johnson Controls |
| Mitsubishi Electric |
| Emerson Electric |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up HVAC contractors anchor pricing discipline through captive installation capacity, compressing spot-market arbitrage opportunities while feeding margin pressure upstream to equipment distributors. Their balance-sheet consolidation across Texas and Florida markets concentrates buying power, forcing manufacturers to absorb commodity volatility through contract pricing rather than pass-through mechanisms. This ownership pattern tightens the feedback loop between copper coil costs and end-user quotes.
Pricing Analysis
Premium pricing for sub-48-hour lead times separates emergency replacement transactions from scheduled installations, with Florida hurricane-season demand spikes extracting maximum margin from inventory-staging distributors. Three-tier pricing structure across premium, standard, and economy levels tracks SEER2 certification thresholds and cold-climate performance ratings. Cost compression in the mid-tier equipment segment intensifies because Asian compressor sourcing faces tariff exposure, while landlord buyers in Texas rental markets exhibit highest price sensitivity and luxury subdivision developers in Arizona show least.
Supply Chain Analysis
Regional distribution centers in Texas, Georgia, and California anchor hub-and-spoke patterns that position inventory within 200 miles of 80% of Sun Belt demand. Compressor manufacturing concentrates in China, Thailand, and Mexico, with copper tubing and aluminum coils drawing from domestic smelters and Canadian metal traders. Single-source vulnerability around rotary compressor supply from Southeast Asian plants creates inventory stranding risk during ocean freight disruptions. Distribution runs through manufacturer-direct branches and independent distributor networks serving contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
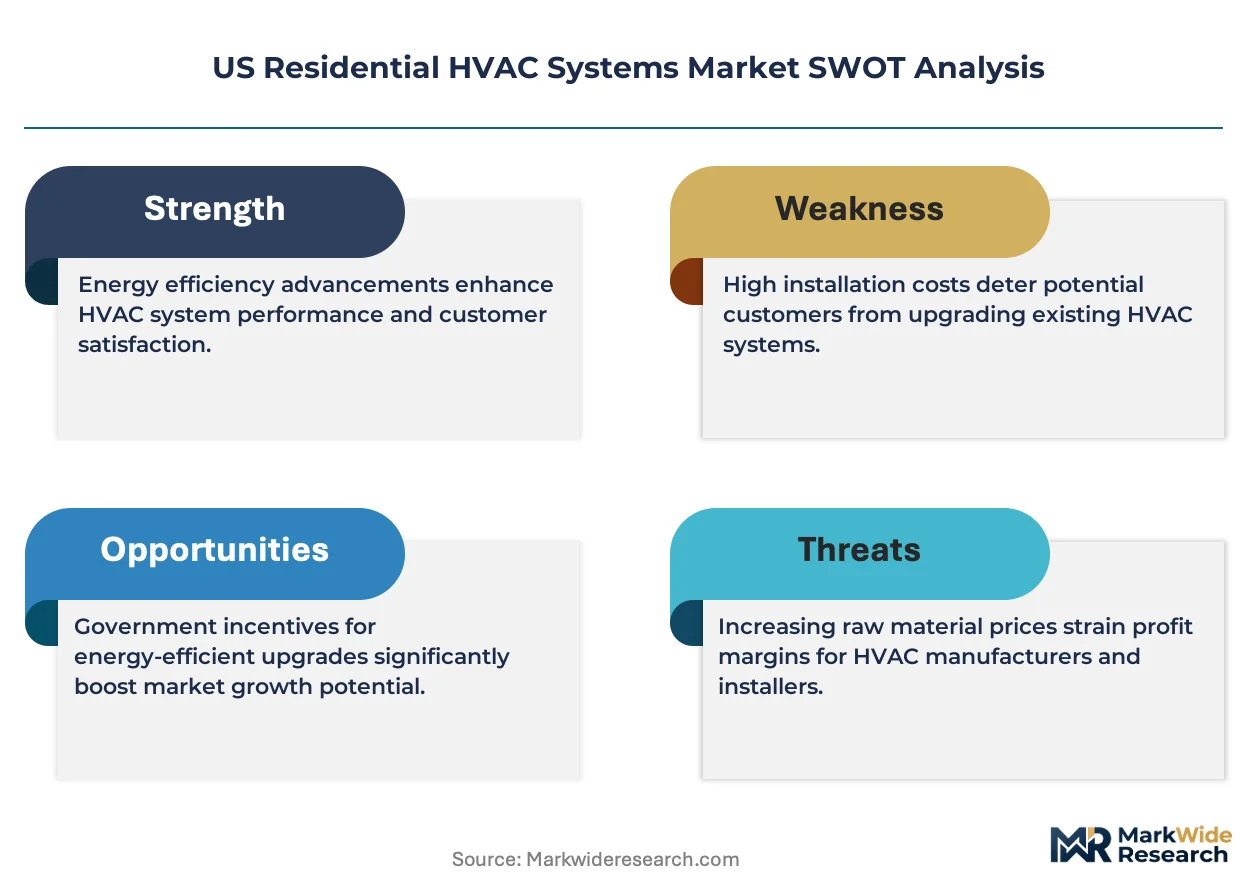
The US Residential HVAC market functions as a cost-of-compliance story where EPA AIM Act refrigerant phase-down schedules erect barrier-to-entry moats for players with certified technician networks and retooling capital. New entrants lacking Section 608 credentialing infrastructure face 6-12 month capability gaps against incumbent compliance bandwidth.
For Market Incumbents: Lock in technician certification pipelines through community college partnerships and EPA-approved training center accreditation, insulating installation capacity from seasonal credentialing backlogs. Backward integration into heat pump compressor supply hedges tariff exposure on Asian-sourced rotary units. Cold-climate heat pump performance certification investments defend premium positioning against emerging ductless specialists.
For New Entrants and Emerging Players: Enter via utility demand-response program partnerships that attach smart thermostat revenue streams to equipment installation, bypassing capital-intensive manufacturing. Northeast brownstone retrofit applications for ductless mini-splits represent the most penetrable segment given incompatible forced-air infrastructure. Digital-native customer acquisition through financing-integrated online platforms captures channel-divergent buyers in Florida and Texas markets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor EPA-certified regional contractors in Sun Belt states with aging owner-operator demographics and limited succession planning. Long-term viability over the projection horizon rests on electrification mandate exposure and cold-climate heat pump capability depth. Monitor state-level gas hookup ban enactment velocity as inflection indicator for furnace-to-heat pump replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Supply | Captive sourcing from Mexican or Thai plants insulates Carrier and Rheem from tariff volatility on Asian rotary units. |
| Cold-Climate Heat Pump Certification | Minnesota and Wisconsin regulatory thresholds for sub-zero operation open premium tiers previously served by dual-fuel systems. |
| Utility Demand-Response Partnership | Mid-Atlantic grid operators compensate homeowners for peak-load curtailment through automated smart thermostat integration. |
| EPA Section 608 Training Center Accreditation | Community college pipeline investments lock in installation capacity ahead of seasonal technician shortage windows. |
| Ductless Mini-Split Distribution Expansion | Northeast masonry construction with inaccessible ductwork favors wall-mounted cassette penetration over central system retrofit. |
Research Methodology
Document review covered EPA AIM Act regulatory filings, DOE appliance efficiency standards, and utility rebate program disclosures, complemented by interviews with HVAC distributor procurement managers, EPA-certified contractor owners, and state energy office electrification leads. Secondary validation drew from EIA residential energy consumption surveys, ACCA industry shipment data, and AHRI certification directories. Bottom-up equipment shipment modeling and top-down construction permit analysis enabled cross-triangulation of market sizing estimates.
Historical replacement cycle patterns were cross-referenced against panel input from distributor inventory managers and manufacturer regional sales directors. Segmentation dimensions across the analysis window included product type, technology tier, end-user category, and installation mode. CAGRs were derived from trend extrapolation of electrification mandate adoption curves and IRA credit utilization rates, with cold-climate heat pump performance thresholds and refrigerant transition timelines serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility or accelerated EPA enforcement schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Commercial Air Conditioner (AC) Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Air Conditioner Quilt Market