
 Dedicated Outdoor Air System Market | 2026-2036
Dedicated Outdoor Air System Market Size, Share, and Industry Trends Forecast 2026-2036
Dedicated Outdoor Air System Market Outlook
The shift from single-source to multi-source component procurement is hardening among DOAS manufacturers seeking supply resilience. Daikin Industries leverages captive compressor production to anchor its position in energy recovery configurations. Carrier Global Corporation competes through extensive service networks that sustain aftermarket revenue streams. LG Electronics differentiates via integrated building automation interfaces that extend system interoperability.
A dedicated outdoor air system conditions 100% outside air separately from return air streams, typically delivering between 500 and 20,000 CFM with energy recovery efficiencies exceeding 70%. This separation enables precise humidity control and ventilation compliance in occupied spaces without overcooling zones for dehumidification alone. Heat recovery product types dominate current installations across North American commercial buildings, while desiccant technology segments are gaining traction in humid climate zones where latent loads strain conventional systems. Variable volume configurations command margin premiums in hospital and laboratory applications where airflow turndown must track occupancy in real time.
The U.S. Department of Energy enforces minimum efficiency standards for commercial unitary air conditioners that directly shape DOAS equipment specifications. ASHRAE Standard 62.1 ventilation requirements and the International Energy Conservation Code create compliance-driven replacement cycles in existing building stock. China's GB standards for building energy efficiency and the Ministry of Ecology and Environment's dual carbon targets are tightening manufacturing benchmarks. Stakeholders must monitor how regional efficiency tier upgrades and refrigerant phase-down schedules will reshape equipment platform planning and service revenue models.
Market Dynamics
The Dedicated Outdoor Air System market is experiencing structural pressure from tightening ventilation mandates in healthcare and laboratory construction, which are forcing equipment specification upgrades faster than replacement cycles would naturally allow.
Growth Catalysts
- ASHRAE Standard 62.1 ventilation requirements:Healthcare facilities in the United States face mandatory air changes per hour that exceed conventional HVAC capacity, driving specification of dedicated outdoor air systems with energy recovery.
- China's dual carbon targets:The Ministry of Ecology and Environment's building efficiency benchmarks are accelerating DOAS adoption in Tier-1 city commercial developments seeking green building certification.
- Heat recovery wheel technology:Sensible and latent recovery efficiencies above 70% are making DOAS economically viable in climate zones previously served by simpler ventilation approaches.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger coil manufacturing faces input cost swings that compress margins on fixed-price commercial contracts.
- Compressor supply concentration:High-efficiency variable-speed compressor sourcing remains concentrated among a limited supplier base in East Asia, creating lead time vulnerability.
- Refrigerant phase-down schedules:The U.S. EPA's AIM Act restrictions on HFCs are forcing platform redesigns before amortization of current equipment generations.
Strategic Opportunities
- India's commercial real estate expansion:The country's Bureau of Energy Efficiency is tightening ECBC codes in metro corridors where DOAS penetration remains below 15% of new construction.
- Desiccant-assisted dehumidification:Solid and liquid desiccant systems are converging with conventional cooling to address latent loads in Southeast Asian pharmaceutical manufacturing.
- Performance-based maintenance contracts:Energy savings guarantees are displacing traditional time-and-materials service agreements in U.S. hospital procurement.
Industry Challenges
- Controls integration complexity:BACnet and Modbus protocol harmonization with legacy building management systems extends commissioning timelines and escalates project risk.
- Commissioning agent certification gaps:Qualified technicians for airflow testing and balancing of variable volume configurations remain scarce in secondary U.S. markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dedicated Outdoor Air System Market |
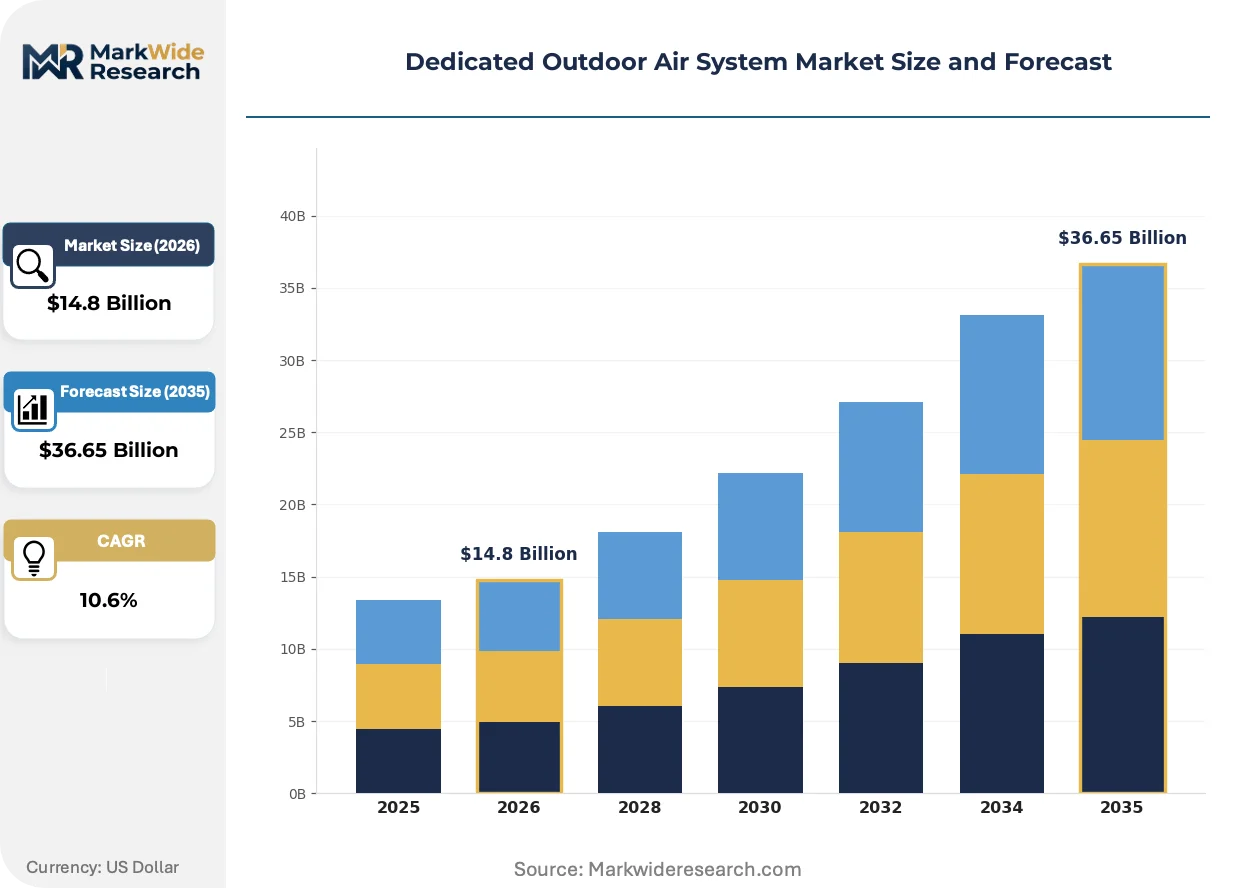
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.65 Billion |
| CAGR (2026 – 2036) | 10.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Recovery, Energy Recovery, Constant Volume, Variable Volume Technology: Direct Expansion, Chilled Beam, Desiccant, Fan Coil Application: Commercial Buildings, Hospitals, Educational Institutions, Industrial Facilities End User: Contractors, Facility Managers, Engineers, Architects |
| Companies Covered | Daikin Industries, Carrier Global Corporation, Trane Technologies, Johnson Controls, LG Electronics, Samsung Electronics, Mitsubishi Electric Corporation, Greenheck Fan Corporation, AAON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dedicated Outdoor Air System Market Strategic Shifts
Equipment manufacturers are racing to integrate predictive control algorithms and modular heat recovery architectures that compress installation footprints while expanding climate applicability across humid subtropical and arid continental zones.
Enthalpy wheels with advanced polymer or silica gel desiccant coatings are converging with demand-controlled ventilation logic to enable latent load management without overcooling. Hospital and laboratory buyers in the southeastern United States are specifying these configurations for year-round humidity control. This convergence is compressing the performance gap between dedicated outdoor air systems and full central plant dehumidification in mid-size facilities.
The U.S. Department of Energy's commercial unitary air conditioner efficiency standards are tightening minimum integrated energy efficiency ratios that directly shape DOAS equipment specifications. Manufacturers are responding with larger coil surface areas and enhanced fan motor efficiency tiers that add first cost but reduce lifecycle operating expenditure. Healthcare construction in California and New York is absorbing these premiums fastest due to state-level stretch codes exceeding federal baselines.
Buyer preference is rotating toward factory-integrated packages with pre-programmed control sequences that reduce field commissioning burden. General contractors on fast-track commercial projects are rejecting component-level procurement in favor of single-source responsibility for ventilation performance. This pattern is most pronounced in China's Tier-1 cities where construction timelines have compressed 20% since 2022 and labor availability for specialized commissioning has tightened.
Dedicated Outdoor Air System Market Segmentation
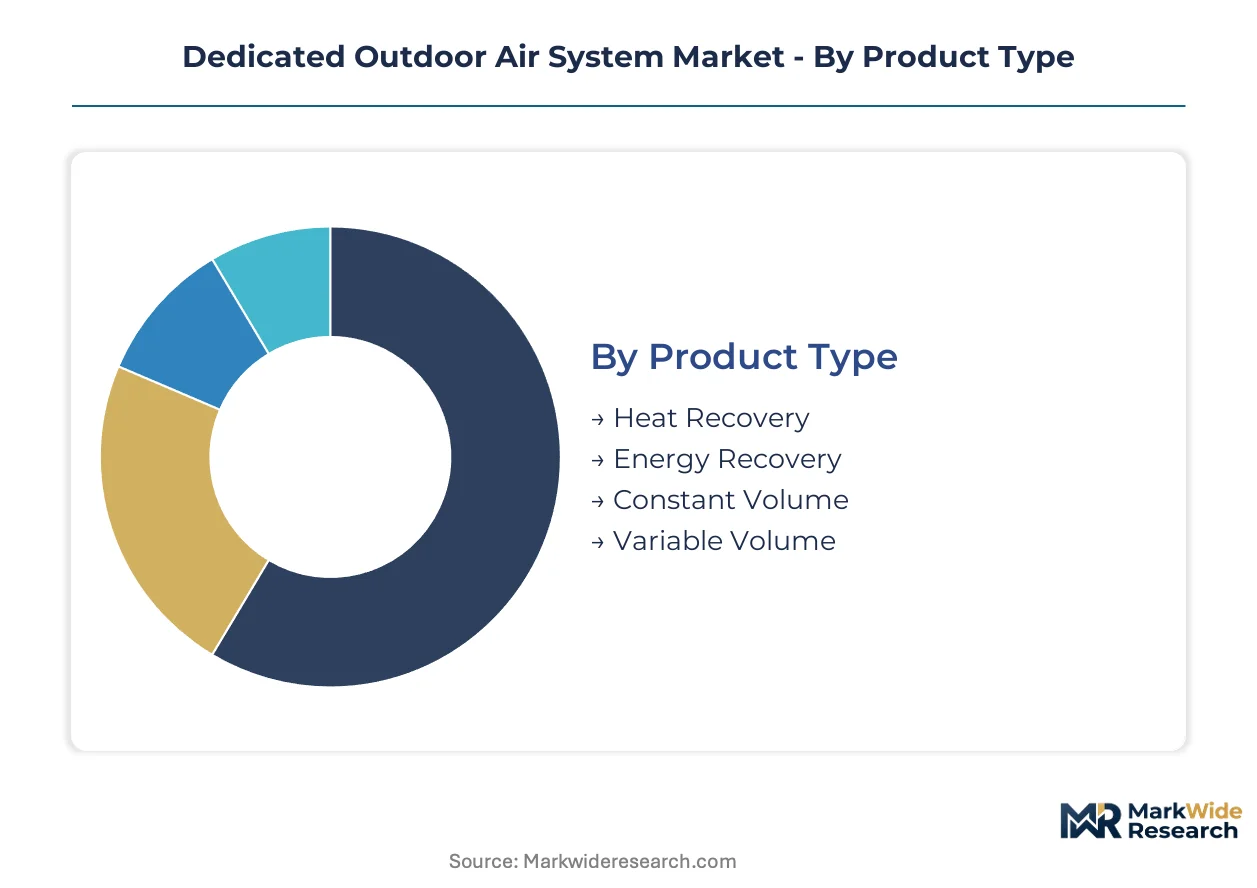
Segmentation in the Dedicated Outdoor Air System market reveals how certification requirements, climate loads, and procurement authority shape equipment specification. Understanding these divisions enables manufacturers to align product platforms with the compliance and performance thresholds that gate commercial viability.
Product Type:
Certification burdens vary sharply across product types, with ASHRAE 90.1 energy recovery mandates and IECC compliance tiers dictating which configurations qualify for federal and state incentive programs in the United States.
- Heat Recovery:Sensible-only heat exchangers transfer dry-bulb temperature between exhaust and supply airstreams without moisture exchange. Demand concentrates in northern U.S. commercial buildings where winter heating loads dominate and ASHRAE 90.1 baseline compliance suffices.
- Energy Recovery:Total enthalpy wheels or membrane cores capture both sensible and latent energy, achieving recovery efficiencies above 70% in humid southeastern U.S. hospital projects where dehumidification compliance with FGI Guidelines drives specification.
- Constant Volume:Fixed airflow delivery simplifies controls integration in smaller educational facilities with predictable occupancy patterns and limited commissioning budgets.
- Variable Volume:Demand-controlled ventilation modulates supply air to track real-time occupancy, specified in California laboratory construction where Title 24 energy codes mandate turndown capability.
Leading the category by volume: Heat Recovery. Growing fastest: Variable Volume.
Technology:
Cost tier stratification separates premium desiccant configurations from baseline direct expansion systems, with first-cost premiums of 40-60% restricting desiccant adoption to humidity-critical applications.
- Direct Expansion:Refrigerant-based cooling coils integrated within DOAS cabinets provide compact footprints and rapid installation. Demand clusters in fast-track commercial construction across China's Tier-1 cities where MEE efficiency benchmarks favor packaged solutions.
- Chilled Beam:Hydronic terminal units paired with dedicated outdoor air systems enable decoupled sensible and latent conditioning. European hospital procurement under EU Green Deal efficiency directives favors this combination for reduced fan energy.
- Desiccant:Solid or liquid desiccant wheels actively dehumidify supply air independent of cooling coil temperature, penetrating Southeast Asian pharmaceutical manufacturing where WHO GMP humidity specifications are stringent.
- Fan Coil:Distributed terminal units with DOAS ventilation provide zonal temperature control in Indian commercial real estate where Bureau of Energy Efficiency ECBC code adoption is tightening.
Dominant by installed base: Direct Expansion. Steepest expansion trajectory: Desiccant.
Application:
Application segments align with ventilation code stringency, with healthcare and laboratory construction imposing air changes per hour requirements that exceed conventional HVAC capacity.
- Commercial Buildings:Office and retail installations prioritize energy recovery for ASHRAE 62.1 ventilation compliance with minimized operating cost. Volume concentrates in U.S. Class-A office renovation where LEED certification drives equipment replacement.
- Hospitals:Infection control mandates from FGI Guidelines and ASHRAE 170 require pressure relationships and filtration that only dedicated outdoor air systems reliably achieve. California and New York state stretch codes accelerate premium specification.
- Educational Institutions:K-12 and university projects balance first-cost constraints with post-occupancy energy guarantees, favoring constant volume configurations in U.S. municipal bond-financed construction.
- Industrial Facilities:Manufacturing and warehouse applications with high internal latent loads or fume exhaust requirements specify DOAS for ventilation dilution without overcooling production zones.
Largest revenue pool: Commercial Buildings. Gaining share fastest: Hospitals.
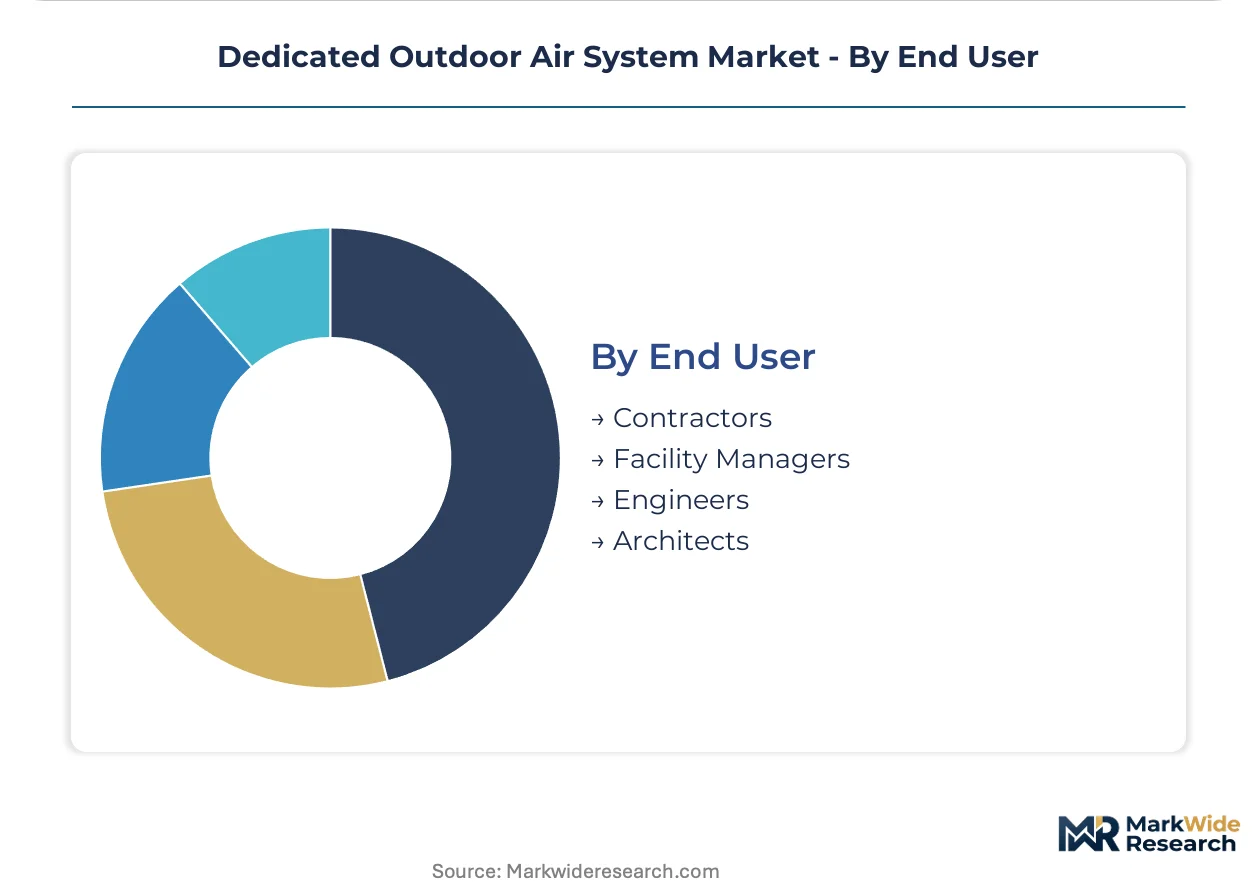
End User:
Procurement authority and technical sophistication determine end-user segments, with engineers and architects exerting greatest influence over specification during design development.
- Contractors:Turnkey construction firms prioritize factory-integrated packages with pre-programmed sequences to compress commissioning timelines and limit field labor risk.
- Facility Managers:Building operators with lifecycle cost accountability drive replacement demand toward energy recovery configurations with performance-based maintenance contracts.
- Engineers:MEP consulting firms specify equipment performance parameters and control sequences, anchoring manufacturer relationships through master specifications and approved product lists.
- Architects:Design professionals integrate DOAS into building massing and facade systems, particularly in urban infill projects where mechanical penthouse space is constrained.
Primary specification authority: Engineers. Fastest-growing procurement influence: Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper coil fabrication clusters in the United States and aluminum extrusion centers in China anchor the Dedicated Outdoor Air System supply geography. Equipment assembly concentrates near these feedstock nodes to minimize heat exchanger transport costs. Demand generation follows commercial construction permits and healthcare capital expenditure cycles across distinct national regulatory environments.
United States
Healthcare construction in California and New York absorbs premium DOAS configurations driven by state stretch codes exceeding federal baselines. The U.S. Department of Energy enforces commercial unitary air conditioner efficiency standards that directly shape equipment specifications through ASHRAE 90.1 compliance tiers. Hospital projects in the Southeast specify enthalpy wheels with desiccant coatings for year-round humidity control.
China
Tier-1 city commercial developments in Shanghai and Beijing accelerate DOAS adoption to secure green building certification under tightening MEE efficiency benchmarks. The Ministry of Ecology and Environment's dual carbon targets compress construction timelines while elevating manufacturing standards for energy recovery equipment. Yangtze River Delta fabricators dominate heat exchanger production for domestic and export markets.
Germany
European hospital procurement under EU Green Deal efficiency directives favors chilled beam-DOAS combinations for reduced fan energy consumption. The F-Gas Regulation mandates refrigerant phase-down schedules that force platform redesigns before equipment generation amortization. Industrial clusters in Baden-Württemberg specialize in hydronic terminal unit integration for decoupled sensible and latent conditioning.
India
Metro corridor commercial real estate in Mumbai and Delhi-NCR drives specification as the Bureau of Energy Efficiency tightens ECBC codes where DOAS penetration remains below 15% of new construction. The national building energy efficiency framework creates compliance-driven replacement cycles in existing stock. Gujarat-based contractors prioritize factory-integrated packages to limit field commissioning labor.
Japan
Pharmaceutical manufacturing facilities in Osaka and Nagoya specify desiccant-assisted configurations to meet stringent WHO GMP humidity specifications. METI efficiency directives push manufacturers toward heat recovery technologies with recovery efficiencies exceeding 70%. Kanto region engineering firms anchor manufacturer relationships through master specifications and approved product lists.
Dedicated Outdoor Air System Market Competitive Environment
Global majors compete with regional champions across energy recovery technology and control system integration. The vendor base stratifies into three tiers: diversified HVAC conglomerates with captive compressor production, specialized ventilation equipment fabricators with deep coil engineering expertise, and building automation specialists extending into packaged air systems. Consolidation pressure concentrates among mid-scale players lacking backward integration into heat exchanger manufacturing. Dominant competitive moves include capacity expansion in Southeast Asian assembly locations and technology licensing agreements for desiccant wheel coatings.
Within the diversified conglomerate tier, Daikin Industries and Carrier Global Corporation exemplify contrasting strategic positions. Daikin anchors its market presence through captive compressor production that secures supply chain resilience for energy recovery configurations. Carrier occupies a position sustained by extensive service networks that generate aftermarket revenue streams independent of equipment replacement cycles. LG Electronics represents the building automation convergence archetype, with integrated control interfaces that extend system interoperability across third-party management platforms. These three players illustrate how vertical scope, service infrastructure, and software integration serve as distinct competitive anchors in specification-driven procurement environments.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global Corporation |
| Trane Technologies |
| Johnson Controls |
| LG Electronics |
| Samsung Electronics |
| Mitsubishi Electric Corporation |
| Greenheck Fan Corporation |
| AAON |
| Others |
Value Chain & Pricing Dynamics
ASHRAE Standard 90.1 energy recovery mandates gate both qualified supply and premium-tier pricing access, as only manufacturers with certified enthalpy wheel production lines can bid on federal and state incentive-eligible projects in the United States. This regulatory filter concentrates pricing power among vertically integrated players with in-house heat exchanger fabrication, while unbundled component suppliers compete on thinner margins in non-compliant segments.
Pricing Analysis
Warranty and service bundling separates premium DOAS offerings from commodity configurations, with factory-integrated packages commanding substantial premiums over component-level procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ASHRAE 90.1-compliant energy recovery units at the top and constant volume heat-only systems at the base. Cost compression in standard tiers is intensifying because general contractors on fast-track commercial projects demand single-source responsibility for ventilation performance. Educational institutions remain most price-sensitive due to municipal bond financing constraints, while hospital procurement committees prioritize lifecycle operating expenditure over first cost.
Supply Chain Analysis
Heat exchanger coil production rests on copper and aluminum feedstock availability concentrated in the United States, China, and Germany. Manufacturing draws from specialty polymer desiccant coatings sourced from Japanese chemical producers, high-efficiency variable-speed compressors anchored in South Korean and Japanese production clusters, and precision aluminum extrusion from Yangtze River Delta fabricators. Single-source vulnerability in compressor supply creates lead time risk for energy recovery configurations. Distribution runs through manufacturer-direct specification sales for large healthcare and laboratory projects, with regional HVAC distributors serving smaller commercial retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
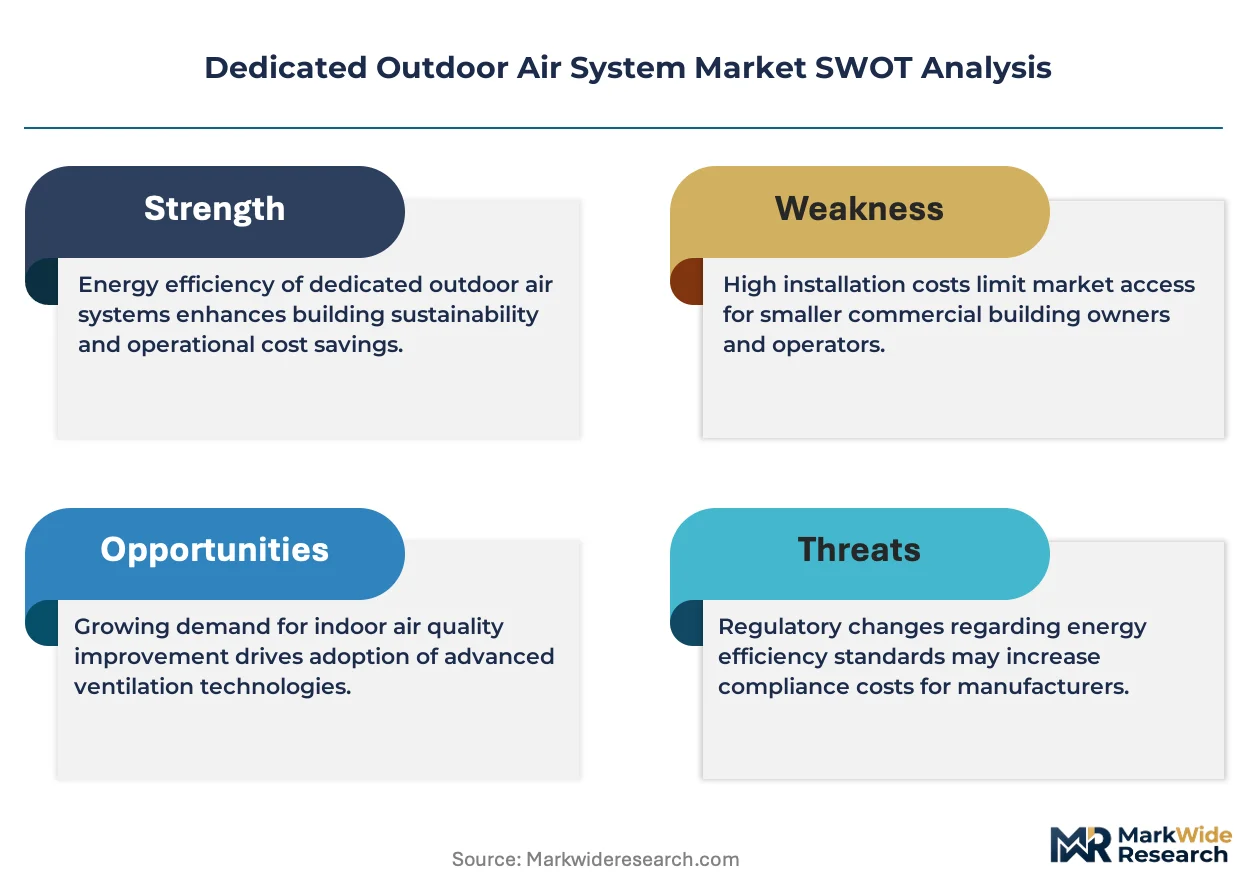
The Dedicated Outdoor Air System market functions as a cost-of-compliance arena where ASHRAE Standard 62.1 ventilation requirements create a regulatory moat that rewards certified incumbents while filtering out undercapitalized entrants lacking testing and certification infrastructure.
For Market Incumbents: Anticipate refrigerant phase-down schedule acceleration by securing alternative refrigerant platform development ahead of EPA AIM Act enforcement milestones. Backward integration into heat exchanger manufacturing defends margin position against copper and aluminum price volatility. Capacity addition in Southeast Asian assembly locations addresses tariff exposure while positioning for India's commercial real estate expansion under tightening ECBC codes.
For New Entrants and Emerging Players: Digital specification tools and building energy modeling software partnerships offer low-friction routes to engineer-level influence without legacy field service infrastructure. White-space opportunity concentrates in India's metro corridors where DOAS penetration remains below comparable Asian markets and commissioning agent scarcity devalues incumbent service network advantages. Target desiccant-assisted dehumidification for Southeast Asian pharmaceutical manufacturing where WHO GMP humidity specifications exceed conventional cooling capabilities.
For Investors and Strategic Acquirers: State-level stretch code adoption exceeding federal baselines is the leading indicator that premium-tier pricing power will concentrate in California and New York healthcare construction markets. Long-term viability favors manufacturers with captive compressor production and certified energy recovery platforms over assemblers dependent on third-party component sourcing. Watch for Ministry of Ecology and Environment dual carbon target enforcement acceleration as the signal for China Tier-1 city demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Wheel Technology Licensing | Desiccant coating partnerships with Japanese chemical producers accelerate humid climate penetration. |
| Factory-Integrated Control Package Development | Pre-programmed BACnet sequences reduce commissioning timelines for fast-track Chinese construction. |
| Southeast Asian Assembly Expansion | Proximity to India's Bureau of Energy Efficiency code tightening captures emerging commercial demand. |
| Performance-Based Maintenance Contract Rollout | Energy savings guarantees displace time-and-materials agreements in U.S. hospital procurement. |
| Alternative Refrigerant Platform Redesign | EPA AIM Act compliance ahead of phase-down schedules preserves federal incentive eligibility. |
Study Parameters
Independent corroboration across MEP consulting engineers, hospital facility managers, and commercial general contractors underwrites the qualitative findings on specification authority and procurement patterns. Primary interviews with heat exchanger manufacturing plant managers, HVAC distributor channel partners, and building automation integration specialists combined with secondary validation from ASHRAE standards documentation, U.S. Department of Energy efficiency rulemaking dockets, and China GB standards filings. Bottom-up equipment shipment analysis and top-down construction permit aggregation triangulate market sizing across product type, technology, and application segments.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, modeling segmentation dimensions including heat recovery versus energy recovery product types, direct expansion versus desiccant technology tiers, and hospital versus commercial building applications. CAGRs derive from regression analysis of historical construction expenditure patterns against regulatory compliance cycle timing. Industry-specific forecast inputs incorporate FGI Guidelines ventilation requirement updates and Ministry of Ecology and Environment dual carbon target implementation schedules.
The model holds under steady regulatory enforcement and copper-aluminum price band stability; deviation in compressor supply disruption or refrigerant phase-down acceleration would shift equipment availability timelines and regional competitive positioning. Forecasts reflect documented assumptions on construction permit growth, code adoption rates, and technology substitution elasticities. A small set of named triggers—state stretch code proliferation, India ECBC enforcement intensity, and desiccant wheel coating supply concentration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
China HVAC Field Device Market