
 North America Homeland Security and Emergency Management Market | 2026-2036
North America Homeland Security and Emergency Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Homeland Security and Emergency Management Market Analytics
FEMA's National Incident Management System compliance threshold is hardening the cost-of-entry calculus for new suppliers seeking federal contracting eligibility. Northrop Grumman Corporation leverages its vertical integration across radar and cyber domains to sustain pricing power in integrated border surveillance programs. Lockheed Martin Corporation anchors the emergency communications segment through hardened satellite relay infrastructure. L3Harris Technologies Inc specializes in interoperable radio networks that dominate first responder channel access across multiple state procurement frameworks.
North America Homeland Security and Emergency Management encompasses integrated systems for threat detection, crisis response coordination, and critical infrastructure protection, incorporating encrypted communication protocols, multi-sensor fusion algorithms, and hardened command-and-control architectures designed to maintain operational continuity under degraded conditions. Surveillance Systems command the largest installed base but face margin compression from commoditized camera hardware, while AI Analytics represents the fastest-expanding technology layer as agencies deploy predictive threat models across IoT sensor networks. Communication Equipment retains durable pricing power due to spectrum licensing barriers and interoperability certification requirements that limit vendor switching.
The Department of Homeland Security's SAFETY Act liability protections and the Federal Communications Commission's FirstNet broadband priority framework shape product development roadmaps and procurement qualification pathways for market participants. State-level fusion center accreditation standards administered through DHS further fragment addressable demand into jurisdiction-specific compliance bundles. Stakeholders must weigh the capital requirements of maintaining dual-certified product lines against the revenue concentration risk of single-agency dependency.
Market Dynamics
FEMA's National Incident Management System compliance mandates are hardening procurement standards across state and local emergency management agencies, forcing system modernization cycles and reshaping supplier qualification pathways.
Growth Catalysts
- FirstNet broadband priority framework:The FCC-administered FirstNet network guarantees dedicated spectrum access for first responders, driving hardware refresh cycles and encrypted device procurement across Texas-California corridor jurisdictions.
- Texas-California corridor infrastructure overlap:Border security and disaster response infrastructure investments are concentrating procurement demand across this geographic band, creating economies of scale for integrated command platform deployments.
- Multi-sensor fusion algorithms:AI-driven threat detection systems are accelerating adoption as fusion centers modernize their analytical capabilities to meet DHS accreditation standards.
Market Restraints
- Commoditized camera hardware:Surveillance Systems face sustained margin compression as standardized imaging components flood the market from offshore suppliers.
- Spectrum licensing barriers:FCC-controlled frequency allocations limit vendor switching and create durable pricing power for incumbent radio network providers.
- SAFETY Act certification timelines:DHS liability protection qualification requires extensive legal and technical documentation, extending sales cycles for new market entrants.
Strategic Opportunities
- Predictive threat modeling:AI Analytics represents the fastest-expanding technology layer as agencies deploy machine learning across IoT sensor networks for pre-incident detection.
- State-level fusion center accreditation:DHS-administered standards fragment demand into jurisdiction-specific compliance bundles, creating niche specialization openings for certified providers.
- Interoperable radio network gaps:Rural and tribal emergency management agencies remain underpenetrated for hardened communication infrastructure, offering expansion paths beyond urban procurement concentration.
Industry Challenges
- Dual-certified product line maintenance:Stakeholders must weigh capital requirements of sustaining parallel federal and state qualification tracks against revenue concentration risk from single-agency dependency.
- Legacy system integration complexity:Hardened command-and-control architectures must maintain operational continuity when interfacing with decades-old emergency dispatch infrastructure.
- Cyber-physical security convergence:Personnel with combined expertise in radar systems and network defense remain scarce, constraining deployment velocity for integrated border surveillance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Homeland Security and Emergency Management Market |
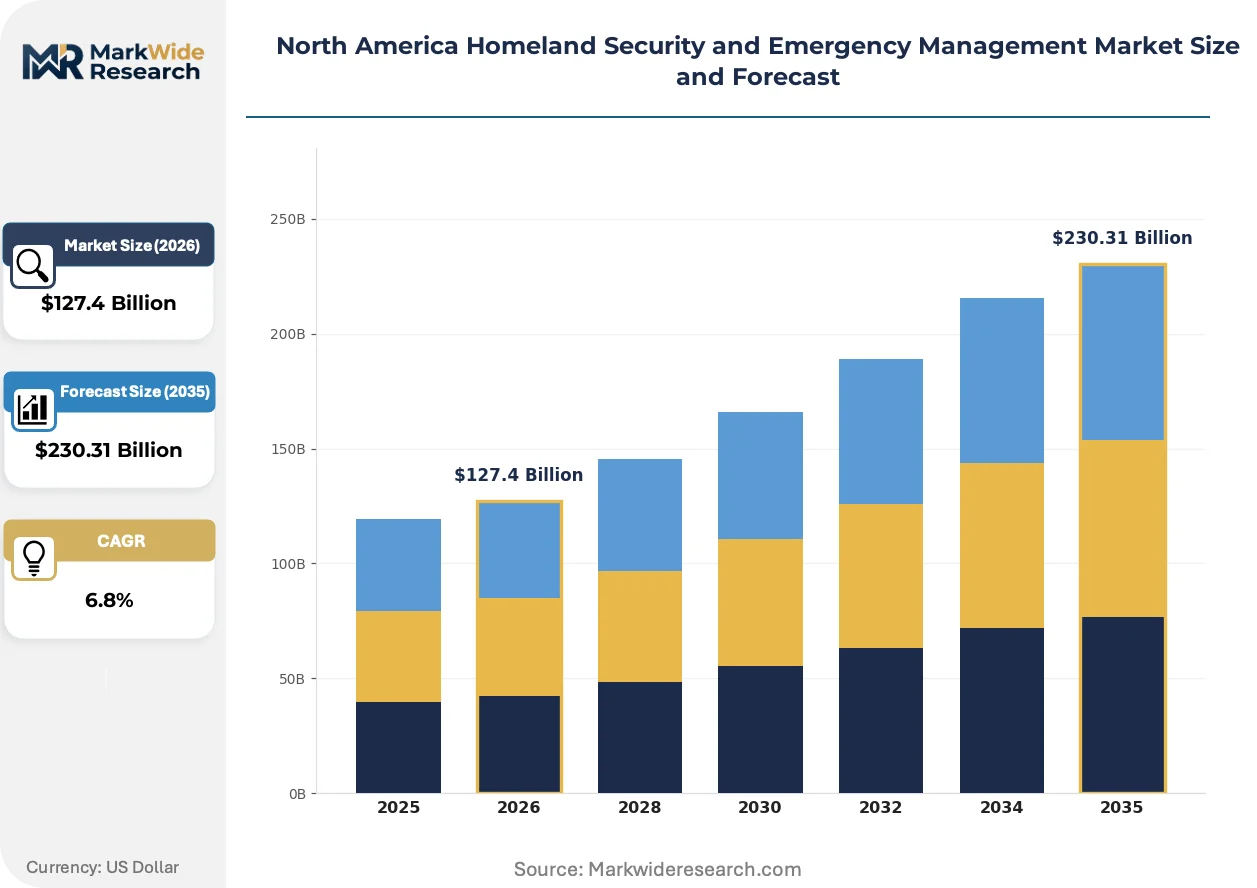
| Market Size in 2026 | $127.4 Billion |
| Market Size in 2035 | $230.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Access Control, Biometrics, Communication Equipment Service Type: Consulting Services, Training Services, System Integration, Maintenance Services End User: Government Agencies, Military, First Responders, Private Sector Technology: AI Analytics, Cloud Computing, Drones, IoT Solutions |
| Companies Covered | Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, BAE Systems plc, Lockheed Martin Corporation, Leidos Holdings Inc, L3Harris Technologies Inc, Thales Group, CACI International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Homeland Security and Emergency Management Market Evolving Landscape
Encrypted communication protocols and hardened satellite relay infrastructure are reshaping how emergency management agencies coordinate multi-jurisdictional crisis response, with procurement patterns increasingly favoring integrated platforms over point solutions.
Edge-deployed sensor processing hardware is modularizing threat detection architectures across border surveillance programs. Customs and Border Protection field offices are adopting containerized compute nodes that process radar and video feeds locally before satellite uplink. This distributed topology is modularizing supplier ecosystems by decoupling hardware procurement from centralized software licensing.
The FCC's FirstNet broadband priority framework is mandating interoperable device certification for all first responder communication equipment. Manufacturers must now engineer for dual-band LTE and LMR compatibility to maintain federal procurement eligibility. Emergency communications segments are responding by consolidating R&D roadmaps around hardened satellite relay infrastructure that bridges legacy and next-generation networks.
State procurement frameworks are consolidating vendor pools through multi-year enterprise agreements that bundle hardware, software, and maintenance. Texas and California emergency management agencies have shifted from transactional equipment purchases to performance-based contracting models. This consolidation pattern is most visible across the border security and disaster response infrastructure overlap zone, where integrated command platform deployments require sustained vendor relationships rather than spot-market sourcing.
North America Homeland Security and Emergency Management Market Segmentation
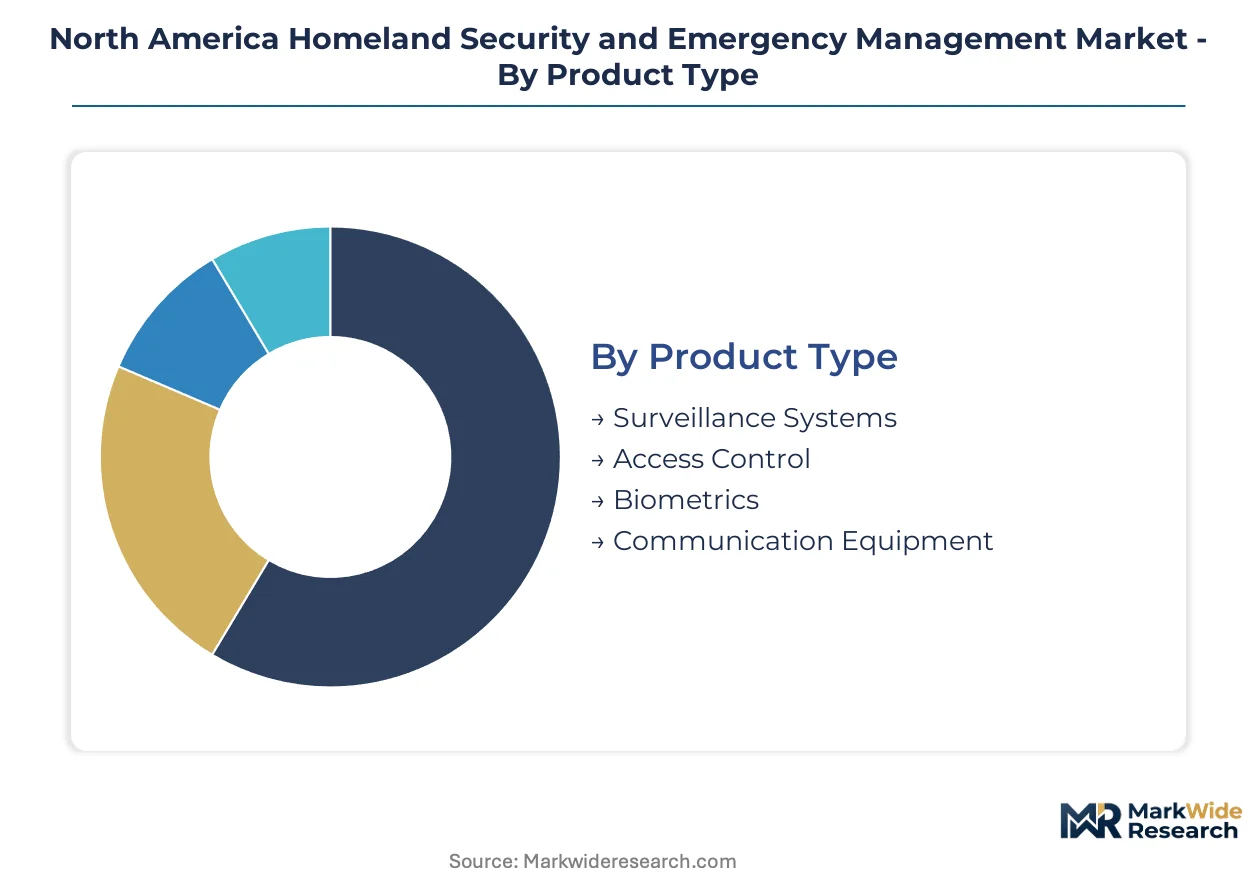
Segmentation in homeland security and emergency management reflects divergent procurement rhythms across federal, state, and local agencies. Technology maturity curves and compliance certification requirements create distinct addressable pockets within each category.
Product Type:
Customization intensity varies sharply across this category, with hardened command platforms demanding extensive configuration while standardized imaging hardware moves through commodity channels.
- Surveillance Systems:Multi-sensor fusion architectures incorporating radar, thermal imaging, and video analytics form the core of border protection infrastructure. Procurement concentrates across the Texas-California corridor where Customs and Border Protection field offices prioritize integrated coverage over point solutions. Margin compression from offshore camera component suppliers is forcing incumbents toward software-defined feature differentiation.
- Communication Equipment:Dual-band LTE and LMR-compatible devices engineered for FirstNet interoperability certification dominate federal procurement frameworks. State emergency management agencies in Texas and California anchor demand through multi-year enterprise agreements bundling hardware with maintenance. FCC spectrum licensing barriers protect incumbent pricing power and limit vendor switching.
- Access Control:Hardened biometric and credential verification systems for critical infrastructure protection.
- Biometrics:Fingerprint, iris, and facial recognition systems deployed at ports of entry and high-security facilities.
Leading the category by volume: Surveillance Systems. Growing fastest: Communication Equipment.
Service Type:
Cost tier stratification separates high-touch consulting engagements from standardized maintenance contracts, with system integration occupying the middle ground where technical complexity meets recurring revenue potential.
- System Integration:Deployment of interoperable command platforms requiring legacy dispatch infrastructure interface engineering. State fusion centers across California and Texas drive demand as DHS accreditation standards harden technical requirements. Project timelines extend when coordinating across multiple agency procurement cycles.
- Maintenance Services:Performance-based contracts with uptime guarantees and cybersecurity patch management. Federal contracting vehicles favor incumbent providers with established SAFETY Act certifications. Recurring revenue streams stabilize supplier cash flows against lumpy capital equipment cycles.
- Consulting Services:Threat assessment and emergency preparedness planning for government and private sector clients.
- Training Services:Certification programs for first responder agencies on new platform deployments.
Dominant by contract value: System Integration. Expanding most quickly: Maintenance Services.
End User:
Customer type fragmentation produces distinct sales motion requirements, from federal RFP processes to municipal emergency management department budget cycles.
- Government Agencies:Federal departments including FEMA and DHS anchor procurement through multi-billion dollar program offices. Compliance with National Incident Management System mandates accelerates modernization spending. SAFETY Act liability protections shape vendor qualification pathways.
- First Responders:State and local police, fire, and emergency medical services drive device-level procurement through FirstNet enrollment. Rural and tribal agencies remain underpenetrated relative to urban concentration. Interoperable radio network gaps create expansion opportunities beyond established corridors.
- Military:Domestic installation protection and civil support mission requirements.
- Private Sector:Critical infrastructure operators in energy, transportation, and telecommunications verticals.
Top spending authority: Government Agencies. Steepest expansion trajectory: First Responders.
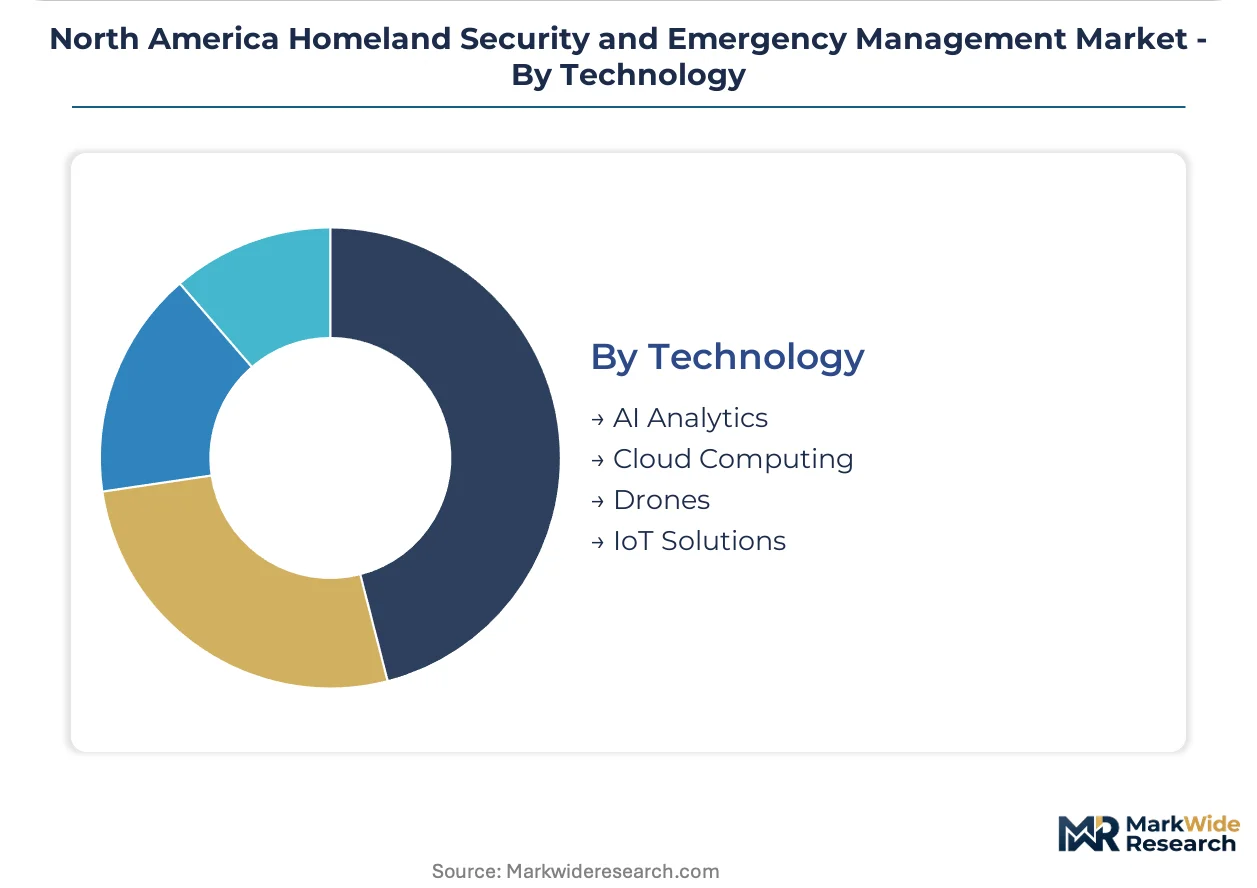
Technology:
Technology maturity stages range from deployed-at-scale IoT sensor networks to emerging AI Analytics layers still navigating procurement qualification.
- AI Analytics:Machine learning models deployed across fusion center sensor networks for predictive threat detection. Edge-deployed processing hardware reduces satellite bandwidth requirements for border surveillance programs. DHS accreditation standards for analytical capabilities drive adoption timelines.
- IoT Solutions:Distributed sensor networks monitoring critical infrastructure across energy and transportation verticals. Procurement concentrates through state-level smart city initiatives in California and Texas. Cyber-physical security convergence requirements constrain deployment velocity.
- Cloud Computing:Hardened government cloud instances for emergency data storage and coordination platforms.
- Drones:Unmanned aerial systems for border patrol and disaster response situational awareness.
Widest installed base: IoT Solutions. Gaining share fastest: AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-California corridor concentrates over half of regional procurement for integrated command platforms, where border security and disaster response infrastructure investments overlap. State fusion centers in this band drive demand for multi-sensor fusion systems and hardened communication networks. Federal compliance mandates from FEMA and DHS accelerate modernization spending unevenly across sub-regions.
United States
Customs and Border Protection field offices along the southwest border anchor demand for surveillance systems with edge-deployed processing capabilities. The FCC's FirstNet broadband priority framework mandates interoperable device certification, reshaping procurement standards for first responder agencies. California and Texas emergency management departments have shifted to performance-based contracting models that bundle hardware, software, and multi-year maintenance.
Canada
Critical infrastructure protection programs drive procurement of access control and biometric verification systems at ports of entry and energy facilities. Health Canada coordinates with the Canadian Border Services Agency on integrated threat detection standards aligned with continental security frameworks. Ontario and British Columbia anchor deployment concentration through provincial smart city initiatives and transportation security upgrades.
Mexico
Northern border states concentrate demand for surveillance and communication equipment as security cooperation with U.S. agencies deepens. The Secretariat of Security and Civil Protection administers federal procurement frameworks that prioritize interoperable systems compatible with continental standards. Manufacturing clusters in Nuevo León and Baja California are developing local assembly capacity for sensor hardware serving regional programs.
North America Homeland Security and Emergency Management Market Competitive Landscape
U.S. defense contractors anchor the prime contractor tier; Canadian and European specialists hold positions in sub-system niches requiring export-controlled technology access. The vendor base concentrates around firms with established SAFETY Act certifications and FirstNet interoperability qualifications, creating credential-based barriers for new entrants. Three archetypes dominate: vertically integrated platform providers, radio network specialists with spectrum licensing advantages, and system integrators with legacy dispatch infrastructure expertise. Competitive moves center on multi-year enterprise agreement consolidation and edge-computing hardware partnerships that decouple software from centralized licensing.
Within the prime contractor tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify vertically integrated platform providers with positions spanning radar, satellite relay, and cyber domains. L3Harris Technologies Inc occupies a specialist position in interoperable radio networks, leveraging spectrum licensing barriers that limit vendor switching. These three firms collectively represent the credential-heavy segment where federal contracting eligibility and dual-band engineering capabilities determine procurement access.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| BAE Systems plc |
| Lockheed Martin Corporation |
| Leidos Holdings Inc |
| L3Harris Technologies Inc |
| Thales Group |
| CACI International Inc |
| Others |
Value Network & Pricing Analysis
Cyber-physical security specialists concentrated in the Washington-Baltimore corridor command wage premiums that widen pricing spreads between tier-one integrated platforms and commoditized hardware alternatives. Labor-cost differentials between cleared engineering talent and offshore manufacturing labor feed directly into procurement-tier stratification across federal and state contracting frameworks.
Pricing Analysis
Volume concentrates in standardized surveillance hardware while margins accrue to encrypted communication platforms and AI-driven analytics layers. Three-tier pricing structure across premium, standard, and economy levels separates SAFETY Act-certified integrated command platforms from state-procured interoperable radio networks and offshore-sourced camera components. Cost compression in imaging hardware intensifies because Taiwanese and Chinese sensor manufacturers flood spot markets with interchangeable modules. State emergency management agencies exhibit highest price sensitivity due to fragmented budget cycles, while federal program offices prioritize certification compliance over unit economics.
Supply Chain Analysis
Specialty semiconductor supply for edge-deployed processing hardware rests on Taiwanese foundry capacity and South Korean memory fabrication. Hardened satellite relay infrastructure draws from domestic defense contractor integration facilities, while standardized radio components source from Mexican and Malaysian electronics assembly clusters. Single-source vulnerability concentrates in gallium nitride substrates for radar transmitters and radiation-hardened chipsets for space-based relay nodes. Distribution runs through prime contractor-led integration channels for federal programs and state procurement cooperative purchasing agreements for local agency deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over spectrum-licensed radio technology and SAFETY Act certification infrastructure determines procurement access. Players are pursuing backward integration into edge-computing hardware to decouple software revenue from centralized licensing dependencies.
For Market Incumbents: Anchor federal contracting eligibility through sustained FirstNet interoperability certification investment and hardened satellite relay capacity expansion. Consolidate position by acquiring niche system integrators with legacy dispatch infrastructure expertise and established state fusion center relationships. Threat from commoditized camera hardware and offshore sensor suppliers demands defensive software-defined feature differentiation.
For New Entrants and Emerging Players: Begin with rural and tribal emergency management agencies where interoperable radio network gaps persist and incumbent presence remains thin. Target AI Analytics deployment for predictive threat modeling at underpenetrated state fusion centers seeking DHS accreditation. Go-to-market angle should emphasize edge-deployed processing hardware that reduces satellite bandwidth costs for border surveillance programs.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier system integrators holding dual-certified product lines across federal SAFETY Act and state procurement frameworks given accelerating National Incident Management System compliance mandates. Long-term viability favors firms with captive supply of spectrum-licensed radio technology and established prime contractor subcontractor relationships. Signal to watch is consolidation of state procurement into multi-year enterprise agreements that bundle hardware, software, and maintenance.
| Strategic Initiative | Industry Significance |
|---|---|
| FirstNet Interoperability Certification | FCC-mandated device standards reshape procurement eligibility across first responder agencies. |
| Edge-Computing Hardware Partnership | Containerized compute nodes decouple software licensing from centralized infrastructure dependencies. |
| SAFETY Act Liability Protection | DHS certification creates credential barriers that extend sales cycles for unqualified competitors. |
| State Fusion Center Accreditation | DHS-administered standards fragment demand into jurisdiction-specific compliance specialization openings. |
| Multi-Year Enterprise Agreement Consolidation | Performance-based contracting in Texas and California shifts procurement toward sustained vendor relationships. |
Research Methodology
Independent corroboration across primary interviews with emergency management procurement officers, system integration engineers, and FCC regulatory specialists, combined with secondary validation of FEMA program documentation and DHS accreditation standards, underwrites the qualitative findings. Primary fieldwork encompassed fusion center directors in California and Texas, prime contractor program managers, and state cooperative purchasing administrators. Secondary sources included federal contracting databases, SAFETY Act certification registries, FirstNet deployment disclosures, and SEC filings from publicly traded defense contractors. Bottom-up segment sizing triangulated against top-down federal budget appropriation analysis.
Rate-of-change decomposition across technology adoption curves, procurement cycle timing, and compliance mandate phasing anchored the analytical framework. Segmentation dimensions encompassed product type, service tier, end-user category, and technology maturity stage, with additional modeling of federal versus state procurement channel dynamics. CAGRs derived from weighted scenario analysis across baseline, accelerated modernization, and fiscal constraint cases. Industry-specific inputs included National Incident Management System compliance deadlines and FirstNet coverage expansion milestones.
Underlying measurement precision varies by segment; AI Analytics and Communication Equipment carry tighter precision than commoditized Surveillance Systems given clearer adoption indicators. Forecasts reflect documented assumptions regarding federal spending continuity and state budget stability. Specific risk factors warranting ongoing watch include shifts in DHS accreditation timelines, FCC spectrum reallocation proceedings, and congressional appropriation volatility for border security infrastructure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market
Emergency and Disaster Management
Emergency Blankets Market