
 Emergency Lighting Market | 2026-2036
Emergency Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Lighting Market Analysis
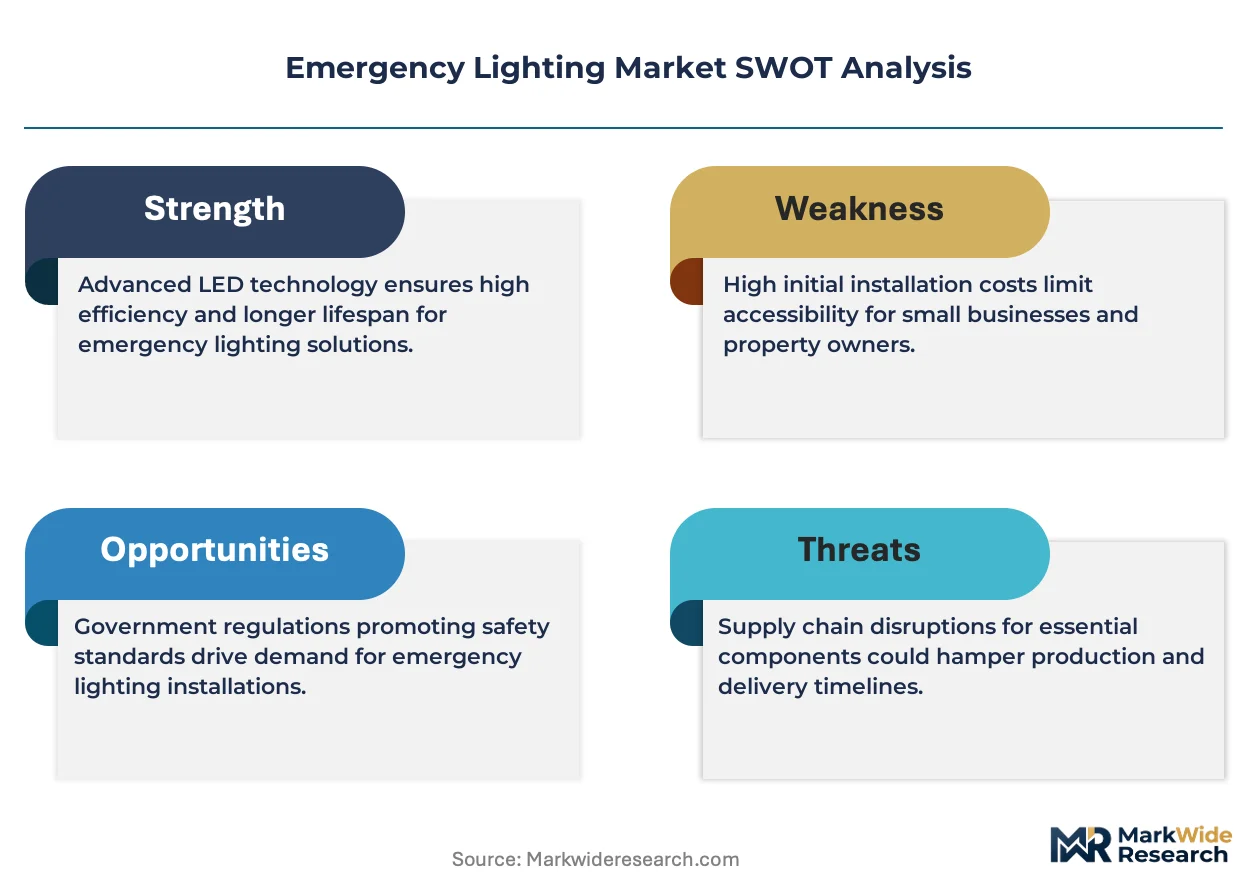
UL 924 certification-grade emergency lighting is redrawing competitive boundaries across commercial and industrial channels. Eaton Electric leverages captive manufacturing of central inverter systems to dominate large-footprint deployments. Legrand anchors its position through deep channel control in European electrical distribution. Acuity Brands specializes in intelligent self-testing luminaires that reduce maintenance labor for facility managers.
Emergency lighting denotes battery-backed illumination systems engineered to activate automatically upon mains power failure, typically maintaining minimum egress-path luminance of one foot-candle for ninety minutes per NFPA 101. These systems incorporate sealed lead-acid or lithium-ion battery packs, charging circuitry, and transfer relays to ensure continuous visibility during evacuation. LED emergency luminaires now command the product mix due to superior efficacy and extended service life versus fluorescent predecessors. Self-testing technology is capturing disproportionate investment as remote diagnostics cut manual inspection costs. Wireless connectivity is gaining traction in multi-building campuses where centralized monitoring replaces distributed maintenance rounds.
NFPA 101 in the United States, the EU Construction Products Regulation with CE marking, and India's National Building Code enforced by the Bureau of Indian Standards collectively mandate minimum egress illumination and testing protocols. These frameworks compel building owners to budget for periodic upgrades rather than indefinite equipment retention. Stakeholders must weigh battery chemistry transitions against total cost of ownership as lithium-ion replacements reshape service intervals and disposal obligations.
Market Dynamics
LED technology is decomposing the installed base of fluorescent emergency luminaires, while lithium-ion battery chemistry is compressing maintenance schedules and reshaping supplier economics across commercial real estate portfolios.
Growth Catalysts
- NFPA 101 compliance deadlines:Healthcare facilities in the United States face mandatory egress-path illumination upgrades, forcing capital allocation toward UL 924-certified central inverter systems and self-testing luminaires.
- Wireless monitoring adoption:Multi-building campuses in Germany are deploying mesh-networked emergency lighting to satisfy F-Gas Regulation-linked building efficiency audits while eliminating distributed maintenance rounds.
- LED efficacy thresholds:Extended service life and superior lumen-per-watt performance are pulling replacement demand from fluorescent predecessors in high-occupancy commercial installations.
Market Restraints
- Lithium supply concentration:Battery cell manufacturing clusters in East Asia create geographic single-source risk for European luminaire assemblers seeking to localize production.
- Sealed lead-acid disposal friction:Stricter hazardous waste protocols in multiple jurisdictions impose reverse-logistics costs that erode total cost-of-ownership advantages for legacy battery chemistry.
- Fluorescent aftermarket persistence:Existing ballast infrastructure and maintenance contractor familiarity slow replacement velocity in budget-constrained municipal and educational buildings.
Strategic Opportunities
- Indian National Building Code enforcement:Bureau of Indian Standards mandates for minimum egress illumination in high-rise construction create first-mover positioning for intelligent self-testing systems in rapidly urbanizing metros.
- EU Construction Products Regulation tailwind:CE marking requirements for emergency lighting are accelerating replacement cycles across aging commercial stock in France and Italy.
- Power-over-Ethernet convergence:Integration of emergency luminaires with building automation networks enables centralized monitoring and predictive battery replacement in smart campus deployments.
Industry Challenges
- UL 924 certification timeline compression:Testing laboratory backlog and documentation requirements delay product launches, compressing revenue recognition windows for new luminaire introductions.
- Legacy system integration friction:Retrofit installations must reconcile incompatible control protocols between existing central inverter architectures and networked LED emergency heads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Lighting Market |
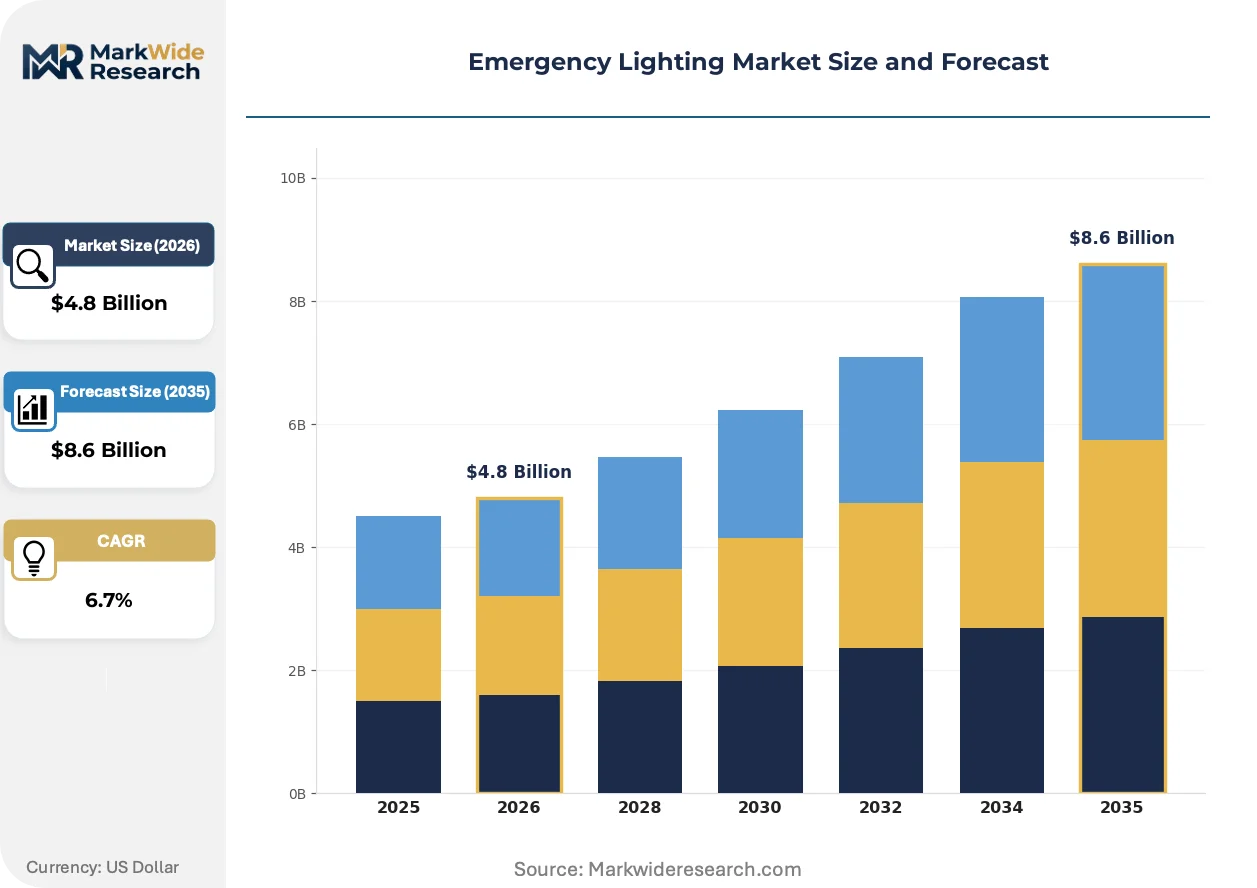
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Installation Type: Hardwired, Plug-in, Battery-operated, Portable End User: Commercial Buildings, Residential Properties, Industrial Facilities, Government Institutions Technology: Self-testing, Wireless, Solar-powered, Hybrid |
| Companies Covered | Eaton Electric, Legrand, Philips Lighting, Emerson, Hubbell Lighting, Schneider Electric, ABB, Cooper Lighting, Acuity Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Lighting Market Emerging Trajectories
Intelligence embedded at the luminaire level is collapsing the distinction between emergency lighting and building automation infrastructure. Three distinct vectors are reorganizing competitive advantage.
Self-diagnostic firmware is decomposing the traditional maintenance contract model. Facility managers in Class A office towers are adopting luminaires that autonomously report battery health and lamp status via Bluetooth Low Energy. This capability is compressing third-party inspection revenue pools while shifting value capture toward hardware vendors with embedded software competency.
Germany's F-Gas Regulation is accelerating refrigerant-phaseout timelines that indirectly tighten building energy budgets. Property owners are responding by specifying emergency lighting with highest-tier efficacy ratings to preserve overall energy performance certificates. This regulatory pressure is filtering specification decisions toward premium LED platforms with integrated controls.
Consolidated procurement by real estate investment trusts is compressing vendor counts. Portfolio managers are awarding multi-site maintenance contracts to single-source providers capable of remote diagnostics across dispersed assets. This concentration is visible most acutely in United States healthcare systems where NFPA 101 compliance liability drives preference for integrated supply agreements covering both equipment and ongoing testing documentation.
Emergency Lighting Market Segmentation
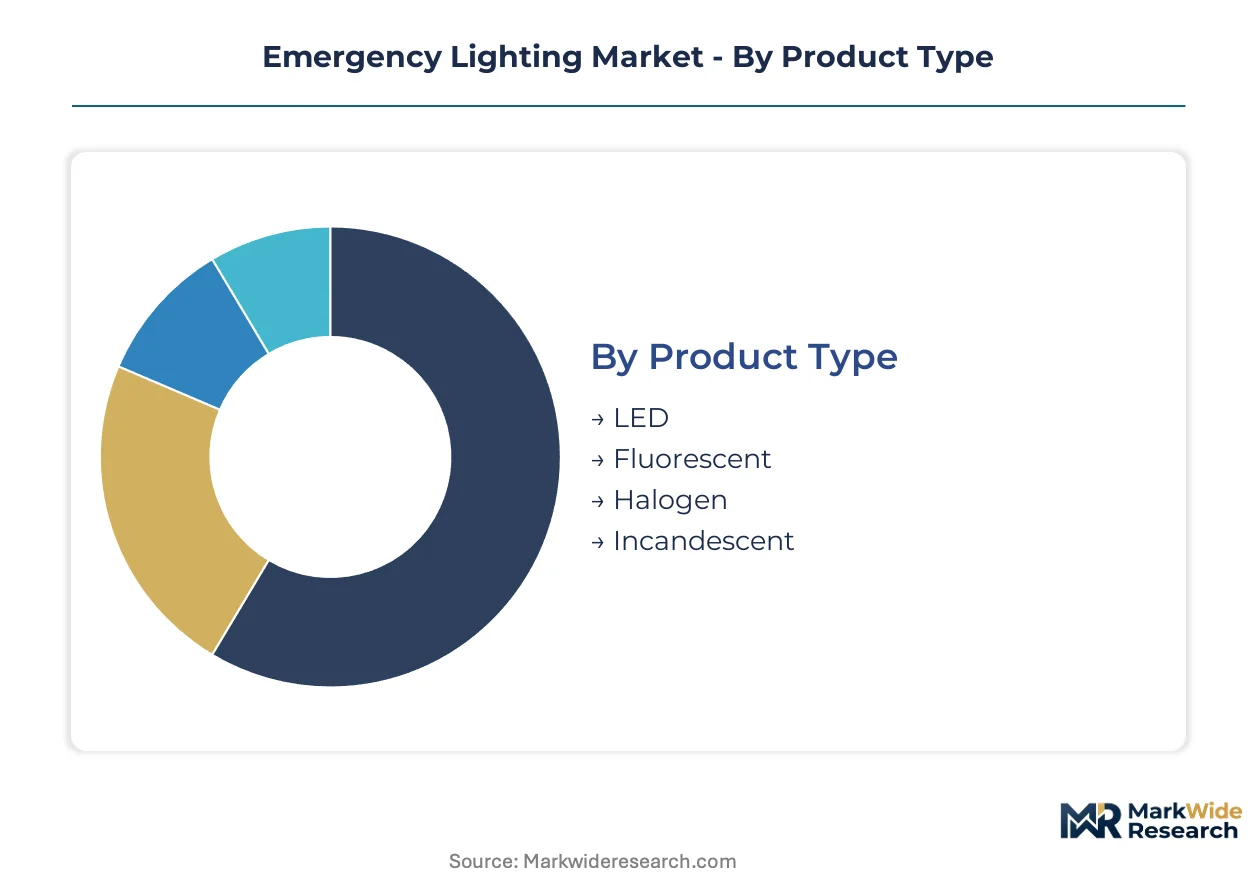
Emergency lighting procurement channels fragment sharply across product categories, with electrical distributors dominating legacy technologies while systems integrators capture connected platforms. Specification decisions increasingly hinge on total cost-of-ownership calculations rather than upfront equipment pricing.
Product Type:
Channel mix varies dramatically by light source, with LED platforms flowing through specification-grade electrical distributors and legacy fluorescent moving through maintenance contractor networks.
- LED:Solid-state luminaires with efficacy ratings exceeding 120 lumens per watt and service lives surpassing 50,000 hours. Demand concentrates in German commercial real estate portfolios where F-Gas Regulation-linked energy audits favor highest-tier efficiency ratings.
- Fluorescent:T5 and compact fluorescent emergency units with magnetic or electronic ballast architectures. Replacement velocity lags in United States municipal buildings where budget constraints preserve existing ballast infrastructure.
- Halogen:Tungsten-halogen emergency heads delivering instant-on illumination for high-temperature industrial environments.
- Incandescent:Legacy filament technology persisting in price-sensitive residential retrofit applications.
By volume, LED leads. By growth pace, LED is climbing the fastest as regulatory mandates accelerate obsolescence of predecessor technologies.
Installation Type:
Cost tier stratification separates permanent infrastructure investments from temporary or supplemental deployments.
- Hardwired:Permanently connected systems integrated into building electrical infrastructure with dedicated circuit protection. Dominates United States healthcare construction where NFPA 101 mandates central inverter architectures for egress-path continuity.
- Battery-operated:Self-contained units with onboard charging circuitry and sealed lead-acid or lithium-ion storage. Expanding most quickly in German multi-building campuses deploying mesh-networked monitoring to eliminate distributed maintenance rounds.
- Plug-in:Cord-connected emergency luminaires for rapid deployment in leased commercial space with limited electrical modification permissions.
- Portable:Mobile battery-powered units for construction sites and temporary event infrastructure.
Hardwired systems capture the largest share of capital expenditure. Battery-operated platforms are gaining share fastest as wireless connectivity reduces lifecycle labor costs.
End User:
Application context dictates specification intensity, with regulated environments demanding certified platforms and unregulated segments tolerating commodity alternatives.
- Commercial Buildings:Class A office towers and retail complexes specifying UL 924-certified or CE-marked systems with remote diagnostic capability. United States healthcare systems drive integrated supply agreements covering equipment and testing documentation.
- Industrial Facilities:Manufacturing plants and warehouses requiring explosion-rated emergency luminaires for hazardous location classifications.
- Government Institutions:Municipal buildings and educational facilities with extended procurement cycles and maintenance contractor familiarity with legacy fluorescent platforms.
- Residential Properties:Multi-family housing and single-family installations with minimal regulatory oversight beyond basic egress requirements.
Commercial buildings generate the highest revenue per installation. Industrial facilities show the steepest expansion trajectory as safety audits tighten globally.
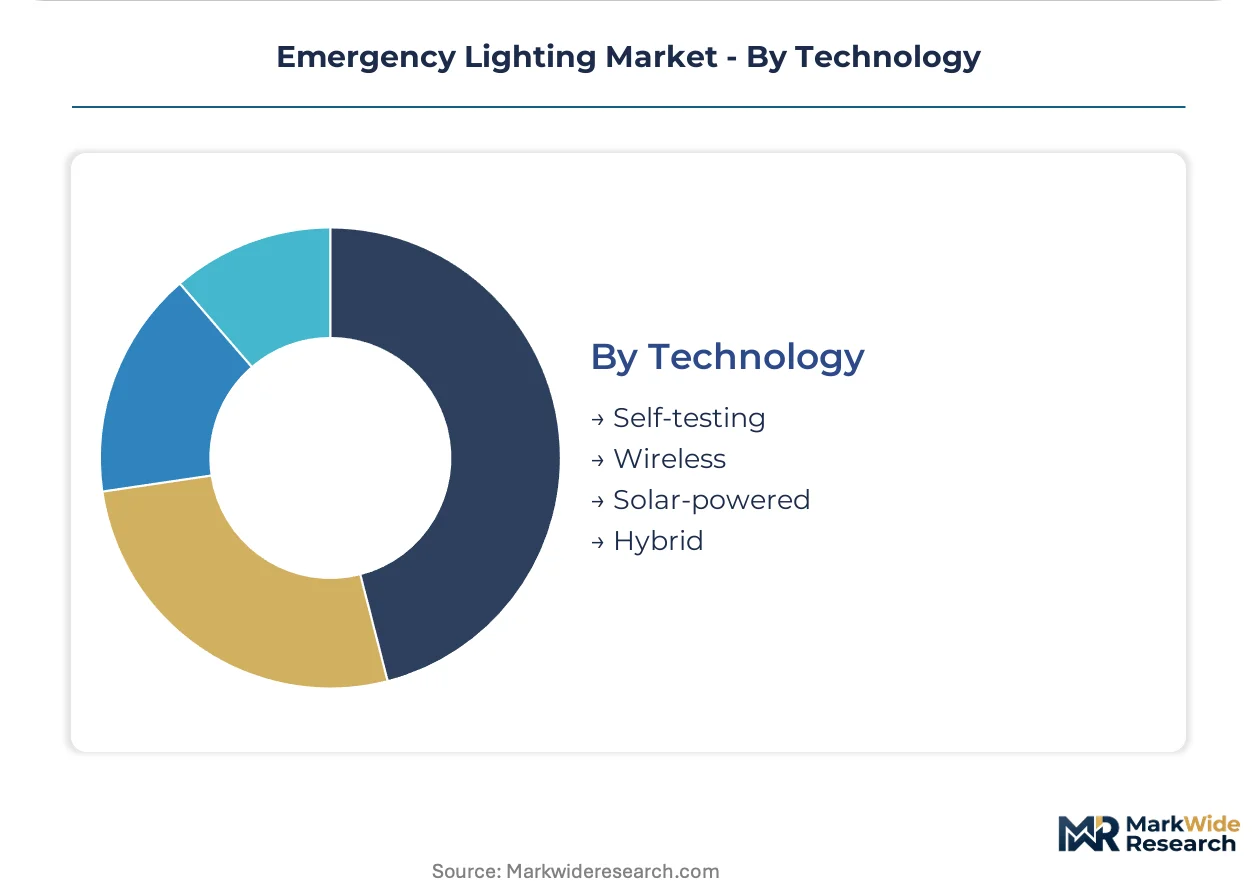
Technology:
Customer type separates facility managers seeking labor reduction from sustainability officers targeting carbon metrics.
- Self-testing:Firmware-enabled luminaires autonomously reporting battery health and lamp status via Bluetooth Low Energy or building automation protocols. United States healthcare facilities adopt these to compress third-party inspection schedules and satisfy NFPA 101 documentation requirements.
- Wireless:Mesh-networked emergency lighting with centralized monitoring dashboards for multi-building portfolios. German property owners deploy these to satisfy F-Gas Regulation-linked efficiency audits while eliminating distributed maintenance rounds.
- Solar-powered:Photovoltaic-integrated emergency units with off-grid capability for remote infrastructure and disaster resilience applications.
- Hybrid:Dual-source systems combining grid charging with solar supplementation for extended autonomy in critical facilities.
Self-testing technology dominates new specification activity. Wireless platforms are expanding most quickly as real estate investment trusts consolidate procurement across dispersed assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of emergency lighting hardware concentrate from German and Chinese manufacturing clusters toward import-dependent markets in India and the Middle East. Trade balances favor producers with integrated battery cell supply chains. Regional regulatory divergence creates specification fragmentation that shapes cross-border procurement patterns.
United States
Healthcare construction and NFPA 101 compliance deadlines drive specification intensity for UL 924-certified central inverter systems. The Department of Energy enforces efficiency standards that accelerate LED displacement of fluorescent emergency heads. Manufacturing concentrates in the Midwest industrial corridor, with Ohio and Michigan hosting captive battery assembly operations for large-footprint deployments.
Germany
Commercial real estate portfolios face F-Gas Regulation-linked energy audits that prioritize highest-tier efficacy ratings in emergency luminaire selection. The EU Construction Products Regulation with CE marking mandates accelerate replacement cycles across aging building stock. Production gravity sits in North Rhine-Westphalia, where electrical distribution channels integrate luminaire assembly with building automation system provisioning.
China
Rapid urbanization and high-rise construction expansion generate volume demand for battery-operated emergency units with basic egress compliance. GB standards enforced by the national standardization administration establish minimum illumination requirements for public buildings. Manufacturing clusters in Guangdong and Zhejiang provinces supply cost-optimized LED emergency heads for export markets across Southeast Asia and Africa.
India
Bureau of Indian Standards mandates for minimum egress illumination in high-rise construction create first-mover positioning for intelligent self-testing systems. The National Building Code enforcement tightens across rapidly urbanizing metros. Industrial activity concentrates in Maharashtra and Gujarat, where electrical equipment distributors build inventory for commercial construction projects in Mumbai and Ahmedabad.
United Arab Emirates
Mega-project construction and hospitality sector expansion drive specification of premium emergency lighting with remote diagnostic capability. Civil defense regulations mandate centralized monitoring systems for high-occupancy buildings. Procurement flows through Dubai-based systems integrators serving Gulf Cooperation Council markets with turnkey compliance documentation.
Emergency Lighting Market Vendor Landscape
Concentration sits with diversified electrical equipment conglomerates that leverage captive battery supply chains and distribution channel control. The vendor base separates into three functional tiers: integrated multinational platforms with central inverter manufacturing, specification-grade luminaire specialists with embedded software competency, and regional assemblers serving price-sensitive retrofit demand. Dominant competitive moves include backward integration into lithium-ion battery pack production and strategic partnerships with building automation systems integrators.
Among the integrated multinational tier, Eaton Electric, Legrand, and Acuity Brands occupy distinct positioning vectors. Eaton Electric exemplifies the captive manufacturing archetype through in-house production of central inverter architectures. Legrand anchors the European channel control model with deep electrical distribution relationships. Acuity Brands represents the intelligent luminaire specialization path, embedding self-diagnostic firmware that compresses third-party maintenance revenue pools.
| Leading Market Players |
|---|
| Eaton Electric |
| Legrand |
| Philips Lighting |
| Emerson |
| Hubbell Lighting |
| Schneider Electric |
| ABB |
| Cooper Lighting |
| Acuity Brands |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with East Asian battery cell manufacturers lock in supply access and price visibility for European luminaire assemblers facing F-Gas Regulation compliance deadlines. These contracts insulate procurement teams from lithium carbonate volatility while committing volume through the analysis window.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing for central inverter systems in United States healthcare construction, where NFPA 101 mandates compress negotiation timelines. Three-tier pricing structure across UL 924-certified premium, standard CE-marked, and economy-grade retrofit tiers reflects certification investment and remote diagnostic capability. Cost compression in the economy tier intensifies as Chinese LED module exports displace legacy fluorescent ballast servicing. Municipal procurement officers exhibit highest price sensitivity due to extended budget cycles, while healthcare facility managers prioritize total cost-of-ownership over upfront equipment spend.
Supply Chain Analysis
Inventory buffers for lithium-ion battery packs stretch to sixteen weeks as German distributors reconcile F-Gas Regulation-linked demand spikes with East Asian cell production schedules. Manufacturing gravity centers on China for LED emergency heads, South Korea for battery cell chemistry, and Germany for central inverter assembly. Raw material flows draw from rare earth processing in China, copper smelting in Chile, and aluminum extrusion in the UAE. Single-source vulnerability concentrates in NMC cathode precursor supply from Chinese chemical complexes. Distribution runs through specification-grade electrical distributors in North America and integrated building automation integrators in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency lighting demand cycles correlate with commercial construction permitting velocity and regulatory compliance deadline clustering. NFPA 101 upgrade mandates in United States healthcare facilities currently sit at the expansion phase of this cycle.
For Market Incumbents: Fortify captive battery pack production through backward integration into lithium-ion cell assembly or strategic offtake with Korean manufacturers. Deepen channel control in German electrical distribution to preempt specification displacement by building automation integrators. The threat of Power-over-Ethernet convergence with IT infrastructure vendors demands firmware competency investment to preserve luminaire-level value capture. For New Entrants and Emerging Players: Lead with wireless mesh-networked emergency lighting targeting Indian high-rise construction in Mumbai and Ahmedabad, where Bureau of Indian Standards enforcement creates specification whitespace absent entrenched incumbent relationships. Position through systems integrator partnerships rather than direct electrical distributor competition, leveraging remote diagnostics as the primary go-to-market wedge against legacy maintenance contractor networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap luminaire specialists with embedded self-testing firmware and established UL 924 certification pipelines, positioned for consolidation by integrated multinational platforms. Long-term viability hinges on software competency differentiation as hardware commoditization accelerates across basic LED emergency heads. The signal to watch is real estate investment trust procurement consolidation toward single-source integrated supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-ion supply secures margin control against East Asian price volatility for European assemblers. |
| Self-Testing Firmware Development | Embedded diagnostics compress third-party maintenance revenue pools and shift value toward hardware vendors. |
| Wireless Mesh Network Deployment | Centralized monitoring eliminates distributed maintenance rounds in German multi-building campuses. |
| UL 924 Certification Pipeline Investment | Testing laboratory relationships accelerate product launches ahead of NFPA 101 compliance deadlines. |
| Systems Integrator Partnership Formation | Building automation channel access preempts displacement by IT infrastructure convergence. |
Methodological Framework
Initial hypotheses were tested against primary input from facility managers at United States healthcare systems, electrical distribution procurement directors, building automation systems integrators, and regulatory compliance officers, then refined through secondary validation against NFPA 101 documentation requirements, UL 924 certification databases, EU Construction Products Regulation filings, and Bureau of Indian Standards enforcement records. Bottom-up luminaire shipment data triangulated against top-down commercial construction permitting velocity across the analysis window.
Variance decomposition across product type, installation architecture, end-use vertical, and technology tier shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling of fluorescent-to-LED transitions and lithium-ion battery chemistry adoption curves. Forecast inputs incorporated F-Gas Regulation audit timelines, NFPA 101 compliance deadline clustering, and real estate investment trust procurement consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or lithium supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding LED efficacy improvement trajectories and wireless connectivity adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Hazard Control Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Global Emergency Beacon Transmitter Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Homeland Security and Emergency Management Market
Emergency and Disaster Management
Emergency and Disaster Response Market