
 Emergency and Disaster Response Market | 2026-2036
Emergency and Disaster Response Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency and Disaster Response Market Foresight
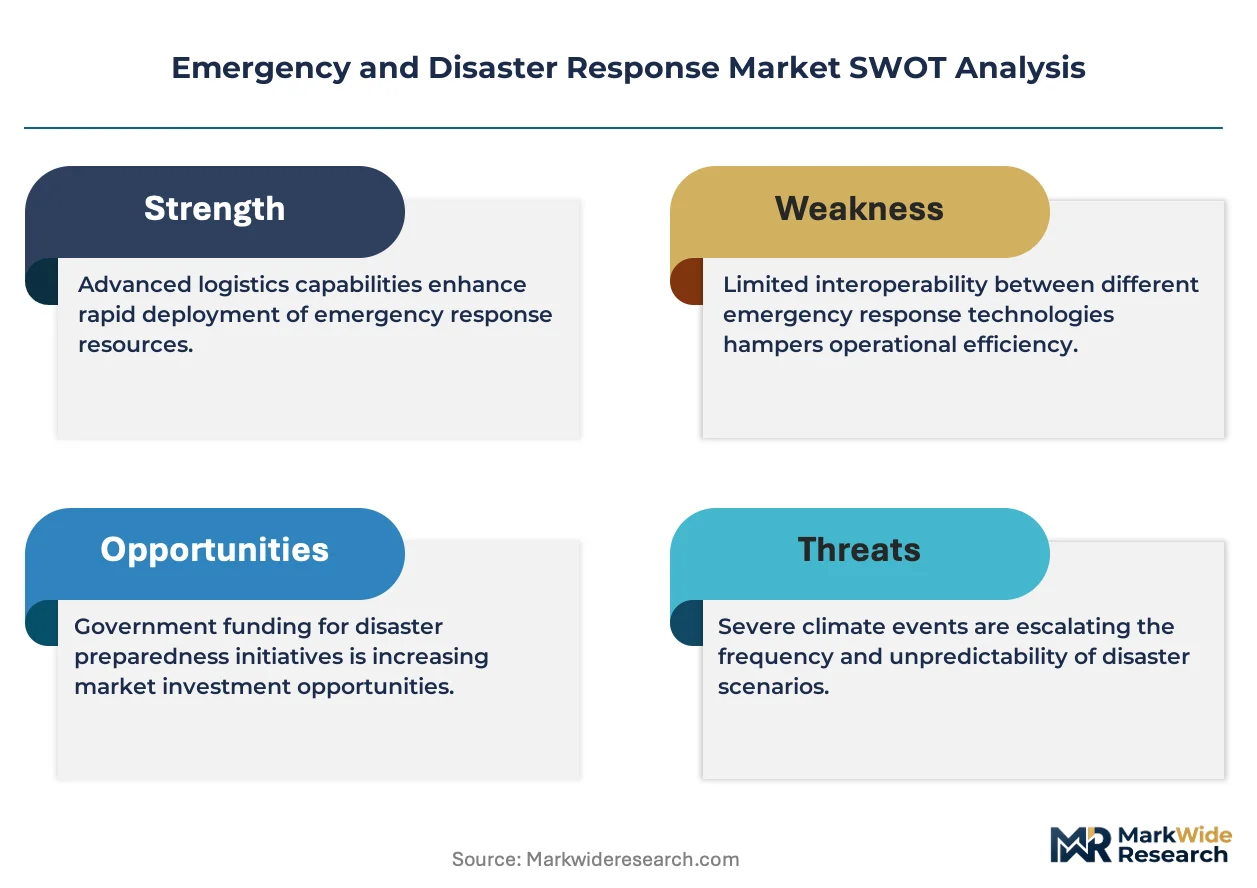
Modular platform bundling is hardening as the dominant procurement pattern for emergency response agencies. Motorola Solutions Inc. leverages its command-center communication stacks to anchor large municipal contracts. Honeywell International Inc. sustains diversified exposure across personal protective equipment and building safety systems. Rosenbauer International AG dominates specialized vehicle manufacturing for fire and rescue deployment.
Emergency and disaster response encompasses coordinated systems, equipment, and services deployed to mitigate, respond to, and recover from hazardous events including natural catastrophes, industrial accidents, and public health crises. Core technical specifications include NFPA 1971 thermal protective performance ratings for turnout gear, IP67 ingress protection for field communication hardware, and redundant satellite-linked dispatch architectures ensuring 99.999% uptime during infrastructure failure. Search & Rescue services command the largest value pool given specialized manpower requirements and aviation asset intensity. Communication Systems technology generates premium margins through encrypted narrowband and LTE interoperability upgrades. Government Agencies represent the most concentrated end-user channel with multi-year appropriation cycles and centralized fleet replacement programs.
FEMA mandates National Incident Management System compliance for federal funding eligibility, forcing standardization across state and local procurement. EPA and OSHA regulations govern hazardous materials response training thresholds and respiratory protection fit-testing protocols, shaping recurring service demand. Stakeholders must monitor spectrum reallocation decisions and next-generation 911 transition timelines to align product roadmaps with interoperability mandates.
Market Dynamics
FEMA's National Incident Management System mandate is compressing procurement timelines across municipal fire departments, forcing vendors to deliver pre-integrated command platforms rather than standalone equipment.
Growth Catalysts
- NFPA 1971 Thermal Protective Standards:Turnout gear replacement cycles accelerate as departments modernize to meet revised thermal protective performance thresholds, sustaining recurring equipment demand.
- United States:Federal appropriations for urban search and rescue task forces expand aviation asset procurement, particularly rotary-wing platforms with hoist-capable configurations.
- Next-Generation 911 Transition:Text-to-911 and multimedia dispatch capabilities drive communication system overhaul, pulling LTE interoperability upgrades into municipal capital budgets.
Market Restraints
- Aluminum and Steel Input Volatility:Specialized vehicle chassis manufacturing faces margin pressure from commodity price swings, constraining Rosenbauer's production scheduling flexibility.
- Spectrum Reallocation Uncertainty:FCC narrowbanding decisions delay narrowband radio replacement cycles, freezing portions of public safety communication spending.
- Aviation Asset Intensity:Search and rescue operations require twin-engine helicopter platforms with night vision goggle compatibility, limiting vendor participation to capital-intensive specialists.
Strategic Opportunities
- Australia:Bushfire response capacity expansion creates demand for mobile command centers with autonomous satellite uplink, particularly in Victoria and New South Wales rural fire districts.
- Dual-Use Drone Convergence:Thermal imaging payloads merged with mesh networking protocols enable wildfire perimeter mapping without manned aviation, opening mid-market agency access.
- EPA Hazardous Materials Training Mandates:Recertification requirements generate recurring service revenue streams for respiratory protection fit-testing and HAZMAT response curriculum delivery.
Industry Challenges
- Interoperability Certification Timelines:P25 compliance testing for land mobile radio systems extends product launch windows, compressing vendor revenue recognition schedules.
- Integrated Platform Integration Complexity:Legacy CAD-to-radio dispatch bridges require custom middleware development, straining municipal IT resources during system cutover phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency and Disaster Response Market |
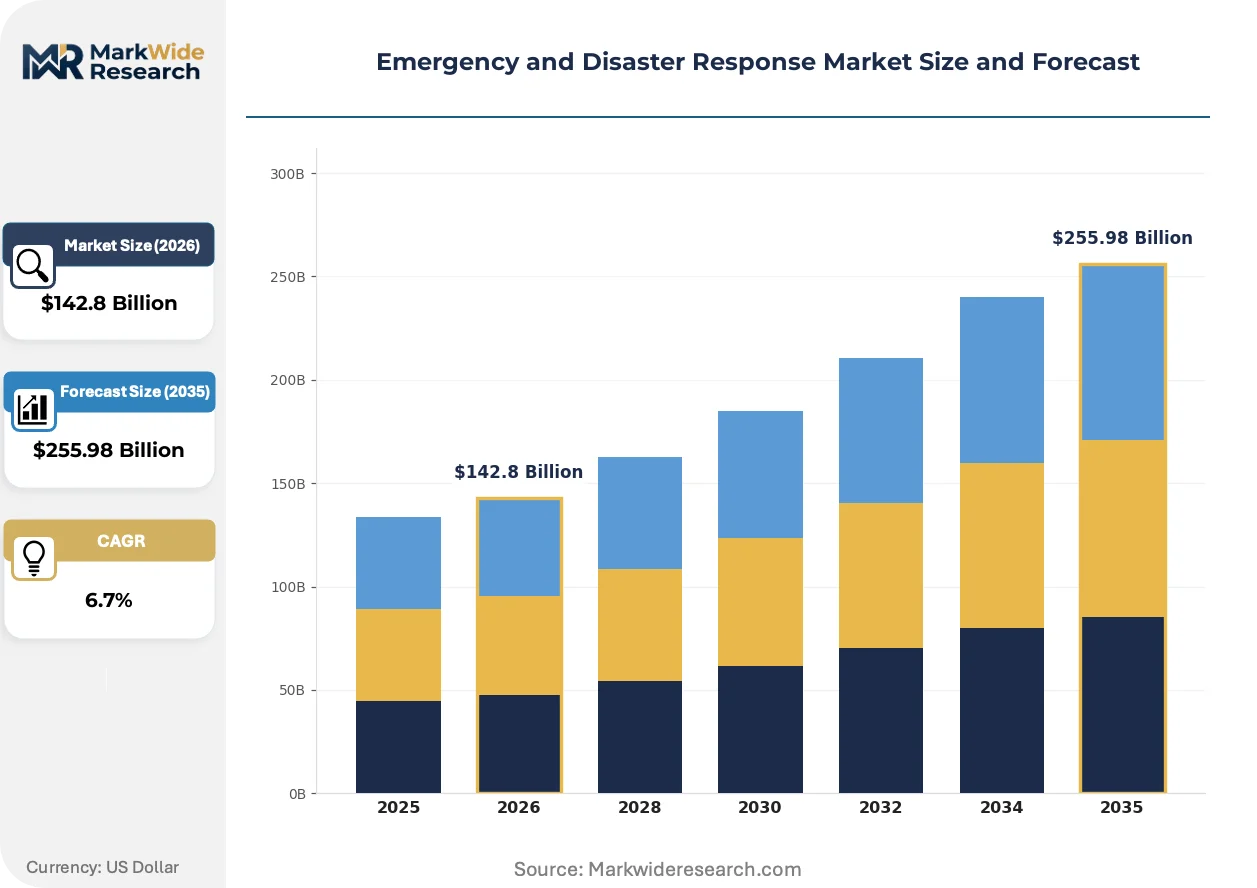
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $255.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Search & Rescue, Medical Assistance, Logistics Support, Disaster Recovery Technology: Drones, Communication Systems, Mobile Apps, Geographic Information Systems End User: Government Agencies, NGOs, Private Sector, Community Organizations Application: Natural Disasters, Humanitarian Crises, Industrial Accidents, Public Health Emergencies |
| Companies Covered | Rosenbauer International AG, Motorola Solutions Inc., Honeywell International Inc., 3M, Esri Inc., Everbridge Inc., Leonardo S.p.A., Textron Inc., Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency and Disaster Response Market Shifts & Advancements
Command-center software stacks are absorbing adjacent functions previously handled by standalone hardware, collapsing procurement categories into unified platform decisions.
LTE-to-narrowband interoperability gateways are unifying previously siloed communication protocols. Large municipal fire departments in California and Texas are deploying these bridges during 2024-2025 fleet replacement cycles. The technology is unifying dispatch architectures that previously required separate maintenance contracts for each radio generation.
REACH chemical registration requirements in Europe are tightening respiratory protection filter specifications. German industrial fire brigades must now document substance-specific cartridge compatibility for HAZMAT scenarios. Turnout gear manufacturers serving the European market are reformulating barrier layer materials to satisfy expanded substance restriction lists.
Consolidated fleet replacement programs now dominate municipal procurement, displacing incremental equipment purchases. State-level cooperative purchasing agreements in the United States aggregate demand across multiple jurisdictions, compressing vendor sales cycles. Texas and Florida emergency management districts exemplify this concentration, issuing multi-year vehicle and communication system awards to single-source integrators.
Emergency and Disaster Response Market Segmentation
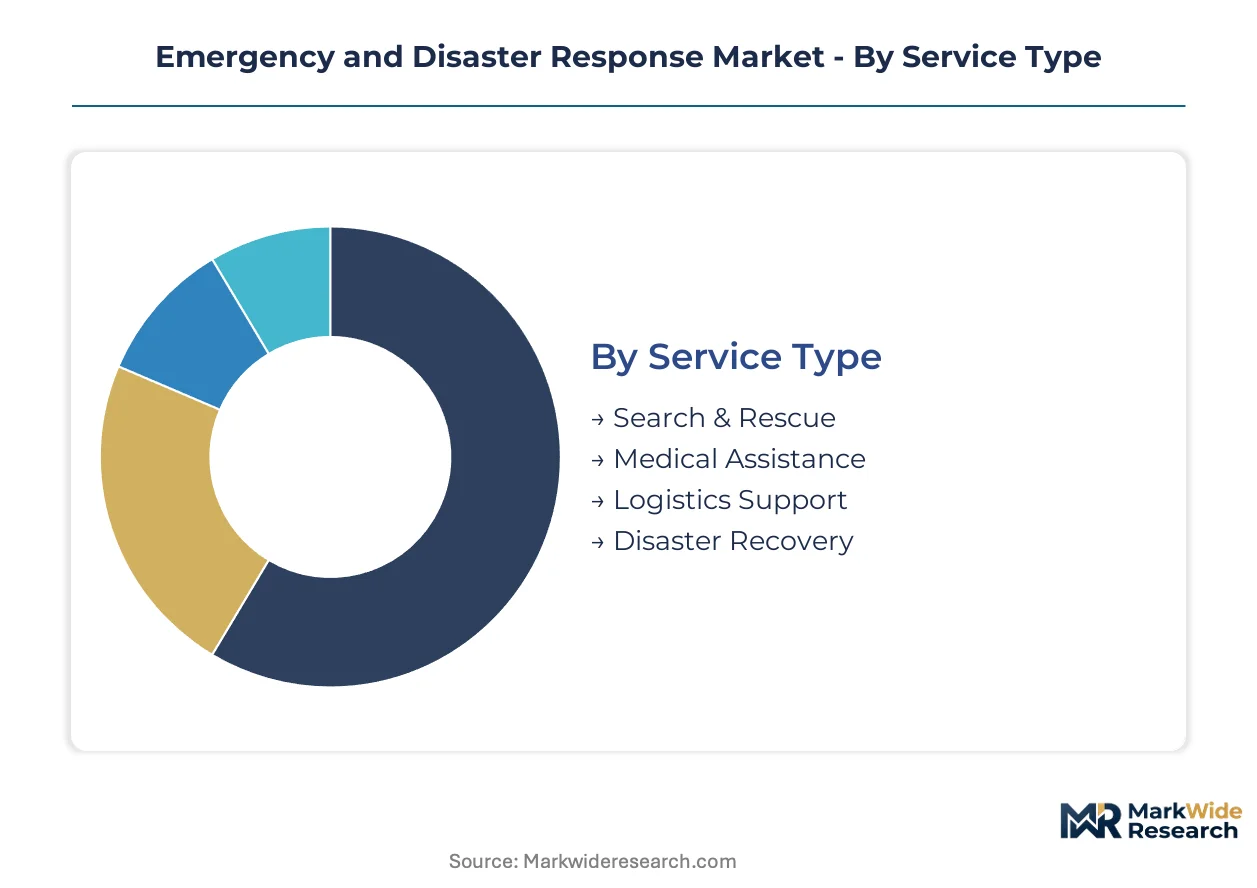
Emergency response procurement splits across four distinct category systems, each governing different budget authorities and technical standards. Service type determines labor cost structures and aviation asset requirements. Technology selection drives interoperability mandates and replacement cycles. End user classification shapes funding mechanisms and compliance thresholds. Application context dictates equipment specifications and deployment protocols.
Service Type:
Budget allocation patterns diverge sharply based on whether services require specialized manpower, heavy equipment, or recurring training infrastructure.
- Search & Rescue:Twin-engine rotary-wing platforms with night vision goggle compatibility anchor capital expenditure profiles. United States urban search and rescue task forces drive aviation asset procurement, particularly hoist-capable helicopter configurations for structural collapse scenarios.
- Medical Assistance:Mobile field hospitals and mass casualty triage systems require ISO 13485 medical device compliance for deployable equipment. German industrial fire brigades sustain demand for physician-staffed emergency response vehicles with advanced life support capabilities.
- Logistics Support:Cold chain preservation and fuel distribution networks enable sustained operations in infrastructure-denied environments.
- Disaster Recovery:Debris removal and temporary power restoration services generate demand for heavy equipment leasing and contractor mobilization.
Search & Rescue leads volumes today; Medical Assistance is gaining share fastest.
Technology:
Procurement cycles compress or extend based on spectrum allocation decisions and legacy system depreciation schedules.
- Drones:Thermal imaging payloads merged with mesh networking protocols enable wildfire perimeter mapping without manned aviation. Australia bushfire response capacity expansion drives demand for autonomous satellite uplink integration in Victoria and New South Wales rural fire districts.
- Communication Systems:LTE-to-narrowband interoperability gateways unify previously siloed dispatch architectures. California and Texas municipal fire departments deploy these bridges during fleet replacement cycles, collapsing separate maintenance contracts into unified platform decisions.
- Mobile Apps:Text-to-911 and multimedia dispatch capabilities pull smartphone-based reporting into next-generation emergency response workflows.
- Geographic Information Systems:Real-time flood modeling and hazmat plume dispersion tools require sub-meter accuracy and redundant data feeds.
Communication Systems commands the largest installed base; Drones shows the steepest expansion trajectory.
End User:
Funding stability and procurement flexibility vary with appropriation cycles and regulatory oversight intensity.
- Government Agencies:Multi-year appropriation cycles and centralized fleet replacement programs concentrate demand. FEMA mandates National Incident Management System compliance for federal funding eligibility, forcing standardization across state and local procurement in the United States.
- NGOs:Humanitarian cluster coordination mechanisms and donor reporting requirements shape equipment procurement specifications for international deployment.
- Private Sector:OSHA respiratory protection fit-testing protocols and EPA hazardous materials training mandates generate recurring service revenue for industrial fire brigades.
- Community Organizations:Volunteer capacity limitations drive demand for simplified equipment interfaces and reduced training burden.
Government Agencies dominates absolute spending; Private Sector shows the most rapid budget expansion.
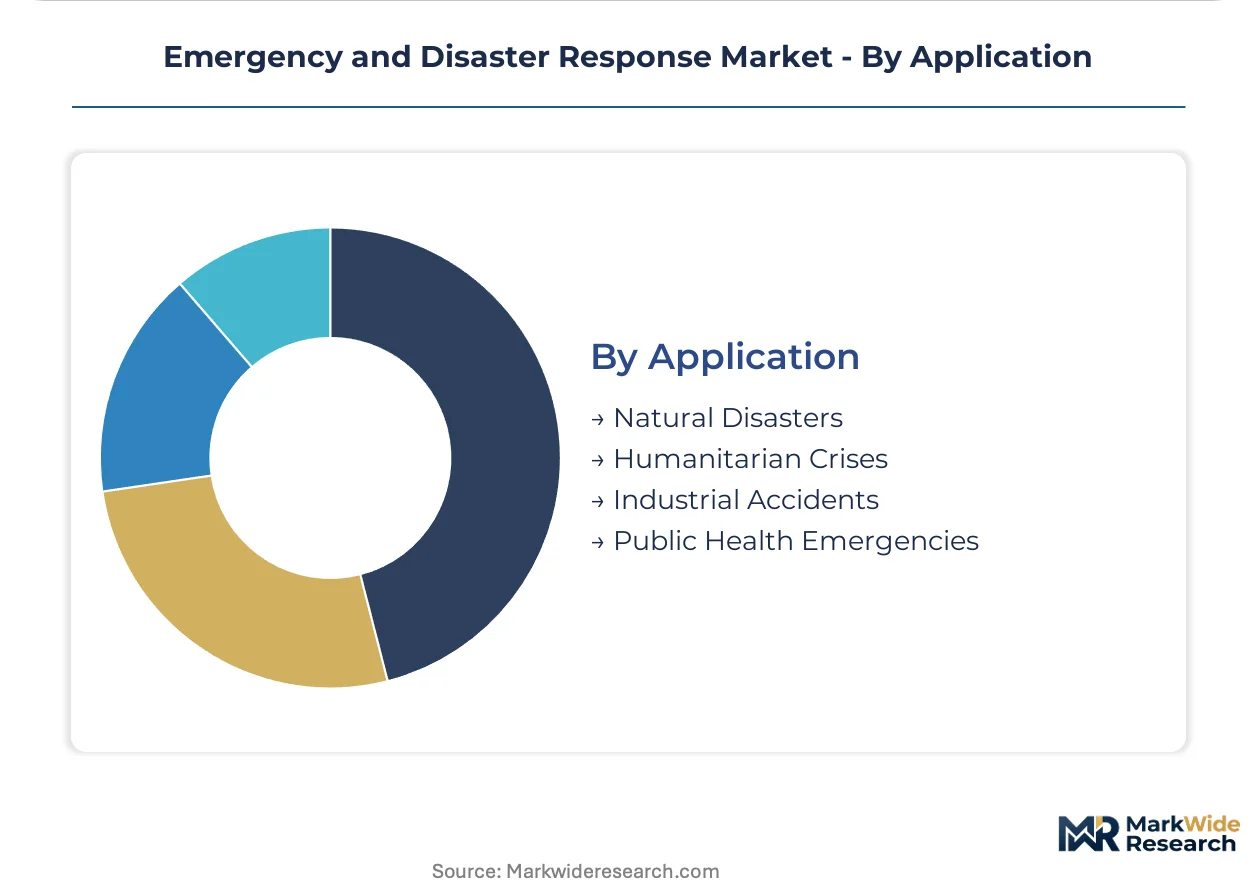
Application:
Event frequency and severity profiles determine equipment redundancy requirements and mutual aid dependency.
- Natural Disasters:Hurricane, earthquake, and wildfire response requires scalable surge capacity and interstate compact activation protocols. Australia bushfire seasons drive mobile command center procurement with autonomous communications.
- Humanitarian Crises:Refugee camp management and population displacement response demands modular shelter systems and water purification assets.
- Industrial Accidents:Chemical release and refinery fire scenarios mandate HAZMAT-specific respiratory protection and substance-specific cartridge documentation under REACH requirements in Europe.
- Public Health Emergencies:Pandemic response and mass vaccination deployment requires surge medical staffing and pharmaceutical cold chain infrastructure.
Natural Disasters accounts for the greatest equipment throughput; Public Health Emergencies expanded most quickly in recent procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emergency and disaster response infrastructure first achieved systematic scale in post-war Europe and the United States through civil defense frameworks. These historical foundations established procurement protocols and technical standards that now propagate across emerging markets. Contemporary demand concentrates in jurisdictions with mature regulatory enforcement and climate-exposed geographies.
United States
FEMA's National Incident Management System mandates unified command protocols for federal funding eligibility, compressing procurement timelines across municipal fire departments. FCC spectrum reallocation decisions govern narrowband radio replacement cycles, freezing portions of public safety communication spending. California and Texas emergency management districts exemplify consolidated fleet replacement programs, issuing multi-year vehicle and communication system awards to single-source integrators.
Germany
Industrial fire brigades sustain demand for physician-staffed emergency response vehicles with advanced life support capabilities. REACH chemical registration requirements tighten respiratory protection filter specifications, forcing turnout gear manufacturers to reformulate barrier layer materials. Bavaria's rural fire districts anchor specialized vehicle procurement, with Rosenbauer International AG maintaining manufacturing presence in the region.
Australia
Bushfire response capacity expansion creates demand for mobile command centers with autonomous satellite uplink in Victoria and New South Wales rural fire districts. TGA medical device compliance governs deployable field hospital equipment for mass casualty scenarios. Queensland's emergency services coordinate interstate compact activation protocols during cyclone seasons, driving scalable surge capacity investments.
Japan
Meteorological Agency earthquake early warning systems mandate redundant communication architectures for infrastructure resilience. METI industrial safety regulations govern hazardous materials response training thresholds for refinery and chemical complex operators. Kanto region municipalities deploy LTE-to-narrowband interoperability gateways during fleet replacement cycles, unifying previously siloed dispatch systems.
United Kingdom
Home Office counter-terrorism preparedness programs fund urban search and rescue task force aviation asset procurement. HSE respiratory protection fit-testing protocols shape recurring service demand for industrial emergency response contractors. London Fire Brigade anchors integrated command platform deployment, collapsing separate maintenance contracts into unified procurement decisions.
Emergency and Disaster Response Market Competitive Landscape
The competitive structure tilts toward integrated platform specialists with established command-center communication stacks. Motorola Solutions Inc. anchors large municipal contracts through pre-integrated procurement offerings. Honeywell International Inc. sustains diversified exposure across personal protective equipment and building safety systems. Rosenbauer International AG dominates specialized vehicle manufacturing for fire and rescue deployment. Market participants pursue strategic partnerships with satellite communications providers and expand geographic presence through state-level cooperative purchasing agreements.
Within the integrated platform tier, Motorola Solutions Inc. and Honeywell International Inc. exemplify diversified technology conglomerates with emergency response verticals. Rosenbauer International AG occupies a specialized position in fire and rescue vehicle manufacturing, representing capital-intensive fabrication expertise. These three entities anchor distinct competitive vectors: communication infrastructure, multi-product safety systems, and purpose-built response vehicles respectively.
| Leading Market Players |
|---|
| Rosenbauer International AG |
| Motorola Solutions Inc. |
| Honeywell International Inc. |
| 3M |
| Esri Inc. |
| Everbridge Inc. |
| Leonardo S.p.A. |
| Textron Inc. |
| Hexagon AB |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Austrian and German fire apparatus manufacturing anchor production scheduling discipline, translating order backlogs into stable pricing for municipal fleet replacement programs while constraining discounting flexibility during commodity volatility periods.
Pricing Analysis
Project-based contracting with multi-year appropriation lock-ins dominates municipal procurement, separating integrated platform bundles from standalone equipment transactions. Price differentiation hinges on NFPA certification tier and after-sales service bundling for turnout gear lifecycle management. Cost compression in specialized vehicle chassis intensifies because aluminum and steel input volatility erodes fixed-margin contracts. State cooperative purchasing agreements in Texas and Florida exhibit lowest price sensitivity; volunteer fire departments in rural districts show highest.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Upper Austrian fabrication clusters limit Rosenbauer's production expansion despite order accumulation. Supply concentrates in Germany, Austria, and the United States for purpose-built response vehicles and command-center hardware. Raw material dependencies span aerospace-grade aluminum, satellite communication chipsets, and thermal protective fabric weaves. Single-source vulnerability in narrowband radio chipset supply feeds from FCC spectrum reallocation uncertainty. Distribution runs through state-level cooperative purchasing agreements and federal fleet replacement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Municipal procurement shifts toward NFPA 1971-certified thermal protective performance specifications justify premium positioning for compliant equipment manufacturers.
For Market Incumbents: Deploy backward integration into thermal protective fabric weaving to secure NFPA 1971 compliance margins against commodity volatility. Lock in multi-year service contracts for respiratory protection fit-testing to capture EPA-mandated recurring revenue. Counter drone-based wildfire mapping entrants by bunding mesh-networked thermal payloads into existing command-center stacks.
For New Entrants and Emerging Players: Launch via direct contracting with Victoria and New South Wales rural fire districts for autonomous satellite uplink mobile command centers. Target Australia's bushfire response capacity expansion as the most penetrable geography. Penetrate through dual-use drone convergence with thermal imaging and mesh networking protocols, avoiding capital-intensive aviation asset competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among communication system specialists with LTE-to-narrowband interoperability gateway portfolios. Long-term viability favors integrated platform vendors with FEMA National Incident Management System compliance embedded in municipal procurement workflows. Watch FCC spectrum reallocation decisions as the inflection signal for narrowband radio replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Platform Bundling | Collapses standalone equipment procurement into unified command-center decisions per FEMA mandate. |
| LTE Interoperability Gateway Deployment | Unifies siloed dispatch architectures across California and Texas municipal fire departments. |
| Dual-Use Drone Convergence | Enables wildfire perimeter mapping without manned aviation capital intensity for mid-market agencies. |
| Respiratory Protection Service Contracts | Captures EPA-mandated HAZMAT recertification revenue from industrial fire brigades. |
| State Cooperative Purchasing Agreements | Aggregates demand across Texas and Florida emergency management districts for volume leverage. |
Research Methodology
Coverage spans the United States, Germany, Australia, Japan, and the United Kingdom, with primary inputs from each market. Primary interviews incorporated fire chiefs, municipal procurement officers, FEMA regional administrators, industrial fire brigade safety directors, and satellite communications integration specialists. Secondary validation drew from FCC spectrum allocation filings, NFPA standard revision documentation, EPA hazardous materials training mandates, and FEMA National Incident Management System compliance guidelines. Bottom-up equipment shipment tracking and top-down appropriation cycle analysis enabled triangulation across the analysis window.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology platform, end-user funding mechanism, and application scenario severity. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and aviation asset procurement pipeline assessment. Specific forecast inputs incorporated Next-Generation 911 transition timelines and REACH chemical registration expansion effects on respiratory protection specifications.
Several conditions sit outside the modeled scope, including unscheduled natural disaster frequency, sovereign debt crises affecting municipal bond financing, and abrupt spectrum reallocation decisions. Forecasts reflect assumptions about regulatory compliance deadline adherence and appropriation cycle continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Global Emergency Notification Software Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Incident and Emergency Management Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Blankets Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market