
 North America Physical Security Market | 2026-2036
North America Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
North America Physical Security Market Analytics
Data center operators and critical infrastructure owners is realigning procurement priorities toward unified physical-cyber platforms. Honeywell International Inc. leverages its building automation heritage to dominate integrated command-and-control installations across federal facilities. Axis Communications AB specializes in edge-computing camera architectures that reduce bandwidth loads for remote oil and gas monitoring sites. Motorola Solutions Inc. anchors public safety demand through its Avigilon video analytics portfolio and land-mobile radio integration.
Physical security encompasses hardware, software, and services that detect, deter, and respond to unauthorized access, theft, sabotage, or violence against personnel, property, and information assets; systems typically integrate video capture at 4K resolution minimum, multi-factor biometric authentication with liveness detection, and edge-based AI inference processing below 150 milliseconds latency. Video surveillance commands the largest installed base across North American commercial real estate, though cloud-based deployment grows fastest as enterprises retire on-premise network video recorder infrastructure. Access control systems capture premium margin pools through subscription-managed identity services, while perimeter security remains concentrated in transportation and utility verticals with federally mandated buffer zone requirements.
The US Department of Homeland Security issues Chemical Facility Anti-Terrorism Standards that mandate layered perimeter detection, while Transport Canada enforces Marine Transportation Security Regulations requiring port video retention exceeding ninety days. The US FAA coordinates with airport operators to integrate physical access control with credentialing databases under TSA-approved specifications. Stakeholders must monitor divergence between US federal procurement mandates and Canadian provincial privacy frameworks governing biometric data retention, as compliance fragmentation will determine vendor eligibility across cross-border infrastructure projects.
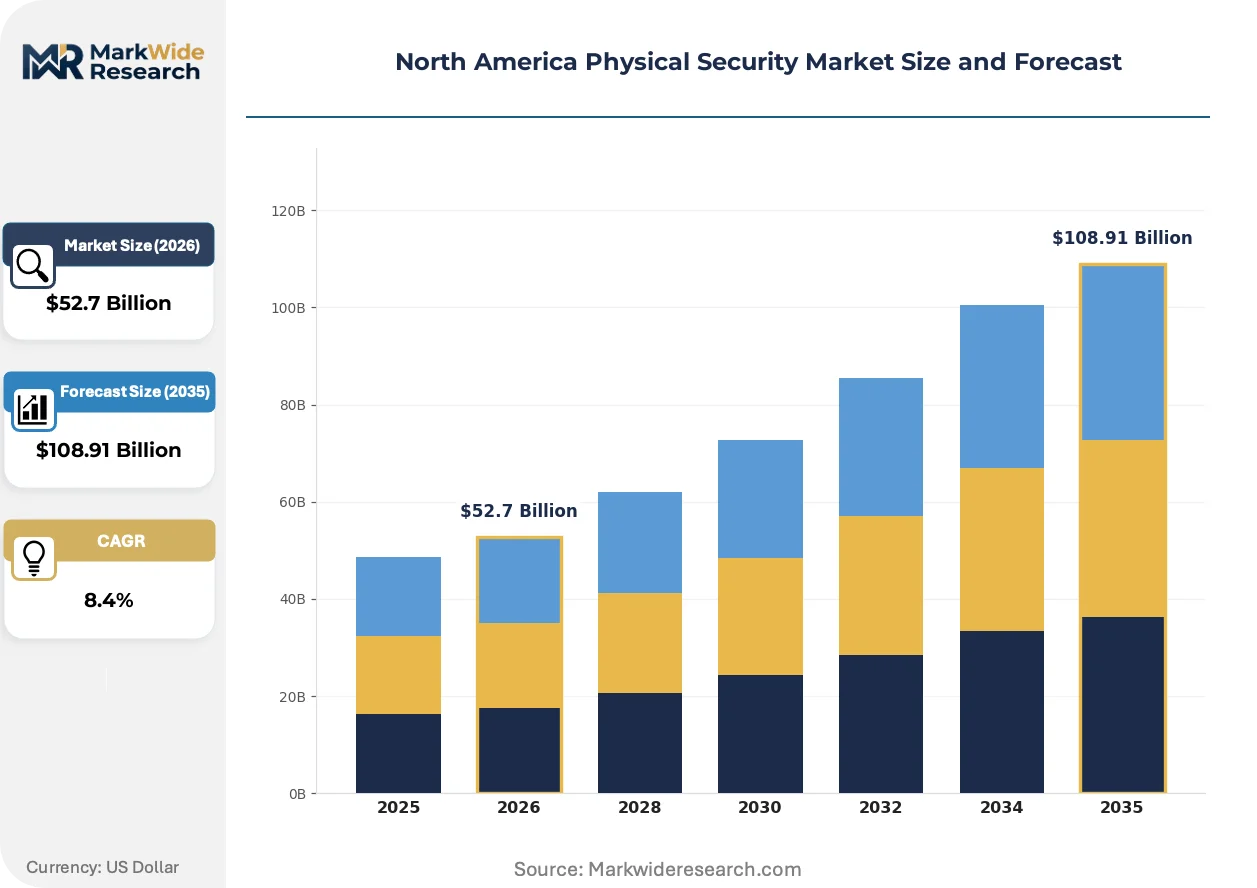
Market Dynamics
Federal infrastructure spending is compressing procurement cycles as state agencies accelerate perimeter hardening at ports and utilities, while data center operators in the US Southwest consolidate vendor relationships around unified physical-cyber platforms.
Growth Catalysts
- IIJA Funding Mandates:The US Infrastructure Investment and Jobs Act directs capital toward hardened perimeter protection at airports and utilities, creating immediate procurement pull-through for integrated surveillance systems.
- Data Center Cluster Expansion:Phoenix and Dallas metropolitan areas are driving large-scale biometric and video analytics deployments as hyperscale facility construction accelerates.
- Edge AI Inference:Sub-150 millisecond latency requirements for real-time threat detection are forcing upgrades from legacy network video recorder infrastructure to edge-computing camera architectures.
Market Restraints
- Semiconductor Supply Concentration:Image sensor and AI accelerator chip fabrication concentrates in East Asian foundries, exposing North American integrators to geopolitical supply disruption.
- Biometric Privacy Fragmentation:Divergent US federal procurement mandates and Canadian provincial privacy frameworks governing biometric data retention create compliance complexity for cross-border infrastructure projects.
- Legacy System Interoperability:Analog-to-IP migration costs and proprietary protocol lock-in from incumbent access control vendors extend replacement cycles in commercial real estate.
Strategic Opportunities
- Subscription Identity Services:Cloud-managed credentialing and mobile access credentials are displacing on-premise physical access control systems in mid-market commercial portfolios.
- Remote Oil and Gas Monitoring:Bandwidth-constrained extraction sites in Alberta and Texas present untapped demand for edge-computing camera architectures with local storage and intermittent cloud sync.
- TSA-Approved Credentialing Integration:FAA-coordinated physical access control specifications at US airports create vendor eligibility barriers that favor early-certified integrators.
Industry Challenges
- Unified Platform Integration:Converging physical security with IT network operations requires cross-functional expertise in cybersecurity, video analytics, and building automation that remains scarce in traditional installer channels.
- Ninety-Day Video Retention Compliance:Transport Canada's Marine Transportation Security Regulations impose storage infrastructure costs that strain municipal port authority budgets and technical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Physical Security Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Surveillance, Access Control, Alarm Systems, Perimeter Security End User: Government, Retail, Transportation, Healthcare Deployment: On-Premise, Cloud-Based, Hybrid, Managed Security Technology: IP Cameras, Biometrics, RFID, Sensors |
| Companies Covered | Honeywell International Inc., Bosch Security Systems GmbH, Genetec Inc., Johnson Controls, Axis Communications AB, ADT Inc., Hikvision, Cisco Systems Inc., Motorola Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Physical Security Market Evolving Landscape
Edge computing architectures are redistributing processing load away from centralized data centers, while regulatory mandates harden data retention requirements and procurement models shift toward managed service consumption.
Edge-based AI inference engines embedded directly within camera housings are decentralizing video analytics processing from on-premise servers to distributed endpoints. Oil and gas operators in remote Permian Basin and Alberta sites are adopting these architectures fastest due to bandwidth constraints. This topology reduces backhaul costs and enables real-time alerting without continuous cloud connectivity.
The US Chemical Facility Anti-Terrorism Standards mandate layered perimeter detection with specific sensor spacing and response protocols. Chemical manufacturing sites along the Gulf Coast and Ohio River corridor are retrofitting fence-line detection and thermal imaging to meet compliance deadlines. Facility operators are consolidating vendor relationships to simplify audit documentation and reduce integration complexity.
Enterprise buyers are consolidating physical security spend under IT procurement functions, displacing traditional facilities-management purchasing channels. Financial services and healthcare verticals in the US Northeast are leading this transition, driven by cybersecurity insurance requirements and board-level risk oversight. This reconfiguration favors vendors with API-first platforms and SOC 2 certification over legacy hardware specialists.
North America Physical Security Market Segmentation
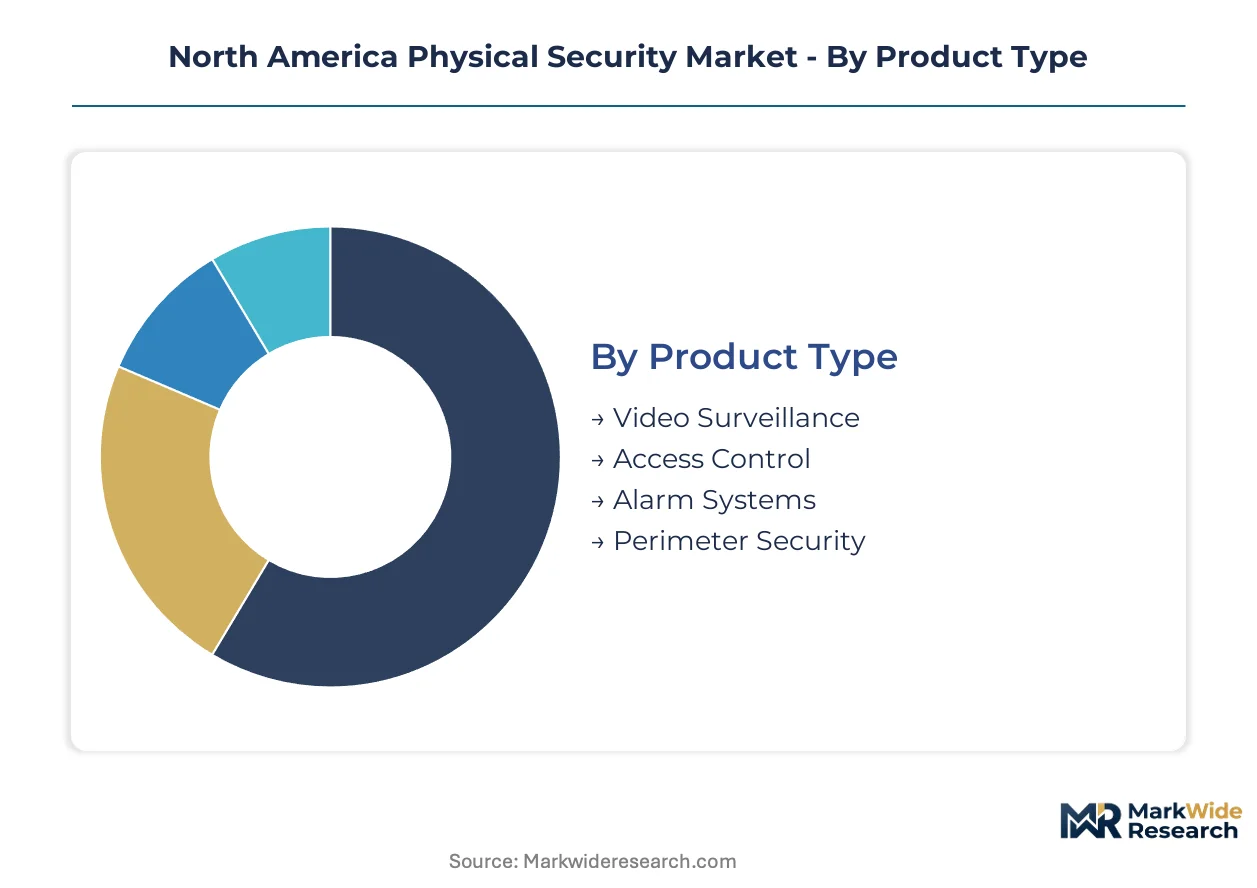
Physical security procurement in North America fragments across integration depths, from standalone perimeter hardware to unified building automation platforms. Buyers prioritize segments that compress procurement cycles under federal infrastructure mandates while satisfying cross-border compliance requirements.
Product Type:
Integration depth varies sharply across product categories, with standalone systems dominating legacy estates while embedded platforms capture new construction.
- Video Surveillance:Systems capture 4K resolution minimum with edge-based AI inference below 150 milliseconds latency. Demand concentrates in Phoenix and Dallas data center clusters where hyperscale operators deploy unified physical-cyber platforms for real-time threat detection.
- Access Control:Multi-factor biometric authentication with liveness detection anchors enterprise deployments. Financial services and healthcare verticals in the US Northeast are displacing on-premise physical access control systems with subscription-managed identity services.
- Alarm Systems:Intrusion detection sensors integrate with building automation networks for automated response protocols.
- Perimeter Security:Layered fence-line detection systems with thermal imaging satisfy US Chemical Facility Anti-Terrorism Standards mandates.
Video Surveillance leads volumes today; Access Control is gaining share fastest.
End User:
Cost tier stratification separates federally funded critical infrastructure from commercial real estate with constrained capital budgets.
- Government:Federal facilities prioritize hardened perimeter protection under IIJA funding mandates with TSA-approved credentialing specifications. State agencies accelerate procurement cycles at ports and utilities.
- Retail:Loss prevention deployments favor cloud-based video analytics with mobile credentialing for high-turnover staff.
- Transportation:US airports integrate physical access control with FAA-coordinated credentialing databases; Canadian ports face ninety-day video retention requirements under Transport Canada regulations.
- Healthcare:HIPAA compliance drives biometric authentication for pharmaceutical storage and patient data protection zones.
Government leads volumes today; Transportation is expanding most quickly.
Deployment:
Volume concentration sits with legacy on-premise infrastructure while margin pools shift toward recurring-revenue service models.
- On-Premise:Network video recorder infrastructure dominates commercial real estate estates but faces retirement pressure from cybersecurity insurance requirements.
- Cloud-Based:Enterprises in bandwidth-constrained Permian Basin and Alberta oil fields adopt intermittent cloud sync with local edge storage.
- Hybrid:Split architectures preserve sensitive biometric processing on-site while pushing archival storage to cloud tiers.
- Managed Security:Subscription models displace capital expenditure in mid-market commercial portfolios lacking internal security operations centers.
On-Premise leads volumes today; Cloud-Based is climbing the fastest.
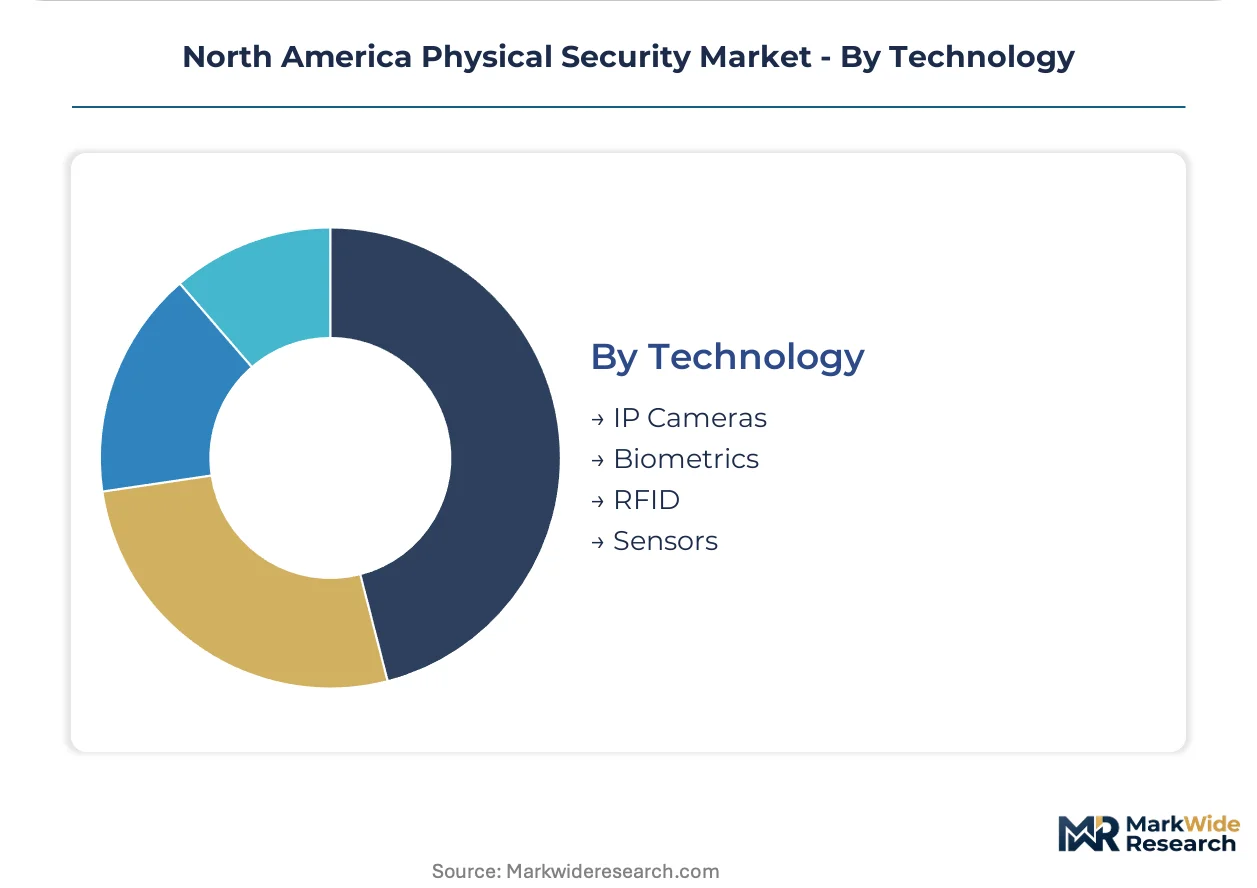
Technology:
Supply concentration in East Asian foundries shapes procurement risk profiles across sensor and processing categories.
- IP Cameras:Edge-computing architectures with embedded inference engines reduce backhaul costs for remote monitoring sites.
- Biometrics:Liveness detection algorithms face compliance fragmentation between US federal procurement mandates and Canadian provincial privacy frameworks.
- RFID:Credentialing systems integrate with mobile wallet platforms for touchless access in high-throughput environments.
- Sensors:Thermal and fence-line detection arrays serve chemical facility perimeter hardening requirements along the Gulf Coast.
IP Cameras leads volumes today; Biometrics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Phoenix-Dallas data center corridor is compressing procurement cycles for biometric and video analytics systems as hyperscale operators deploy unified physical-cyber platforms across newly constructed facilities.
United States
Federal infrastructure spending and data center construction dominate demand. The Infrastructure Investment and Jobs Act channels capital toward hardened perimeter protection at ports and utilities. Phoenix and Dallas metropolitan areas are driving large-scale biometric deployments as hyperscale facility construction accelerates.
Canada
Transport Canada regulations and provincial privacy frameworks shape procurement decisions. The Marine Transportation Security Regulations impose ninety-day video retention requirements on port authorities. Alberta oil and gas extraction sites are adopting edge-computing camera architectures with local storage for bandwidth-constrained remote monitoring.
Mexico
Cross-border manufacturing corridors and energy infrastructure drive perimeter security demand. Mexican federal energy regulators mandate layered detection systems at strategic petroleum storage terminals. Industrial parks in Nuevo León and Baja California are integrating access control with US credentialing databases for seamless cross-border logistics.
North America Physical Security Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors consolidate around unified command-and-control platforms. The market structures into three tiers: diversified industrial conglomerates with building automation heritage, pure-play video surveillance specialists with edge-computing architectures, and integrated security service providers with recurring revenue models. Competitive moves concentrate on technology licensing for AI inference engines and backward integration into sensor manufacturing to reduce supply chain exposure.
Among diversified industrial conglomerates, Honeywell International Inc. and Johnson Controls occupy positions anchored by federal facility relationships and building automation integration capabilities. Motorola Solutions Inc. exemplifies the public safety-focused archetype through land-mobile radio and video analytics convergence. Axis Communications AB sits within the specialized video surveillance tier with edge-computing camera architectures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bosch Security Systems GmbH |
| Genetec Inc. |
| Johnson Controls |
| Axis Communications AB |
| ADT Inc. |
| Hikvision |
| Cisco Systems Inc. |
| Motorola Solutions Inc. |
| Others |
Value Network & Pricing Analysis
CMOS image sensor spot prices cascade through North American physical security manufacturing tiers, compressing margins for integrators serving mid-market commercial real estate while hyperscale data center operators absorb volatility through long-term supply agreements.
Pricing Analysis
Input-cost pass-through from East Asian foundries dominates pricing dynamics across camera and biometric hardware tiers. Three-tier pricing structure across premium, standard, and economy levels separates TSA-certified airport integrators from municipal port authorities and retail loss-prevention deployments. Price differentiation hinges on UL 294 certification grade and after-sales service bundling. Cost compression in standard-tier access control is intensifying because semiconductor supply concentration limits vendor negotiation leverage. Municipal port authorities exhibit highest price sensitivity; federal facilities demonstrate lowest due to IIJA funding insulation.
Supply Chain Analysis
US federal Buy American Act provisions and Canadian domestic content requirements for critical infrastructure are reshaping sourcing strategies for perimeter hardware procurement. Component fabrication concentrates in Taiwan, South Korea, and China for image sensors, AI accelerators, and edge-computing processors. North American integrators draw from overseas foundries for liveness-detection chipsets and thermal imaging arrays. Single-source vulnerability in advanced node semiconductor manufacturing exposes security system lead times to geopolitical disruption. Distribution runs through authorized dealer networks serving regional installer channels with project-based fulfillment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America Physical Security Market functions as a regulatory compounder where IIJA funding mandates and TSA-approved credentialing specifications create durable demand visibility for compliant vendors.
For Market Incumbents: Acquire edge-computing camera architecture specialists to close capability gaps against Axis Communications' bandwidth-optimized deployments. Consolidate around unified command-and-control platforms to defend against IT procurement function encroachment. Backward integration into sensor manufacturing reduces exposure to East Asian foundry concentration risk. For New Entrants and Emerging Players: Enter via subscription-managed identity services targeting mid-market commercial portfolios lacking internal security operations centers. Bandwidth-constrained Permian Basin oil extraction sites present the most penetrable geography for edge-storage-with-intermittent-sync architectures. Partner with building automation integrators to bypass traditional facilities-management purchasing channel lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with SOC 2-certified platform vendors serving financial services and healthcare verticals where cybersecurity insurance requirements accelerate IT procurement consolidation. Long-term viability favors vendors with API-first architectures and recurring-revenue service models over legacy hardware specialists. Monitor FAA credentialing database integration progress as inflection indicator for airport security vendor eligibility barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified physical-cyber command centers satisfy IIJA-mandated perimeter hardening at US ports and utilities. |
| Acquisition of Specialist Firm | Edge-computing camera architects reduce backhaul costs for Alberta and Texas bandwidth-constrained extraction sites. |
| Strategic Partnership | TSA-approved credentialing collaborations create vendor eligibility barriers favoring early-certified integrators. |
| Product Launch | Biometric liveness-detection systems address compliance fragmentation between US federal and Canadian provincial frameworks. |
| Geographic Expansion | Phoenix-Dallas data center corridor deployments capture hyperscale facility construction acceleration. |
Research Methodology
Multiple input streams — primary interviews with security system integrators, facility managers, and IT procurement officers; secondary validation through DHS CFATS filings, FAA credentialing specifications, and Transport Canada regulatory databases; plus customs trade data for sensor component flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, deployment model, end-user vertical, and regional regulatory cluster dimensions anchored the analytical framework throughout the forecast period. CAGRs were derived from installed base retirement curves and new construction pipeline tracking. Edge AI inference latency requirements and ninety-day video retention compliance costs served as industry-specific forecast inputs.
Inputs from federal procurement databases and provincial privacy commission rulings were available through the study window; gaps in real-time hyperscale data center construction timelines introduce uncertainty bands around Phoenix-Dallas corridor demand estimates. Forecasts reflect documented assumptions regarding IIJA funding disbursement velocity and cross-border infrastructure project regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Canada Data Center Physical Security Market
Physical Security
Security Guard Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Body Armor Market
Physical Security
Global Wearable Security Device Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Security Market
Physical Security
Smart Police Helmet Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Physical Security Services Market