
 Homeland Security and Emergency Management Market | 2026-2036
Homeland Security and Emergency Management Market Size, Share, and Industry Trends Forecast 2026-2036
Homeland Security and Emergency Management Market Analysis
Platform licensing revenue is reshaping margin distribution between hardware sales and recurring software subscriptions in the homeland security sector. Lockheed Martin Corporation leverages its satellite communications backbone to sustain long-term service contracts with federal clients. Northrop Grumman Corporation dominates unmanned systems integration for border surveillance applications. Thales Group anchors European demand through encrypted communication networks deployed across NATO member states.
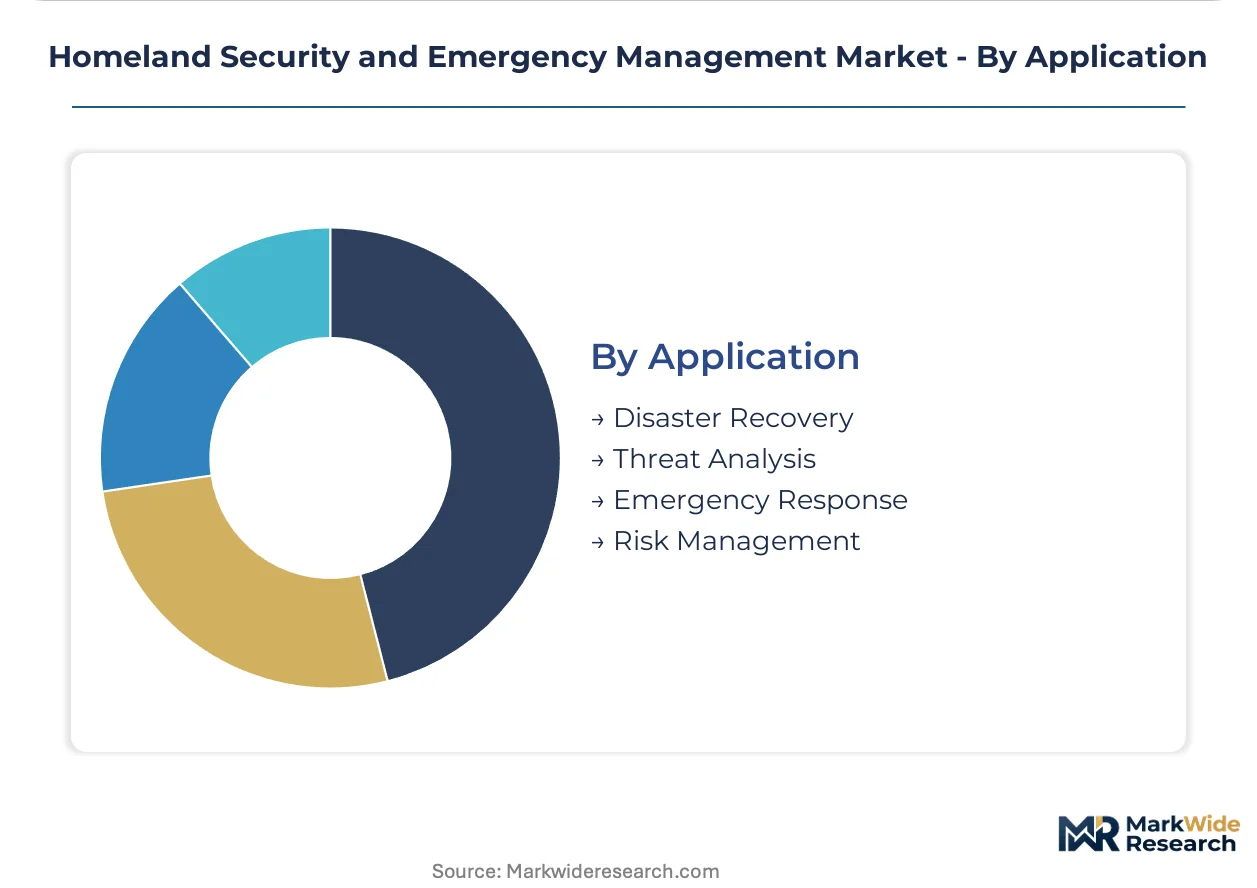
Homeland security and emergency management encompasses the coordinated systems, technologies, and protocols designed to prevent, prepare for, respond to, and recover from threats to national security and public safety, incorporating real-time sensor fusion, multi-agency communication interoperability, and predictive analytics operating across classified and unclassified networks. Surveillance equipment within the solution segment captures the largest share of current procurement budgets as agencies prioritize perimeter and critical infrastructure monitoring. Cybersecurity within the technology segment represents the fastest-expanding capability area as ransomware attacks against municipal systems and energy grids intensify. Disaster recovery within the application segment remains mature with established funding mechanisms, though threat analysis is gaining share as artificial intelligence enables pattern recognition across intelligence streams.
The US Department of Homeland Security coordinates federal grant programs that shape state-level purchasing priorities, while the EU AI Act restricts biometric surveillance deployments in public spaces, forcing vendors to reconfigure product architectures for European compliance. India's BIS certification requirements for electronic security equipment create additional market access conditions for imported systems. Stakeholders must monitor evolving cross-border data sovereignty rules that determine where threat intelligence can be stored and processed.
Market Dynamics
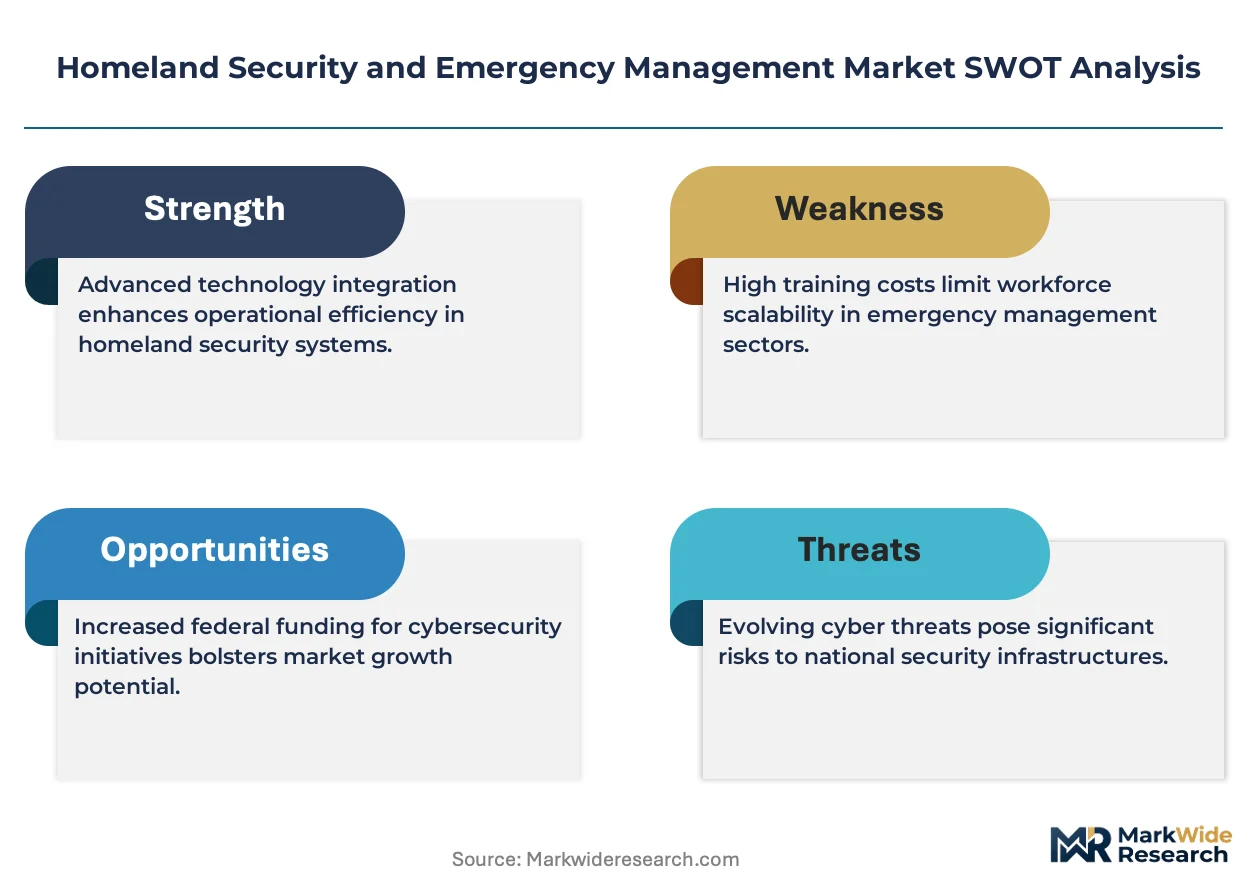
The convergence of artificial intelligence with legacy surveillance infrastructure is compressing procurement cycles for federal agencies while forcing vendors to re-architect product lines for algorithmic transparency mandates. This structural pressure reshapes competitive positioning across hardware, software, and services layers.
Growth Catalysts
- EU AI Act compliance requirements:Vendors investing in explainable AI for biometric systems unlock access to European public procurement channels previously restricted by black-box prohibitions.
- Critical infrastructure protection mandates:Energy utilities and water treatment facilities accelerate sensor deployment to meet NERC CIP and EPA cybersecurity directives.
- India:Smart city initiatives in Mumbai, Delhi, and Bangalore generate sustained demand for integrated command-and-control platforms linking traffic, emergency services, and disaster response.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwanese and South Korean foundries for advanced image processors creates vulnerability in thermal camera and drone payload manufacturing.
- Export control friction:US Bureau of Industry and Security restrictions on geospatial software and AI training data limit vendor eligibility for certain foreign contracts.
- Interoperability technical debt:Legacy radio systems operating on proprietary protocols resist integration with IP-based emergency networks, forcing costly rip-and-replace decisions.
Strategic Opportunities
- Underpenetrated sub-Saharan Africa:Nigeria, Kenya, and South Africa present whitespace for mobile-based early warning systems bypassing fixed infrastructure gaps.
- Convergence of satellite imagery and edge AI:Onboard processing in low-earth orbit constellations enables real-time disaster assessment without ground station latency.
- US Infrastructure Investment and Jobs Act:Broadband expansion funds create attached demand for rural emergency communication networks and resilient backup systems.
Industry Challenges
- Security clearance bottlenecks:Personnel vetting backlogs at Defense Counterintelligence and Security Agency delay deployment of cleared technical staff to classified programs.
- Multi-agency integration complexity:Fusion centers struggle to normalize data formats across FBI, DHS, state police, and municipal fire departments with incompatible legacy databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homeland Security and Emergency Management Market |
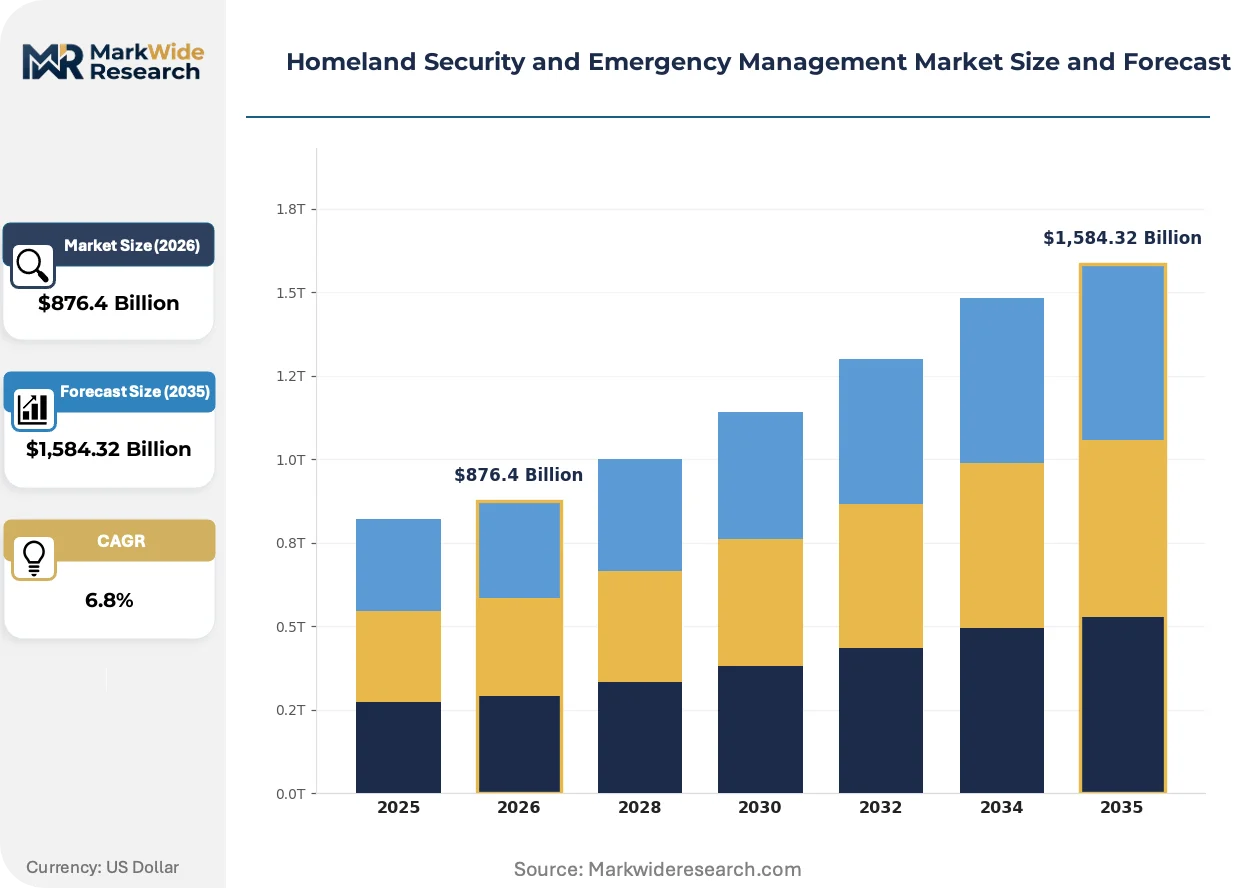
| Market Size in 2026 | $876.4 Billion |
| Market Size in 2035 | $1,584.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Security Systems, Surveillance Equipment, Access Control, Communication Solutions End User: Government Agencies, Military, First Responders, Private Sector Technology: Biometrics, Cybersecurity, Geospatial Technology, Drones Application: Disaster Recovery, Threat Analysis, Emergency Response, Risk Management |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems Plc, General Dynamics Corporation, Thales Group, Raytheon Technologies Corporation, L3Harris Technologies Inc., Elbit Systems Ltd., CACI International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homeland Security and Emergency Management Market Emerging Trajectories
Sensor fusion architectures are collapsing the distinction between physical and cyber threat detection, requiring vendors to build unified platforms rather than point solutions. This integration imperative drives consolidation across historically siloed product categories.
Multi-spectral imaging systems combining thermal, visual, and radar signatures into single analytic streams is migrating from military-exclusive deployments to commercial border and facility applications. Customs and Border Protection pilots in Arizona and Texas validate operational reliability for 24-hour perimeter monitoring. The technology is migrating from classified programs to municipal police and private critical infrastructure operators, compressing price premiums and expanding addressable market volume.
The EU AI Act's prohibited practices list for biometric identification in public spaces forces vendors to disable real-time facial recognition features in European deployments. Industrial consequence includes mandatory human-in-the-loop review requirements and algorithmic impact assessments before procurement approval. Border control and transportation security segments in Germany, France, and Netherlands now prioritize behavioral analytics and object detection over identity matching, redirecting R&D investment toward pattern-recognition alternatives.
Subscription-based platform licensing is displacing perpetual software sales across federal and state procurement channels. Lockheed Martin and Northrop Grumman service contracts demonstrate preference for operational expenditure models with embedded upgrade cycles. This shift concentrates buyer power with agencies possessing multi-year budget authority while squeezing smaller vendors lacking balance sheet capacity for deferred revenue recognition.
Homeland Security and Emergency Management Market Segmentation
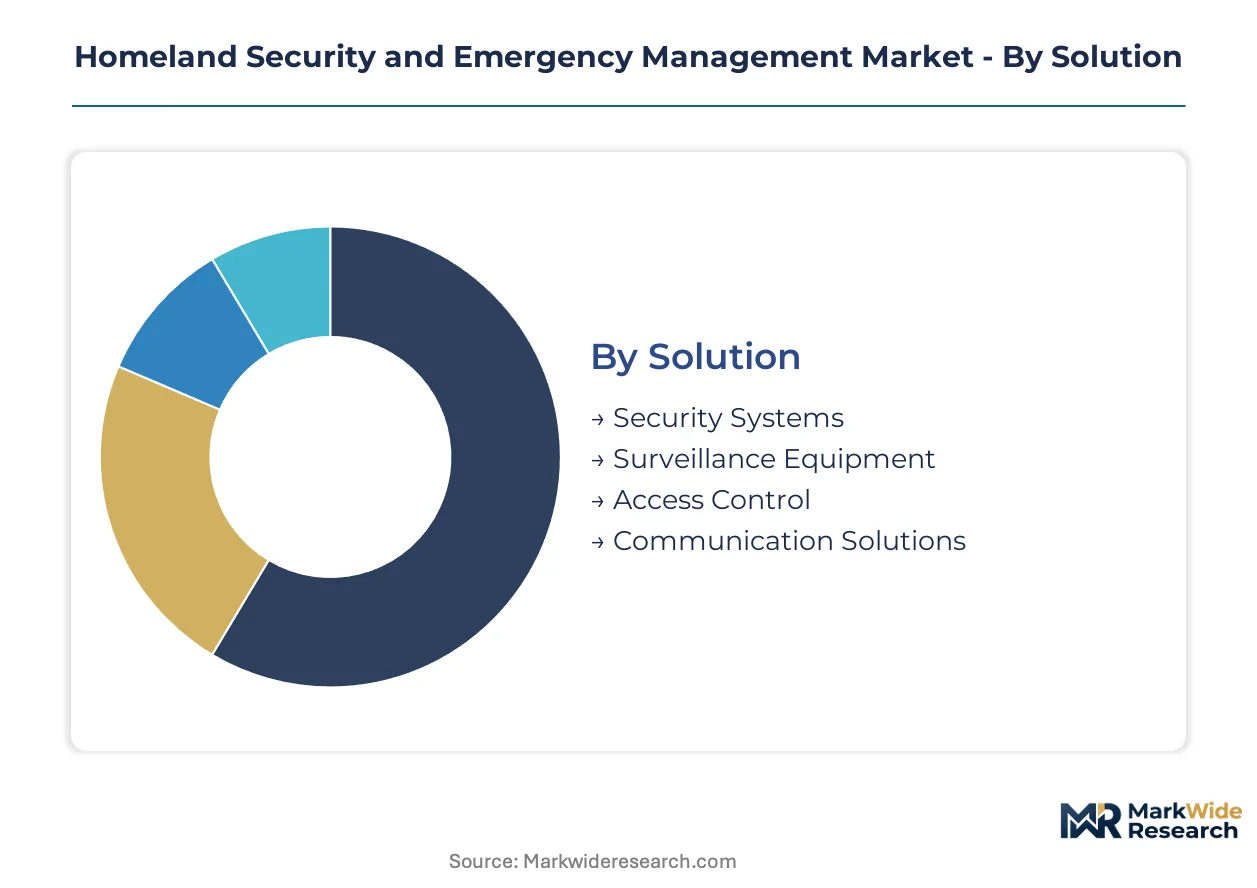
Segmentation in homeland security and emergency management reveals distinct procurement rhythms across solution types, end users, and technology layers. Federal agencies rotate capital budgets on multi-year cycles while cybersecurity subscriptions renew annually, creating heterogeneous cash flow profiles for vendors serving mixed accounts.
Solution:
Surveillance equipment turns over fastest as sensor generations compress from five-year to three-year refresh intervals, while security systems endure decade-long installations with modular upgrade paths.
- Surveillance Equipment:Multi-spectral imaging arrays combining thermal, visual, and radar signatures into unified analytic streams. Demand concentrates at US Customs and Border Protection installations in Arizona and Texas, driven by 24-hour perimeter monitoring mandates and congressional funding for southern border infrastructure.
- Security Systems:Integrated command-and-control platforms unifying access control, intrusion detection, and mass notification across facility networks. India's smart city initiatives in Mumbai, Delhi, and Bangalore generate sustained procurement for urban-scale deployments linking traffic management with emergency services coordination.
- Access Control:Biometric and credential-based entry systems for critical infrastructure facilities.
- Communication Solutions:Encrypted radio and satellite networks enabling interoperability between agencies with incompatible legacy protocols.
Security systems dominate installed base. Surveillance equipment is where expansion concentrates.
End User:
Government agencies absorb premium pricing for certified systems, while private sector buyers prioritize cost efficiency and faster deployment timelines.
- Government Agencies:Federal, state, and municipal departments operating under standardized procurement regulations. The US Department of Homeland Security shapes purchasing priorities through grant programs that require NERC CIP and EPA cybersecurity compliance for energy and water infrastructure recipients.
- Military:Classified programs demanding cleared personnel and air-gapped network architectures. Deployment velocity slows due to Defense Counterintelligence and Security Agency vetting backlogs that delay technical staff placement.
- First Responders:Fire departments, police units, and emergency medical services requiring interoperable communication.
- Private Sector:Critical infrastructure operators in energy, transportation, and telecommunications.
Government agencies anchor revenue stability. Private sector is climbing the fastest as regulatory mandates expand to commercially operated infrastructure.
Technology:
Biometrics and drones command hardware margins, while cybersecurity and geospatial layers generate recurring software revenue with superior retention economics.
- Cybersecurity:Defensive systems protecting municipal networks and industrial control systems from ransomware campaigns. German, French, and Dutch procurement channels prioritize behavioral analytics over identity matching after EU AI Act restrictions on real-time biometric identification in public spaces.
- Drones:Unmanned aerial platforms with onboard edge processing for real-time disaster assessment. Nigeria, Kenya, and South Africa present whitespace for mobile-based deployment models that bypass fixed infrastructure gaps in sub-Saharan markets.
- Biometrics:Fingerprint, iris, and facial recognition systems for identity verification.
- Geospatial Technology:Satellite imagery and mapping systems for threat visualization and resource allocation.
Biometrics holds the largest deployed footprint. Cybersecurity is where expansion concentrates.
Application:
Disaster recovery commands established funding mechanisms with predictable renewal patterns, while threat analysis absorbs discretionary investment sensitive to budget volatility.
- Threat Analysis:Artificial intelligence-enabled pattern recognition across intelligence streams for predictive security posture. US fusion centers drive demand despite integration complexity normalizing data formats across FBI, DHS, state police, and municipal fire databases with incompatible legacy architectures.
- Disaster Recovery:Coordinated response and infrastructure restoration protocols following natural or man-made catastrophes. Funding mechanisms remain mature with established federal-state cost-sharing formulas, though climate intensification is stretching resource allocation models.
- Emergency Response:Real-time coordination of personnel and assets during active incidents.
- Risk Management:Procedural frameworks for identifying, assessing, and mitigating security vulnerabilities.
Disaster recovery dominates installed base. Threat analysis is gaining share fastest as AI capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb premium pricing for EU AI Act-compliant systems, while procurement in India and sub-Saharan Africa prioritizes cost efficiency and mobile-first deployment models.
United States
Customs and Border Protection drives demand for multi-spectral imaging arrays at Arizona and Texas installations under 24-hour perimeter monitoring mandates. The Department of Homeland Security shapes state-level purchasing through grant programs requiring NERC CIP compliance for energy infrastructure recipients. Congressional funding for southern border infrastructure sustains procurement velocity through federal fiscal cycles.
Germany
Federal Police and transportation security agencies prioritize behavioral analytics over biometric identity matching following EU AI Act restrictions on real-time facial recognition. The country's national data protection regulator enforces algorithmic impact assessments before procurement approval. Industrial clusters in Bavaria and Baden-Württemberg host encrypted communication network deployments across NATO interoperability frameworks.
India
Smart city initiatives in Mumbai, Delhi, and Bangalore generate sustained procurement for integrated command-and-control platforms. BIS certification requirements for electronic security equipment create market access conditions for imported surveillance systems. State-level disaster management authorities in Maharashtra and Karnataka accelerate sensor deployment for urban emergency coordination.
France
CNIL oversight of biometric surveillance deployments redirects vendor investment toward pattern-recognition alternatives for border control applications. The country's national cybersecurity agency mandates compliance frameworks for critical infrastructure operators. Defense and interior ministry procurement in the Île-de-France region concentrates on satellite-integrated emergency communication networks.
United Kingdom
Home Office funding for counter-terrorism and border security sustains demand for fusion center analytics platforms. The country's national surveillance camera commissioner enforces data protection standards for public space monitoring. Metropolitan Police Service procurement in London validates operational requirements for multi-agency interoperability systems.
Homeland Security and Emergency Management Market Vendor Landscape
Defense conglomerates and specialized technology providers split the market between integrated platform contracts and component subsystem sales. Consolidation pressure concentrates buyer power with agencies possessing multi-year budget authority. Tier-one integrators and mid-tier specialists represent the dominant strategic archetypes. Competitive moves center on algorithmic transparency investments for European compliance and subscription-based licensing transitions.
Within the tier-one integrator segment, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the shift toward recurring service contracts over perpetual hardware sales. Thales Group occupies a position bridging European regulatory compliance with NATO interoperability requirements. These three entities represent contrasting geographic anchoring strategies for vendor eligibility under divergent export control and data sovereignty regimes.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems Plc |
| General Dynamics Corporation |
| Thales Group |
| Raytheon Technologies Corporation |
| L3Harris Technologies Inc. |
| Elbit Systems Ltd. |
| CACI International Inc. |
| Others |
Supply Flow & Price Mechanics
The Port of Long Beach container corridor shapes cost dynamics for thermal camera and drone payload manufacturers, concentrating supply chain leverage with Taiwanese and South Korean foundries while downstream price differentiation separates federal integrators from municipal procurement tiers.
Pricing Analysis
Service contract extensions and embedded upgrade cycles drive lifetime value capture across federal accounts. Subscription-based platform licensing dominates, with three-tier pricing structure across premium, standard, and economy levels separating cleared personnel programs from commercial off-the-shelf deployments. Certification grade under EU AI Act compliance and NERC CIP cybersecurity directives anchors premium tiers. Cost compression in municipal segments intensifies because grant-funded state agencies lack multi-year budget authority. Private sector critical infrastructure operators exhibit highest price sensitivity; classified military programs absorb premium pricing without elasticity.
Supply Chain Analysis
Advanced image processors and thermal sensors feed from concentrated upstream capacity in Taiwan, South Korea, and Japan. Gallium arsenide substrates, precision optics, and encrypted radio chipsets rest on single-source foundry relationships. Tariff exposure on geospatial software and AI training data under US Bureau of Industry and Security restrictions creates procurement friction for foreign contracts. Distribution runs through prime integrators holding cleared facility status, with component subsystems flowing via defense logistics channels or commercial IT distributors depending on end-use classification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where security clearance requirements and certified facility status create structural moats that delay competitive displacement.
For Market Incumbents: Harden algorithmic transparency investments to maintain European procurement eligibility under EU AI Act mandates. Deepen satellite-integrated communication backbone deployments to anchor NATO interoperability frameworks. Consolidate subcontractor networks in Bavaria and Baden-Württemberg industrial clusters to secure regional supply resilience against semiconductor concentration risk. For New Entrants and Emerging Players: Mobile-based early warning systems in Nigeria, Kenya, and South Africa represent the most penetrable entry point given fixed infrastructure gaps and bypassed legacy radio debt. Municipal cybersecurity subscriptions for water treatment facilities under EPA directives offer attachable wedge. Partner with Indian BIS-certified local manufacturers to satisfy import substitution requirements for smart city command-and-control platforms. For Investors and Strategic Acquirers: Specialized edge-AI processing firms with onboard satellite payload capabilities anchor acquisition interest given convergence of low-earth orbit constellations and real-time disaster assessment demand. Long-term viability hinges on recurring revenue transition completion. Monitor Defense Counterintelligence and Security Agency clearance processing velocity as inflection indicator for classified program deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act compliance unlocks German Federal Police and French CNIL-approved procurement channels previously restricted. |
| Satellite-Integrated Communication Backbone | NATO interoperability frameworks in Bavaria anchor Thales Group's encrypted network deployments across member states. |
| Mobile-First Platform Localization | BIS certification partnerships in Mumbai and Bangalore satisfy India's import requirements for electronic security equipment. |
| Cleared Personnel Pipeline Expansion | Defense Counterintelligence and Security Agency vetting capacity directly determines deployment velocity for classified programs. |
| Subscription Licensing Transition | Operational expenditure models with embedded upgrades concentrate buyer power with agencies possessing multi-year budget authority. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with fusion center operations directors, DHS grant program administrators, critical infrastructure CISOs, and NATO interoperability officers combined with EU AI Act implementation guidance, NERC CIP violation records, EPA cybersecurity directives, and BIS export control updates. Bottom-up vendor revenue aggregation and top-down federal budget appropriation analysis complete the triangulation.
Calibration against historical procurement velocity and policy implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include solution type, end-user classification, technology layer, application priority, and regional regulatory cluster. CAGRs derive from weighted scenario modeling across grant funding continuity, export control expansion, and clearance processing efficiency assumptions. Satellite constellation deployment schedules and smart city tender pipelines feed industry-specific inputs.
Practitioners should monitor congressional appropriation delays, EU AI Act enforcement variance across member states, and semiconductor foundry capacity allocation for early signals of forecast revision. Cross-checking against DHS grant obligation rates and NATO defense expenditure commitments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Automatic Floodgate Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Advanced Disaster Management Simulator Market
Emergency and Disaster Management
Emergency Shutdown System Market
Emergency and Disaster Management
Lifeboat Market
Emergency and Disaster Management
Emergency Lighting Market
Emergency and Disaster Management
Cyber Crisis Management Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
Emergency Location Transmitter Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Survival Tools Market