
 Middle-East and Africa Airport Passenger Screening Systems Market | 2026-2036
Middle-East and Africa Airport Passenger Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Airport Passenger Screening Systems Market Foresight
Airport security procurement channels across the Middle-East and Africa are reshaping as national aviation authorities consolidate vendor selection under centralized tender frameworks. Smiths Detection leverages its installed base of hold baggage screening systems to sustain recurring service contracts across Gulf hubs. L3Harris Technologies anchors its regional presence through long-term maintenance agreements with major flag carriers. Nuctech Company competes aggressively on total cost of ownership for new terminal builds in East Africa.
Airport passenger screening systems comprise integrated hardware and software platforms designed to detect prohibited items, explosives, and contraband on persons and in carry-on luggage, typically operating at throughput rates exceeding 400 passengers per hour per lane. These systems employ multi-energy X-ray transmission, automated threat recognition algorithms, and millimeter wave reflectometry to satisfy aviation security protocols without manual pat-downs. Computed tomography technology leads product investment as airports phase out legacy single-view X-ray scanners ahead of regulatory deadlines. Millimeter wave body scanners capture the fastest expansion trajectory across the technology dimension, driven by passenger throughput advantages and reduced false alarm rates. Fixed installation types dominate the current installed base, though modular configurations are gaining traction for terminal expansion projects where permanent construction timelines conflict with traffic growth.
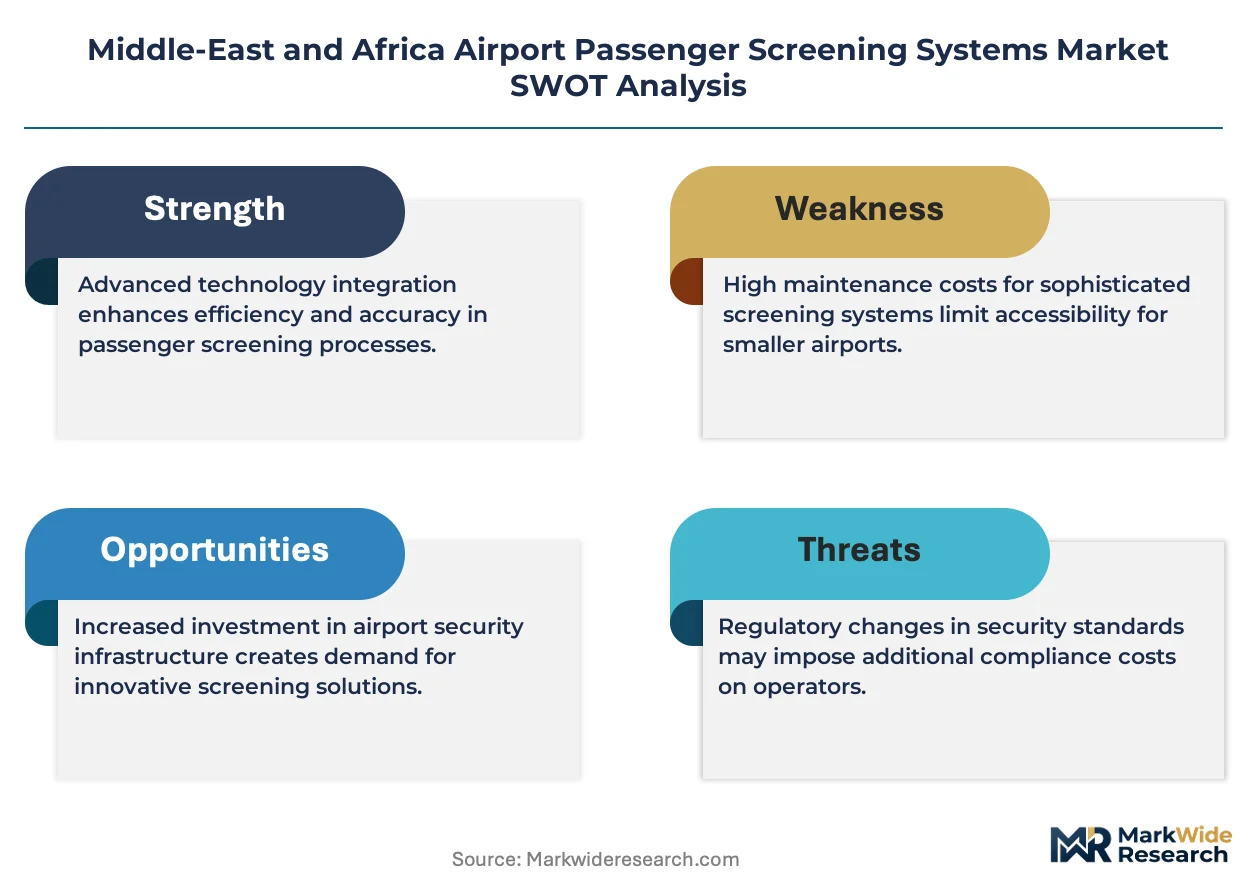
Saudi Arabia's General Authority of Civil Aviation, the UAE's General Civil Aviation Authority, and South Africa's Civil Aviation Authority each enforce screening standards that reference ICAO Annex 17 and EU aviation security regulations, creating harmonized but jurisdictionally distinct compliance obligations for equipment suppliers. The EU AI Act and associated CE marking requirements for automated threat detection algorithms are beginning to influence procurement specifications even outside European territory, as Gulf carriers operating EU routes adopt equivalent standards. Stakeholders must monitor how biometric integration mandates and evolving lithium battery detection protocols will redefine system architecture requirements across the region's major hub airports.
Market Dynamics
ICAO Standard 3 mandates for hold baggage screening are compressing replacement cycles across Gulf Cooperation Council airports, forcing capital deployment toward computed tomography systems before regulatory deadlines hit.
Growth Catalysts
- ICAO Annex 17 Compliance Deadlines:Gulf aviation authorities are mandating computed tomography upgrades for all hold baggage screening lanes, creating immediate equipment replacement demand across Saudi Arabia and the United Arab Emirates.
- Greenfield Terminal Construction:Saudi Arabia's airport expansion program is installing millimeter wave body scanners as primary screening infrastructure, bypassing legacy single-view X-ray configurations entirely.
- EU Route Harmonization Requirements:Gulf carriers operating European routes are voluntarily adopting EU AI Act standards for automated threat detection, expanding addressable market for CE-marked algorithm platforms.
Market Restraints
- Capital Intensity Barriers:Full computed tomography lane deployments require USD 2-4 million per installation, excluding civil works, which constrains procurement at secondary African airports.
- Technical Integration Complexity:Legacy single-view X-ray systems at OR Tambo International and Cape Town International lack the data architecture for seamless computed tomography retrofits, forcing complete lane rebuilds.
- Supply Concentration Risk:Critical millimeter wave sensor components originate from a concentrated East Asian supplier base, exposing procurement timelines to single-source dependency.
Strategic Opportunities
- East African Terminal Modernization:Ethiopia and Kenya are expanding hub airport capacity without legacy baggage screening infrastructure, enabling direct-to-CT procurement without retrofit constraints.
- Biometric-Converged Screening Lanes:Integration of facial recognition with millimeter wave body scanners is creating new system architecture demand at Dubai International and King Abdulaziz International.
- EU AI Act Certification Premium:Automated threat recognition algorithms with CE marking command pricing premiums from Gulf carriers seeking operational equivalence with European security standards.
Industry Challenges
- Algorithm Training Data Scarcity:Automated threat recognition systems require region-specific prohibited item libraries, and Middle-East and Africa aviation security agencies lack standardized contraband image databases.
- Certification Timeline Compression:Dual-track approvals from national civil aviation authorities and EU notified bodies for AI-enabled detection systems are extending vendor time-to-revenue by 12-18 months.
- Legacy System Interoperability:Existing security operations centers at major Gulf hubs operate on proprietary middleware that resists integration with modern computed tomography data outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Airport Passenger Screening Systems Market |
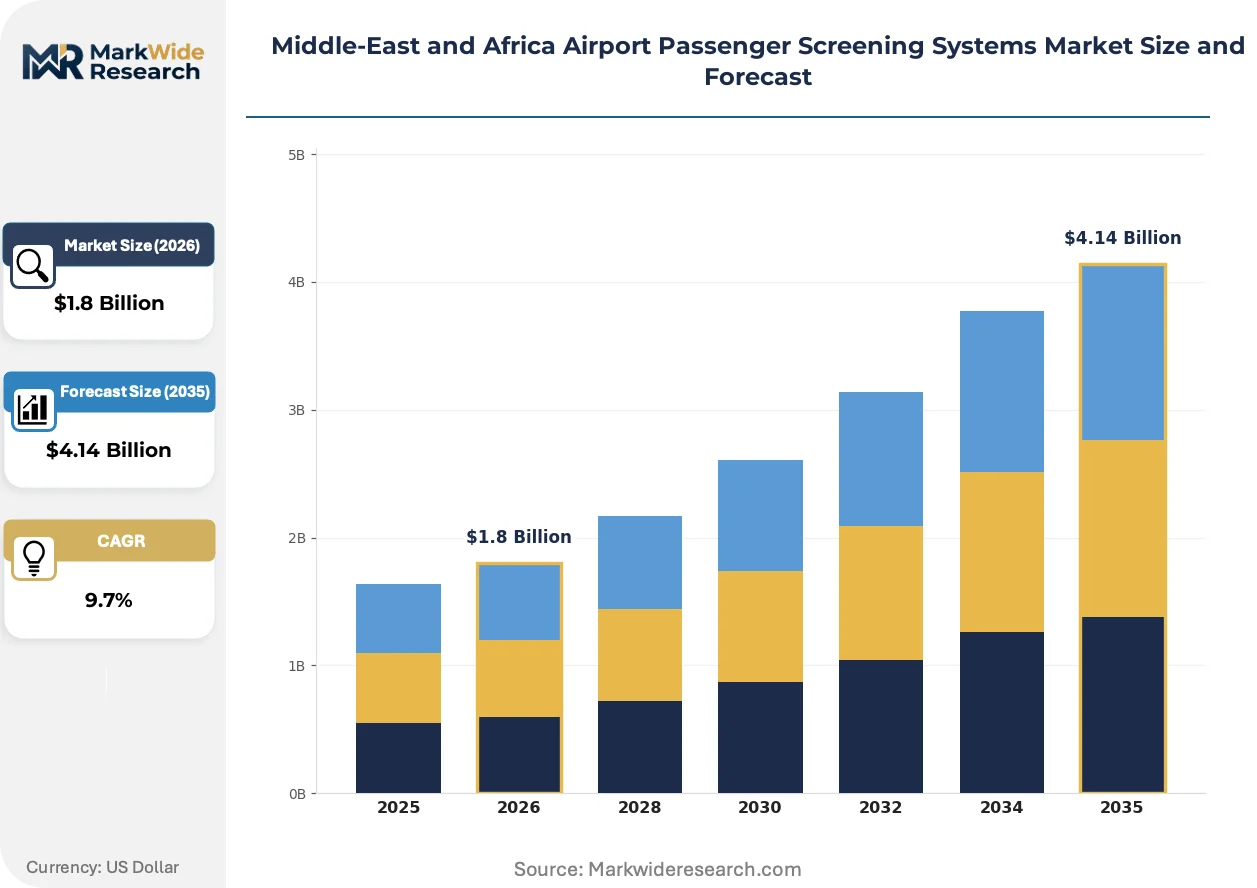
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Scanners, Body Scanners, Explosive Detectors, Liquid Scanners Technology: Computed Tomography, Millimeter Wave, Backscatter, Dual-View End User: Airports, Government Agencies, Airlines, Security Firms Installation Type: Fixed, Mobile, Modular, Permanent |
| Companies Covered | Rapiscan Systems, Vanderlande Industries, C.E.I.A. S.p.A., Garrett Electronics, Leidos, Smiths Detection, L3Harris Technologies, Nuctech Company, Analogic Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Airport Passenger Screening Systems Market Shifts & Advancements
Computed tomography baggage screening is digitizing threat detection workflows across Middle-East and Africa hub airports, compressing false alarm rates while accelerating passenger throughput. Three convergent developments are restructuring competitive positioning.
Deep learning algorithms embedded in computed tomography scanners are digitizing the resolution of organic-inorganic material discrimination, enabling automated detection of liquid explosives and concealed electronics without manual bag inspection. Saudi Arabia's General Authority of Civil Aviation is requiring these capabilities in all new terminal procurements. The technology is digitizing operator staffing models, reducing lane personnel requirements by half at greenfield installations.
The EU AI Act's risk classification framework for biometric identification systems is extending influence beyond European territory through operational harmonization pressures. Gulf carriers maintaining EU route authority are pre-emptively adopting CE marking standards for automated threat detection algorithms. This regulatory export is compressing competitive space for non-certified vendors across UAE and Saudi procurement channels.
Centralized tender frameworks are consolidating vendor selection authority under national aviation authorities, displacing airport-level procurement autonomy. South Africa's Airports Company has shifted all passenger screening system acquisitions to national-level competitive bidding. This concentration is visible across Gulf Cooperation Council states, where multi-airport framework agreements now dominate capital deployment patterns.
Middle-East and Africa Airport Passenger Screening Systems Market Segmentation
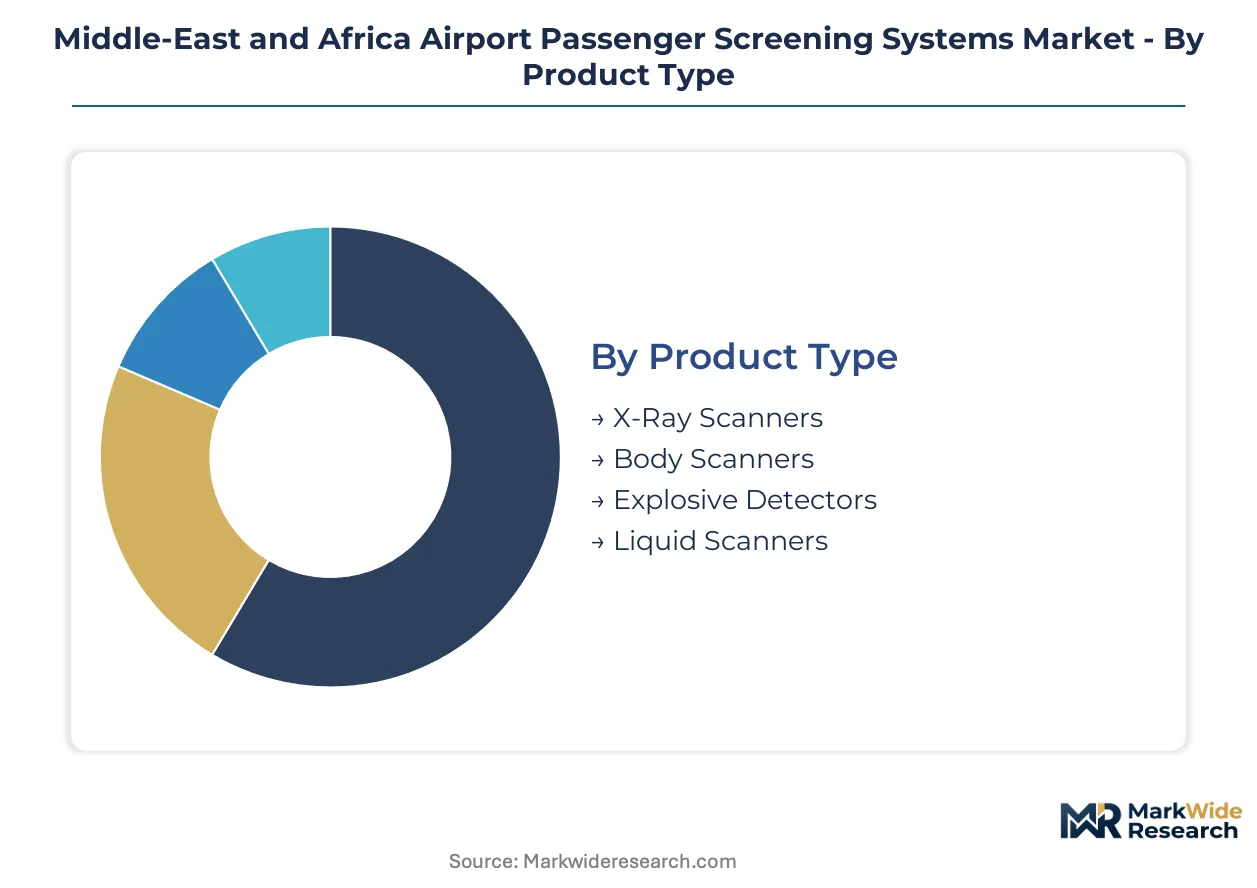
Segmentation of airport passenger screening systems reveals distinct procurement patterns across product types, technologies, and installation configurations. Each dimension carries specific service contract structures and replacement cycle dynamics that shape vendor engagement models across Middle-East and Africa aviation hubs.
Product Type:
After-sales service intensity varies sharply across product categories, with computed tomography baggage systems generating multi-year maintenance agreements and body scanners requiring frequent software algorithm updates.
- X-Ray Scanners:Single-view and dual-view transmission systems form the legacy installed base at secondary African airports. Procurement concentrates in Ethiopia and Kenya where greenfield terminals bypass older configurations entirely for computed tomography.
- Body Scanners:Millimeter wave reflectometry units deploy as primary passenger screening infrastructure at Saudi Arabia's new terminal builds. These systems demand continuous algorithm retraining for region-specific threat libraries, embedding vendors in long-term service relationships.
- Explosive Detectors:Trace detection portals for carry-on item verification.
- Liquid Scanners:Standalone bottle screening units for prohibited fluid identification.
By volume, X-Ray Scanners lead. By growth pace, Body Scanners is ahead.
Technology:
Technology selection directly determines capital deployment scale and civil works requirements, with computed tomography installations demanding structural lane modifications that mobile configurations avoid.
- Computed Tomography:Three-dimensional baggage reconstruction systems satisfy ICAO Standard 3 mandates across Gulf Cooperation Council states. Saudi Arabia's General Authority of Civil Aviation requires these capabilities in all new terminal procurements, forcing replacement cycles at Dubai International and King Abdulaziz International.
- Millimeter Wave:Non-ionizing passenger screening systems capture expansion at UAE greenfield terminals. Deployment accelerates where passenger throughput advantages justify premium procurement costs against backscatter alternatives.
- Backscatter:Low-radiation body imaging technology with slower passenger processing rates.
- Dual-View:Two-angle X-ray transmission for enhanced bag inspection without full tomography.
Computed Tomography dominates current procurement value. Millimeter Wave systems are climbing the fastest.
End User:
End user type structures procurement authority concentration, with national aviation authorities displacing airport-level purchasing autonomy across major Gulf hubs.
- Airports:Terminal operators at OR Tambo International and Cape Town International drive lane modernization programs. South Africa's Airports Company consolidated all screening system acquisitions under national-level competitive bidding, compressing vendor negotiation cycles.
- Government Agencies:Civil aviation authorities in Saudi Arabia and the UAE enforce harmonized standards referencing ICAO Annex 17. These regulators now control multi-airport framework agreements that dominate capital deployment patterns.
- Airlines:Flag carriers procuring passenger screening for private terminals and premium lounges.
- Security Firms:Third-party contractors operating outsourced screening lanes under aviation authority supervision.
Airports account for the largest installed base. Government Agencies are gaining share fastest through centralized tender frameworks.
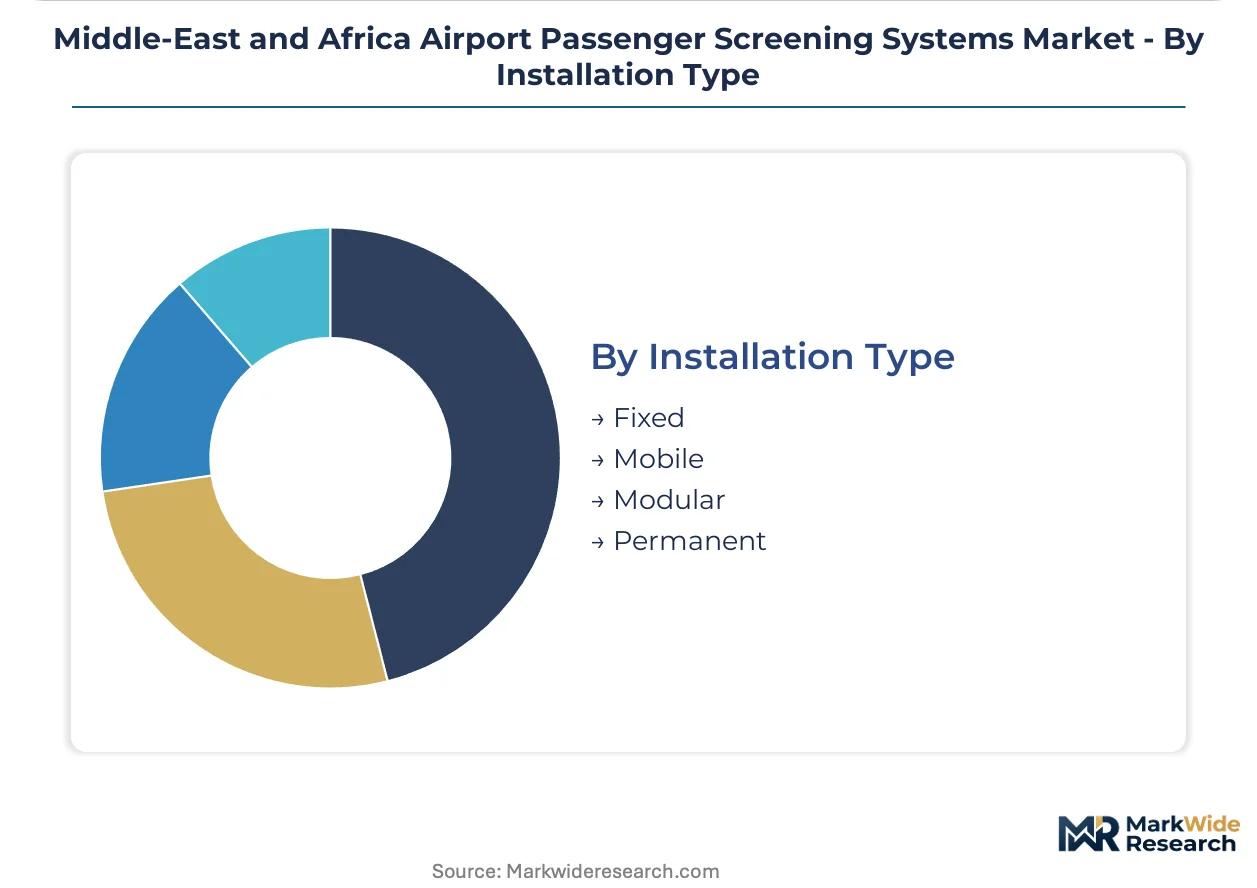
Installation Type:
Installation configuration determines procurement flexibility for terminal expansion projects where permanent construction timelines conflict with traffic growth.
- Fixed:Permanent lane infrastructure dominates current installed base across established Gulf hubs. These installations lock in vendor relationships through proprietary middleware integration that resists replacement.
- Mobile:Deployable screening units serve temporary capacity surges and construction-phase operations. Demand concentrates at East African hubs expanding hub capacity without legacy infrastructure constraints.
- Modular:Reconfigurable lane components gaining traction for phased terminal expansions.
- Permanent:Civil works-integrated installations with 15-20 year depreciation schedules.
Fixed installations lead by volume. Modular configurations are expanding most quickly for flexibility-constrained expansion projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA enforcement of ICAO Standard 3 mandates is compressing equipment replacement timelines across Saudi Arabia's aviation network. National regulators across the Middle-East and Africa are consolidating procurement authority under centralized tender frameworks.
Saudi Arabia
Greenfield terminal construction at King Abdulaziz International and NEOM Bay Airport is deploying millimeter wave body scanners as primary screening infrastructure. The General Authority of Civil Aviation requires computed tomography capabilities in all new procurements. Riyadh's aviation cluster anchors regional demand for integrated screening lanes.
United Arab Emirates
Dubai International and Abu Dhabi International are modernizing hold baggage screening lanes ahead of regulatory deadlines. MOHAP coordinates multi-airport framework agreements that dominate capital deployment patterns. The Dubai South logistics corridor concentrates service contract demand for CT system maintenance.
South Africa
OR Tambo International and Cape Town International are executing lane modernization programs under Airports Company South Africa direction. The Civil Aviation Authority enforces standards referencing ICAO Annex 17 and EU aviation security regulations. Gauteng province hosts the continent's most concentrated installed base of legacy screening systems requiring replacement.
Ethiopia
Addis Ababa Bole International is expanding hub capacity without legacy baggage screening infrastructure constraints. The country's national aviation regulator mandates compliance with ICAO Annex 17 for all international terminal operations. The Addis Ababa industrial corridor enables direct-to-CT procurement for new terminal builds.
Kenya
Jomo Kenyatta International Airport is expanding passenger throughput capacity with modular screening lane configurations. The Kenya Civil Aviation Authority references EU security standards for equipment certification. Nairobi's aviation services cluster is attracting regional maintenance contracts for CT and millimeter wave systems.
Middle-East and Africa Airport Passenger Screening Systems Market Competitive Landscape
Integrated-system specialists and component-focused suppliers split the market across procurement channels. Gulf aviation authorities favor vendors with established service networks for multi-year maintenance agreements. Three archetypes dominate: legacy security conglomerates with installed base advantages, regional specialists competing on total cost of ownership, and algorithm-software platforms seeking CE marking certification. Competitive moves center on framework agreement positioning and biometric-converged lane partnerships.
Among the legacy security conglomerates, Smiths Detection and L3Harris Technologies occupy positions anchored by recurring service contracts across Gulf hub airports. Nuctech Company exemplifies the regional specialist archetype competing on procurement economics for East African greenfield terminals. These three entities represent the dominant competitive anchors within a procurement environment increasingly shaped by centralized tender authority and regulatory harmonization pressures.
| Leading Market Players |
|---|
| Rapiscan Systems |
| Vanderlande Industries |
| C.E.I.A. S.p.A. |
| Garrett Electronics |
| Leidos |
| Smiths Detection |
| L3Harris Technologies |
| Nuctech Company |
| Analogic Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian millimeter wave sensor suppliers compresses both pricing tier spreads and supply chain resilience across Middle-East and Africa procurement channels. Gulf aviation authorities face extended lead times and premium pricing for configured-to-order CT systems while secondary African airports absorb standard-configuration cost premiums driven by logistics fragmentation.
Pricing Analysis
The customization-premium spread separates configured-to-order CT lane deployments from standard millimeter wave body scanner configurations. Project-based pricing dominates, with ICAO Standard 3 compliance mandates and EU AI Act certification tiers driving price differentiation between CE-marked algorithm platforms and non-certified alternatives. Pricing pressure stems from centralized tender frameworks consolidating buyer power under Saudi Arabia's General Authority of Civil Aviation and South Africa's Airports Company. Government agencies exhibit lowest price sensitivity due to regulatory deadline imperatives, while security firms operating outsourced lanes face acute cost compression.
Supply Chain Analysis
Upstream feedstock for millimeter wave arrays and X-ray detector components draws from concentrated manufacturing bases in China, Japan, and South Korea. Critical inputs include gallium arsenide semiconductors, scintillator crystals, and precision-machined waveguide assemblies. Single-source vulnerability pervades millimeter wave sensor procurement, exposing Gulf hub deployments to geopolitical logistics chokepoints. Distribution runs through national aviation authority tender frameworks that displace direct airport-level procurement, embedding vendor relationships through multi-year service agreements rather than spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICAO Standard 3 compliance deadlines and EU AI Act certification requirements are compressing vendor selection cycles across Middle-East and Africa aviation security procurement. This regulatory inflection creates asymmetric opportunity for algorithm-certified platform specialists against legacy hardware incumbents.
For Market Incumbents: Build switching-cost moats through proprietary middleware integration at Dubai International and King Abdulaziz International that resists CT system replacement. Deepen service contract density to capture recurring revenue from algorithm update mandates. Counter Nuctech Company's total-cost-of-ownership challenge by anchoring multi-airport framework agreements with Saudi Arabia's General Authority of Civil Aviation.
For New Entrants and Emerging Players: Pursue biometric-converged lane architecture partnerships at greenfield terminals in Ethiopia and Kenya where legacy infrastructure constraints are absent. Target modular installation configurations for phased terminal expansions at Jomo Kenyatta International Airport. Lead with EU AI Act pre-certification to capture premium positioning in Gulf carrier procurement channels.
For Investors and Strategic Acquirers: The market sits at a regulatory-upgrade phase that favors algorithm-software platforms with CE marking pathways over pure-hardware vendors. Long-term viability hinges on automated threat recognition capability rather than scanner hardware manufacturing. Watch for biometric integration mandates at Dubai International and King Abdulaziz International as signal for next-generation system architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | CE marking unlocks premium procurement channels with Gulf carriers operating European routes. |
| Biometric-Converged Lane Development | Facial recognition integration with millimeter wave systems captures Dubai International modernization demand. |
| East African Greenfield Terminal Partnership | Direct-to-CT procurement at Addis Ababa Bole International bypasses retrofit competition. |
| Multi-Airport Framework Agreement Positioning | Saudi Arabia's General Authority of Civil Aviation consolidation favors vendors with national service networks. |
| Algorithm Training Data Consortium | Region-specific threat libraries address ICAO Standard 3 compliance gaps across Middle-East aviation authorities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs import records, and aviation authority procurement databases. Primary interviews engaged airport security directors, civil aviation authority procurement officers, CT system maintenance engineers, and airline security compliance managers. Secondary validation drew from ICAO Annex 17 implementation reports, EU AI Act technical documentation, SEC filings of listed security equipment vendors, and national tender announcement repositories. Bottom-up lane deployment tracking triangulates against top-down market sizing from aviation passenger throughput projections.
Forecast inputs span technology substitution curves for CT versus legacy X-ray, regulatory deadline phasing across Gulf Cooperation Council states, greenfield terminal construction pipelines, and biometric integration adoption rates. Segmentation dimensions modeled include product type, technology tier, installation configuration, and end-user procurement authority concentration. CAGRs derive from equipment replacement cycle compression analysis and capital deployment patterns under centralized tender frameworks. ICAO Standard 3 compliance timelines and EU route harmonization requirements anchor demand elasticity assumptions.
Sensitivities concentrate around algorithm certification timeline delays, millimeter wave component supply disruptions, and biometric integration mandate timing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and aviation traffic recovery trajectories. Cross-checking against ICAO implementation progress reports and national civil aviation authority capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
South Korea Access Control Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Access Control Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
North America Keyless Vehicle Access Control System Market