
 China Access Control Market | 2026-2036
China Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
China Access Control Market Insights
Silicon-based facial recognition modules are rebalancing hardware cost structures as CMOS image sensors displace legacy CCD arrays in mid-tier readers. Hangzhou Hikvision Digital Technology Co., Ltd. leverages captive semiconductor sourcing to protect margin pools on biometric terminals. Zhejiang Dahua Technology Co., Ltd. anchors its position through deep vertical integration into SoC design for edge-computing access nodes. ASSA ABLOY AB Group competes on mechanical-electronic hybrid architectures that satisfy dual-redundancy requirements in financial institutions.
China access control systems comprise credential verification hardware, lock mechanisms, and management software governing physical entry points across facilities, with typical biometric readers operating at false acceptance rates below 0.001% and response latencies under one second for real-time authentication. Biometric technology leads solution deployment in high-security government complexes where fingerprint and facial recognition have matured beyond pilot phases. Cloud-based solutions represent the fastest-expanding architecture as state-owned enterprises migrate from legacy on-premises servers to hybrid deployments that centralize multi-site credential management.
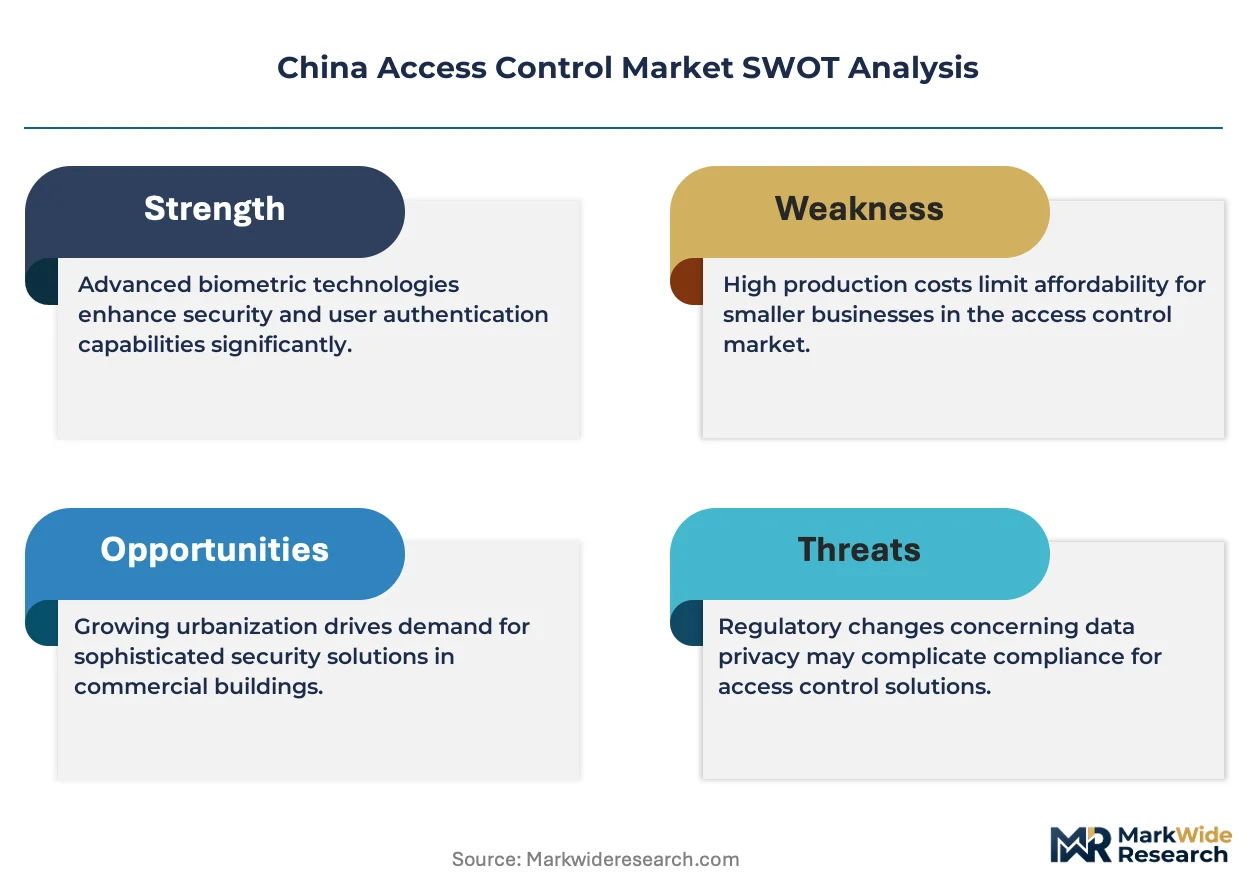
MIIT cybersecurity classifications and GB/T 35678 national standards for biometric data protection shape product development timelines and certification costs for domestic manufacturers. NMPA-equivalent oversight of healthcare facility access and SAMR consumer-data governance extend compliance burdens across commercial and institutional segments. Stakeholders must weigh the trade-off between algorithm localization mandates and interoperability with multinational enterprise security stacks as procurement rules tighten.
Market Dynamics
GB/T biometric certification mandates are compressing product development cycles as domestic manufacturers reengineer hardware architectures to satisfy MIIT cybersecurity classifications before commercial deployment.
Growth Catalysts
- Smart city infrastructure mandates:Hangzhou and Shenzhen municipal governments are embedding facial recognition terminals into new government facility construction, creating anchored demand for multi-factor authentication systems.
- MIIT cybersecurity classifications:Tiered compliance requirements are filtering out low-specification imports and accelerating domestic vendor qualification for state-owned enterprise procurement.
- Silicon CMOS sensor migration:Cost curves for biometric-grade image sensors are enabling mid-tier enterprise campuses to upgrade from card-based to facial recognition entry systems.
Market Restraints
- SoC supply concentration:Edge-computing access node processors rely on concentrated Taiwan and South Korea foundry capacity, exposing lead time volatility for domestic terminal manufacturers.
- GB/T 35678 compliance costs:Biometric data protection certification requires third-party laboratory testing cycles that extend product launch timelines by 8-14 months for new market entrants.
- Mechanical lock substitution:Low-security commercial premises in inland provinces continue specifying electromagnetic strikes over biometric readers due to installed base familiarity and maintenance simplicity.
Strategic Opportunities
- Central and western province penetration:Chengdu and Xi'an enterprise zones exhibit sub-15% biometric adoption rates against coastal benchmarks, presenting first-mover expansion terrain for certified vendors.
- Healthcare facility vertical:NMPA-equivalent oversight of hospital access control is mandating contactless authentication for infection control, opening specialized product lines for surgical suite and pharmaceutical storage applications.
- Cloud-hybrid architecture convergence:State-owned enterprises are consolidating multi-site credential management onto hybrid platforms that blend edge authentication with centralized policy administration.
Industry Challenges
- Algorithm localization mandates:Domestic data residency requirements are forcing multinational security stack vendors to rearchitect cloud backends, complicating interoperability with existing enterprise IT infrastructure.
- Field engineering skill scarcity:Biometric terminal deployment requires certified technicians capable of integrating facial recognition modules with legacy building management systems, a capability pool concentrated in eastern coastal cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Access Control Market |
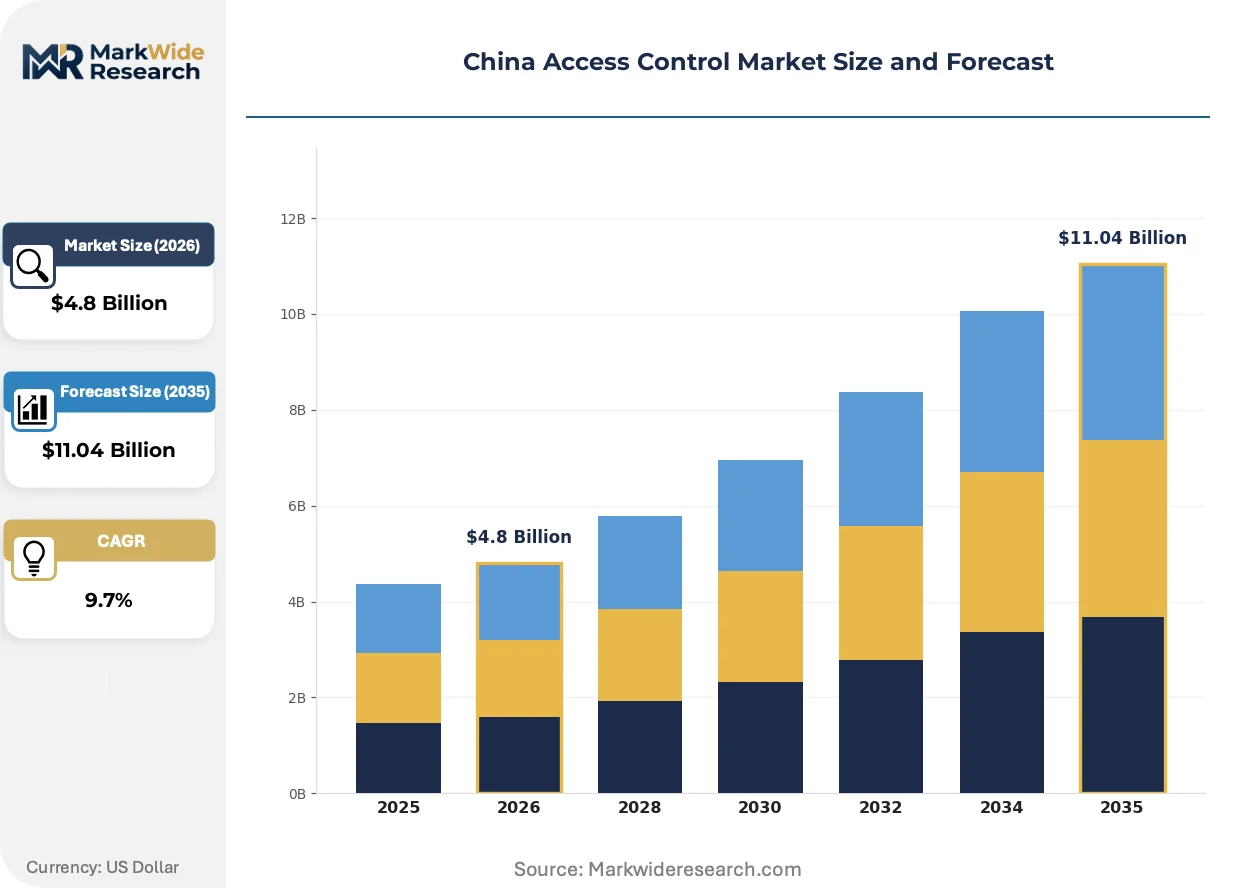
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, RFID, Keypad, Smart Card Application: Commercial, Government, Residential, Industrial End User: Enterprises, Healthcare Facilities, Educational Institutions, Retail Businesses Solution: Cloud-Based, On-Premises, Hybrid, Integrated Systems |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Honeywell International Inc., ASSA ABLOY AB Group, Johnson Controls International plc, Bosch Security Systems Inc., Thales Group, Idemia Group, Kaadas Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Access Control Market Trends and Innovations
Edge-computing architectures are redistributing processing load from centralized servers to door-mounted nodes, altering hardware specifications and service delivery models across installation and maintenance channels.
Multispectral imaging sensors are integrating liveness detection capabilities directly into biometric reader hardware. High-security government complexes in Beijing and Shanghai are specifying these modules for anti-spoofing protection. The technology is integrating anti-tamper safeguards that reduce reliance on separate server-side verification, compressing authentication latency below 500 milliseconds.
GB/T national standards for biometric data protection are mandating encrypted template storage and transmission protocols. Domestic manufacturers are redesigning firmware architectures to satisfy SAMR consumer-data governance requirements. Financial institutions in Shenzhen and Guangzhou are prioritizing certified terminals in procurement specifications, filtering non-compliant imports from vendor shortlists.
Enterprise buyers are unbundling hardware procurement from software licensing and maintenance contracts. State-owned enterprises in Jiangsu and Zhejiang are negotiating separate SaaS agreements for credential management platforms. This pattern is visible most acutely in campus-style headquarters where multi-building deployments create volume leverage for disaggregated purchasing.
China Access Control Market Segmentation
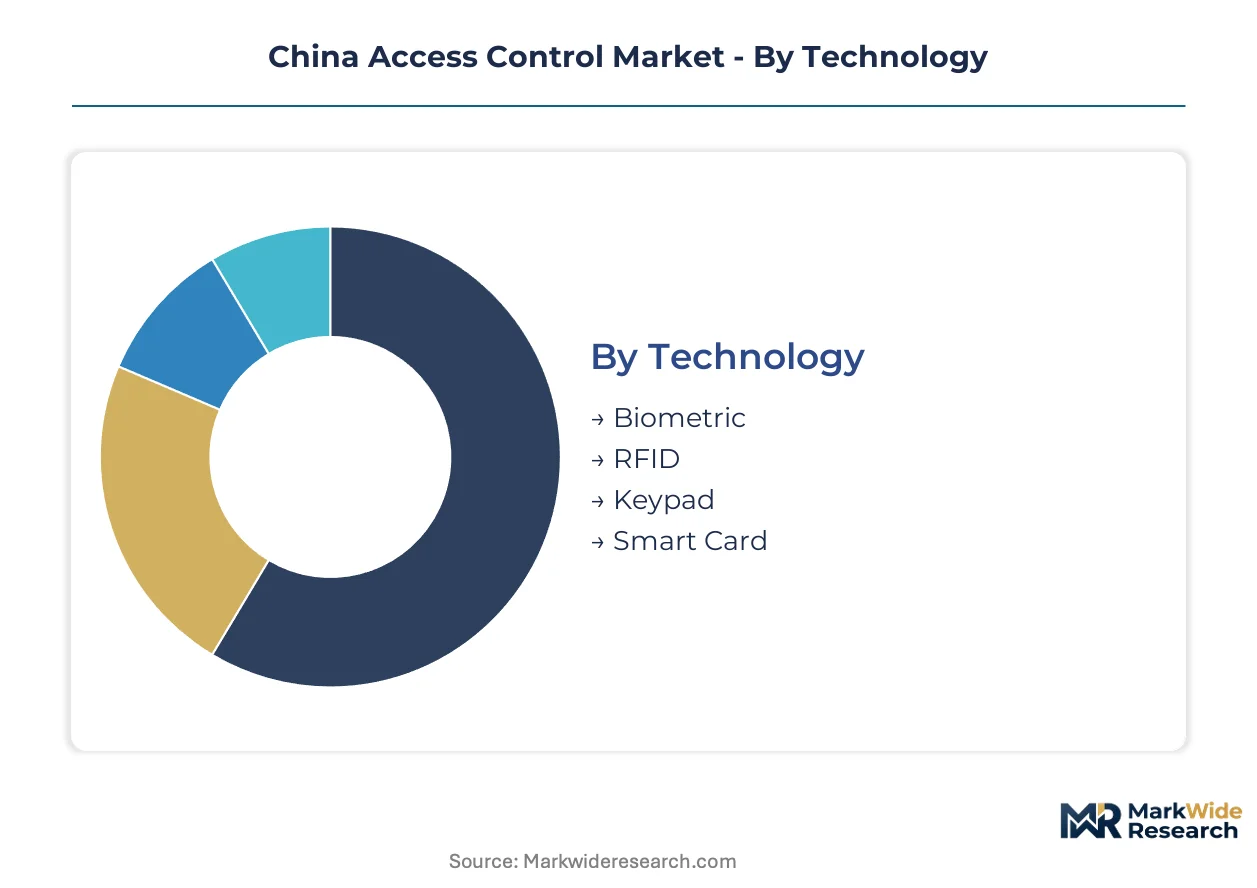
Segmentation in the China access control market reveals how procurement patterns split between embedded system architectures and standalone deployments. Understanding these divides exposes where MIIT certification burdens fall heaviest and which integration pathways state-owned enterprises favor.
Technology:
Biometric and RFID modules anchor embedded installations in new construction, while keypad and smart card systems persist as standalone retrofits in legacy facilities.
- Biometric:Facial recognition and fingerprint modules incorporate CMOS image sensors with liveness detection. Hangzhou and Shenzhen government facilities specify these for new smart city infrastructure under MIIT cybersecurity classifications.
- RFID:Proximity and contactless credential readers operate at 13.56 MHz with encrypted transaction protocols. Eastern coastal enterprise campuses deploy these for high-throughput employee entry where authentication speed dominates security tiering.
- Keypad:PIN-entry systems with tamper-resistant enclosures serve low-security commercial premises in inland provinces where installed base familiarity reduces maintenance training costs.
- Smart Card:Contact and contactless credential readers integrate with legacy building management systems through Wiegand or OSDP protocols.
Volume placements concentrate in RFID; the faster expansion belongs to Biometric.
Application:
Cost tiering separates premium-specification government complexes from price-sensitive residential installations, with commercial and industrial occupying mid-tier procurement bands.
- Commercial:Office towers and retail complexes specify multi-factor authentication with centralized credential management. Shanghai and Beijing financial districts prioritize GB/T 35678-compliant terminals for data protection audit trails.
- Government:Municipal facilities and state-owned enterprise headquarters mandate biometric readers with encrypted template storage under MIIT tiered compliance. Procurement specifications filter non-certified imports from vendor shortlists.
- Residential:Apartment complexes and gated communities deploy intercom-integrated access with mobile credential capability. Cost pressures favor electromagnetic strikes over biometric readers in sub-15% adoption western provinces.
- Industrial:Manufacturing plants and logistics hubs specify ruggedized readers with environmental sealing against dust and moisture ingress.
Commercial applications absorb the highest unit volumes; government verticals are climbing the fastest on smart city infrastructure mandates.
End User:
Customer type determines whether deployments emphasize centralized IT integration or decentralized facility management autonomy.
- Enterprises:Campus-style headquarters across Jiangsu and Zhejiang negotiate disaggregated hardware and SaaS procurement for multi-building credential administration.
- Healthcare Facilities:Hospitals under NMPA-equivalent oversight mandate contactless authentication for infection control in surgical suites and pharmaceutical storage zones.
- Educational Institutions:University dormitories and research facilities balance open campus access with restricted laboratory security tiering.
- Retail Businesses:Chain stores prioritize low-maintenance electromagnetic locks with audit logging for loss prevention compliance.
Enterprise deployments dominate absolute unit placements; healthcare facilities are gaining share fastest on post-pandemic infection control mandates.
Solution:
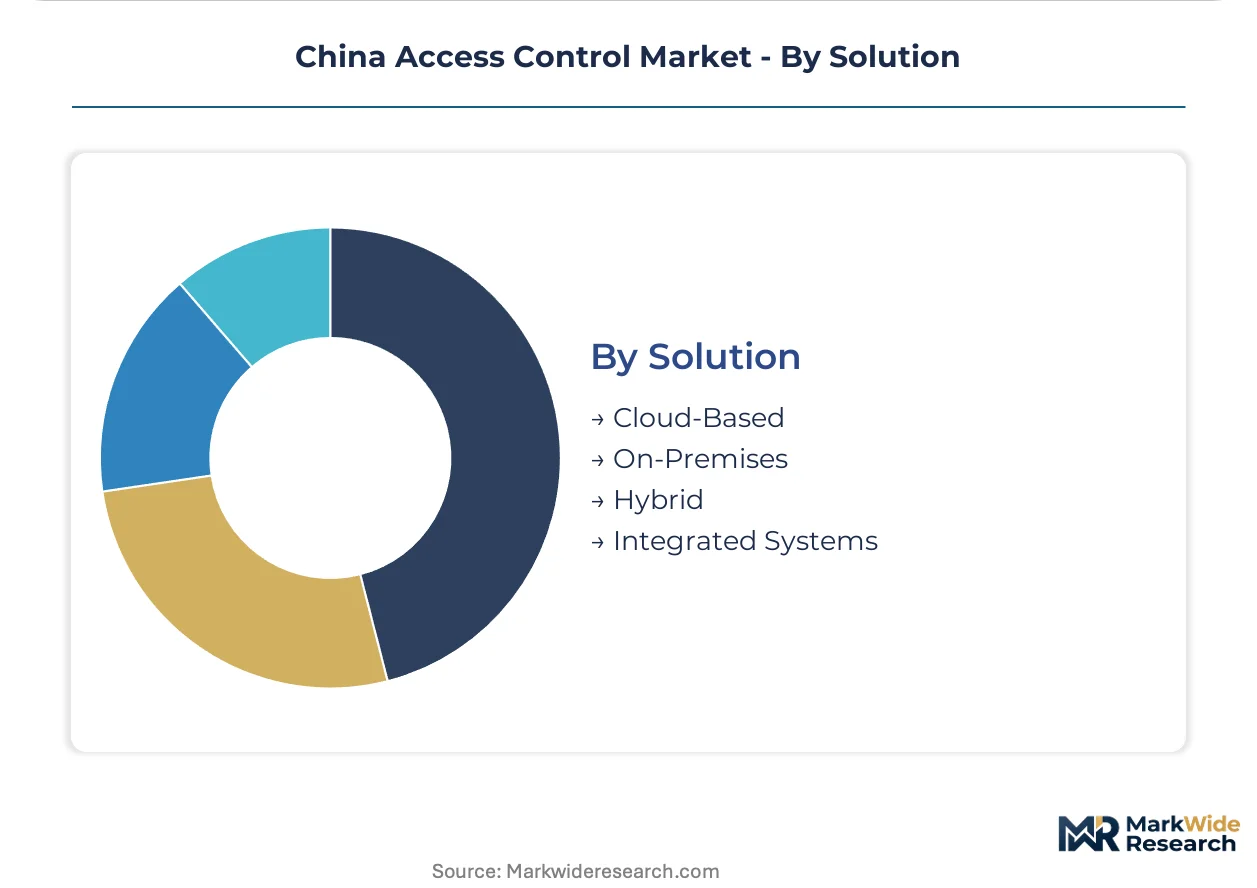
Architecture maturity separates proven on-premises deployments from emerging cloud-hybrid configurations that redistribute processing between edge nodes and centralized policy engines.
- Cloud-Based:Fully hosted credential management eliminates on-site server maintenance. State-owned enterprises migrate cautiously due to data residency requirements under SAMR governance.
- On-Premises:Local server installations with air-gapped operation satisfy highest-tier MIIT cybersecurity classifications for classified government facilities.
- Hybrid:Edge authentication with centralized policy administration dominates new procurement in multi-site state-owned enterprises consolidating fragmented legacy systems.
- Integrated Systems:Biometric readers fused with video surveillance and building management platforms reduce vendor count for greenfield smart city construction.
On-premises solutions retain the largest installed base; hybrid architectures are expanding most quickly as SOEs rationalize multi-site infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's access control demand clusters in eastern coastal provinces where smart city infrastructure spending concentrates. Provincial governments in Zhejiang, Guangdong, and Jiangsu account for the majority of biometric terminal procurement volumes. Western and central provinces remain underpenetrated, creating divergent competitive dynamics across domestic sub-markets.
Guangdong Province
Shenzhen municipal facilities and Pearl River Delta enterprise campuses drive multi-factor authentication system deployment. MIIT cybersecurity classifications filter vendor qualification for state-owned enterprise procurement in this manufacturing hub. Shenzhen and Guangzhou financial districts prioritize GB/T 35678-compliant terminals for data protection audit trails.
Zhejiang Province
Hangzhou smart city infrastructure mandates embed facial recognition terminals into new government facility construction. Campus-style headquarters across Jiangsu and Zhejiang negotiate disaggregated hardware and SaaS procurement for multi-building credential administration. Hangzhou Hikvision Digital Technology Co., Ltd. leverages captive semiconductor sourcing to protect margin pools on biometric terminals manufactured in this cluster.
Jiangsu Province
Nanjing and Suzhou enterprise zones exhibit high RFID reader penetration in high-throughput employee entry applications. State-owned enterprises migrate from legacy on-premises servers to hybrid cloud deployments that centralize multi-site credential management. Eastern coastal enterprise campuses in this province deploy proximity and contactless credential readers where authentication speed dominates security tiering.
Sichuan-Chongqing Region
Chengdu enterprise zones exhibit sub-15% biometric adoption rates against coastal benchmarks, presenting first-mover expansion terrain for certified vendors. Low-security commercial premises in this inland region continue specifying electromagnetic strikes over biometric readers due to installed base familiarity. Field engineering skill scarcity concentrates capability gaps in western provinces where certified technicians capable of integrating facial recognition modules remain limited.
Beijing-Tianjin-Hebei Corridor
High-security government complexes in Beijing specify multispectral imaging sensors with integrated liveness detection for anti-spoofing protection. GB/T national standards for biometric data protection mandate encrypted template storage and transmission protocols that domestic manufacturers redesign firmware architectures to satisfy. Financial institutions in this northern cluster prioritize certified terminals in procurement specifications, filtering non-compliant imports from vendor shortlists.
China Access Control Market Competitive Landscape
Vertical integration into semiconductor and SoC design dominates the current landscape as domestic manufacturers seek supply chain control. The vendor base splits between consolidated domestic technology conglomerates with captive component sourcing and multinational security specialists competing on mechanical-electronic hybrid architectures. Three archetypes occupy distinct positions: vertically integrated domestic platform vendors, multinational mechanical-electronic hybrid specialists, and regional component assemblers serving price-sensitive segments. M&A activity and strategic partnerships represent the dominant competitive moves as players address algorithm localization mandates and cloud-hybrid architecture requirements.
Among domestic technology conglomerates, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. represent the vertically integrated archetype with upstream control over semiconductor supply chains. ASSA ABLOY AB Group occupies a position within the multinational specialist tier competing on mechanical-electronic hybrid architectures. These named entities exemplify how competitive positioning diverges between domestic platform vendors leveraging captive sourcing and international players emphasizing dual-redundancy specifications for financial institution procurement.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Honeywell International Inc. |
| ASSA ABLOY AB Group |
| Johnson Controls International plc |
| Bosch Security Systems Inc. |
| Thales Group |
| Idemia Group |
| Kaadas Group |
| Others |
Pricing and Supply Chain Analysis
State-backed technology conglomerates with captive semiconductor sourcing anchor supply-side discipline, translating upstream component control into pricing power across biometric terminal tiers while compressing margin pools for import-dependent assemblers.
Pricing Analysis
High-volume RFID deployments absorb unit placement leadership while biometric modules command margin premiums. Three-tier pricing structure across MIIT-certified, standard-compliance, and non-certified equipment levels separates government procurement from commercial retrofit budgets. Cost compression in mid-tier enterprise segments is intensifying because CMOS sensor commoditization erodes hardware differentiation. Residential buyers in western provinces exhibit highest price sensitivity; financial institutions in Shenzhen and Guangzhou demonstrate lowest sensitivity due to audit-trail compliance mandates.
Supply Chain Analysis
GB/T 35678 certification gates access to state-owned enterprise procurement channels, filtering non-compliant imports from vendor shortlists. Taiwan and South Korea foundry capacity for edge-computing SoCs draws from concentrated semiconductor manufacturing clusters; domestic CMOS image sensor production hinges on Zhejiang and Guangdong assembly bases. Single-source vulnerability in advanced node fabrication exposes lead time volatility for biometric terminal manufacturers. Distribution runs through systems integrators with MIIT-certified field engineering capabilities concentrated in eastern coastal cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's access control sector sits in a hardware-transition phase as facial recognition modules displace legacy card-based credentials across municipal and enterprise installations.
For Market Incumbents: Lock in component supply through backward integration into CMOS sensor sourcing or long-term foundry offtake agreements. Deepen firmware certification investment to satisfy tightening GB/T biometric data protection mandates before product launch windows compress further. Electromagnetic lock substitution in inland provinces threatens volume growth; counter with bundled SaaS credential management to elevate switching costs. For New Entrants and Emerging Players: Capture white-space opportunity in Chengdu and Xi'an enterprise zones where biometric adoption lags coastal benchmarks by substantial margins. Prioritize healthcare facility verticals under NMPA-equivalent oversight where contactless authentication mandates create specialized product gaps. Lead with cloud-hybrid architecture proposals that appeal to state-owned enterprises consolidating fragmented multi-site legacy systems. For Investors and Strategic Acquirers: MIIT cybersecurity classification announcements for new equipment categories are the leading indicator that vendor qualification windows are narrowing and consolidation pressure is accelerating. Position for five-to-ten year horizon viability by targeting component-assemblers with latent certification capabilities and eastern coastal field engineering networks. Watch for SAMR consumer-data governance enforcement actions as the inflection signal for compliance-cost escalation that favors scaled domestic platforms over multinational entrants.| Strategic Initiative | Industry Significance |
|---|---|
| SoC Design Capability Acquisition | Upstream control over edge-computing processors insulates margin pools from Taiwan foundry volatility. |
| GB/T 35678 Certification Fast-Track | Accelerated laboratory testing cycles compress product launch timelines against import competitors. |
| Cloud-Hybrid Platform Launch | Centralized credential management appeals to Jiangsu and Zhejiang state-owned enterprise consolidation mandates. |
| Western Province Field Engineering Buildout | Chengdu and Xi'an technician certification addresses capability scarcity blocking biometric penetration. |
| Healthcare Vertical Product Line Extension | NMPA-equivalent contactless mandates open surgical suite and pharmaceutical storage applications. |
Research Methodology
Regulatory filing databases, customs trade records, and MIIT certification registries formed the secondary backbone, cross-referenced with primary interviews involving access control systems integrators, municipal procurement officers, semiconductor supply planners, and enterprise facility managers. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending allocations across provincial smart city budgets.
Bottom-up modeling tracked deployment volumes by technology tier and application vertical, while top-down analysis validated aggregate market scale against government IT procurement disclosures. Segmentation dimensions spanned biometric modality, solution architecture, end-user category, and provincial regulatory cluster. CAGRs were derived from infrastructure pipeline analysis and vendor shipment trajectory patterns, with MIIT cybersecurity classification timelines and CMOS sensor cost curves as primary forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation shifts and algorithm localization mandate enforcement intensity. Projections reflect assumptions regarding GB/T standard adoption pacing and state-owned enterprise cloud migration willingness. A model refresh is warranted upon material change in MIIT tiered compliance implementation schedules or semiconductor export control regime adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
France Access Control Market
Access Control Systems
North America Safety Connection Devices Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Europe Smart Lock Market