
 Building Access Control Security Market | 2026-2036
Building Access Control Security Market Size, Share, and Industry Trends Forecast 2026-2036
Building Access Control Security Market Outlook
Enterprise facility managers is rotating toward cloud-native access platforms as legacy on-premises systems face obsolescence. Honeywell leverages its building automation integration to bundle climate, fire, and access control into unified dashboards. Bosch anchors European commercial real estate with hardened biometric readers certified to Common Criteria standards. Genetec specializes in video-integrated access software that unifies physical and logical security layers for critical infrastructure operators.
Building access control security encompasses electromechanical and electronic systems that authenticate identities and authorize entry through credentials, biometric templates, or cryptographic tokens, typically operating across 125 kHz proximity to 13.56 MHz smart card frequencies and BLE/NFC mobile channels. These systems enforce perimeter integrity, audit trail compliance, and time-based access rights across commercial, industrial, and institutional environments. Biometric systems command premium positioning due to liveness detection advances and elimination of credential sharing, while cloud-based solutions capture fastest expansion as multi-tenant architectures reduce capital intensity for mid-market buyers. RFID solutions sustain substantial volume through retrofit compatibility with existing Wiegand and OSDP infrastructures across aging commercial building stock.
FCC certification governs wireless access device emissions in the United States, while the EU AI Act imposes risk-classification obligations on biometric identification systems deployed across European member states. The NFC Forum and Bluetooth SIG shape interoperability mandates that determine hardware procurement compatibility across integrated building ecosystems. Buyers must weigh vendor cloud sovereignty commitments against emerging data residency requirements from national cybersecurity agencies.
Market Dynamics
Cloud-native access platforms are decomposing the installed base of on-premises controllers as facility managers prioritize subscription-based operational expenditure models over capital-intensive hardware refresh cycles.
Growth Catalysts
- EU AI Act risk-classification mandates:Biometric identification systems deployed across European commercial real estate now face mandatory conformity assessments, accelerating replacement of legacy proximity readers with certified liveness-detection hardware.
- Post-pandemic occupancy analytics:Corporate headquarters and flex-office operators in the United States demand integrated access-video platforms that correlate entry events with space utilization metrics.
- Bluetooth SIG Auracast and NFC Forum Device Requirements:Standardized mobile credential protocols enable smartphone-based entry without proprietary app ecosystems, reducing friction for multi-tenant building deployments.
Market Restraints
- Semiconductor supply concentration:Secure element chips for smart card and mobile credential encryption remain concentrated among Taiwanese and South Korean foundries, exposing lead time volatility for reader manufacturers.
- Cybersecurity insurance underwriting:Underwriters now exclude coverage for physical access control breaches stemming from unpatched firmware, forcing buyers to absorb residual risk or upgrade to vendor-managed SaaS architectures.
- Wiegand protocol persistence:Aging commercial building stock across Germany and Japan retains incompatible wiring infrastructure that complicates OSDP and Power over Ethernet retrofits without full cable replacement.
Strategic Opportunities
- India smart city mission integration:Municipal building access systems in Bengaluru, Mumbai, and Delhi are being specified as interoperable nodes within city-wide public safety networks, creating demand for API-first platforms.
- Convergence of access control and building automation:HVAC and lighting vendors seek credential-aware occupancy triggers, opening white space for middleware that unifies BACnet and OSDP protocols.
- FCC Part 15 unlicensed spectrum expansion:New ultra-wideband allocations enable centimeter-precision indoor positioning for touchless entry workflows in high-security federal facilities.
Industry Challenges
- Embedded systems firmware expertise scarcity:Vendors struggle to hire engineers capable of hardening ARM-based reader platforms against side-channel attacks while maintaining real-time authentication latency under 200 milliseconds.
- Common Criteria EAL4+ certification timelines:Biometric reader vendors targeting European critical infrastructure face 18-to-24-month evaluation periods that delay product launches and compress competitive windows.
- Multi-tenant data residency enforcement:Cloud platform operators must architect separate instance deployments for buyers subject to divergent national cybersecurity agency requirements across the United Kingdom, Germany, and France.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Access Control Security Market |
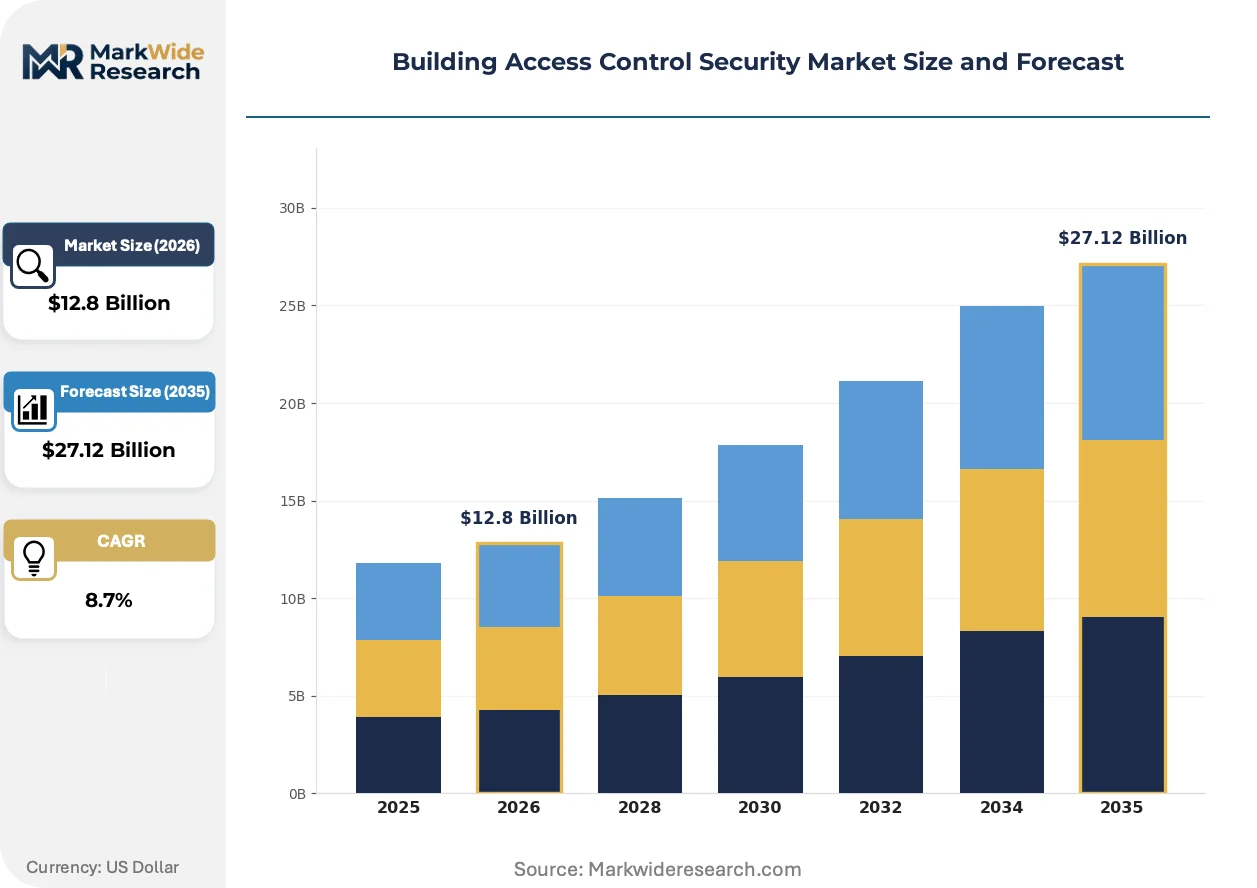
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, RFID Solutions, Key Cards, Keypad Entry Technology: Smart Locks, Intercom Systems, Cloud-Based Solutions, Traditional Locks Installation: On-Premises, Remote Access, Hosted Solutions, Integrated Systems End User: Commercial Buildings, Residential Properties, Industrial Facilities, Government Institutions |
| Companies Covered | Bosch, Avigilon, Honeywell, Lenel, HID, Brivo, Genetec, ADT Commercial, Kisi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Access Control Security Market Strategic Shifts
Edge computing architectures are redistributing authentication logic from central servers to door-mounted controllers, reducing latency while complicating firmware lifecycle management across distributed real estate portfolios.
Multi-modal biometric fusion is decomposing single-factor authentication paradigms in high-assurance environments. Financial services data centers in Frankfurt and Singapore now deploy simultaneous fingerprint, iris, and facial template matching to eliminate spoofing vectors. This convergence is compressing hardware vendor margins as specialized sensor suppliers capture value previously retained by integrated reader manufacturers.
The EU AI Act's prohibited-practices annex is restructuring procurement specifications for biometric systems across European member states. Real estate investment trusts now mandate algorithmic transparency documentation and human-in-the-loop override capabilities for all new access control deployments. German commercial landlords are responding fastest, embedding these requirements into technical tender documents ahead of the 2026 enforcement deadline.
Facility management outsourcing is consolidating buyer decision-making power among a shrinking pool of integrated service providers. Jones Lang LaSalle and Cushman Wakefield now specify standardized access control platforms across their managed portfolios, displacing fragmented site-by-site purchasing. This concentration is most visible in United States Class A office buildings where landlord-controlled base building systems increasingly override tenant preferences.
Building Access Control Security Market Segmentation
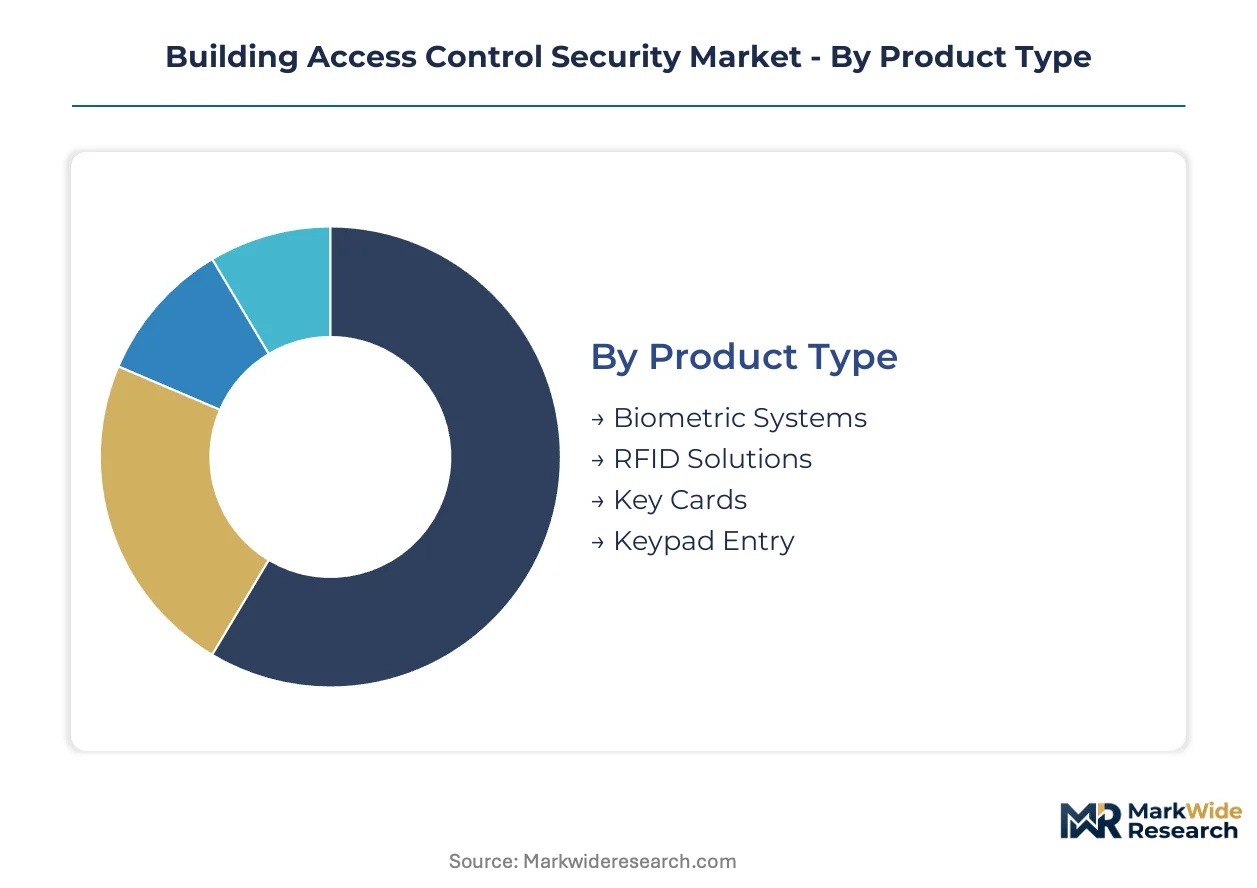
Building access control vendors configure channel strategies around deployment complexity and buyer procurement maturity. Product type determines whether systems flow through security integrators, building automation contractors, or direct SaaS subscriptions.
Product Type:
Biometric and RFID solutions move through certified security integrators demanding technical validation, while key cards and keypads reach buyers via electrical distributors and facility supply catalogs.
- Biometric Systems:Fingerprint, facial recognition, and iris template readers with liveness detection algorithms. Demand concentrates in United States financial services data centers and German critical infrastructure where EU AI Act compliance mandates certified hardware.
- RFID Solutions:Proximity and smart card readers operating at 125 kHz and 13.56 MHz frequencies with Wiegand or OSDP output protocols. Corporate headquarters in Japan and aging commercial stock across Germany sustain retrofit demand despite wiring infrastructure constraints.
- Key Cards:Physical credential tokens in PVC or composite formats for legacy system compatibility.
- Keypad Entry:PIN-based authentication devices for low-security perimeter points and secondary access layers.
By volume, RFID Solutions leads. By growth pace, Biometric Systems is climbing the fastest.
Technology:
Technology tiering separates capital-intensive hardware from recurring-revenue software platforms, with cloud-native architectures commanding premium valuations in private equity-backed vendor portfolios.
- Smart Locks:Battery-powered electromechanical locks with BLE and Wi-Fi connectivity for residential and small commercial retrofit. United Kingdom multi-tenant housing operators and United States flex-office providers drive replacement of mechanical cylinders.
- Intercom Systems:Audio-visual entry verification with SIP protocol integration and mobile app extensions. German commercial real estate investment trusts specify these for Class A office lobbies requiring visitor management audit trails.
- Cloud-Based Solutions:Multi-tenant access management platforms with API-first architectures and subscription billing. Mid-market buyers in China and India favor operational expenditure models over controller hardware procurement.
- Traditional Locks:Mechanical and electromechanical locking hardware without network connectivity.
Cloud-Based Solutions capture margin expansion. Traditional Locks dominate unit shipments.
Installation:
Installation modality determines buyer IT resource requirements and vendor service attach rates, with hosted architectures reducing field engineering dependency.
- On-Premises:Local server and controller infrastructure requiring dedicated IT administration and physical security for credential databases. Government institutions in the United States and Japan mandate air-gapped deployments for classified facility zones.
- Remote Access:Browser and mobile-administered systems with VPN or zero-trust network access for distributed real estate portfolios. Facility management outsourcing providers in the United States standardize on these for multi-site visibility.
- Hosted Solutions:Vendor-managed private cloud instances with single-tenant isolation for data residency compliance.
- Integrated Systems:Unified platforms combining access control with video management, intrusion detection, or building automation via BACnet or Modbus protocols.
On-Premises retains security-critical share. Hosted Solutions are expanding most quickly.
End User:
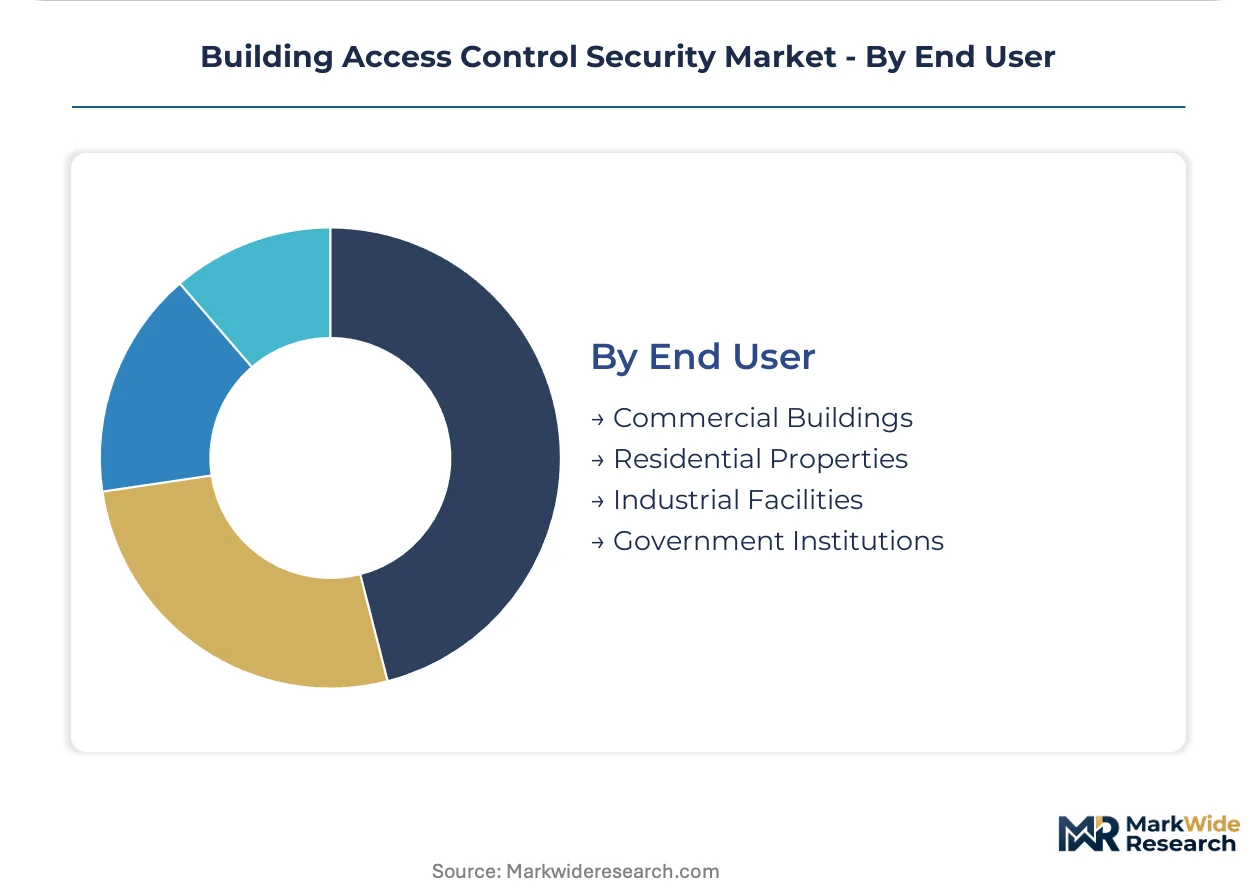
End-user verticals segment by procurement authority concentration and compliance stringency, with government and commercial buyers driving divergent specification priorities.
- Commercial Buildings:Corporate headquarters, retail, and hospitality facilities prioritizing occupancy analytics and tenant experience. United States Class A office landlords and German commercial real estate investment trusts consolidate purchasing through integrated facility managers.
- Residential Properties:Multi-family housing, gated communities, and single-family smart home installations. China and India urbanization drives demand for smartphone-integrated entry in high-rise developments.
- Industrial Facilities:Manufacturing plants, warehouses, and energy infrastructure requiring hazardous-area certifications and time-and-attendance integration.
- Government Institutions:Federal, state, and municipal facilities with FICAM or equivalent identity credential mandates and classified zone requirements.
Commercial Buildings lead by revenue contribution. Residential Properties show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese and South Korean foundries dominate secure element chip production for credential encryption, creating lead time volatility that ripples through reader manufacturing worldwide.
United States
Federal agencies mandate FICAM-compliant identity credentials for classified facilities, while Class A office landlords in Manhattan and Chicago consolidate purchasing through facility management outsourcing providers. The FCC governs wireless device emissions under Part 15 rules, with new ultra-wideband allocations enabling precision indoor positioning for touchless federal workflows.
Germany
Commercial real estate investment trusts specify biometric readers with Common Criteria EAL4+ certification for critical infrastructure, embedding EU AI Act algorithmic transparency requirements into tender documents ahead of enforcement deadlines. The Federal Office for Information Security accelerates conformity assessments for liveness-detection hardware deployed across Frankfurt financial data centers.
China
Urbanization drives smartphone-integrated entry systems in high-rise residential developments across Shenzhen and Shanghai, with mid-market buyers favoring subscription-based operational expenditure models over capital-intensive controller procurement. The Ministry of Industry and Information Technology shapes domestic interoperability standards for BLE and NFC mobile credential protocols.
Japan
Aging commercial building stock in Tokyo and Osaka retains Wiegand wiring infrastructure that complicates OSDP retrofits, sustaining demand for proximity card compatibility despite security limitations. METI guidelines encourage smart building investments that converge access control with building automation systems for energy efficiency compliance.
India
Municipal specifications in Bengaluru, Mumbai, and Delhi treat building access systems as interoperable nodes within city-wide public safety networks, creating demand for API-first platforms. The Smart Cities Mission drives standardized procurement for multi-tenant commercial developments requiring visitor management audit trails.
Building Access Control Security Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized physical security software vendors competing across fragmented procurement channels. The vendor base spans building automation integrators, security-focused technology developers, and facility management outsourcing providers. Two strategic archetypes dominate: hardware-anchored conglomerates bundling climate, fire, and access control into unified dashboards; and cloud-native software specialists unifying physical and logical security layers through video-integrated platforms. Competitive moves center on M&A to acquire biometric certification capabilities and strategic partnerships to embed access control within HVAC and lighting automation workflows.
Among diversified technology conglomerates, Honeywell and Bosch exemplify the integrated building automation archetype, leveraging climate and fire control synergies to capture bundled facility management contracts. Genetec occupies a position within the video-centric software tier, representing specialists who unify physical and logical security layers for critical infrastructure operators. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Bosch |
| Avigilon |
| Honeywell |
| Lenel |
| HID |
| Brivo |
| Genetec |
| ADT Commercial |
| Kisi |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month lead times for Common Criteria EAL4+ biometric reader certifications compress competitive windows and anchor pricing power with vendors holding pre-certified inventory, while subscription-based cloud platforms disrupt traditional hardware-centric cost structures across mid-market procurement.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating certified liveness-detection hardware from uncertified proximity readers. Three-tier pricing structure across premium biometric, standard smart card, and economy keypad levels reflects certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because cybersecurity insurance underwriters now exclude coverage for unpatched firmware breaches. Mid-market buyers in China and India exhibit highest price sensitivity, favoring operational expenditure models, while United States federal agencies demonstrate lowest sensitivity due to FICAM mandate compliance requirements.
Supply Chain Analysis
Taiwan and South Korea anchor secure element chip fabrication for credential encryption, with reader assembly drawing from Chinese and Mexican contract manufacturers. Raw material dependencies center on ARM-based microcontroller units, BLE/NFC radio modules, and biometric sensor arrays. Single-source vulnerability concentrates in Taiwanese foundry capacity for cryptographic processors. Distribution runs through certified security integrators for biometric systems and electrical distributors for legacy RFID retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building access control security sits in early-cycle expansion as cloud-native platforms displace legacy on-premises controllers and EU AI Act compliance deadlines accelerate hardware refresh cycles across European commercial real estate.
For Market Incumbents: Fortify certification pipelines by accelerating Common Criteria EAL4+ pre-evaluation investments ahead of competitor product launches, while deepening backward integration into secure element chip sourcing to insulate margins from Taiwanese foundry lead time volatility. Channel control through facility management outsourcing provider partnerships protects against cloud-native software specialists capturing mid-market share.
For New Entrants and Emerging Players: Lead with API-first architectures targeting India's Smart Cities Mission municipal specifications, where building access systems function as interoperable nodes within city-wide public safety networks. White space concentrates in middleware unifying BACnet and OSDP protocols for HVAC-credential convergence. Go-to-market through building automation contractors rather than traditional security integrators bypasses entrenched incumbent relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription billing models capture operational expenditure shifts while biometric certification capabilities create durable competitive moats. Acquisition target archetype: cloud-native access platforms with multi-tenant architectures and existing API integrations. Signal to watch: facility management outsourcing provider consolidation accelerating standardized platform specification across Class A office portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Investment | Common Criteria EAL4+ pre-certification compresses competitive windows ahead of EU AI Act enforcement deadlines. |
| Cloud Platform Integration | API-first architectures capture municipal smart city procurement in India requiring interoperable public safety nodes. |
| Building Automation Partnership | Middleware development unifying BACnet and OSDP protocols opens HVAC-credential convergence white space. |
| Secure Element Sourcing | Backward integration into Taiwanese and South Korean chip supply insulates margins from foundry concentration risk. |
| Facility Management Channel Control | Standardized platform specification through Jones Lang LaSalle and Cushman Wakefield consolidates purchasing power. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and vendor financial disclosures through structured interviews with facility management directors, security integrators, building automation contractors, and commercial real estate investment trust procurement leads. Bottom-up triangulation validates installed base estimates and refresh cycle timing, while top-down cross-checks anchor market sizing against smart building investment flows and cybersecurity mandate compliance spending.
Segmentation dimensions modeled span product type, technology tier, installation modality, and end-user vertical across the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, regulatory deadline impacts, and cloud adoption elasticity coefficients. Industry-specific forecast inputs include EU AI Act implementation pacing, FCC Part 15 ultra-wideband allocation uptake for federal touchless entry, and semiconductor foundry capacity utilization rates affecting reader manufacturing lead times.
The analysis sits within stated boundaries; outcomes outside sustained smart building investment levels, stable semiconductor supply, or unaltered regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding cloud platform migration rates and biometric hardware certification completion schedules. Recalibration cycles align with material shifts in cybersecurity insurance underwriting standards, foundry capacity expansions, or municipal smart city procurement accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
US Access Control Market
Access Control Systems
Network Access Control Market
Access Control Systems
France Access Control Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Access Control and Authentication Market