
 Sanitary Valves Market | 2026-2036
Sanitary Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Valves Market Outlook
German stainless steel forging capacity is consolidating around specialized producers serving hygienic equipment OEMs. Alfa Laval leverages integrated foundry operations in southern Sweden to sustain margin control across its valve portfolio. GEA Group Aktiengesellschaft anchors European dairy equipment supply through dedicated hygienic component manufacturing in Bavaria. Emerson Electric Co. competes on instrumentation-integrated valve architectures for aseptic pharmaceutical lines.
Sanitary valves are fluid control devices engineered from corrosion-resistant alloys with surface finishes typically achieving Ra 0.8 micrometers or smoother, designed for rapid disassembly and sterilization between production batches. Their primary purpose is to eliminate contamination risks in processes where microbial control or product purity is mandatory. Butterfly valves dominate food and beverage installations where frequent cleaning cycles and compact footprint matter most. Stainless steel material grades, particularly 316L with low carbon content, command premium positioning due to weldability requirements and chloride corrosion resistance in CIP systems. Clamp connections lead biotechnology applications where tool-free disassembly supports validation protocols.
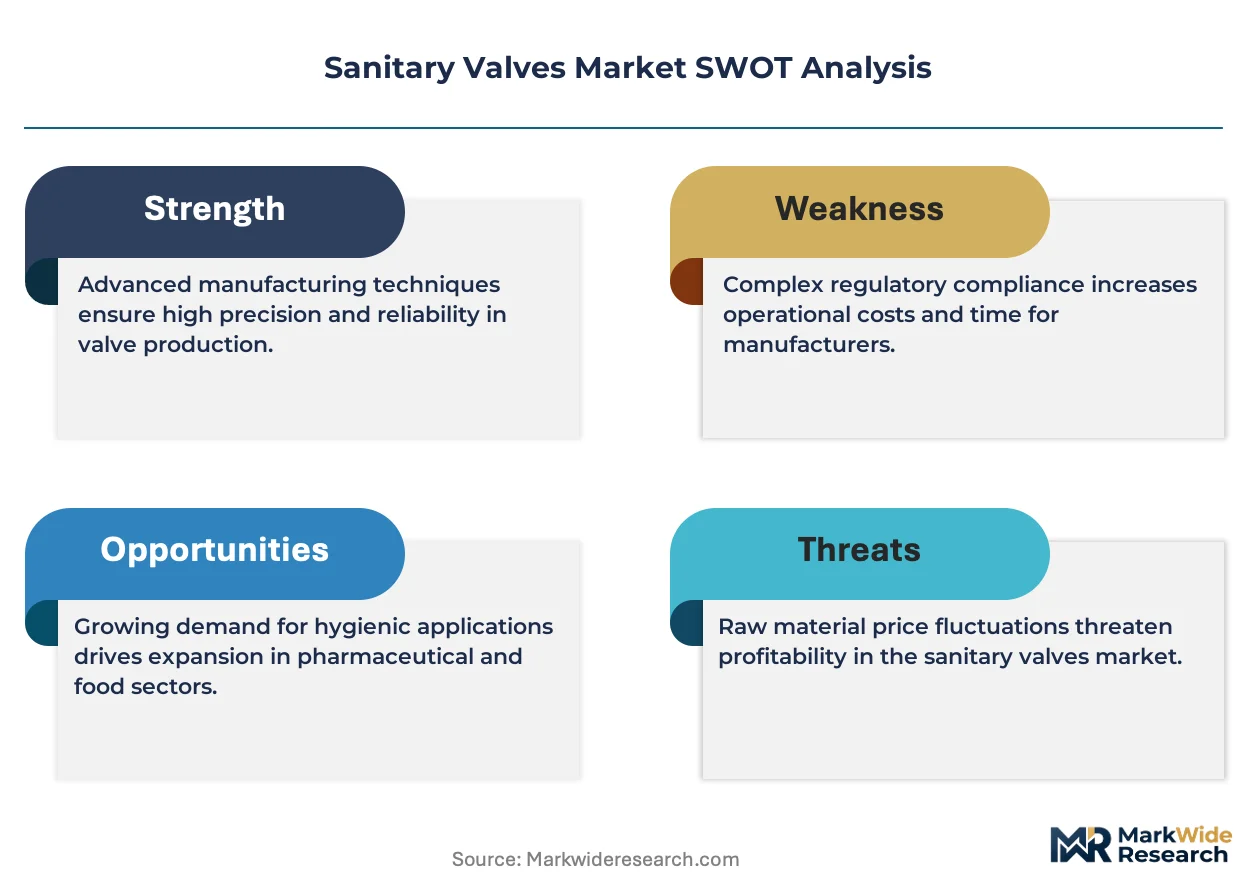
FDA's 21 CFR Part 117 sanitary design rules and the EU's MDR framework for process equipment both elevate documentation and traceability burdens on valve suppliers seeking market access. EMA's Annex 1 revision on sterile manufacturing pushes pharmaceutical end users toward valves with validated steam sterilization cycles and enhanced sealing integrity. India's BIS adoption of ISO 2852 clamp standards harmonizes import requirements while creating compliance thresholds for domestic fabricators. Stakeholders must weigh regional certification divergence against platform standardization when configuring global supply footprints.
Market Dynamics
EMA's Annex 1 sterile manufacturing revision is compressing validation timelines and forcing pharmaceutical processors to replace legacy valve architectures with steam-sterilizable designs certified for enhanced sealing integrity.
Growth Catalysts
- EMA Annex 1 Compliance Mandate:European pharmaceutical manufacturers must upgrade sterile processing lines to meet contamination control requirements, directly expanding demand for validated hygienic valve systems.
- India Dairy Corridor Expansion:Stainless steel valve procurement concentrates in Uttar Pradesh and Maharashtra as cooperative processing capacity scales to meet export quality thresholds.
- 316L Low-Carbon Specification:Weldability requirements in clean-in-place systems elevate material grade preferences, pulling premium alloy demand from standard 304 formulations.
Market Restraints
- Nickel Price Volatility:Stainless steel 316L input costs fluctuate with London Metal Exchange nickel contract movements, compressing fabricator margins on fixed-price pharmaceutical contracts.
- German Forging Concentration:Specialized hygienic-grade forging capacity clusters in Bavaria and Baden-Württemberg, creating geographic supply vulnerability for pan-European OEMs.
- Electropolishing Bottleneck:Surface finish achievement below Ra 0.4 micrometers requires certified subcontractor networks with limited throughput expansion.
Strategic Opportunities
- Biotechnology Clamp Standardization:India's BIS adoption of ISO 2852 creates compliance pathways for domestic fabricators to displace import dependency in bioprocessing installations.
- Instrumentation Convergence:Valve-actuator-sensor integration architectures enable predictive maintenance contracts in aseptic pharmaceutical lines.
- Single-Use Hybrid Systems:Disposable valve manifold assemblies penetrate multi-product biotech facilities requiring rapid changeover validation.
Industry Challenges
- Certified Welder Scarcity:Orbital welding qualification for 316L hygienic joints limits fabrication throughput expansion in high-growth dairy processing corridors.
- Legacy System Integration:Steam-sterilizable valve retrofits into existing CIP/SIP infrastructure require custom flange adaptations extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Valves Market |
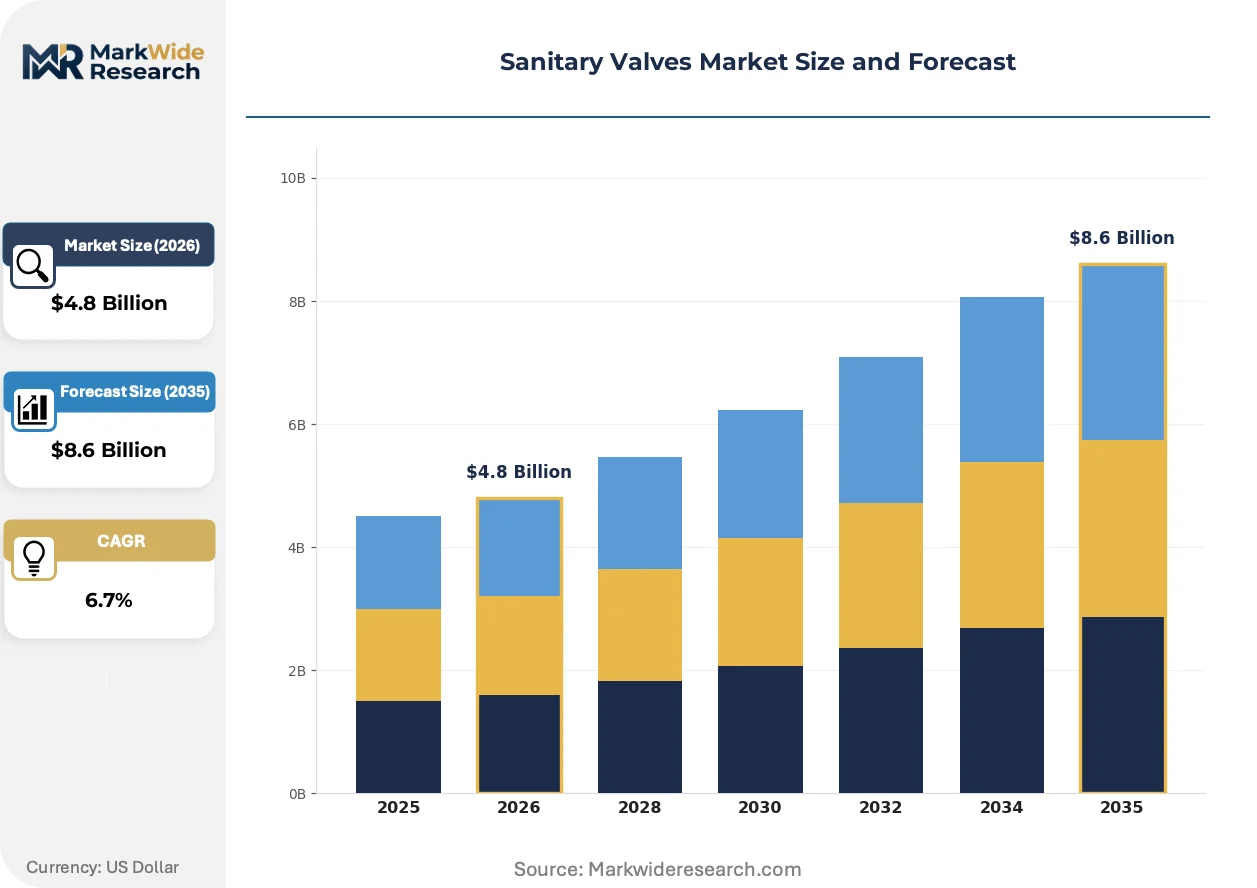
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Butterfly Valves, Gate Valves, Check Valves Material: Stainless Steel, Plastic, Bronze, Brass End User: Food & Beverage, Pharmaceutical, Biotechnology, Chemical Connection Type: Welded, Flanged, Threaded, Clamp |
| Companies Covered | Alfa Laval, GEA Group Aktiengesellschaft, SPX FLOW, Emerson Electric Co., Flowserve Corporation, GEMÜ Group, KSB SE & Co. KGaA, ITT Inc., Spirax-Sarco Engineering plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Valves Market Strategic Shifts
Surface engineering and control architecture convergence are compressing the gap between commodity fluid handling and validated pharmaceutical-grade systems, reshaping competitive differentiation around certification depth rather than base metallurgy alone.
Electropolished 316L valve bodies with sub-Ra 0.4 micrometer finishes are consolidating specification standards in parenteral drug manufacturing. Pfizer and Roche facilities in Switzerland and Germany now mandate this surface grade for all product-contact surfaces. The technology is consolidating tier-2 fabricators into specialized electropolishing subcontractor networks rather than in-house capability builds.
EU MDR framework documentation requirements for process equipment traceability are extending valve supplier audit obligations through three-tier supply chains. Medical device manufacturers must now validate forging heat lot records and surface treatment batch documentation. German dairy equipment OEMs serving pharmaceutical adjacent markets face the steepest compliance cost escalation.
Pharmaceutical procurement teams now unbundle valve supply from installation and validation services, creating separate contract tiers for hardware, commissioning, and ongoing metrology. This disintermediation pressures traditional full-service distributors in the Netherlands and Belgium. Biotechnology startups in Cambridge and Basel increasingly source valves direct from Swedish foundry-integrated manufacturers while contracting validation separately.
Sanitary Valves Market Segmentation
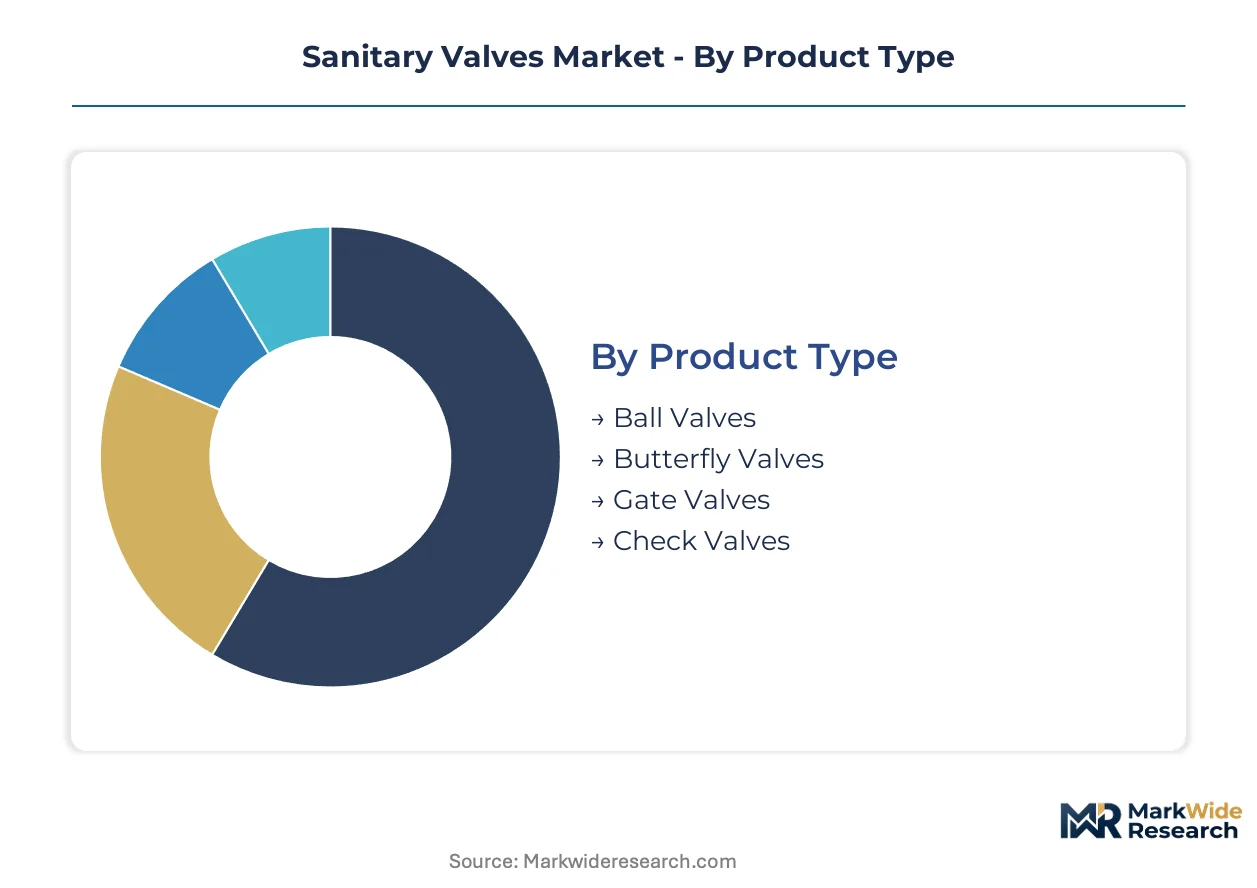
Sanitary valve procurement patterns diverge sharply across product architectures and material grades, with specification decisions cascading through connection geometry, sterilization protocols, and end-use compliance burdens. Each segmentation axis carries distinct margin profiles and supplier qualification thresholds that reshape competitive positioning.
Product Type:
Specialized forging capacity for hygienic valve bodies clusters in southern Germany and western Sweden, creating geographic supply asymmetries that favor integrated manufacturers.
- Ball Valves:Spherical closure elements with full-bore flow paths achieve Ra 0.8 micrometer surface finishes through precision machining and electropolishing sequences. Pharmaceutical sterile processing lines in Switzerland and Germany specify these for precise flow modulation under validated steam sterilization cycles. EMA Annex 1 compliance mandates are compressing validation timelines for ball valve retrofits.
- Butterfly Valves:Compact disc-shaped closure mechanisms rotate within the flow stream, minimizing pressure drop and enabling rapid actuation. Dairy processing corridors in Uttar Pradesh and Maharashtra favor these for frequent CIP cycles where footprint constraints dominate. India's BIS adoption of ISO 2852 clamp standards is harmonizing procurement specifications across cooperative processing facilities.
- Gate Valves:Linear-motion closure elements provide unobstructed full-flow capacity with minimal turbulence generation.
- Check Valves:Self-acting flow prevention devices eliminate backflow contamination risks without external actuation.
Butterfly valves absorb the bulk of installed capacity in food and beverage applications; ball valves are expanding most quickly in pharmaceutical sterile processing retrofits.
Material:
Raw material cost tiers stratify procurement patterns, with nickel-bearing alloys commanding premium positioning against lower-grade alternatives.
- Stainless Steel:Austenitic grades 316L and 304L dominate validated hygienic systems, with low-carbon 316L specifications mandatory for chloride-rich CIP chemistries and orbital welding sequences. German pharmaceutical OEMs in Bavaria specify heat-lot traceable 316L forgings to satisfy EU MDR documentation requirements. London Metal Exchange nickel volatility directly compresses fabricator margins on fixed-price contracts.
- Plastic:Polypropylene and PVDF formulations penetrate single-use bioprocessing manifolds where gamma sterilization compatibility and disposal economics outweigh metallic durability. Cambridge and Basel biotechnology startups specify these for rapid product changeover validation without steam sterilization infrastructure.
- Bronze:Copper-tin alloys serve lower-purity water and steam applications where cost sensitivity exceeds corrosion resistance requirements.
- Brass:Zinc-copper formulations occupy economy-tier plumbing and secondary process water roles outside validated pharmaceutical contact zones.
Stainless steel commands the dominant share of pharmaceutical and dairy installed base; plastic is gaining share fastest in disposable bioprocessing architectures.
End User:
Compliance intensity and validation documentation burdens segment demand across radically different procurement workflows and supplier qualification depths.
- Food & Beverage:Dairy, brewery, and processed food operations prioritize rapid CIP cycle compatibility and tool-free maintenance access over extreme surface finish specifications. India's expanding cooperative processing capacity in Maharashtra drives stainless steel valve procurement concentrated in 316L clamp configurations. FSSAI hygiene mandates are elevating documentation requirements for equipment traceability.
- Pharmaceutical:Sterile drug manufacturing mandates steam-sterilizable designs with validated sealing integrity and sub-Ra 0.4 micrometer electropolished surfaces for parenteral applications. Pfizer and Roche facilities in Switzerland and Germany now specify this grade universally for product-contact surfaces. EMA Annex 1 revisions are forcing legacy valve architecture replacements across European sterile processing lines.
- Biotechnology:Multi-product cell culture facilities balance stainless steel durability against single-use disposability for campaign-based manufacturing.
- Chemical:Aggressive media handling prioritizes corrosion resistance alloys and specialized elastomer selections over hygienic surface finish protocols.
Food and beverage represents the largest installed volume; pharmaceutical is climbing the fastest on compliance-driven replacement cycles.
Connection Type:
Fabrication labor intensity and field adaptability create distinct total-cost-of-ownership profiles across installation methodologies.
- Welded:Permanent orbital-welded joints eliminate gasket contamination risks and achieve the highest sealing integrity for sterile pharmaceutical lines. Certified orbital welder scarcity in India's dairy processing corridors limits fabrication throughput expansion despite surging demand. 316L low-carbon specifications are mandatory to preserve corrosion resistance in heat-affected zones.
- Clamp:Tool-free tri-clover or ISO 2852 configurations enable rapid disassembly for validation protocols and maintenance access. Biotechnology applications in Cambridge and Basel standardize on these for flexible facility reconfiguration. India's BIS adoption of ISO 2852 is creating compliance pathways for domestic fabricators to displace import dependency.
- Flanged:Bolted mating surfaces accommodate higher pressure ratings and legacy system integration requirements.
- Threaded:Screw-in configurations serve lower-pressure utility and secondary process applications where rapid field modification outweighs hygienic sealing priorities.
Welded connections dominate pharmaceutical sterile installations; clamp configurations are expanding most quickly in biotechnology flexible manufacturing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish foundry-integrated operations and Bavarian forging clusters anchor stainless steel valve supply chains serving pharmaceutical and dairy processing demand across multiple continents.
Germany
EMA Annex 1 sterile manufacturing mandates are compressing validation timelines for pharmaceutical processors in Bavaria and Baden-Württemberg. The country's national pharmaceutical regulator enforces contamination control requirements that force legacy valve architecture replacements. Specialized forging capacity clusters around hygienic equipment OEMs in southern Germany.
India
Dairy cooperative processing capacity in Uttar Pradesh and Maharashtra is scaling to meet export quality thresholds, concentrating stainless steel valve procurement. BIS adoption of ISO 2852 clamp standards harmonizes import requirements while creating compliance thresholds for domestic fabricators. Certified orbital welder scarcity limits fabrication throughput expansion despite surging demand.
Switzerland
Pfizer and Roche facilities mandate sub-Ra 0.4 micrometer electropolished surfaces for all product-contact surfaces in parenteral drug manufacturing. Swissmedic oversight elevates documentation and traceability burdens on valve suppliers seeking market access. Basel biotechnology startups increasingly source valves direct from foundry-integrated manufacturers while contracting validation separately.
United States
FDA 21 CFR Part 117 sanitary design rules elevate documentation requirements for food and beverage processing equipment across dairy and brewery installations. Biotechnology clusters in Cambridge and Greater Boston standardize on clamp configurations for flexible facility reconfiguration. Single-use hybrid valve manifold assemblies penetrate multi-product facilities requiring rapid changeover validation.
Sweden
Foundry-integrated valve manufacturing in southern Sweden sustains margin control through captive alloy supply and precision machining capabilities. EU MDR framework documentation requirements extend supplier audit obligations through three-tier supply chains. Electropolishing subcontractor networks consolidate tier-2 fabricators rather than in-house capability builds.
Sanitary Valves Market Competitive Environment
Global majors compete with regional champions across certification depth and metallurgical integration. The vendor base stratifies into three tiers: integrated foundry operators commanding premium positioning, specialized hygienic fabricators serving regional dairy corridors, and instrumentation-convergent suppliers targeting aseptic pharmaceutical lines. Consolidation pressure concentrates in German forging capacity and Swedish alloy supply. Dominant competitive moves include backward integration into foundry operations and geographic expansion into India's dairy processing corridor.
Within the integrated-foundry tier, Alfa Laval exemplifies Scandinavian captive-supply positioning through southern Swedish operations. GEA Group Aktiengesellschaft anchors European dairy equipment supply through Bavarian manufacturing concentration. Emerson Electric Co. occupies the instrumentation-convergent position, competing on valve-actuator-sensor architectures for aseptic pharmaceutical applications. These three represent distinct competitive archetypes rather than direct substitutes.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group Aktiengesellschaft |
| SPX FLOW |
| Emerson Electric Co. |
| Flowserve Corporation |
| GEMÜ Group |
| KSB SE & Co. KGaA |
| ITT Inc. |
| Spirax-Sarco Engineering plc |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical OEM procurement teams in Bavaria and Baden-Württemberg unbundle hardware supply from validation services, compressing margin capture for traditional full-service distributors and favoring foundry-integrated manufacturers with captive alloy supply.
Pricing Analysis
Warranty and commissioning service bundling now separates three distinct contract tiers in European pharmaceutical procurement: hardware-only supply, installation with FAT/SAT documentation, and ongoing metrology with predictive maintenance subscriptions. Three-tier pricing structure across premium electropolished 316L, standard machined 316L, and economy 304L grades reflects certification depth and surface finish achievement. Cost compression in standard-grade dairy valves intensifies because Indian domestic fabricators displace import dependency under BIS ISO 2852 compliance pathways. Dairy cooperatives in Maharashtra exhibit the highest price sensitivity; Swiss parenteral drug manufacturers show the least.
Supply Chain Analysis
Container freight rate volatility from Swedish foundries to Basel biotechnology clusters and Bavarian pharmaceutical corridors elevates landed cost unpredictability for electropolished valve bodies. Supply concentrates in southern Sweden, Bavaria, and western Germany, drawing from nickel-bearing alloy feedstock, precision machining capacity, and certified electropolishing subcontractor networks. Single-source vulnerability in orbital welding qualification for 316L hygienic joints limits fabrication throughput expansion in India's dairy processing corridors. Distribution runs through OEM direct channels for pharmaceutical sterile lines and regional equipment distributors for food and beverage installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive foundry operations and electropolishing capability defines the current competitive race, as alloy supply control and surface finish certification separate margin leaders from commodity fabricators.
For Market Incumbents: Acquire certified electropolishing subcontractor networks to secure surface finish throughput below Ra 0.4 micrometers for parenteral pharmaceutical specifications. Consolidate Bavarian forging capacity around heat-lot traceable 316L supply to satisfy EU MDR documentation requirements. Defend against instrumentation-convergent entrants by embedding sensor architectures into valve-actuator systems for predictive maintenance contracts. For New Entrants and Emerging Players: Begin with ISO 2852 clamp configuration fabrication for India's dairy cooperative processing expansion in Uttar Pradesh and Maharashtra, where certified orbital welder scarcity constrains incumbent throughput. Target biotechnology flexible manufacturing platforms in Cambridge and Basel with single-use hybrid valve manifold assemblies. Pursue direct-to-facility sales models that bypass traditional distributor markups on validation-bundled procurement. For Investors and Strategic Acquirers: The window for entry favors foundry-integrated mid-cap specialists with captive Swedish alloy supply and established electropolishing subcontractor relationships over pure-play fabricators exposed to nickel price volatility. Long-term viability hinges on certification depth rather than volume scale, positioning specialized hygienic-grade manufacturers for sustained margin capture. Monitor EMA Annex 1 enforcement intensity across European sterile processing lines as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive 316L alloy supply insulates margin control from London Metal Exchange nickel volatility. |
| Electropolishing Capability Buildout | In-house sub-Ra 0.4 micrometer surface finish achievement captures parenteral pharmaceutical specification premiums. |
| Instrumentation Convergence Investment | Valve-actuator-sensor integration architectures enable predictive maintenance contracts in aseptic lines. |
| ISO 2852 Compliance Certification | BIS harmonization in India creates displacement pathways for domestic fabricators against import dependency. |
| Single-Use Hybrid System Development | Disposable manifold assemblies penetrate Basel and Cambridge biotechnology facilities requiring rapid changeover validation. |
Study Parameters
Multi-period observation of EMA Annex 1 implementation timelines, BIS standard adoption rates, and nickel contract price movements anchored the trend analysis, supplemented by interviews with pharmaceutical sterile processing engineers, dairy plant maintenance directors, hygienic equipment OEM procurement teams, and certified orbital welding instructors. Secondary validation drew from FDA 21 CFR Part 117 guidance documents, EU MDR technical documentation requirements, SEC filings of listed valve manufacturers, and stainless steel trade flow data. Bottom-up fabrication capacity assessments and top-down end-use demand estimates were triangulated to constrain projection variance.
Segment-weighting across product architecture, material grade, end-use compliance intensity, and connection geometry informed the analytical framework over the projection horizon. Stainless steel 316L specification trends, electropolishing subcontractor network expansion, and clamp standard adoption patterns served as industry-specific forecast inputs. CAGRs were derived from installed base replacement cycle analysis and greenfield capacity addition tracking across pharmaceutical and dairy processing corridors.
Underlying measurement precision varies by segment; pharmaceutical sterile processing specifications carry tighter precision than food and beverage commodity procurement given documented validation protocol requirements. Forecasts reflect assumptions about regulatory enforcement continuity, alloy price stabilization, and certified welder training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Tubing Heads Market
Valves
Valve Driver Market
Valves
Pneumatic Slide Gates Market
Valves
Safety Valve Market
Valves
US Water & Wastewater Valves Market
Valves
Insulation Flanges Market
Valves
Valve Sack Market
Valves
Pneumatic Needle Valves Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Europe Valves Market
Valves
Reciprocating Compressor Components Market
Valves
Rupture Discs Market
Valves
Chemical Injection Skid Market
Valves
Pipeline Strainers Market
Valves
Mechanical Shaft Seal Market
Valves
Global Control Valves Market