
 Servo Valves Market | 2026-2036
Servo Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Servo Valves Market Outlook
The EU F-Gas Regulation is hardening emission thresholds for industrial fluid power systems, compelling servo valve suppliers to redesign sealing architectures and reduce hydraulic fluid leakage rates. Moog leverages its aerospace heritage to dominate high-reliability flight control actuation, where failure tolerance approaches zero. Parker Hannifin anchors its position through backward integration into precision spool manufacturing, capturing margin pools that competitors outsource. Eaton Corporation competes aggressively in defense platforms, sustaining long-term service contracts that lock in replacement part revenue.
A servo valve is a closed-loop electrohydraulic flow control device that modulates fluid pressure and direction through a torque motor-driven flapper-nozzle or jet-pipe pilot stage, achieving response times below 5 milliseconds and positional accuracy within 0.5 percent. Its primary industrial purpose is to translate low-power electrical command signals into precise, high-force mechanical motion in systems where open-loop control would introduce unacceptable position error or instability. Digital servo valves represent the fastest-expanding product category, as embedded microprocessors enable real-time diagnostics and field-reconfigurable gain settings that reduce commissioning downtime. Within applications, aerospace commands the highest unit margins due to certification burdens, while industrial automation generates the largest aggregate volume as Chinese and German manufacturers retrofit presses and injection molding equipment with closed-loop positioning.
The EPA oversees hydraulic fluid spill containment under Clean Water Act provisions, while ISO 4406 cleanliness standards dictate permissible particulate contamination in servo valve supply lines, directly influencing filter specification and maintenance intervals. Japan's METI promotes energy-efficient fluid power through its Top Runner program, creating asymmetric compliance costs for exporters serving Japanese OEMs. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape material selection for valve bodies and electromagnetic coils, as embodied carbon reporting extends into tier-two component sourcing decisions.
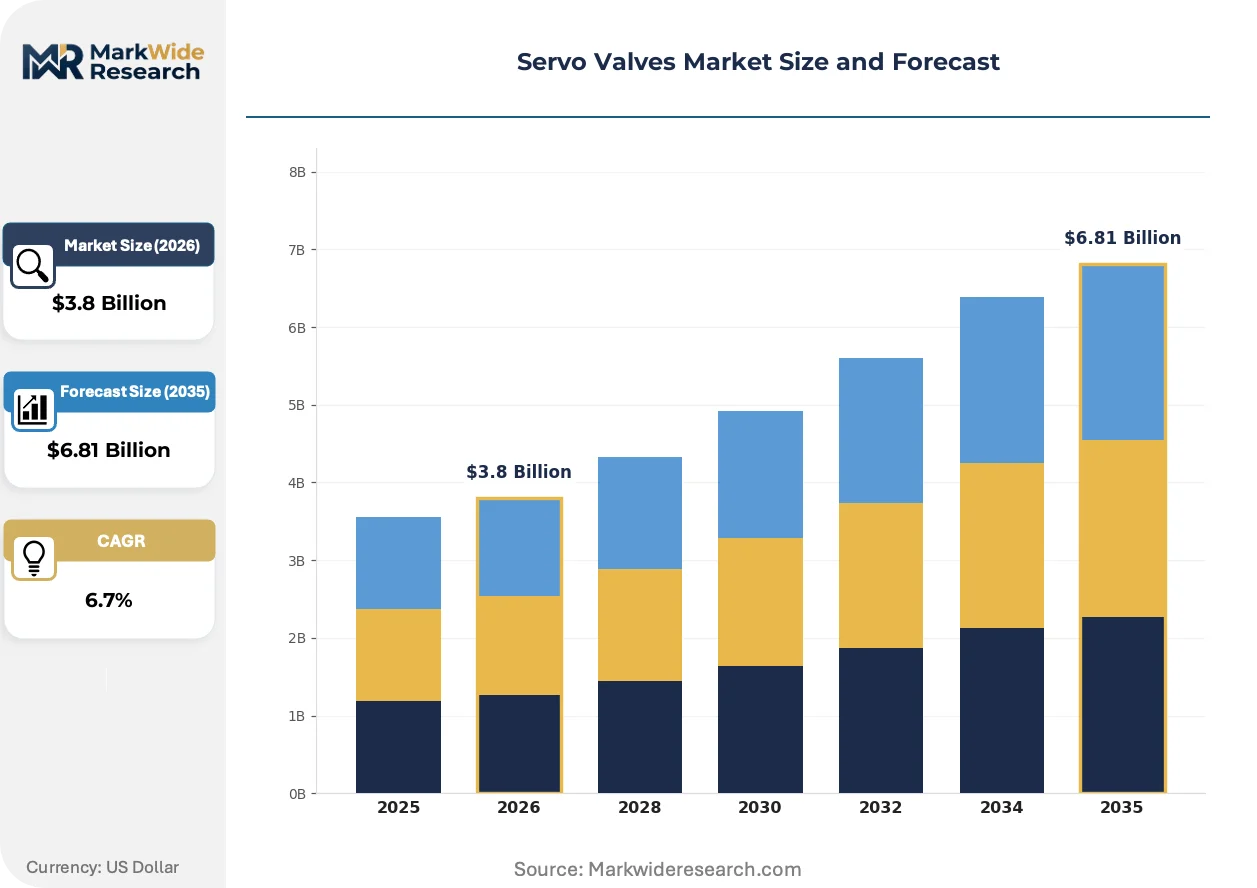
Market Dynamics
The EU F-Gas Regulation is compressing permissible leakage thresholds for industrial hydraulic systems, forcing servo valve manufacturers to redesign sealing architectures and migrate toward low-emission fluid power architectures across European industrial automation clusters.
Growth Catalysts
- Electrified Production Lines:German automotive OEMs require high-response servo valve solutions for battery assembly and electric drivetrain manufacturing, driving precision motion control procurement.
- Aerospace Platform Modernization:Flight control actuation systems for next-generation aircraft demand fail-safe servo valve architectures with sub-5 millisecond response times.
- REACH Compliance Spillover:Restrictions on hazardous substances in hydraulic fluids are accelerating adoption of bio-based synthetic alternatives compatible with advanced sealing materials.
Market Restraints
- Raw Material Concentration:Precision spool manufacturing depends on specialty steel alloys concentrated in Japanese and German metallurgical suppliers, creating input vulnerability.
- Certification Burden:Aerospace servo valves require FAA and EASA airworthiness certification cycles spanning 18-36 months, freezing design iterations and elevating development cost structures.
- Electromechanical Substitution:High-force electric linear actuators are displacing hydraulic servo systems in sub-50 kW industrial positioning applications where fluid maintenance is prohibitive.
Strategic Opportunities
- Chinese Industrial Retrofit:Domestic manufacturers in Jiangsu and Guangdong provinces are retrofitting injection molding and metal forming equipment with closed-loop servo hydraulics to meet energy efficiency mandates.
- Digital Valve Integration:Embedded microprocessors enabling real-time diagnostics and field-reconfigurable gain settings are creating service revenue streams through predictive maintenance platforms.
- EU Green Deal Procurement:Public infrastructure and defense tenders now incorporate embodied carbon scoring for valve bodies and electromagnetic coils, favoring suppliers with verified low-carbon supply chains.
Industry Challenges
- Torque Motor Calibration Expertise:The specialized electromechanical knowledge required for flapper-nozzle pilot stage assembly is concentrated among aging technician populations in the US and Germany.
- ISO 4406 Cleanliness Compliance:Maintaining particulate contamination thresholds below 18/16/13 in high-cycle industrial environments demands intensive filter management and fluid monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Servo Valves Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
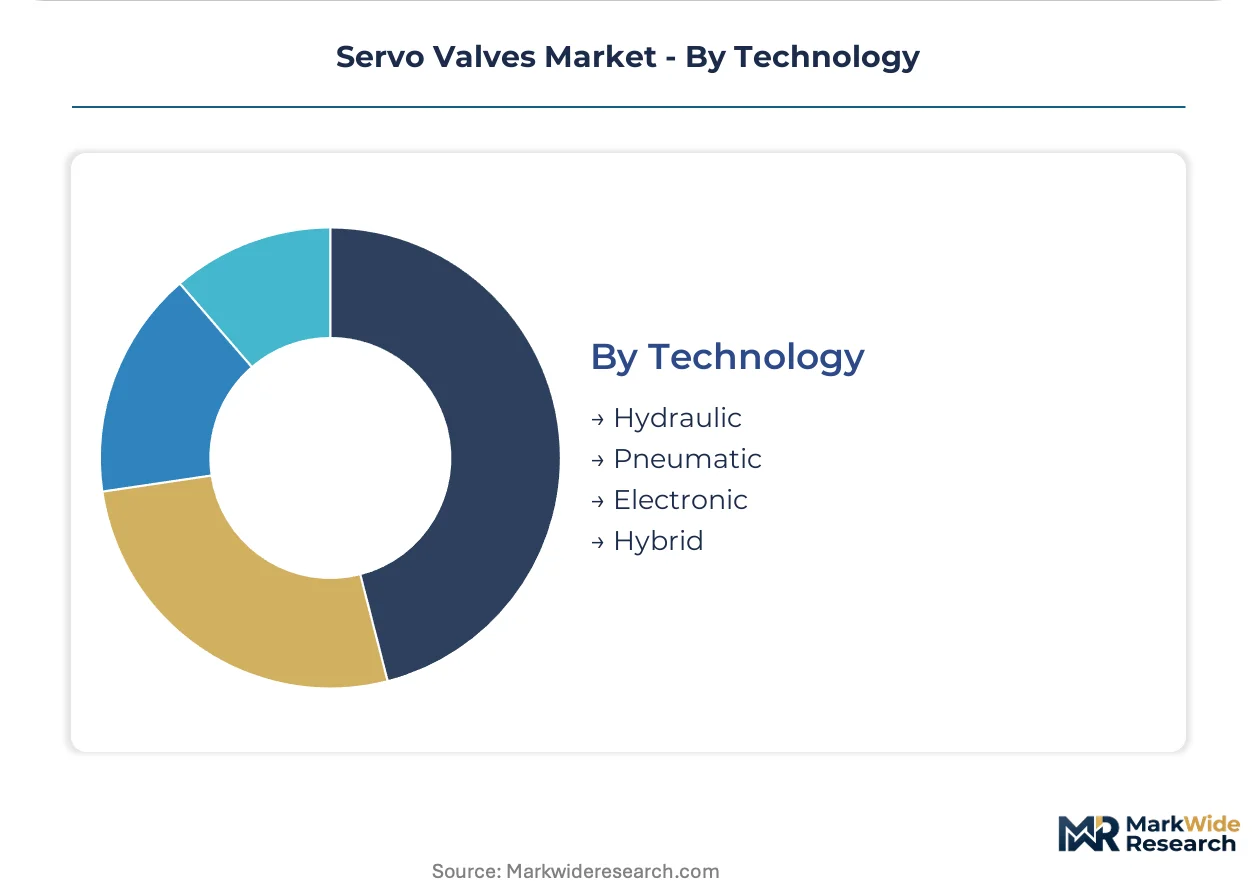
| Segmentation | Product Type: Linear Servo Valves, Rotary Servo Valves, Proportional Servo Valves, Digital Servo Valves Application: Aerospace, Automotive, Industrial Automation, Marine End User: Manufacturing, Defense, Oil & Gas, Robotics Technology: Hydraulic, Pneumatic, Electronic, Hybrid |
| Companies Covered | Moog, Parker Hannifin, HAWE Hydraulik, Honeywell International, Eaton Corporation, Yuken Kogyo, Daikin Industries, Duplomatic MS, Domin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Servo Valves Market Strategic Shifts
Digital intelligence is penetrating hydraulic control architectures, enabling real-time performance optimization and shifting competitive advantage toward software-integrated fluid power platforms.
Jet-pipe pilot stage technology is converging with additive manufacturing for flow passage optimization. Aerospace tier-one suppliers are qualifying 3D-printed valve bodies for non-flight-critical actuation, compressing prototyping cycles from months to weeks. This convergence is lowering barriers for customized servo valve geometries tailored to specific airframe hydraulic architectures.
The EPA's hydraulic fluid spill containment enforcement under Clean Water Act provisions is hardening liability exposure for industrial operators. Manufacturing facilities must now deploy secondary containment and leak detection systems for hydraulic reservoirs above threshold volumes. Chemical processing and steel milling operations in the US Gulf Coast and Great Lakes regions are accelerating replacement of legacy valve fleets with low-leakage cartridge designs.
After-sales service unbundling is fragmenting traditional supplier-customer relationships. German automotive press manufacturers now purchase servo valves without bundled maintenance contracts, instead procuring predictive analytics subscriptions from third-party IIoT platforms. This behavioral shift is compressing OEM service margins and forcing valve suppliers to open diagnostic protocols to interoperable software ecosystems.
Servo Valves Market Segmentation
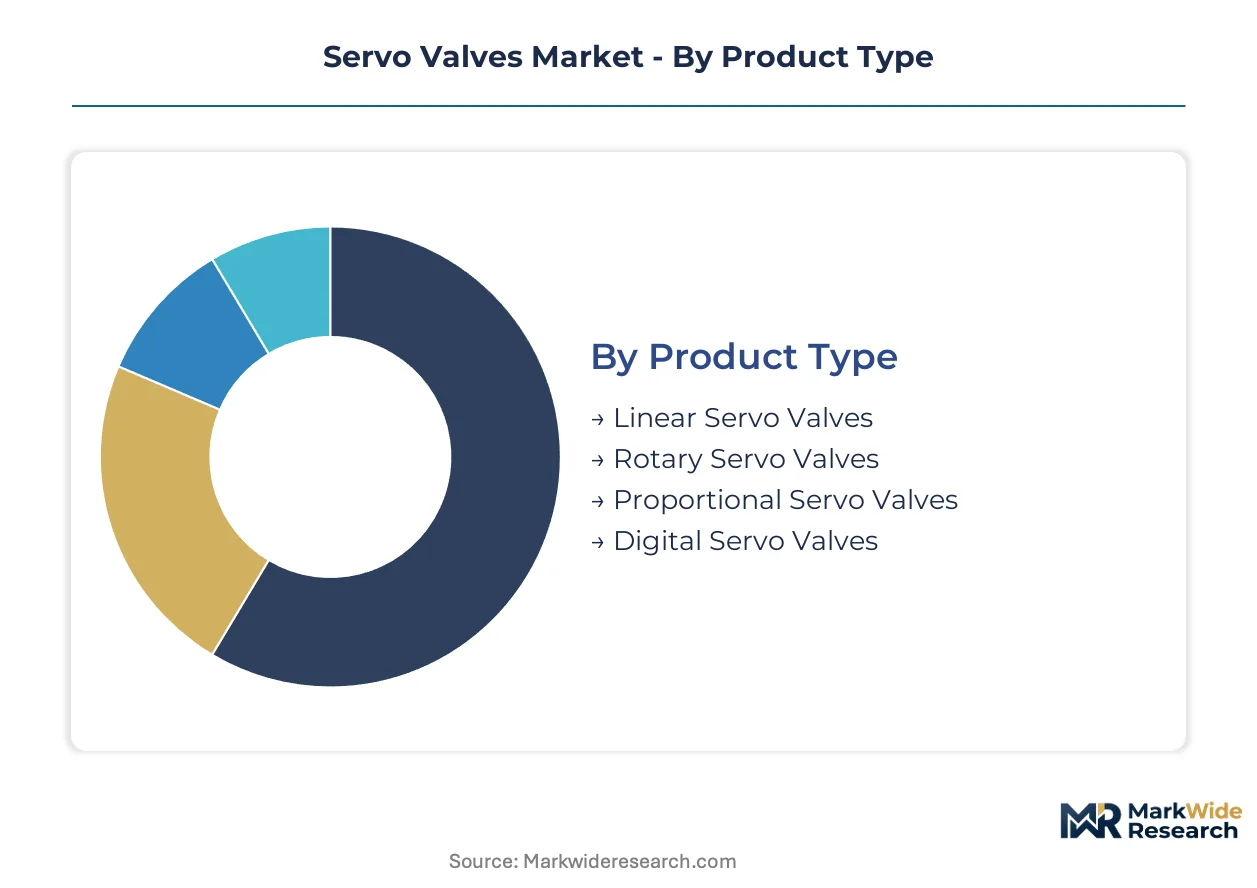
Segmentation in servo valves reveals how performance specifications, certification burdens, and fluid power architectures split commercial opportunity across divergent buyer requirements. Each axis—product design, application environment, end-user procurement patterns, and underlying technology—creates distinct margin profiles and competitive barriers.
Product Type:
Valve kinematics and control intelligence define this axis, separating electromechanical sophistication from mechanical simplicity.
- Linear Servo Valves:These devices translate electrical signals into precise linear displacement of a spool or poppet, achieving positional accuracy within 0.5 percent in flight control actuation. Aerospace OEMs in Germany and the US specify these for primary flight surfaces where failure tolerance approaches zero, with EASA certification cycles extending 24-36 months.
- Digital Servo Valves:Embedded microprocessors enable real-time diagnostics, field-reconfigurable gain settings, and predictive maintenance integration. Industrial automation clusters in Jiangsu province and German automotive press manufacturers are retrofitting legacy hydraulic systems with these units to meet energy efficiency mandates and reduce commissioning downtime.
- Rotary Servo Valves:Torque motor-driven flapper mechanisms modulate flow through angular displacement, common in missile fin actuation and radar positioning systems.
- Proportional Servo Valves:Simpler electromechanical architectures without closed-loop feedback dominate cost-sensitive industrial positioning where sub-10-millisecond response suffices.
Mature deployment sits with linear architectures in certified aerospace platforms. Newer deployment is concentrated in digital valve integration across electrified automotive production lines.
Application:
Environmental severity and regulatory exposure determine specification intensity across installation environments.
- Aerospace:Flight control actuation demands fail-safe architectures with sub-5-millisecond response times and dual-redundant torque motor configurations. FAA and EASA airworthiness requirements freeze design iterations for 18-36 months, elevating unit margins through certification scarcity.
- Industrial Automation:Chinese injection molding retrofits and German metal forming equipment generate the largest aggregate volume, with closed-loop positioning replacing open-loop hydraulics to satisfy ISO 4406 cleanliness standards and EU F-Gas leakage thresholds.
- Automotive:Battery assembly lines and electric drivetrain manufacturing require high-response solutions for precision joining and pressing operations.
- Marine:Subsea blowout preventer actuation and naval steering systems specify corrosion-resistant sealing architectures against saltwater ingress.
Certification-locked aerospace procurement sustains premium pricing. Volume expansion is accelerating most quickly in industrial automation retrofits across East Asian manufacturing clusters.
End User:
Procurement sophistication and service integration expectations separate fragmented industrial buyers from concentrated defense contractors.
- Defense:Long-term service contracts lock in replacement part revenue through proprietary diagnostic protocols and depot-level maintenance requirements. US Department of Defense platforms and European NATO procurement sustain multi-decade supplier relationships.
- Manufacturing:German automotive press manufacturers now unbundle valve procurement from maintenance contracts, instead subscribing to third-party IIoT predictive analytics platforms. This behavioral shift compresses OEM service margins and forces diagnostic protocol openness.
- Oil & Gas:EPA Clean Water Act spill containment enforcement drives replacement of legacy valve fleets with low-leakage cartridge designs in Gulf Coast processing facilities.
- Robotics:Collaborative robot joint actuation and exoskeleton force feedback systems specify miniature servo valves with reduced power-to-weight ratios.
Integrated service relationships dominate defense procurement. Disaggregated purchasing is spreading fastest among German manufacturing equipment buyers.
Technology:
Energy transmission medium determines power density, maintenance burden, and regulatory exposure.
- Hydraulic:Mineral oil-based systems deliver the highest force density for metal forming and flight control, with REACH restrictions on hazardous substances accelerating bio-based synthetic fluid adoption compatible with advanced sealing materials.
- Electronic:Direct-drive electromechanical actuation eliminates fluid maintenance entirely, displacing hydraulic servo systems in sub-50 kW industrial positioning where ISO 4406 cleanliness compliance proves prohibitive.
- Pneumatic:Compressed air systems serve low-force, high-speed packaging and material handling where precision requirements remain modest.
- Hybrid:Electro-hydrostatic actuation combines electric motor drive with localized hydraulic pressure generation, emerging in next-generation aircraft secondary flight controls.
Established infrastructure favors hydraulic deployment in heavy-force applications. Electromechanical substitution is advancing most rapidly in precision manufacturing below 50 kW.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in German and Japanese precision manufacturing clusters, while consumption spreads across aerospace centers in the United States and industrial automation corridors in China. The report tracks how regulatory divergence across these geographies is fragmenting product specifications and compliance architectures.
United States
Aerospace OEMs in Seattle and Wichita drive procurement of flight control actuation systems with FAA certification requirements. The EPA enforces hydraulic fluid spill containment under Clean Water Act provisions, elevating liability exposure for Gulf Coast processing facilities. Manufacturing clusters in Texas and Ohio are retrofitting metal forming equipment with closed-loop servo hydraulics.
Germany
Automotive press manufacturers in Stuttgart and Munich require high-response solutions for battery assembly and electric drivetrain production. The EU F-Gas Regulation tightens permissible fluorinated gas emissions, compelling sealing architecture redesigns. Industrial automation clusters in Bavaria and Baden-Württemberg are migrating toward low-leakage hydraulic architectures.
China
Domestic manufacturers in Jiangsu and Guangdong provinces retrofit injection molding equipment with closed-loop positioning to meet energy efficiency mandates. The country's dual carbon goals reshape material selection for valve bodies and electromagnetic coils. Yangtze River Delta production facilities are expanding precision motion control procurement for electrified manufacturing lines.
Japan
METI's Top Runner program promotes energy-efficient fluid power, creating asymmetric compliance costs for exporters serving Japanese OEMs. Specialty steel alloy suppliers in Nagoya and Osaka anchor precision spool manufacturing inputs. Chubu region industrial clusters specify miniature servo valves for collaborative robot joint actuation systems.
France
Aerospace tier-one suppliers in Toulouse qualify 3D-printed valve bodies for non-flight-critical actuation, compressing prototyping cycles. EASA airworthiness requirements freeze design iterations for 18-36 months, elevating certification burdens. Île-de-France defense contractors sustain long-term service contracts through proprietary diagnostic protocols.
Servo Valves Market Competitive Environment
The competitive structure tilts toward vertically integrated specialists with captive precision manufacturing capabilities. Three tiers separate aerospace-certified suppliers with multi-decade certification relationships from industrial automation vendors competing on commissioning speed and field service density. Dominant competitive moves include backward integration into specialty alloy supply and strategic unbundling of predictive maintenance subscriptions from hardware procurement.
Among US-based precision motion control specialists, Moog and Eaton Corporation occupy positions within the aerospace-defense tier, where certification scarcity sustains premium positioning. Parker Hannifin anchors the industrial automation vector through in-house production of precision spool components. Japanese specialists Yuken Kogyo and Daikin Industries exemplify the Asia-Pacific manufacturing cluster, representing regional supply concentration for high-response hydraulic architectures.
| Leading Market Players |
|---|
| Moog |
| Parker Hannifin |
| HAWE Hydraulik |
| Honeywell International |
| Eaton Corporation |
| Yuken Kogyo |
| Daikin Industries |
| Duplomatic MS |
| Domin |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between aerospace-qualified and industrial-grade servo valves manifests in divergent pricing architectures and supply chain configurations. EASA and FAA certification cycles spanning 18-36 months prop pricing premiums for flight control actuation systems, while commodity industrial positioning valves compete on field service density and commissioning speed. This tier divergence concentrates precision spool manufacturing in German and Japanese metallurgical clusters, with uncertified industrial variants sourcing from distributed Asian machine shops.
Pricing Analysis
Margin tightening in industrial automation traces to German automotive OEMs unbundling hardware procurement from maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace units from ISO 4406-compliant industrial valves and uncertified proportional alternatives. Cost-down pressure on standard-tier products accelerates because Chinese injection molding retrofitters prioritize per-unit economics over predictive diagnostics. Battery assembly line integrators exhibit highest price sensitivity, while defense contractors locked in long-term service agreements show least.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty steel alloy suppliers anchoring precision spool manufacturing. Production draws from Nagoya metallurgical clusters, Baden-Württemberg precision machining corridors, and Jiangsu province valve assembly facilities. Torque motor electromagnetic coil winding depends on rare earth processing concentrated in Chinese refining operations. Tariff exposure on specialty steel imports threatens margin stability for European valve assemblers. Distribution runs through aerospace tier-one suppliers, industrial automation OEMs, and aftermarket service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo valve supply remains constrained by aging technician populations concentrated in US and German torque motor calibration expertise, propping pricing power for incumbents with captive electromechanical assembly capabilities.
For Market Incumbents: Anticipate electromechanical substitution in sub-50 kW industrial positioning by deepening backward integration into precision spool manufacturing and securing long-term offtake agreements with Japanese specialty steel suppliers. Lock in replacement part revenue through proprietary diagnostic protocols before third-party IIoT platforms commoditize predictive maintenance.
For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for low-leakage sealing architecture specialists to penetrate German automotive press manufacturer procurement. White-space targets include Chinese Jiangsu province injection molding retrofits and collaborative robot joint actuation systems. Go-to-market angle: field-reconfigurable digital valve gain settings reducing commissioning downtime for mid-tier automation integrators.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated precision motion control specialists given accelerating aerospace platform modernization and defense procurement expansion. Long-term viability favors suppliers with captive EASA certification relationships and in-house electromagnetic coil production. Watch for inflection in Chinese dual carbon goal enforcement reshaping material selection mandates for valve bodies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive supply of precision spool alloys insulates margin from Japanese supplier concentration risk. |
| Digital Valve Microprocessor Integration | Embedded diagnostics enable predictive maintenance subscriptions competing with third-party IIoT platforms. |
| EASA Certification Pathway Investment | Airworthiness approval sustains premium positioning in flight control actuation procurement. |
| Low-Leakage Sealing Architecture Development | EU F-Gas compliance positions suppliers for German automotive and industrial automation retrofit demand. |
| Electro-Hydrostatic Actuation R&D | Hybrid architectures address next-generation aircraft secondary flight control displacement threats. |
Study Parameters
Multi-period observation of aerospace procurement cycles, industrial automation retrofit rates, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with maintenance directors at German automotive press manufacturers, plant engineers at Chinese injection molding facilities, aftermarket service heads at US defense contractors, and OEM procurement teams at aerospace tier-one suppliers. Secondary validation drew from EASA airworthiness filings, EPA Clean Water Act enforcement records, EU F-Gas Regulation implementation guidance, and METI Top Runner program documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, application environment, end-user procurement sophistication, and underlying fluid power technology informed the analytical framework throughout the projection horizon. Aerospace certification burden, industrial energy efficiency mandate compliance cost, and electromechanical substitution elasticity served as industry-specific forecast inputs. CAGRs derived from installed base turnover modeling and replacement cycle compression in Chinese manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for direct-drive electromechanical actuation would alter the outlook for hydraulic servo valve demand in sub-50 kW applications. Deviation in EU F-Gas Regulation enforcement stringency or Chinese dual carbon goal implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Fin Tube Market
Valves
Sandblast Valves Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Global Solenoid Valves Market
Valves
Diaphragm Valve Market
Valves
Actuators and Valves Market
Valves
Global Globe Valve Market
Valves
Angle Opening Ball Locator Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Liner Regulators Market
Valves
Manual Control Valve Market
Valves
Global Valves Market
Valves
Valve Seat Inserts Market
Valves
Backflow Preventers Market
Valves
North America Industrial Valves Market