
 Global Valve Positioners Market | 2026-2036
Global Valve Positioners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Valve Positioners Market Outlook
The gap between premium smart positioners and commodity pneumatic units is rebalancing as end-users weigh total cost of ownership against upfront capital constraints. Emerson Electric Co. leverages its digital valve controller portfolio to dominate high-specification projects in LNG and hydrogen infrastructure. SAMSON AG anchors its position through deep specialization in severe-service applications across European chemical complexes. Baker Hughes competes aggressively in the Middle East through integrated valve and positioner packages tied to large EPC contracts.
A valve positioner is a control device that interfaces with an actuator to ensure precise valve stem positioning in response to a control signal, typically operating with input ranges of 4–20 mA or 3–15 psi and achieving positioning accuracy within 0.5% of span. Its primary purpose is to maintain process variables such as flow, pressure, and temperature within tight tolerances across continuous and batch operations. Smart technology leads in value contribution as diagnostic-enabled units command premium pricing and reduce unplanned shutdowns. Electronic positioners sustain faster growth than pneumatic alternatives in greenfield installations. Modulating type positioners occupy the deepest margin pools due to their complexity and criticality in loop control applications.
EPA methane regulations and the EU F-Gas Regulation are accelerating replacement demand by mandating lower emission intensities and tighter sealing standards across valve fleets. China's GB standards and SAMR certification requirements shape market access for imported positioners in petrochemical expansions along the eastern seaboard. ISO 9001 quality frameworks and IEC 61508 functional safety standards further stratify supplier eligibility for safety instrumented systems. Stakeholders must monitor how hydrogen service compatibility and digital twin integration reshape specification criteria before the next procurement cycle consolidates.
Market Dynamics
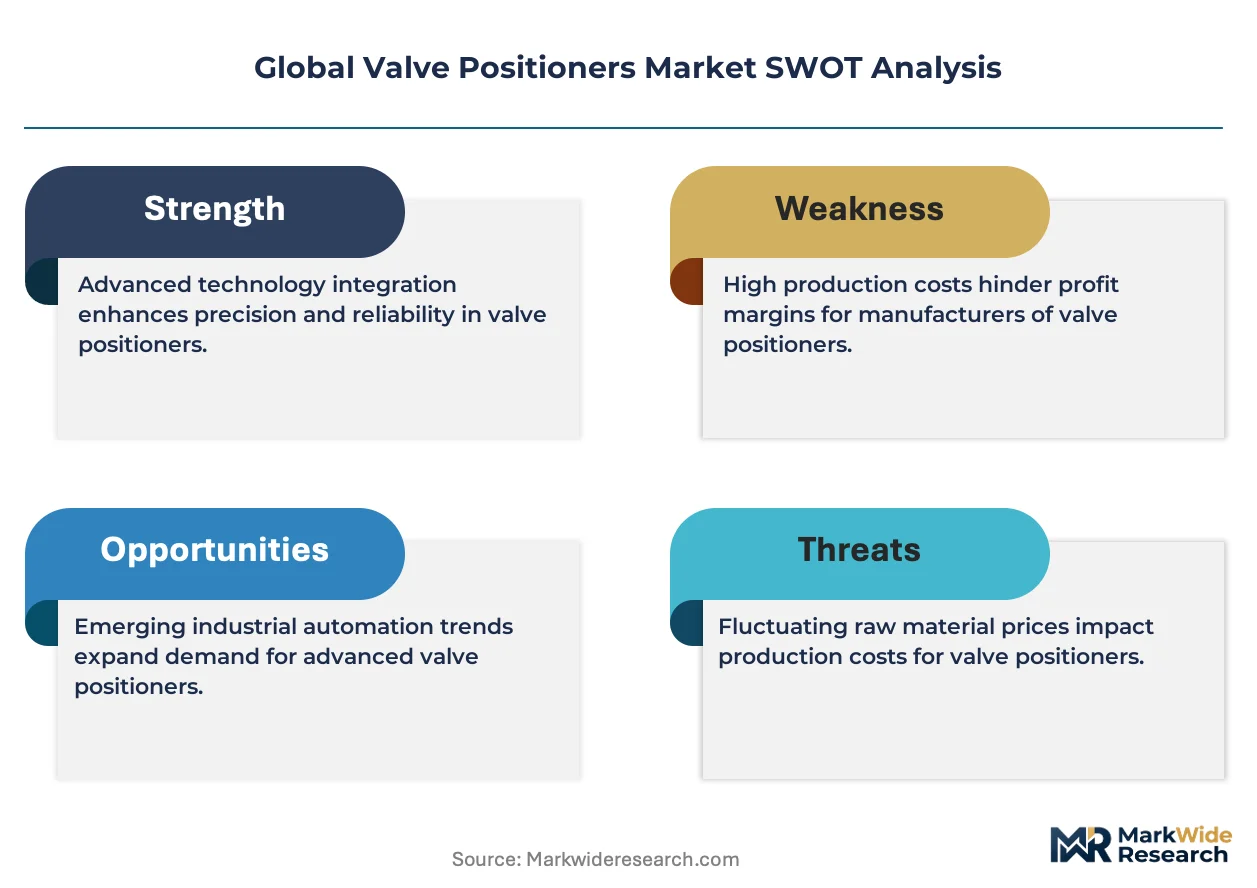
The valve positioners market is undergoing a fundamental rebalancing as fugitive emission regulations force accelerated replacement cycles across installed bases, while smart diagnostics compress the total cost-of-ownership gap versus legacy pneumatic units.
Growth Catalysts
- EPA methane rules:Tightening fugitive emission standards in the United States are compelling upstream oil and gas operators to retire legacy pneumatic positioners ahead of schedule, creating replacement pull across the Gulf Coast petrochemical corridor.
- Smart diagnostic integration:Positioners with embedded HART and Foundation Fieldbus protocols are reducing unplanned shutdowns in continuous process operations, justifying premium positioning in hydrogen and LNG infrastructure specifications.
- EU F-Gas Regulation:The European framework mandating lower emission intensities is accelerating retrofit demand across Germany's Rhine-Ruhr chemical cluster and comparable industrial zones.
Market Restraints
- Stainless steel input volatility:Fluctuations in specialty alloy pricing compress margins for severe-service positioner manufacturers serving high-temperature catalytic cracking units.
- Supply concentration in semiconductor components:Reliance on concentrated Asian sources for microcontrollers and sensor chips creates vulnerability in electronic positioner production schedules.
- Pneumatic unit residual preference:Explosion-risk environments in certain chemical processing segments maintain specification inertia toward non-electronic actuation despite smart unit advantages.
Strategic Opportunities
- Hydrogen service certification:Positioners rated for high-pressure hydrogen embrittlement resistance are capturing specification slots in emerging European and Middle Eastern hydrogen export infrastructure.
- Digital twin integration:Valve positioners with native asset performance management APIs are enabling predictive maintenance contracts that unbundle hardware from lifecycle service revenue.
- China's eastern seaboard expansions:Petrochemical capacity additions along the Yangtze River Delta are creating demand for SAMR-certified smart positioners among international suppliers.
Industry Challenges
- IEC 61508 functional safety certification timelines:The protracted validation processes for safety instrumented system positioners delay market entry and compress product refresh windows.
- Legacy control system integration:Retrofitting smart positioners into existing 4–20 mA analog loops without distributed control system upgrades requires complex signal conditioning and creates commissioning friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Valve Positioners Market |
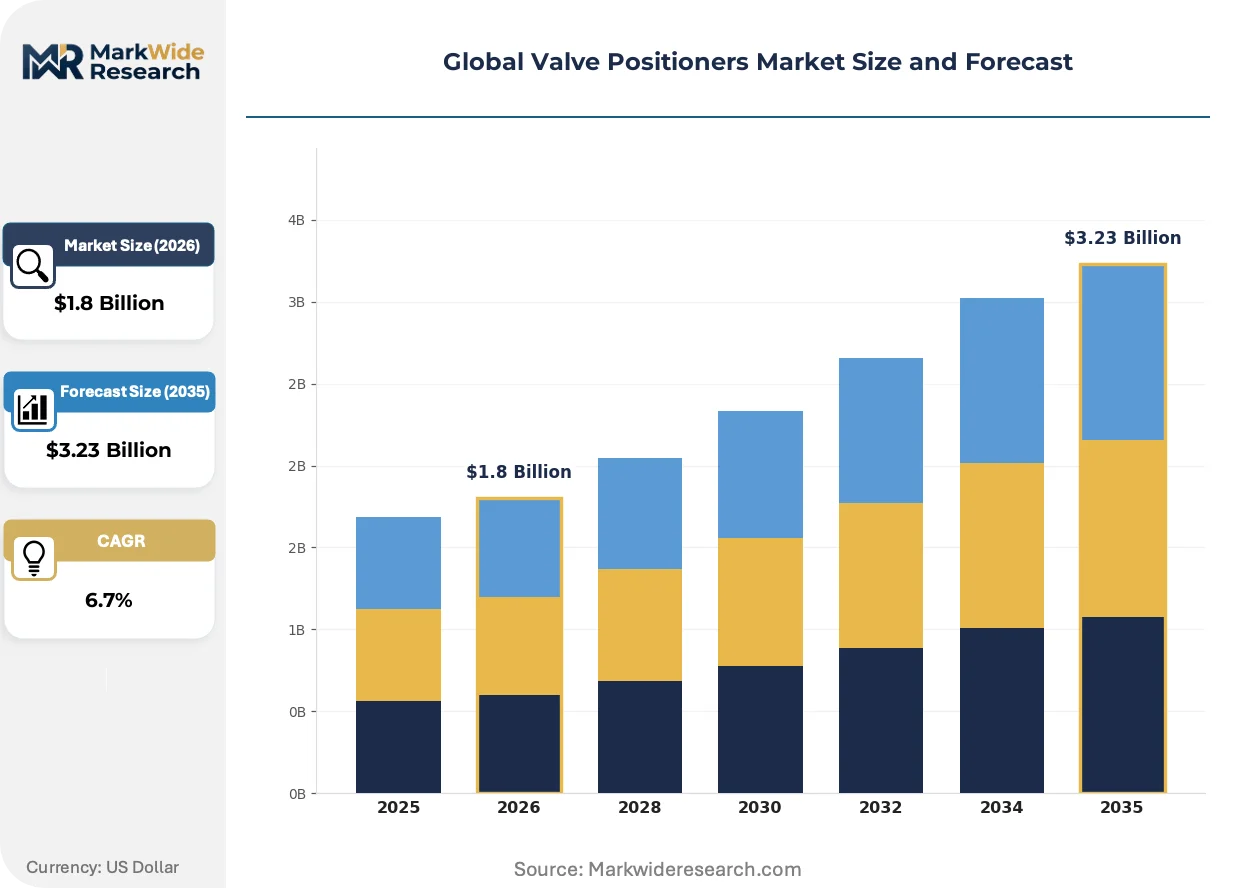
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pneumatic, Electronic, Hydraulic, Smart Type: On-Off, Modulating, Digital, Analog End User: Oil & Gas, Water & Wastewater, Power Generation, Chemicals Installation: Field Mounted, Remote Mounted, Panel Mounted, Integrated |
| Companies Covered | Flowserve Corporation, Azbil Corporation, Emerson Electric Co., Rotork plc, Baker Hughes, ABB, Schneider Electric, SAMSON AG, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Valve Positioners Market Strategic Shifts
Wireless communication protocols and edge-computing diagnostics are reconfiguring how positioners interface with plant asset management systems, compressing the distinction between field device and data node.
Embedded HART-IP and WirelessHART modules are consolidating valve positioner architecture by eliminating separate position transmitters and reducing wiring density in greenfield installations. LNG terminal operators and hydrogen liquefaction facilities are specifying these integrated units to simplify loop commissioning. The technology is consolidating supplier value chains as diagnostics software becomes the primary differentiation layer.
The EU F-Gas Regulation and parallel EPA methane enforcement are tightening sealing standards across valve fleets, forcing positioner manufacturers to redesign pneumatic circuits and feedback mechanisms for lower bleed rates. Chemical processors in Germany and the Netherlands are now specifying positioners with certified low-emission packing systems as procurement prerequisites. This regulatory pressure is compressing the viable lifespan of non-compliant legacy units.
After-sales service unbundling is reshaping how end-users contract for positioner maintenance, with operating companies separating hardware procurement from predictive analytics subscriptions. Refinery operators on the United States Gulf Coast are piloting performance-based contracts where diagnostics providers retain ownership of positioner firmware and algorithm updates. This model is concentrating service revenue with specialized software vendors.
Global Valve Positioners Market Segmentation
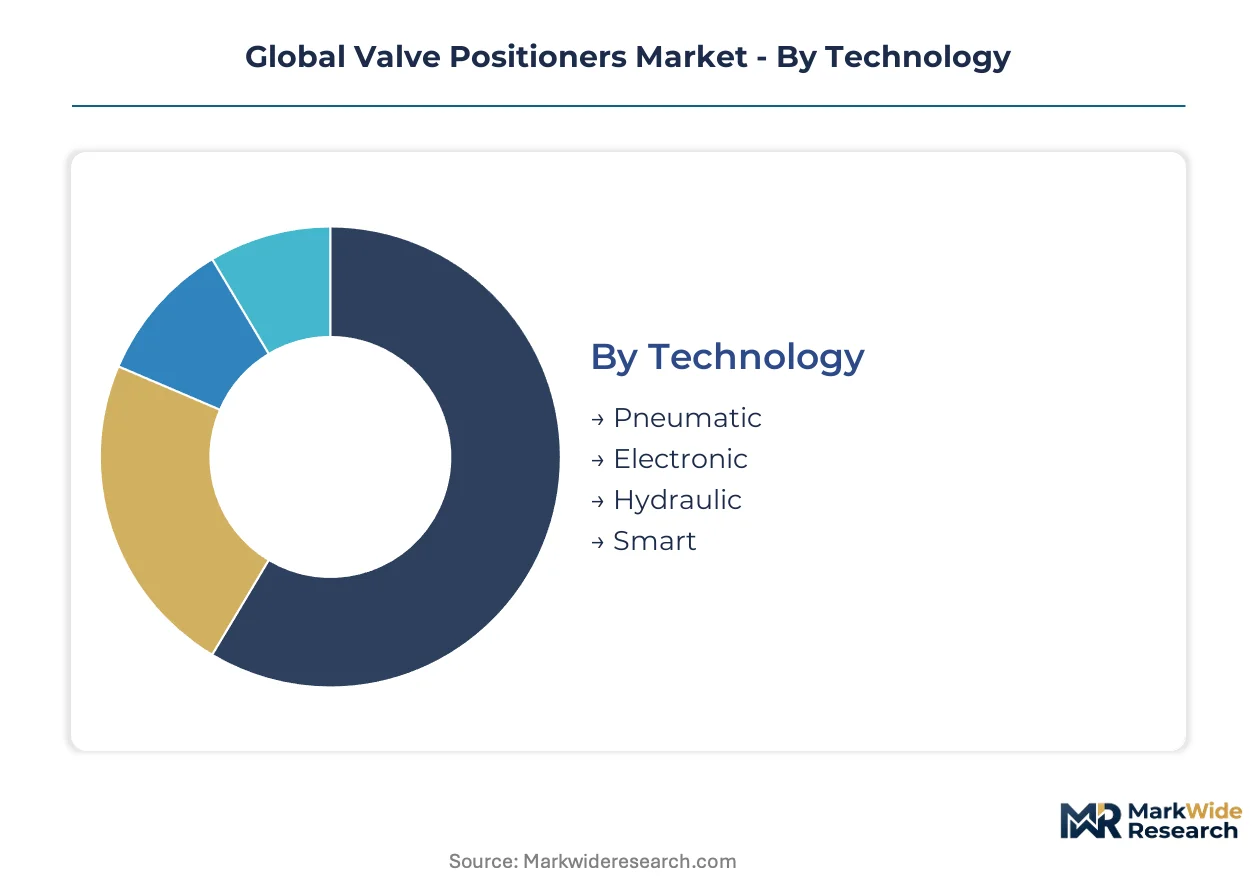
Valve positioner segmentation reveals how technology tiers map to capital intensity and lifecycle economics across process industries. Understanding these splits guides procurement strategy for both greenfield specifications and retrofit cycles.
Technology:
Smart technology commands premium positioning while pneumatic units retain volume dominance in legacy infrastructure.
- Smart:Embedded HART and Foundation Fieldbus protocols enable predictive diagnostics and unplanned shutdown reduction. Demand concentrates in United States Gulf Coast LNG terminals and European hydrogen export hubs where EPA methane rules and EU F-Gas Regulation mandate emission-compliant retrofits.
- Electronic:Microcontroller-based positioning achieves faster response times than pneumatic alternatives with 4–20 mA signal compatibility. Greenfield chemical complexes in China's Yangtze River Delta specify these units for SAMR-certified installations ahead of pneumatic legacy preferences.
- Pneumatic:Compressed air-actuated units persist in explosion-risk environments where electrical certification costs outweigh smart diagnostic benefits.
- Hydraulic:High-force actuation for severe-service valves in catalytic cracking and hydroprocessing units requiring thrust beyond pneumatic or electronic capacity.
Today's leader: Pneumatic. Tomorrow's challenger: Smart.
Type:
Application complexity determines margin structure, with continuous control applications sustaining deeper margin pools than discrete switching.
- Modulating:Continuous throttling control for flow, pressure, and temperature loops demands precise positioning accuracy within 0.5% of span. Refinery fluid catalytic crackers and ethylene steam crackers specify these units for loop-critical service where deviation tolerance is tightest.
- On-Off:Binary positioning for isolation valves prioritizes fail-safe speed over precision. Water treatment facilities and pipeline block valve stations favor these simpler actuation packages for lower total installed cost.
- Digital:Native digital communication protocols eliminate analog signal conversion losses in distributed control system architectures.
- Analog:3–15 psi or 4–20 mA signal compatibility maintains relevance for brownfield retrofits avoiding control system replacement.
Modulating units extract the steepest pricing premiums. Digital architectures are climbing fastest in greenfield specifications.
End User:
Regulatory exposure and asset intensity create divergent procurement patterns across verticals.
- Oil & Gas:Upstream pneumatic replacement cycles and midstream compressor station automation drive specification volume. EPA methane enforcement accelerates smart positioner adoption across Permian Basin and Bakken Shale operations.
- Chemicals:Batch and continuous process loops demand high-availability positioning with IEC 61508 functional safety certification. Germany's Rhine-Ruhr cluster and Netherlands Antwerp-Rotterdam chemical corridor specify severe-service units for high-temperature catalytic processes.
- Power Generation:Steam turbine bypass and feedwater regulation applications require fast-stroking positioners for load-following flexibility.
- Water & Wastewater:Municipal treatment plants prioritize cost-minimization over diagnostic sophistication in actuation specifications.
Oil & Gas anchors current procurement volume. Chemicals present the steepest technology upgrade trajectory.
Installation:
Mounting configuration reflects site constraints, maintenance accessibility, and integration depth with valve-actuator packages.
- Field Mounted:Direct attachment to valve yoke or actuator housing exposes electronics to ambient temperature cycling and vibration. Offshore platforms and desert refining sites specify ruggedized enclosures for these exposed installations.
- Remote Mounted:Positioner separation from valve via tubing or cable allows mounting in controlled environments away from extreme temperatures or radiation zones. Nuclear power containment areas and cryogenic LNG service favor this configuration for electronics protection.
- Panel Mounted:Centralized rack installation for manifold valve assemblies in analyzer houses and instrument air distribution skids.
- Integrated:Factory-assembled valve-positioner-actuator packages from single suppliers streamline commissioning and warranty coverage.
Field mounted dominates retrofit activity. Integrated packages are gaining fastest in EPC-led greenfield construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr chemical corridor outpaces United States Gulf Coast retrofit intensity, while China's Yangtze River Delta expansion absorbs the largest share of new smart positioner installations.
United States
Upstream oil and gas operators in the Permian Basin and Bakken Shale are retiring legacy pneumatic positioners ahead of schedule. EPA methane enforcement is compelling these replacements across compressor stations and wellhead facilities. The Gulf Coast petrochemical corridor from Houston to Corpus Christi is specifying HART-enabled diagnostics for LNG export terminal automation.
Germany
Chemical processors in the Rhine-Ruhr industrial cluster demand severe-service positioners for high-temperature catalytic cracking units. The EU F-Gas Regulation is accelerating retrofit cycles with mandated lower emission intensities. BASF and Bayer complexes in Ludwigshafen and Leverkusen are specifying IEC 61508-certified units for safety instrumented systems.
China
Petrochemical capacity additions along the Yangtze River Delta are creating demand for SAMR-certified smart positioners. GB standards and national certification requirements are shaping market access for imported units. Sinopec and PetroChina refineries in Shanghai and Ningbo are prioritizing electronic positioners with native digital communication protocols.
Saudi Arabia
Integrated valve and positioner packages are dominating Aramco-led megaprojects across the Eastern Province. The country's national hydrocarbon regulator is tightening fugitive emission standards for upstream facilities. Jubail Industrial City and Ras Al-Khair are emerging as concentration points for hydrogen export infrastructure specifications.
Netherlands
The Antwerp-Rotterdam chemical corridor is specifying low-emission packing systems as procurement prerequisites. REACH compliance and EU Green Deal alignment are filtering supplier eligibility for safety-critical applications. Shell and Dow facilities in Rotterdam are piloting digital twin integration for predictive maintenance contracts.
Global Valve Positioners Market Competitive Environment
Top-tier vendors anchor high-specification LNG and hydrogen infrastructure projects, while mid-tier specialists capture severe-service niches in European chemical complexes. The market structure stratifies across three tiers: diversified industrial conglomerates with full automation portfolios, dedicated valve control specialists with deep application expertise, and regional fabricators serving cost-sensitive municipal and water segments. Strategic archetypes include diagnostic-integrated solution providers, severe-service material specialists, and integrated valve-actuator-package suppliers. M&A activity is consolidating adjacent sensing and analytics capabilities, while geographic expansion into China's eastern seaboard dominates capacity allocation decisions.
Within the diversified industrial tier, Emerson Electric Co. and ABB exemplify full-portfolio automation vendors with integrated digital valve controller offerings. Siemens anchors the European premium segment through its process automation division. SAMSON AG occupies a distinct position as a family-owned German specialist with concentrated expertise in severe-service chemical applications. Baker Hughes represents the integrated energy technology archetype, bundling positioners with rotating equipment and valve packages for Middle Eastern EPC contracts. Azbil Corporation and Rotork plc sit within the dedicated motion control specialist tier, with the latter's London-listed structure signaling Anglo-American market orientation.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Azbil Corporation |
| Emerson Electric Co. |
| Rotork plc |
| Baker Hughes |
| ABB |
| Schneider Electric |
| SAMSON AG |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Family-owned German specialists and private-equity-rolled-up motion control portfolios anchor supply-side discipline, translating certification depth into pricing power across severe-service chemical applications and resisting commoditization through embedded diagnostics bundling.
Pricing Analysis
The bundled-vs-unbundled service split stratifies valve positioner economics. Three-tier pricing structure across premium, standard, and economy levels separates HART-enabled diagnostic units from basic electronic positioners and legacy pneumatic alternatives. Price differentiation hinges on IEC 61508 functional safety certification grade and after-sales predictive analytics subscription attach rates. Cost compression in economy-tier pneumatic units is intensifying because stainless steel input volatility squeezes margin buffers. Municipal water treatment buyers exhibit highest price sensitivity, while LNG terminal operators prioritize total cost-of-ownership over upfront capital.
Supply Chain Analysis
Certification/qualification gating concentrates qualified supplier pools around Germany, the United States, and Japan for severe-service applications. Production draws from specialty alloy foundries in Germany's Rhine-Ruhr cluster, semiconductor component sources in Taiwan and South Korea, and precision machining capacity across Japan's industrial belt. Single-source vulnerability in microcontroller supply creates schedule risk for electronic positioner manufacturers. Distribution runs through EPC contractor specification channels for greenfield projects and aftermarket service networks for retrofit cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The valve positioners market functions as a stable compounder, with regulatory-mandated replacement cycles providing predictable demand visibility regardless of broader industrial capital expenditure volatility.
For Market Incumbents: Anticipate margin compression from Asian electronic component suppliers by deepening captive supply of severe-service alloy castings and securing long-term semiconductor allocation agreements. Prioritize IEC 61508 certification maintenance as safety instrumented system specifications tighten. Defensive consolidation around predictive maintenance software capabilities will differentiate against hardware commoditization. For New Entrants and Emerging Players: Direct-to-end-user digital sales channels bypass entrenched EPC specification gatekeepers and enable pilot program traction with independent refiners. Target hydrogen service certification gaps in European export infrastructure as the most penetrable white space. Lead with API-native positioners for digital twin integration contracts to establish referenceability before scaling. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking diagnostic software capabilities to complement hardware portfolios. Five-to-ten-year viability rests on hydrogen infrastructure buildout trajectory and regulatory enforcement consistency. Monitor EPA methane rule implementation pace as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Service Certification Investment | Positions suppliers for European and Middle Eastern hydrogen export hub specifications. |
| Backward Integration into Alloy Casting | Secures margin control against specialty steel price volatility in severe-service production. |
| Predictive Maintenance Platform Launch | Enables recurring revenue unbundling from hardware sales for refinery operators. |
| Joint Venture with Chinese SAMR-Certified Partner | Accelerates market access for Yangtze River Delta petrochemical expansions. |
| WirelessHART Module Integration | Consolidates transmitter architecture for LNG terminal greenfield specifications. |
Study Parameters
Direct dialogue with plant maintenance directors, EPC specification engineers, valve OEM procurement teams, and aftermarket service heads combined with secondary validation through SEC 10-K filings, customs trade databases, IEC certification registries, and petrochemical project announcement tracking. Bottom-up and top-down triangulation cross-checks unit shipment estimates against capital expenditure disclosures and regulatory compliance timelines.
Bottom-up modeling aggregates segment-level demand across technology tiers, end-use verticals, and installation configurations, while top-down verification benchmarks against regional industrial production indices and energy infrastructure investment flows. CAGRs derive from regression analysis of historical replacement cycles, regulatory phase-in schedules, and greenfield project pipelines. Hydrogen infrastructure buildout assumptions and F-Gas Regulation enforcement intensity represent critical forecast sensitivities.
The model assumes a particular technology adoption path; alternative pathways for wireless diagnostic protocols would alter the outlook. Forecasts reflect assumptions around regulatory enforcement consistency, commodity input stability, and semiconductor supply normalization. A model refresh is warranted upon material change in EPA methane rule implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Electronic Expansion Valves Market
Valves
Air Heated Vaporizer Market
Valves
Diaphragm Valve Market
Valves
Electro Pneumatic Positioner Market
Valves
Hot Blast Valves Market
Valves
Global Globe Valve Market
Valves
Harmonic Dampers Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Battery Safety Valve Market
Valves
Global Stainless Steel Control Valves Market
Valves
Servo Valves Market
Valves
Europe Butterfly Valve Market
Valves
Gas Equipment Market
Valves
Rising Stem Ball Valve Market
Valves
Liner Regulators Market
Valves
Orifice Reducers Market