
 Valve Seat Inserts Market | 2026-2036
Valve Seat Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Seat Inserts Market Outlook
The capital-intensity divergence between integrated powder metallurgy specialists and conventional casting houses is unwinding competitive hierarchies in valve seat insert supply. MAHLE leverages captive sintering capacity to anchor premium OEM contracts across European powertrain platforms. Tenneco competes through high-volume steel insert production for light-duty aftermarket channels. Eaton Corporation differentiates via proprietary copper-nickel alloy formulations targeting natural gas engine thermal loads.
Valve seat inserts are precision-engineered annular components, typically fabricated from sintered iron-based powders, cobalt-chrome alloys, or bronze matrices, that press-fit into cylinder head recesses to provide a durable sealing surface against valve faces under cyclic combustion pressures exceeding 150 bar. Their primary industrial purpose centers on maintaining combustion chamber integrity, thermal conductivity management, and valve recession control across millions of operating cycles in internal combustion and alternative fuel engines. Steel inserts dominate automotive OEM volume given cost scalability and established stamping-to-sintering process economics, while bronze formulations command aftermarket margin pools in marine and stationary power applications where corrosion resistance outweighs unit cost sensitivity. Conical seat geometries are displacing flat configurations in aerospace turbine applications as engine manufacturers seek optimized gas flow dynamics at elevated operating temperatures.
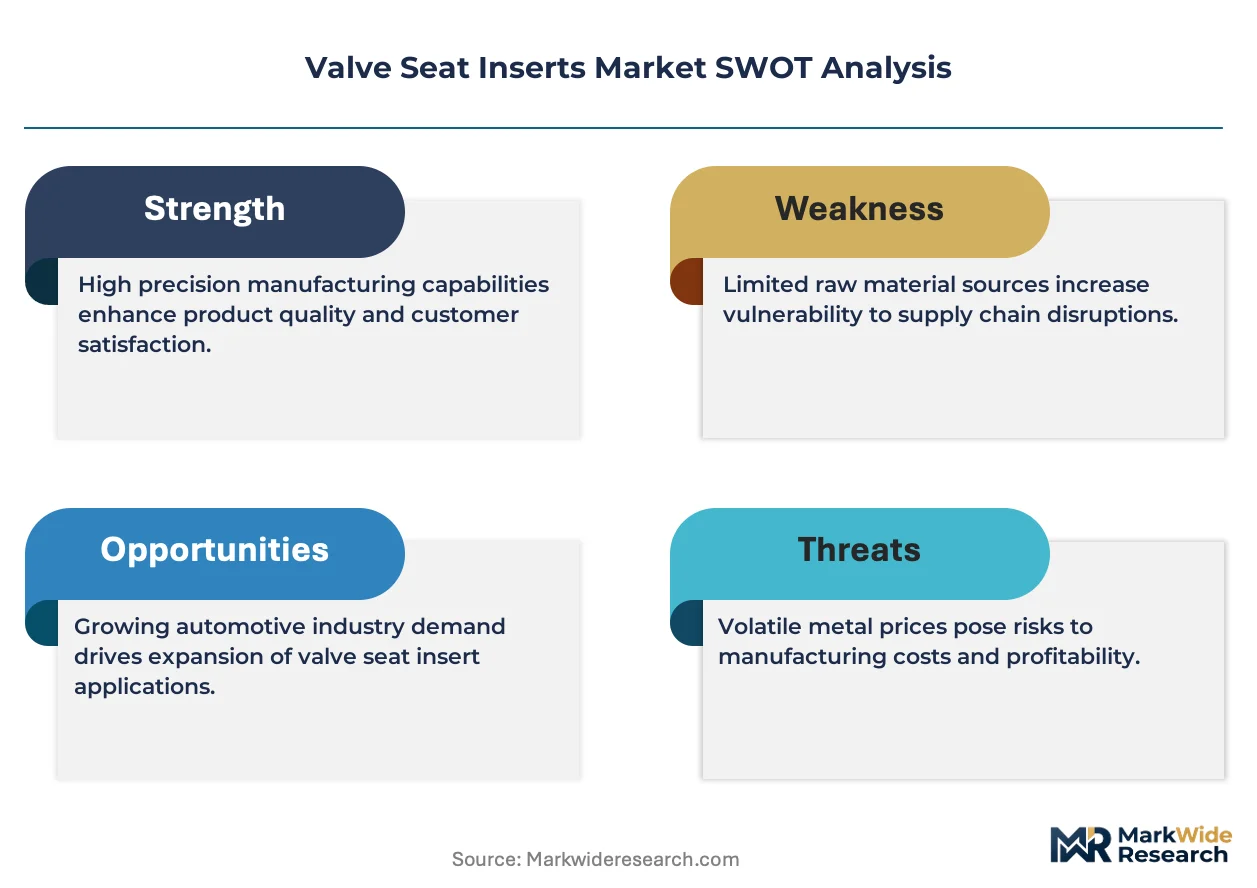
EPA tailpipe standards and Euro Stage V/VI emissions frameworks compel OEMs to specify higher-grade seat materials capable of withstanding elevated exhaust gas recirculation rates and prolonged lean-burn conditions. China's MIIT fuel consumption mandates and India's BIS automotive component certification protocols are synchronizing material specification convergence across export-oriented supply chains. Stakeholders must monitor cobalt supply concentration in the Democratic Republic of Congo and corresponding SAMR stockpiling directives, as alloy cost volatility threatens margin structures in premium insert categories.
Market Dynamics
Powder metallurgy advances in cobalt-chrome alloys are compressing service intervals and rewiring procurement criteria for heavy-duty powertrain suppliers.
Growth Catalysts
- EPA Tier 4 and Euro Stage V mandates:Diesel engine OEMs are upgrading to sintered valve seat inserts to withstand elevated exhaust gas recirculation rates and prolonged lean-burn combustion cycles.
- Cobalt-chrome alloy sintering:High-compression natural gas engines require thermal conductivity management that bronze matrices cannot deliver, pulling demand toward advanced powder metallurgy formulations.
- Germany's commercial vehicle corridor:Stuttgart and Munich production clusters concentrate procurement volume from tier suppliers serving Mercedes-Benz and MAN powertrain platforms.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominance in raw cobalt extraction exposes alloy cost structures to SAMR stockpiling directives and export restriction volatility.
- Steel insert price floors:Conventional stamping-to-sintering economics for iron-based powders limit margin expansion in light-duty automotive OEM contracts.
- Flat seat geometry lock-in:Legacy cylinder head machining equipment constrains rapid adoption of conical seat configurations in aftermarket marine and stationary power channels.
Strategic Opportunities
- India's BIS certification convergence:Export-oriented suppliers can harmonize material specifications to serve both domestic automotive OEMs and European powertrain tier-1 procurement.
- Aerospace turbine thermal management:Conical seat geometries optimized for gas flow dynamics at elevated temperatures represent unpenetrated demand from jet engine manufacturers.
- Copper-nickel alloy natural gas specialization:Proprietary formulations targeting thermal loads in compressed natural gas engines create defensible niche positioning against commodity steel competitors.
Industry Challenges
- Powder metallurgy technician scarcity:Captive sintering operations require specialized furnace control expertise that conventional casting houses struggle to recruit.
- ISO 9001/IATF 16949 certification timelines:New entrants face 18-24 month validation cycles before qualifying for European commercial vehicle OEM supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Seat Inserts Market |
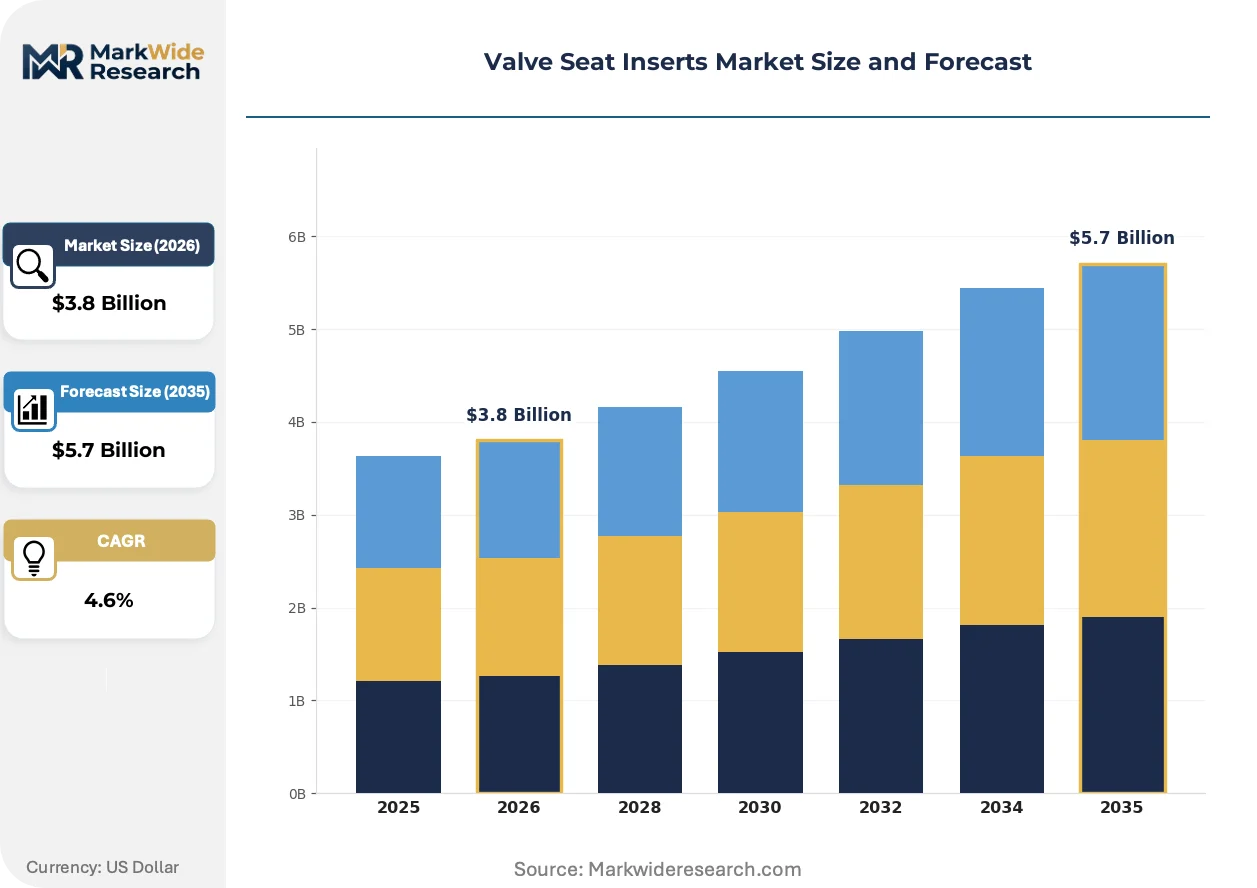
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Bronze, Others Application: Automotive, Aerospace, Marine, Industrial Form: Flat, Conical, Beveled, Others End User: OEMs, Aftermarket Providers, Repair Shops, Distributors |
| Companies Covered | Tenneco, AVL List, MAHLE, Mitsubishi Materials Corporation, L.E. Jones, Eaton Corporation, GKN Automotive, Nippon Piston Ring, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Seat Inserts Market Strategic Shifts
Material science convergence with emissions engineering is collapsing the traditional separation between thermal management components and combustion system design.
Additive manufacturing of cobalt-chrome valve seat preforms is miniaturizing grain structures to sub-10 micron uniformity, enabling direct net-shape sintering without secondary machining. Aerospace turbine OEMs are piloting these preforms for conical seat geometries in next-generation high-bypass engines. The technology is miniaturizing tolerance bands from ±25 microns to ±8 microns, compressing quality assurance cycles and reducing press-fit scrap rates.
REACH authorization requirements for cobalt compounds are forcing reformulation strategies across European powder metallurgy supply chains. Manufacturers must submit substitution plans for high-cobalt alloys by 2026 or face import restrictions. Germany-based tier suppliers are accelerating nickel-copper-tungsten development programs to maintain CE marking compliance for export markets.
Fleet operators are unbundling valve seat insert procurement from full engine rebuild contracts, creating direct aftermarket channels independent of OEM dealer networks. Independent distributors in marine and stationary power segments are capturing margin pools previously held by engine manufacturers. This pattern is most visible in North American natural gas compression and European inland waterway shipping, where vessel operators prioritize corrosion-resistant bronze formulations over unit cost minimization.
Valve Seat Inserts Market Segmentation
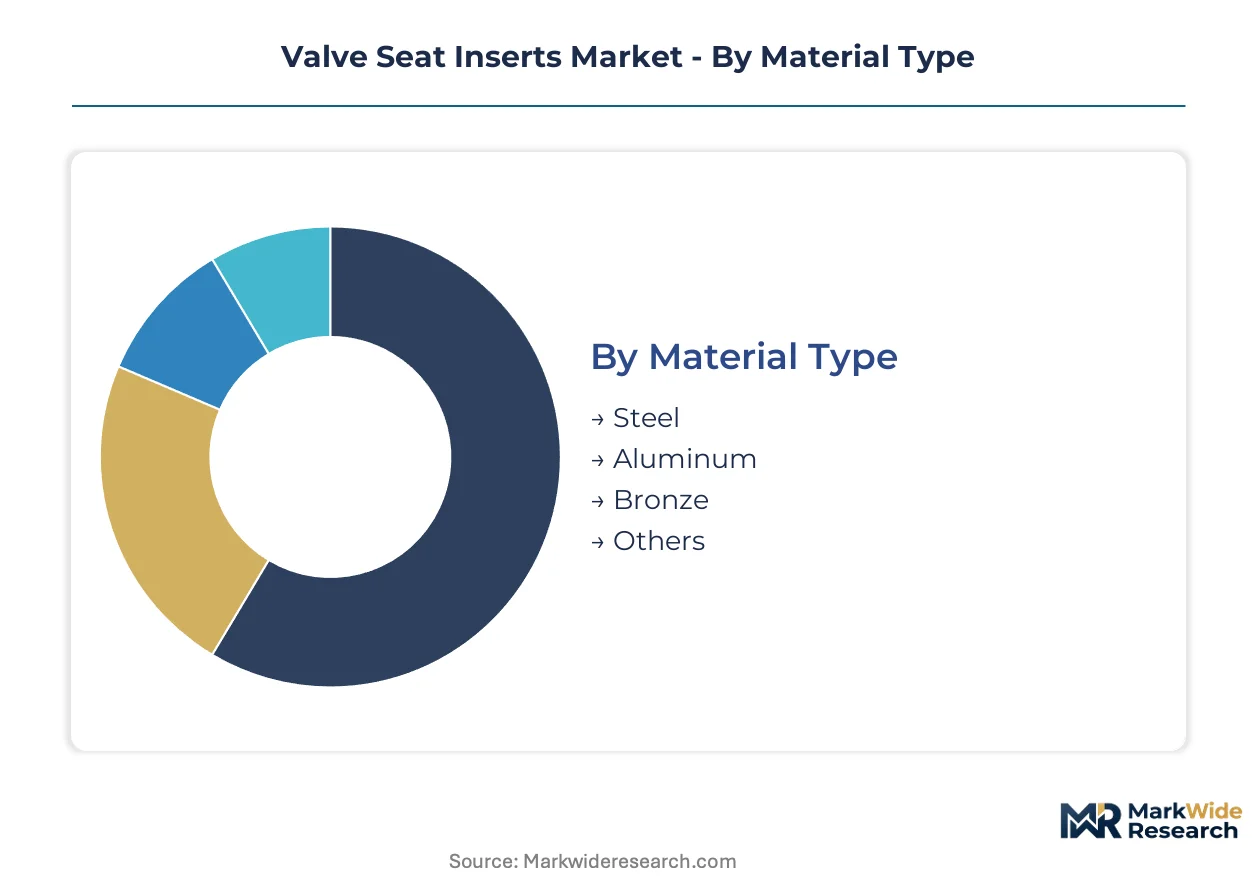
Valve seat insert procurement channels diverge sharply by material grade and thermal performance requirements. OEMs specify sintered alloys through tier-1 powertrain suppliers, while aftermarket channels favor bronze formulations for corrosion-critical marine and stationary applications.
Material Type:
Steel and bronze formulations dominate distinct channel tiers, with steel flowing through high-volume automotive OEM contracts and bronze capturing premium aftermarket margins in marine and corrosive environments.
- Steel:Iron-based sintered powders processed through stamping-to-sintering economics anchor light-duty automotive OEM volume. Stuttgart and Munich production corridors concentrate procurement from Mercedes-Benz and MAN powertrain platforms seeking EPA Tier 4 compliance.
- Bronze:Copper-tin matrices deliver superior corrosion resistance for marine propulsion and stationary natural gas compression where service intervals outweigh unit cost sensitivity. North American inland waterway operators and European canal shipping fleets specify bronze for saltwater exposure durability.
- Aluminum:Lightweight inserts serve niche aerospace turbine applications where thermal conductivity requirements are secondary to mass reduction.
- Others:Cobalt-chrome and nickel-copper-tungsten experimental alloys target REACH substitution mandates and high-compression natural gas engine thermal loads.
By volume, steel leads. By growth pace, bronze is ahead in marine aftermarket channels.
Application:
End-use thermal environments dictate alloy selection, with heavy-duty diesel and natural gas engines driving powder metallurgy upgrades while aerospace turbine OEMs pilot conical seat geometries.
- Automotive:Light-duty gasoline and diesel engines specify steel inserts through established tier-1 supply chains. Euro Stage V mandates are compressing procurement criteria toward sintered cobalt-chrome formulations capable of withstanding elevated exhaust gas recirculation rates.
- Aerospace:Jet engine manufacturers pilot additive-manufactured cobalt-chrome preforms for conical seat configurations in high-bypass turbines. Grain structures miniaturized to sub-10 micron uniformity enable tolerance bands of ±8 microns.
- Marine:Saltwater corrosion resistance drives bronze specification in propulsion and auxiliary power systems across European inland waterways and North American coastal shipping.
- Industrial:Stationary natural gas compression and power generation specify proprietary copper-nickel alloys for thermal load management in lean-burn combustion cycles.
Automotive captures the largest revenue pool. Aerospace exhibits the steepest expansion trajectory for advanced alloy development.
Form:
Seat geometry selection hinges on cylinder head machining equipment legacy versus gas flow optimization requirements, with conical configurations gaining share in aerospace and next-generation automotive designs.
- Flat:Legacy configurations dominate aftermarket marine and stationary power channels where cylinder head machining equipment constrains rapid geometry conversion. Repair shops and independent distributors stock flat seats for engine rebuild compatibility.
- Conical:Optimized gas flow dynamics at elevated temperatures drive adoption in aerospace turbine applications and high-performance automotive cylinder heads. Additive manufacturing enables direct net-shape sintering without secondary machining.
- Beveled:Intermediate geometry serves transitional engine platforms bridging flat legacy systems and conical next-generation designs.
- Others:Custom profiles address specialized thermal management requirements in natural gas and hydrogen combustion research programs.
Flat geometry retains installed base dominance. Conical configurations gain share fastest in OEM forward production.
End User:
Procurement authority is fragmenting as fleet operators unbundle valve seat insert purchasing from full engine rebuild contracts, creating direct aftermarket channels independent of OEM dealer networks.
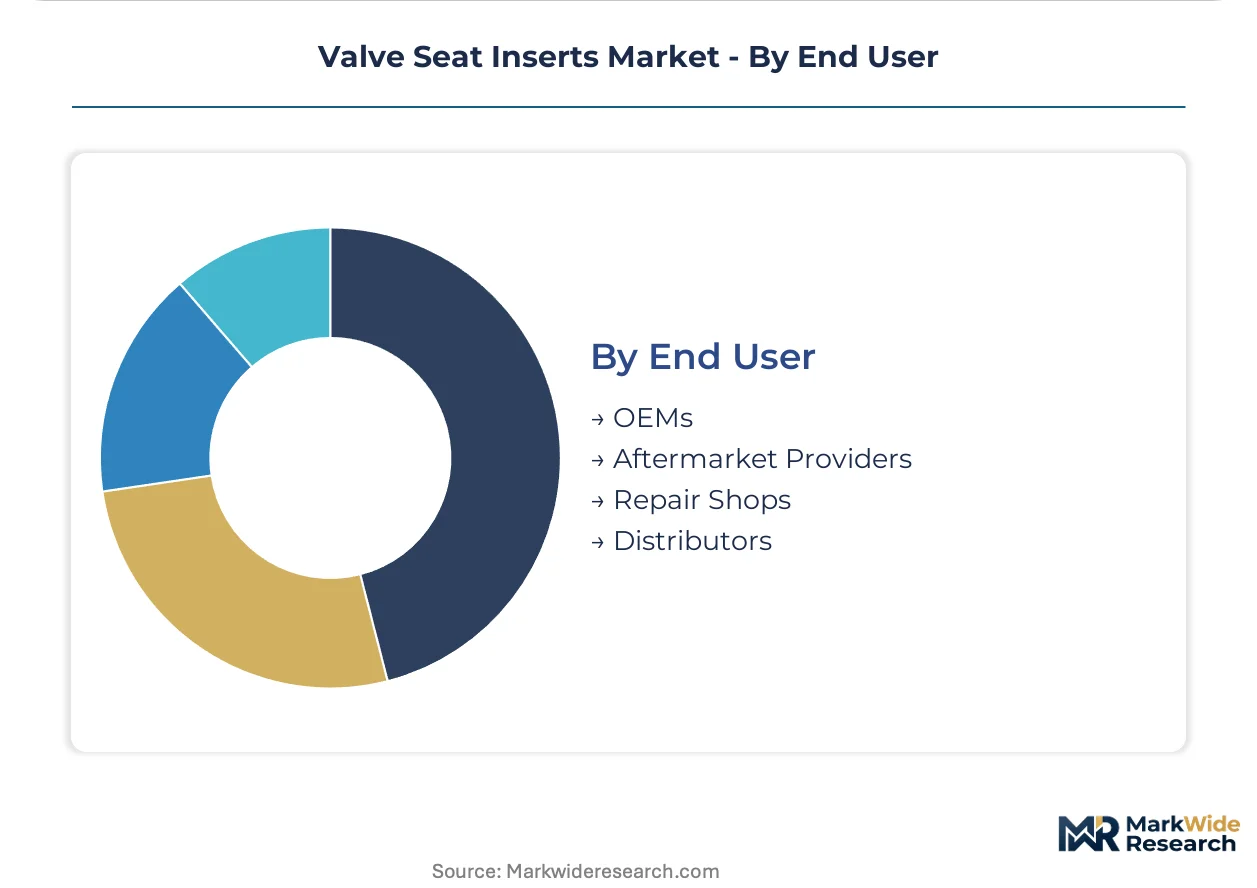
- OEMs:Mercedes-Benz, MAN, and other commercial vehicle manufacturers specify sintered alloys through captive tier-1 relationships. IATF 16949 certification requirements enforce 18-24 month supplier qualification timelines.
- Aftermarket Providers:Independent distributors in marine and stationary power segments capture margin pools previously held by engine manufacturers. Bronze formulations command premium positioning in corrosion-critical applications.
- Repair Shops:Legacy flat-seat inventory dominates rebuild economics, constraining geometry upgrade adoption in marine and industrial channels.
- Distributors:Inventory pooling across bronze and steel grades serves fragmented regional demand in European inland waterways and North American natural gas compression fleets.
OEMs anchor volume concentration. Aftermarket providers are expanding share fastest through fleet operator direct procurement unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in valve seat inserts track the geographic dispersion of heavy-duty engine manufacturing, with Germany and China running structural surpluses in sintered alloy components while the United States and India remain net importers of premium cobalt-chrome formulations.
Germany
Commercial vehicle OEM procurement concentrates demand for EPA Tier 4-compliant sintered inserts around Stuttgart and Munich production corridors. REACH authorization requirements for cobalt compounds are forcing MAHLE and tier suppliers to accelerate nickel-copper-tungsten development programs. The KBA enforces stringent component certification timelines that lock out unqualified Asian competitors.
United States
Natural gas compression fleets and marine operators drive bronze insert demand through independent aftermarket channels unbundled from OEM dealer networks. EPA tailpipe standards compel domestic engine rebuilders to source higher-grade seat materials for elevated exhaust gas recirculation rates. Houston and Gulf Coast industrial clusters concentrate procurement for stationary power applications.
China
MIIT fuel consumption mandates synchronize domestic material specifications with Euro Stage V export requirements for commercial vehicle powertrains. SAMR stockpiling directives on cobalt raw materials expose alloy cost structures to supply volatility. Yangtze River Delta manufacturing bases host powder metallurgy operations serving both domestic OEMs and European tier-1 procurement.
India
BIS automotive component certification protocols are harmonizing material specifications to serve export-oriented supply chains targeting European powertrain platforms. Domestic commercial vehicle manufacturers specify steel inserts through established tier-1 relationships. Maharashtra and Tamil Nadu production clusters concentrate foundry capacity for iron-based sintered powders.
Japan
METI industrial standards govern material specifications for marine propulsion systems requiring corrosion-resistant bronze formulations. Domestic powder metallurgy specialists supply precision inserts to aerospace turbine OEMs piloting conical seat geometries. Nagoya and Osaka industrial corridors anchor production for high-tolerance sintered components.
Valve Seat Inserts Market Competitive Environment
Concentration sits with integrated powder metallurgy specialists holding captive sintering capacity and IATF 16949 certification credentials. The vendor base stratifies across three tiers: multinational automotive suppliers with OEM captive relationships, regional foundries serving aftermarket channels, and alloy specialists targeting natural gas and aerospace thermal management applications. M&A activity targets powder metallurgy technician expertise and REACH-compliant formulation capabilities.
Among European-based powertrain suppliers, MAHLE and AVL List exemplify the integrated specialist archetype with captive sintering operations anchoring premium OEM contracts. Tenneco occupies a position at the scale-driven end, representing high-volume steel insert production for light-duty automotive and aftermarket channels. Eaton Corporation exemplifies the alloy innovation archetype through proprietary copper-nickel formulations targeting thermal loads in compressed natural gas engines.
| Leading Market Players |
|---|
| Tenneco |
| AVL List |
| MAHLE |
| Mitsubishi Materials Corporation |
| L.E. Jones |
| Eaton Corporation |
| GKN Automotive |
| Nippon Piston Ring |
| BorgWarner |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for REACH-compliant cobalt-chrome alloys concentrate pricing power with German powder metallurgy specialists while compressing margins for conventional iron-based sintering houses serving light-duty automotive contracts.
Pricing Analysis
Configured-to-order sintered alloy inserts command spreads of 40-60 percent above standard steel formulations due to IATF 16949 certification tiers and thermal performance grading. Three-tier pricing structure across premium cobalt-chrome, standard iron-based, and economy bronze levels segments buyer archetypes, with fleet operators in marine aftermarket channels exhibiting lowest price sensitivity. Cost compression in steel insert tiers intensifies because of stamping-to-sintering commoditization and volume concentration around Stuttgart-Munich OEM corridors. Tier-1 powertrain procurement teams anchor the most price-elastic demand segment, while independent distributors in natural gas compression capture margin pools through corrosion-resistant bronze specification.
Supply Chain Analysis
Inventory buffers for cobalt raw materials rarely exceed 45 days given SAMR stockpiling volatility and Democratic Republic of Congo extraction concentration. Supply draws from Germany for precision sintering equipment, China for iron powder feedstock, and Japan for high-tolerance furnace control systems. Raw material dependencies center on cobalt cathode precursors, atomized iron powders, and copper-nickel master alloys. Single-source vulnerability in Congolese cobalt exposes alloy cost structures to export restriction shocks. Distribution runs through captive tier-1 relationships for OEM volume and independent aftermarket channels for marine and stationary power rebuilds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator unbundling of valve seat insert procurement from full engine rebuild contracts concentrates buyer power with aftermarket distributors, fragmenting OEM dealer network control over replacement part economics.
For Market Incumbents: Consolidate captive sintering capacity around REACH-compliant nickel-copper-tungsten formulations before substitution mandates crystallize. Lock in 18-24 month IATF 16949 certification pipelines with Mercedes-Benz and MAN procurement teams. Vertical integration into atomized powder production hedges cobalt price volatility threatening premium insert margins.
For New Entrants and Emerging Players: Lead with additive-manufactured cobalt-chrome preforms for aerospace turbine conical seat geometries, where tolerance bands of ±8 microns create qualification barriers for conventional sintering houses. Target India's BIS-certified export supply chains harmonizing with Euro Stage V specifications. Partner with Yangtze River Delta powder metallurgy operations for furnace control technician access.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because emissions engineering convergence with thermal management component design collapses traditional supplier boundaries. Acquisition targets should prioritize captive sintering operations with REACH-compliant formulation pipelines. The signal to watch is cobalt substitution program acceleration among Germany-based tier suppliers facing 2026 authorization deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atomized Powder Production | Captive iron powder supply secures margin control against commodity spot volatility for steel insert tiers. |
| REACH-Compliant Alloy Substitution Program | Nickel-copper-tungsten development maintains CE marking access as cobalt compound authorizations expire. |
| Additive Manufacturing Preform Qualification | Sub-10 micron grain structures enable aerospace turbine conical seat contracts with ±8 micron tolerances. |
| Aftermarket Channel Direct Procurement | Independent distributor relationships capture fleet operator unbundling from OEM dealer rebuild networks. |
| IATF 16949 Certification Pipeline Investment | Eighteen-to-twenty-four-month qualification cycles lock in Mercedes-Benz and MAN powertrain platform access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA Tier 4 compliance filings, Euro Stage V technical documentation, and SAMR cobalt stockpiling directives. Primary interviews engaged powder metallurgy plant managers, Tier 1 supplier procurement directors, aftermarket distributor operations heads, and aerospace turbine OEM materials engineers. Secondary validation drew from KBA component certification records, REACH authorization databases, and MIIT fuel consumption mandate circulars. Bottom-up demand modeling across material grades, applications, and end-user channels triangulates against top-down powertrain production forecasts.
Segmentation dimensions modeled include material type across steel, bronze, aluminum, and experimental alloys; application spanning automotive, aerospace, marine, and industrial end-uses; form configuration distinguishing flat, conical, and beveled geometries; and end-user procurement authority separating OEM captive relationships from aftermarket independent channels. CAGRs derive from production volume elasticity to emissions mandate phase-ins and alloy substitution timelines. Industry-specific inputs incorporate exhaust gas recirculation rate specifications and lean-burn combustion thermal load profiles.
The analysis sits within stated boundaries; outcomes outside synchronized Euro Stage V and EPA Tier 4 implementation schedules would require recalibration. Forecasts reflect assumptions around cobalt supply concentration persistence and powder metallurgy technician availability. SAMR export restriction volatility, REACH substitution program acceleration, and aerospace turbine additive manufacturing adoption curves represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
China Explosion-Proof Equipment Market
Valves
Subsea Valves Market
Valves
Oil Drain Valves Market
Valves
Emergency Venting System Market
Valves
Global Valve Positioners Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Directional Control Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Deluge Valve Market
Valves
Pneumatic Slide Gates Market
Valves
Isolator Valves Market
Valves
Global Plastic Valves Market
Valves
Vaneometer Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Pigging Valves Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market