
 North America Helicopters Market | 2026-2036
North America Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Helicopters Market Analytics
FAA Part 135 air carrier certification is redrawing competitive boundaries for commercial helicopter operators in North America. Bell Textron leverages its integrated supply chain to dominate the light-twin segment for law enforcement agencies. Airbus Helicopters anchors its position through sustained R&D investment in fly-by-wire technology for medium-lift platforms. Sikorsky Aircraft Corporation competes on manufacturing scale, particularly in heavy-lift configurations for offshore energy contracts.
A helicopter is a rotary-wing aircraft generating lift through powered main rotors, with turboshaft engines typically delivering 500 to 3,000 shaft horsepower depending on weight class, designed for vertical takeoff and landing in confined areas inaccessible to fixed-wing aircraft. Light Helicopters occupy the largest volume share due to training fleet turnover and private aviation accessibility, while Heavy Helicopters command concentrated margin pools in offshore oil-and-gas logistics. The Emergency Services end-user segment shows structural momentum from hospital network expansion, whereas Corporate deployment faces pressure from fractional jet alternatives.
The FAA governs airworthiness standards through 14 CFR Part 27 and Part 29 certification pathways, while Transport Canada mandates equivalent compliance under Canadian Aviation Regulations for cross-border fleet interoperability. EPA emission thresholds for turboshaft engines are forcing powerplant redesign cycles, and OSHA workplace safety directives shape maintenance facility investments. Stakeholders must weigh certification timelines against fleet renewal deadlines as electrification prototypes advance toward regulatory validation.
Market Dynamics
FAA Part 135 certification tightening is forcing commercial operators to accelerate fleet renewal cycles, compressing procurement timelines and redistributing maintenance spend toward OEM-authorized service centers.
Growth Catalysts
- Emergency medical services fleet modernization:Hospital network expansion across the United States and Canada is driving replacement demand for aging single-engine airframes with IFR-capable twins.
- 14 CFR Part 27/29 airworthiness mandates:Transport Canada and FAA alignment on certification pathways enables cross-border fleet interoperability, simplifying procurement for multinational operators.
- Offshore oil corridor activity:Gulf of Mexico energy logistics sustain heavy-lift utilization rates, anchoring demand for long-range payload configurations.
Market Restraints
- Turboshaft engine supply concentration:Powerplant manufacturing concentrates among three dominant suppliers, creating delivery bottlenecks during fleet renewal surges.
- EPA emission threshold compliance costs:Redesign cycles for combustion efficiency add non-recurring engineering burden to new platform development.
- Fractional jet substitution:Corporate transport buyers increasingly divert budget toward light fixed-wing alternatives for missions not requiring vertical lift capability.
Strategic Opportunities
- Electrification prototype validation:FAA certification pathways for hybrid-electric powertrains open regulatory tailwinds for reduced-emission urban air mobility platforms.
- Southwestern border patrol sector expansion:Federal surveillance mission growth creates sustained demand for medium-lift equipped with multi-sensor payloads.
- Law enforcement fly-by-wire adoption:Airbus Helicopters' sustained R&D investment creates technology convergence opportunities for reduced-pilot-workload mission profiles.
Industry Challenges
- Airframe mechanic certification gaps:FAA Part 147 training program throughput lags fleet renewal demand, extending maintenance turnaround times.
- Type certificate amendment timelines:Supplemental certification for avionics upgrades stretches 18-24 months, delaying revenue service entry for modified aircraft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Helicopters Market |
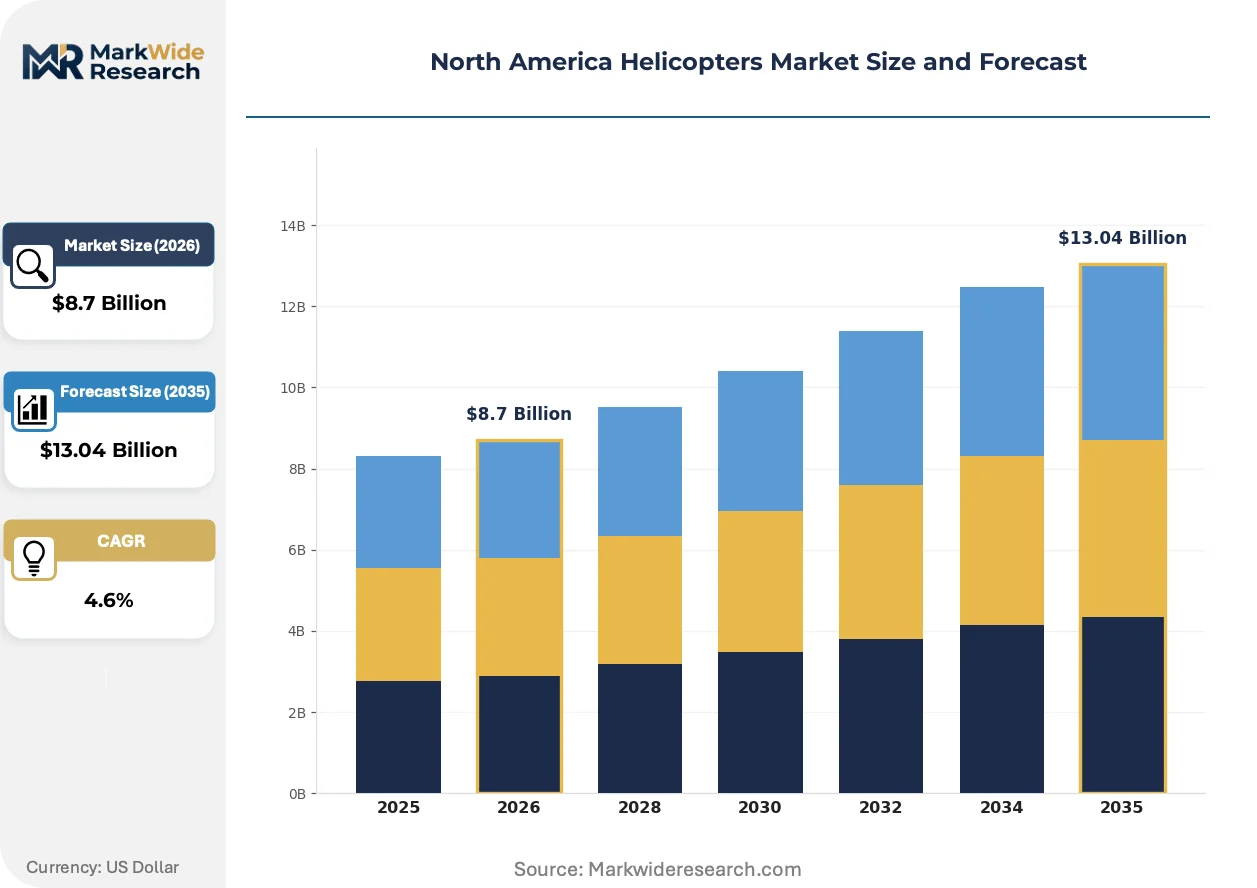
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters End User: Emergency Services, Law Enforcement, Corporate, Tourism Deployment: Onshore, Offshore, Private, Public Technology: Electro-Mechanical, Fly-by-Wire, Autonomous, Turboshaft |
| Companies Covered | Airbus Helicopters, Bell Textron, Lockheed Martin Corporation, Leonardo S.p.A., The Boeing Company, Sikorsky Aircraft Corporation, Enstrom Helicopter Corp., MD Helicopters, Robinson Helicopter Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Helicopters Market Evolving Landscape
Rotorcraft technology is bifurcating between legacy turboshaft refinement and electric propulsion experimentation, with regulatory validation pacing commercial deployment.
Fly-by-wire flight control architecture is fragmenting the medium-lift competitive landscape. Airbus Helicopters embeds full-authority digital controls in new H160 platforms, reducing pilot workload during instrument meteorological conditions. EMS operators in the United States are specifying these configurations for night vision goggle-compatible missions, compressing training time for transitioning fixed-wing pilots.
EPA emission thresholds for turboshaft engines are forcing powerplant redesign cycles with industrial consequence. Manufacturers must balance combustion efficiency gains against thermal management complexity in confined engine compartments. Offshore energy operators in the Gulf of Mexico face the steepest compliance timeline pressure, as heavy-lift platforms consume the highest fuel volumes per flight hour.
Buyer procurement patterns are consolidating through fleet standardization mandates. Large-scale EMS operators in the United States are reducing type diversity from six airframes to two, unbundling after-sales service from OEM packages. This concentration is most visible in the southwestern hospital network corridor, where shared maintenance infrastructure drives volume discounts on rotable component pools.
North America Helicopters Market Segmentation
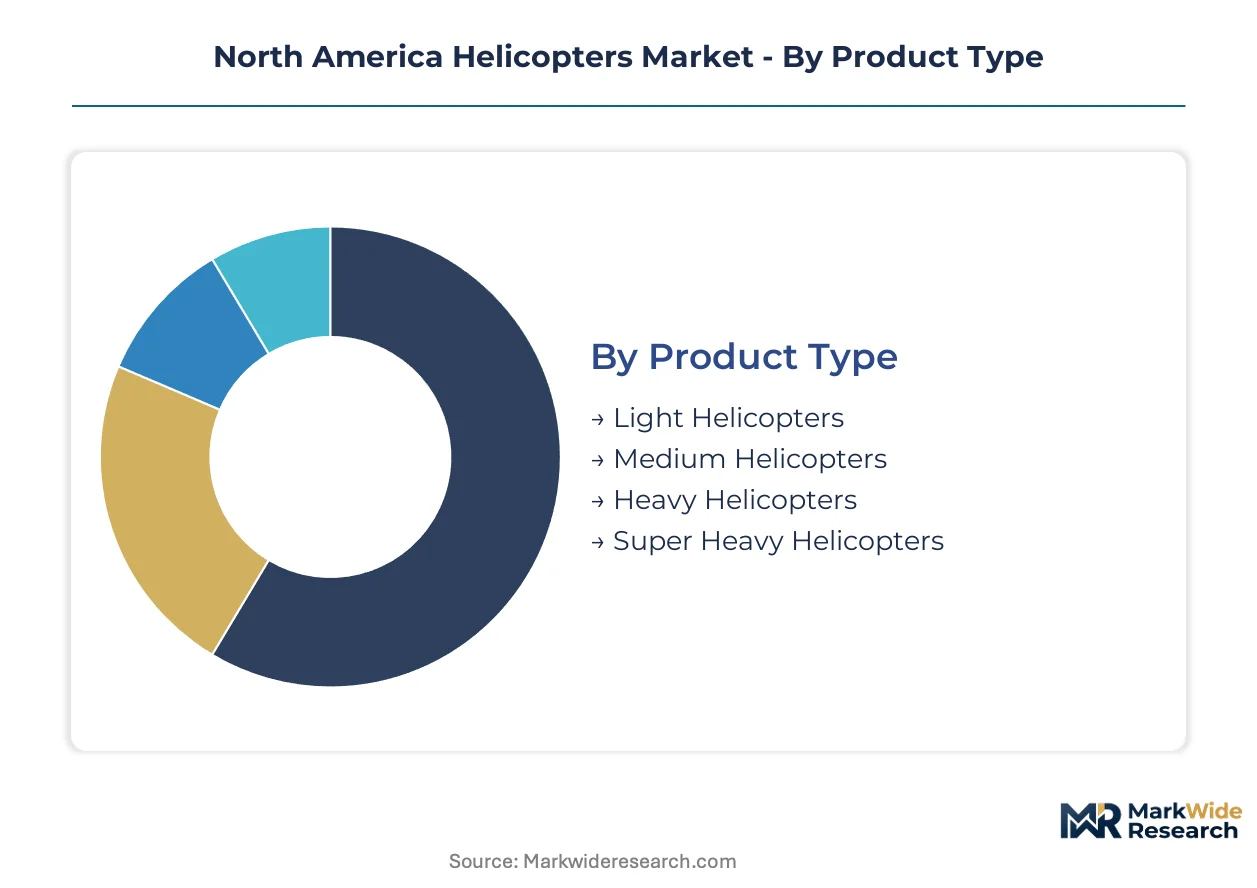
Helicopter procurement in North America follows distinct regulatory and operational pathways that reshape fleet composition across federal, commercial, and private buyers. FAA Part 27 and Part 29 certification tiers create structural boundaries between weight classes, while end-use mission profiles determine technology specification priorities.
Product Type:
FAA Part 27 airworthiness standards govern lighter platforms under 7,000 pounds maximum takeoff weight, while Part 29 mandates stricter structural and performance requirements for heavier configurations.
- Light Helicopters:Single-engine and light-twin configurations dominate training fleet turnover and private aviation accessibility. EMS operators in the southwestern United States are replacing aging single-engine airframes with IFR-capable twins to meet tightening FAA Part 135 operational requirements.
- Medium Helicopters:Twin-turboshaft platforms with 8,000-15,000 pound payload capacity anchor law enforcement and multi-mission government contracts. Border patrol sectors across Texas and Arizona specify these configurations for extended-range surveillance missions requiring multi-sensor payload integration.
- Heavy Helicopters:Long-range payload platforms sustain offshore energy logistics in the Gulf of Mexico corridor. EPA emission thresholds for high-volume turboshaft engines are forcing powerplant redesign cycles with concentrated compliance burden.
- Super Heavy Helicopters:Specialized heavy-lift configurations serve infrastructure construction and external load operations. Transport Canada cross-border certification alignment enables fleet interoperability for multinational operators serving Arctic resource extraction.
Light Helicopters handle the majority of unit throughput; Heavy Helicopters are expanding most quickly on margin contribution.
End User:
Procurement authority fragments across federal budget cycles, hospital network capital committees, and corporate aviation departments with divergent mission requirements.
- Emergency Services:Hospital network expansion across the United States and Canada drives replacement demand for night vision goggle-compatible platforms. FAA Part 135 IFR certification mandates are compressing procurement timelines for aging fleet replacement.
- Law Enforcement:Federal, state, and municipal agencies standardize on fly-by-wire configurations to reduce pilot workload during instrument meteorological conditions. Fleet consolidation mandates are reducing type diversity from six airframes to two across large-scale operators.
- Corporate:Fractional jet alternatives are diverting transport budgets away from rotary-wing configurations for missions not requiring vertical lift capability.
- Tourism:Scenic flight operators concentrate in Grand Canyon corridor and Alaska wilderness access routes with seasonal demand fluctuation.
Emergency Services commands the largest procurement volume; Law Enforcement is gaining share fastest on federal surveillance mission expansion.
Deployment:
Operating environment determines maintenance infrastructure investment and regulatory compliance burden across the ownership spectrum.
- Onshore:Continental operations span urban air mobility corridors, rural EMS networks, and inland resource extraction with established maintenance facility access.
- Offshore:Gulf of Mexico energy logistics platforms require corrosion-resistant configurations and extended-range fuel systems. OSHA workplace safety directives shape maintenance facility investments for helicopter landing decks.
- Private:Individual and corporate ownership concentrates in training fleet turnover and recreational aviation with Part 91 operational flexibility.
- Public:Government ownership spans federal border patrol, state law enforcement, and municipal emergency response with standardized procurement protocols.
Onshore deployment accounts for the greatest flight hour accumulation; Offshore operations show the steepest expansion trajectory on energy sector activity.
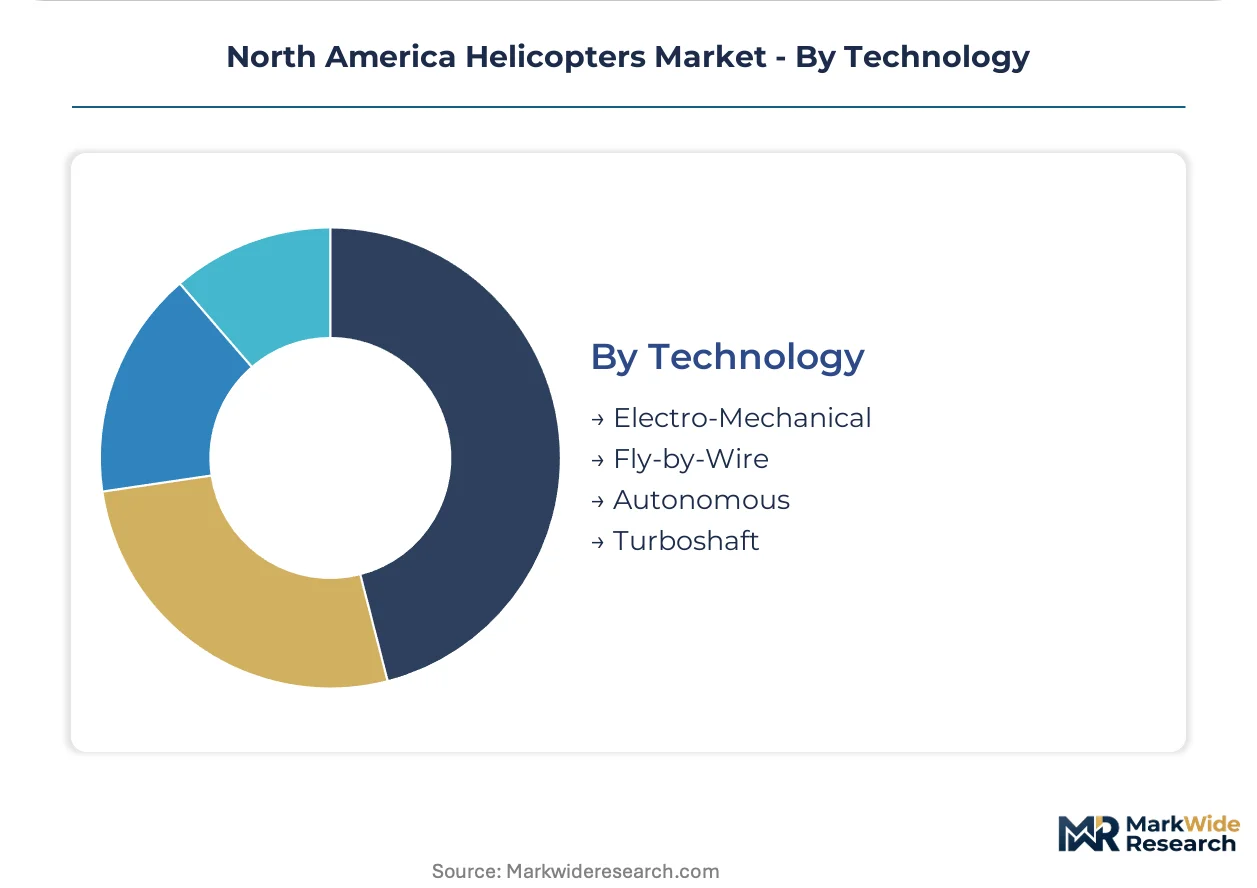
Technology:
Powerplant architecture and flight control systems are bifurcating between legacy refinement and electrification experimentation, with regulatory validation pacing commercial deployment.
- Electro-Mechanical:Conventional hydraulic and mechanical flight control linkages persist in legacy fleet and cost-sensitive training applications.
- Fly-by-Wire:Full-authority digital controls reduce pilot workload and enable instrument meteorological condition operations. Airbus Helicopters embeds this architecture in new platforms targeting EMS night vision goggle missions.
- Autonomous:Pilot-optional systems remain in experimental certification phases with FAA pathway development for reduced-crew urban air mobility.
- Turboshaft:Combustion powerplants dominate current fleet with EPA emission thresholds forcing combustion efficiency redesign cycles.
Turboshaft technology underpins current fleet operations; Fly-by-Wire is climbing the fastest on new platform specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 135 certification tightening and Transport Canada regulatory alignment are redrawing operational boundaries across North American helicopter markets, concentrating fleet renewal investment in cross-border interoperable configurations.
United States
Hospital network expansion across the southwestern corridor drives EMS fleet replacement demand for IFR-capable twins. FAA Part 135 IFR certification mandates compress procurement timelines for aging single-engine airframe retirement. The Gulf of Mexico offshore energy logistics cluster sustains heavy-lift utilization rates for long-range payload configurations.
Canada
Transport Canada CARs compliance alignment with FAA Part 27/29 pathways enables cross-border fleet interoperability for multinational operators. Arctic resource extraction contracts demand specialized heavy-lift configurations with cold-weather operational certification. Ontario and Alberta maintenance hubs consolidate rotable component pooling for shared EMS infrastructure.
Mexico
Federal surveillance mission expansion along the northern border corridor creates sustained demand for medium-lift multi-sensor platforms. Mexican civil aviation authority type validation timelines for imported airframes shape procurement planning for commercial operators. The offshore oil logistics cluster in the Bay of Campeche mirrors Gulf of Mexico operational requirements.
North America Helicopters Market Competitive Landscape
Listed aerospace conglomerates compete with private specialists across certification bandwidth and mission specialization tiers. Market structure concentrates around three dominant manufacturing archetypes: full-spectrum platform builders, mission-specific specialists, and government-contract anchors. Competitive positioning hardens through fleet standardization mandates from large-scale EMS operators and federal procurement consolidation. OEMs defend position through backward integration into authorized service networks and captive aftermarket parts distribution.
Within the full-spectrum platform tier, Airbus Helicopters and Bell Textron exemplify divergent technology strategies, while Sikorsky Aircraft Corporation anchors the heavy-lift government-contract segment. Leonardo S.p.A. occupies a position bridging commercial and specialized mission configurations. These three represent the dominant competitive archetypes shaping procurement outcomes across federal, commercial, and private buyer segments.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Bell Textron |
| Lockheed Martin Corporation |
| Leonardo S.p.A. |
| The Boeing Company |
| Sikorsky Aircraft Corporation |
| Enstrom Helicopter Corp. |
| MD Helicopters |
| Robinson Helicopter Company |
| Others |
Value Network & Pricing Analysis
Eighteen-month powerplant delivery backlogs concentrate pricing leverage among three dominant turboshaft suppliers, compressing OEM negotiation bandwidth and forcing operators toward bundled aftermarket service contracts. FAA Part 147 mechanic certification gaps extend maintenance turnaround times, amplifying the cost premium for authorized service center access.
Pricing Analysis
Certification level (FAA Part 27 versus Part 29) creates the primary spread between light and heavy platform pricing tiers. Three-tier pricing structure across premium fly-by-wire, standard IFR-capable, and economy VFR-only configurations segments buyer budgets. Cost compression in the light-twin segment is intensifying because EMS fleet standardization mandates consolidate procurement volume. Corporate transport buyers show the highest price sensitivity, diverting budget toward fractional jet alternatives.
Supply Chain Analysis
Port congestion on the Houston-Galveston corridor delays inbound engine component flows, stretching rotable inventory cycles for Gulf of Mexico offshore operators. Turboshaft powerplant manufacturing draws from the United States, France, and Canada. Critical dependencies include nickel-based superalloys, precision-forged turbine discs, and composite rotor blade prepregs. Single-source vulnerability concentrates in specialized gearbox housings. Distribution runs through OEM-authorized service networks and captive aftermarket parts channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue pools expand faster than airframe hardware sales as fleet standardization drives long-term maintenance contracts. Recurring rotable component subscriptions and predictive analytics packages capture margin from operational uptime guarantees.
For Market Incumbents: Shield market position by deepening backward integration into authorized service networks and securing FAA Part 147 training program accreditation. Electrification prototype entrants threaten legacy turboshaft aftermarket streams. Certification investment in hybrid-electric validation pathways defends against technology substitution.
For New Entrants and Emerging Players: FAA certification fast-tracks for supplemental type certificates open procurement access to EMS fleet renewal cycles. The southwestern United States hospital network corridor shows the most penetrable demand concentration. Target law enforcement fly-by-wire adoption through pilot workload reduction demonstrations.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core rotorcraft divisions. Long-term viability hinges on aftermarket service attach rates and electrification optionality. Watch for FAA pathway clarity on hybrid-electric powertrains as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Certification Investment | Part 29 validation for heavy-lift platforms unlocks Gulf of Mexico offshore contracts. |
| Backward Integration into Service Networks | OEM-controlled maintenance hubs capture recurring revenue from fleet standardization mandates. |
| Fly-by-Wire Technology Licensing | Airbus Helicopters' architecture reduces pilot training costs for EMS night vision missions. |
| Long-term Component Supply Agreement | Rostable pooling contracts with hospital networks secure volume commitments across replacement cycles. |
| Electrification Prototype Validation | FAA pathway development for hybrid-electric powertrains positions for emission threshold compliance. |
Research Methodology
Desk research of FAA certification databases, Transport Canada CARs filings, and offshore energy operator fleet registries preceded structured interviews with EMS procurement directors, Part 135 operations managers, and turboshaft powerplant engineering leads. Secondary validation drew from airframe mechanic union training records, hospital network capital expenditure disclosures, and Gulf of Mexico helicopter activity reports. Bottom-up unit demand estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, end user, and technology segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fleet replacement cycle analysis and regulatory mandate timing. Modeled inputs included FAA Part 135 IFR adoption curves and EPA emission threshold compliance deadlines.
Underlying assumptions cover stable FAA-Transport Canada regulatory alignment and sustained Gulf of Mexico energy sector activity, with deviation risk concentrated in electrification certification timeline delays and turboshaft supply chain disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aviation Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Medium and Heavy-Lift Helicopters Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Air Starter Market
Aircraft
Aviation Crew Management System Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
GCC General Aviation Market
Aircraft
Japan Aviation Market
Aircraft
Aircraft Control Surface Market
Aircraft
Europe Helicopters Market