
 North America Aviation Market | 2026-2036
North America Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aviation Market Analytics
The FAA's Sustainable Aviation Fuel Grand Challenge is restructuring procurement priorities across North American carriers. Southwest Airlines leverages its all-Boeing 737 fleet architecture to simplify SAF blending logistics and crew training standardization. Delta Air Lines anchors its decarbonization roadmap through offtake agreements with renewable fuel producers and fleet renewal cycles. American Airlines differentiates via aggressive narrowbody replacement schedules targeting fuel efficiency gains.
North America aviation encompasses the design, manufacture, operation, and servicing of heavier-than-air vehicles with fixed or rotary wings, typically powered by turbine or piston engines achieving cruise altitudes of 31,000 to 42,000 feet and operating within controlled airspace classes A through E. Commercial aircraft command the dominant revenue share as airlines replace aging A320ceo and 737NG platforms with next-generation single-aisle variants. Business jets represent the fastest-growing product category, driven by fractional ownership expansion and corporate flight department reactivation post-pandemic. Military operations applications sustain demand for propulsion systems optimized for supersonic performance and extended range in contested environments.
The FAA enforces airworthiness standards under 14 CFR Parts 25 and 33, while Transport Canada mandates equivalent certification through its National Aircraft Certification division, shaping product development timelines and market access conditions for cross-border suppliers. EPA emissions regulations for commercial aircraft engines tighten nitrogen oxide and particulate matter thresholds, forcing propulsion system redesigns. Stakeholders must monitor the divergence between FAA and EASA certification timelines for electric propulsion architectures, as asynchronous approvals will fragment fleet deployment strategies and training infrastructure investments.
Market Dynamics
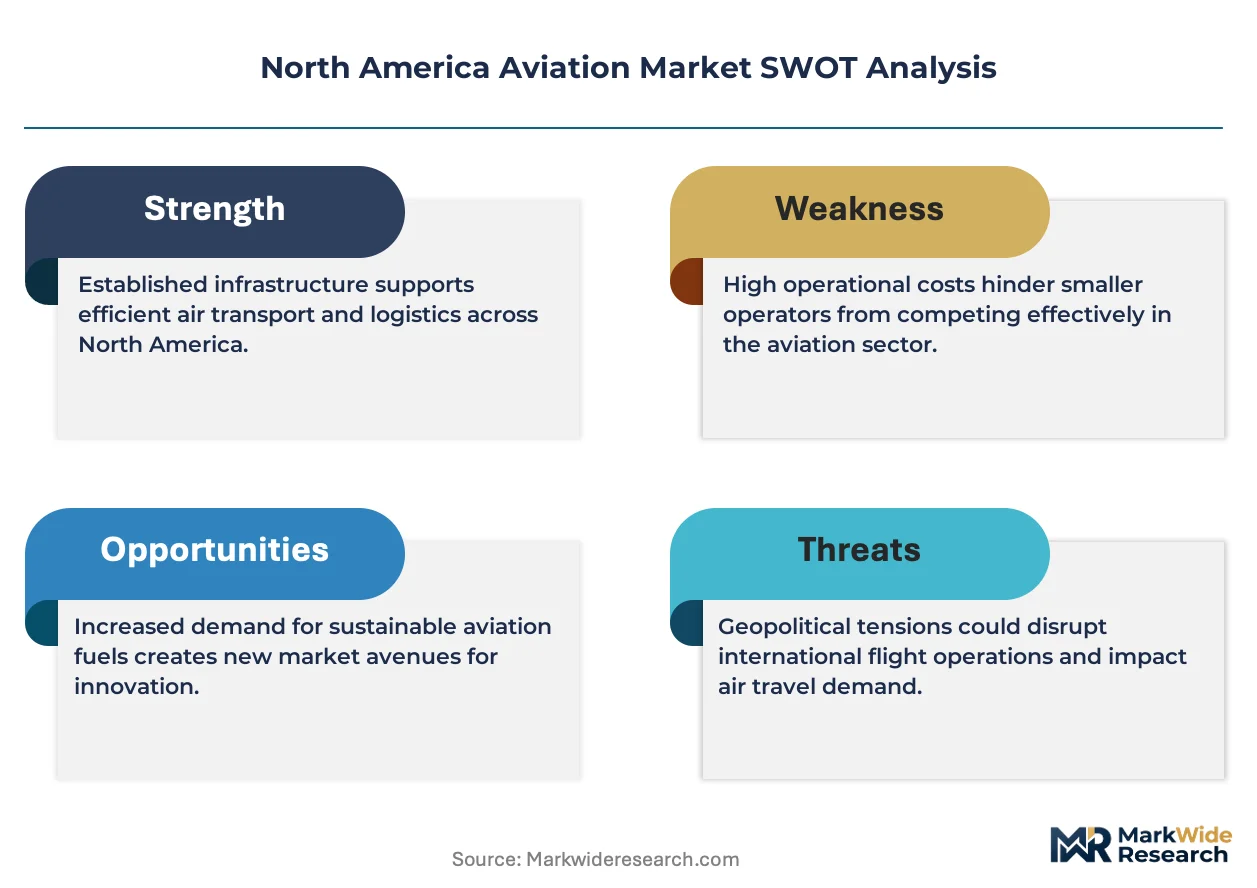
The FAA's NextGen airspace modernization program is forcing simultaneous avionics retrofits across aging fleets while new equipment mandates compress upgrade timelines for regional carriers and cargo operators.
Growth Catalysts
- E-commerce logistics demand:Cargo operators are expanding dedicated freighter fleets to capture parcel volume growth from online retail distribution networks. Dedicated air freight capacity is displacing belly-hold cargo on passenger routes.
- 14 CFR Part 25 mandates:The FAA's airworthiness standard updates are accelerating replacement cycles for narrowbody platforms approaching structural limits. Airlines face compliance deadlines that favor new aircraft acquisition over life-extension programs.
- Texas MRO cluster concentration:Dallas-Fort Worth and Houston anchor specialized maintenance infrastructure that reduces turnaround times for engine overhauls and structural repairs. Proximity to airline headquarters creates integrated fleet management ecosystems.
Market Restraints
- Turbine engine supply concentration:Propulsion system manufacturing concentrates among three dominant suppliers, creating delivery bottlenecks during demand surges. Airlines face extended lead times for spare powerplants.
- SAF feedstock cost volatility:Sustainable aviation fuel production depends on agricultural waste and renewable oil supplies subject to commodity price swings. Blending economics remain unfavorable without subsidy support.
- 14 CFR Part 33 certification friction:The FAA's engine certification timeline stretches 24-36 months for novel propulsion architectures, delaying entry of hybrid-electric systems into commercial service.
Strategic Opportunities
- Fractional ownership expansion:Business aviation demand is rotating toward shared-asset models that reduce capital barriers for corporate flight departments. Management companies are capturing operating revenue from non-owned fleets.
- Electric propulsion convergence:Battery chemistry advances and distributed motor architectures are enabling regional aircraft designs with sub-500 mile range. Urban air mobility platforms are leveraging this technology stack for vertiport networks.
- EPA emissions credit trading:The agency's nitrogen oxide threshold tightening creates transferable compliance instruments that reward early fleet renewals. Carriers with newer narrowbodies can monetize surplus credits.
Industry Challenges
- A&P mechanic shortage:Airframe and powerplant certification programs face enrollment declines that lag retirement rates among experienced technicians. MRO facilities compete for limited qualified labor pools.
- Legacy avionics integration complexity:New digital flight decks must interface with analog systems on mid-life aircraft, creating software validation burdens and intermittent compatibility failures.
- Dual certification timeline divergence:The FAA and Transport Canada process electric propulsion approvals on asynchronous schedules, fragmenting fleet deployment strategies for cross-border operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aviation Market |
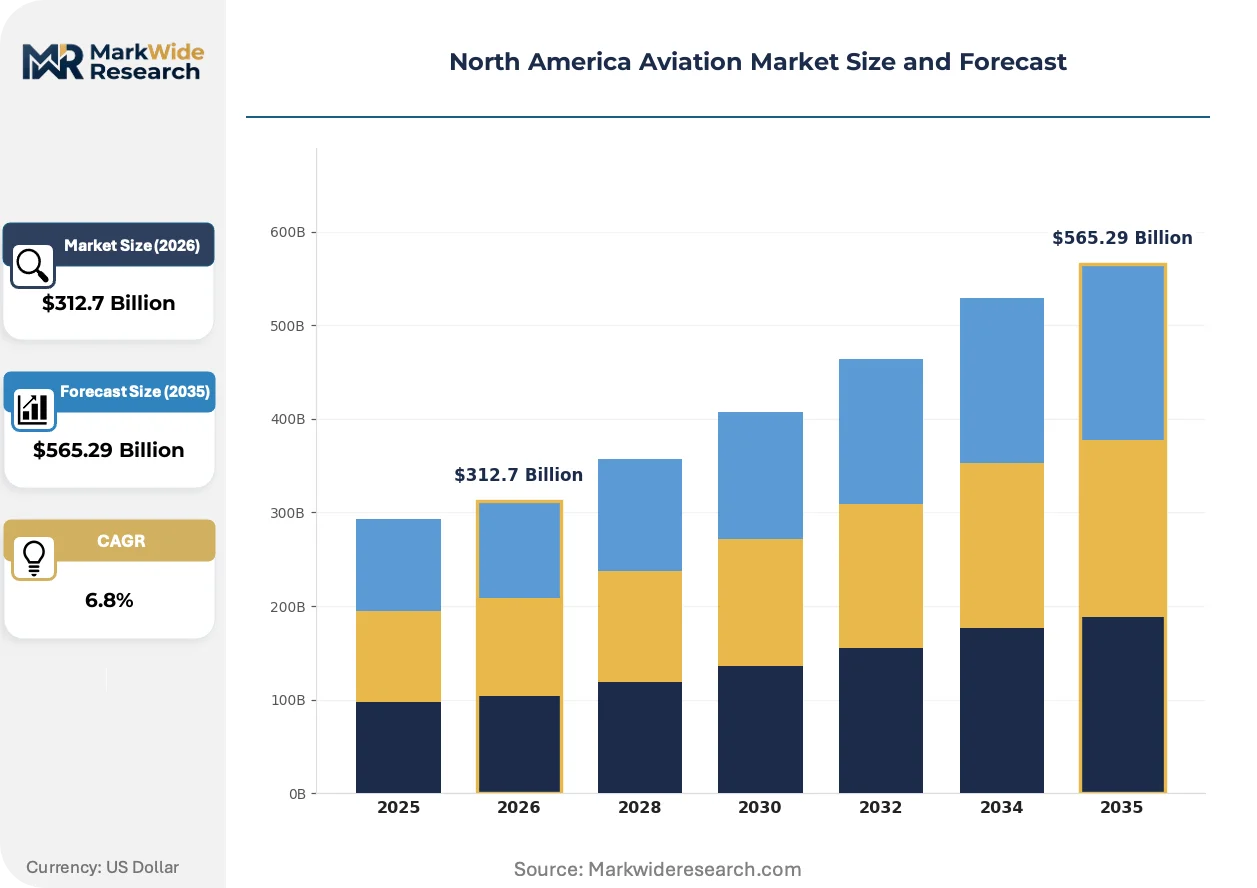
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Business Jets, Helicopters, UAVs End User: Airlines, Cargo Operators, Government, Private Owners Application: Passenger Transport, Freight Transport, Military Operations, Surveillance Technology: Avionics, Aerodynamics, Propulsion Systems, Navigation Systems |
| Companies Covered | Southwest Airlines, Airbus SE, American Airlines, Lockheed Martin Corporation, Air Canada, Delta Air Lines, The Boeing Company, General Dynamics Corporation, United Airlines, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aviation Market Evolving Landscape
Digital flight control systems and predictive maintenance algorithms are compressing operational cost structures while regulatory pressure on emissions intensifies technology substitution across propulsion architectures.
Artificial intelligence-driven predictive maintenance is automating component failure detection through real-time sensor data analysis from turbine engines and auxiliary power units. Regional carriers and cargo operators are deploying these platforms fastest due to higher aircraft utilization rates. The technology is automating scheduled inspection intervals, extending time-between-overhauls and reducing unscheduled downtime at line maintenance stations.
The FAA's Sustainable Aviation Fuel Grand Challenge establishes production volume targets and procurement incentives that restructure carrier fuel sourcing strategies. Refinery capacity investments in renewable feedstock processing lag mandated blending requirements, creating supply gaps. Narrowbody domestic routes face the tightest SAF availability constraints, forcing airlines to concentrate limited supplies on specific hub operations.
Corporate flight departments are unbundling aircraft management from fractional ownership contracts, selecting specialized operators for crew provisioning and maintenance while retaining asset control. This disintermediation of traditional program structures shifts revenue toward fee-for-service arrangements. The pattern is most visible in Texas and California, where dense executive travel corridors support standalone management company economics.
North America Aviation Market Segmentation
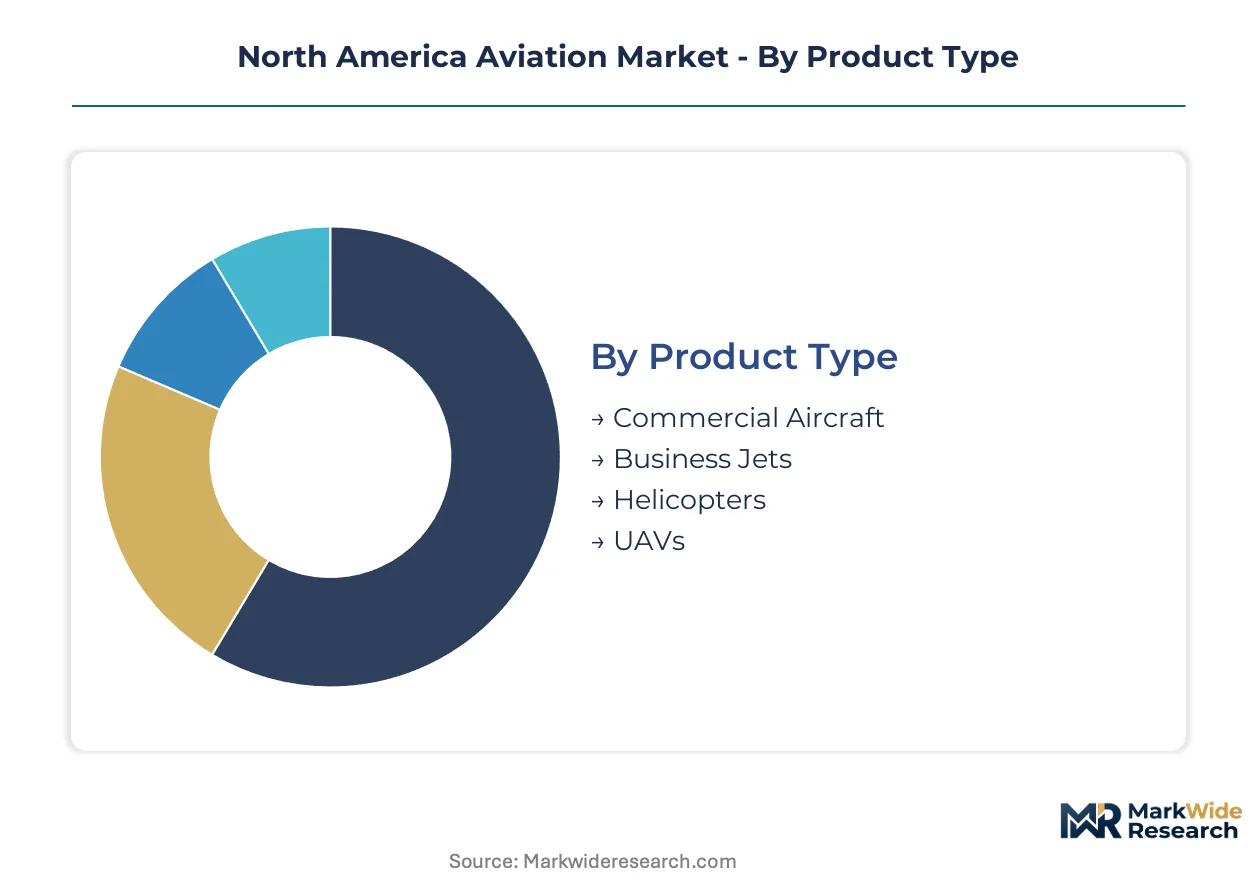
Segmentation reveals how fleet renewal cycles and regulatory mandates concentrate investment across distinct aviation platforms. Replacement timelines vary dramatically by product type and end-use, creating asynchronous demand peaks that suppliers must anticipate.
Product Type:
Upgrade imperatives differ sharply across fixed-wing and rotary platforms as 14 CFR Part 25 mandates force retirement decisions on aging airframes.
- Commercial Aircraft:Narrowbody platforms dominate replacement pipelines as airlines retire A320ceo and 737NG fleets. Texas and California hubs anchor the steepest delivery concentration for next-generation single-aisle variants.
- Business Jets:Fractional ownership expansion drives light-jet demand across corporate flight departments. Post-pandemic reactivation of executive travel corridors concentrates orders in Dallas-Fort Worth and Teterboro.
- Helicopters:Offshore energy transport and emergency medical services sustain turbine rotorcraft demand. Gulf Coast operators favor medium-twin configurations for platform crew transfers.
- UAVs:Agricultural spraying and infrastructure inspection applications expand beyond military origins. FAA Part 107 certification growth enables commercial drone fleet scaling.
Volume placements concentrate in Commercial Aircraft; the faster expansion belongs to Business Jets.
End User:
Procurement authority varies across asset ownership models, dictating contract structures and financing terms.
- Airlines:Network carriers dominate narrowbody replacement schedules through sale-leaseback arrangements. Fleet standardization pressures favor single-type certifications for crew and maintenance efficiency.
- Cargo Operators:E-commerce logistics demand accelerates dedicated freighter acquisitions. Express carriers expand Memphis and Louisville hub capacity with converted widebody platforms.
- Government:Defense procurement sustains multi-role fighter and surveillance platform development. Coast Guard rotary-wing modernization programs drive medium-lift helicopter demand.
- Private Owners:Individual asset control persists in agricultural aviation and flight training segments. Owner-operated aircraft face steeper compliance burdens under evolving avionics mandates.
Contract values peak with Airlines; the steepest volume climb occurs in Cargo Operators.
Application:
Operational profiles determine utilization rates and technology specifications across mission types.
- Passenger Transport:Hub-and-spoke networks concentrate demand on 150-seat narrowbodies. Slot-constrained airports drive range-payload optimization for stage-length flexibility.
- Freight Transport:Dedicated cargo capacity displaces belly-hold reliance on passenger routes. Express networks prioritize quick-turn capability over maximum payload.
- Military Operations:Supersonic performance and contested-environment survivability dictate propulsion requirements. Extended-range strike missions drive aerial refueling integration.
- Surveillance:Maritime patrol and border security applications sustain specialized sensor platforms. Long-endurance unmanned systems reduce crewed asset exposure.
Revenue concentration sits with Passenger Transport; Surveillance gains share fastest on unmanned platform adoption.
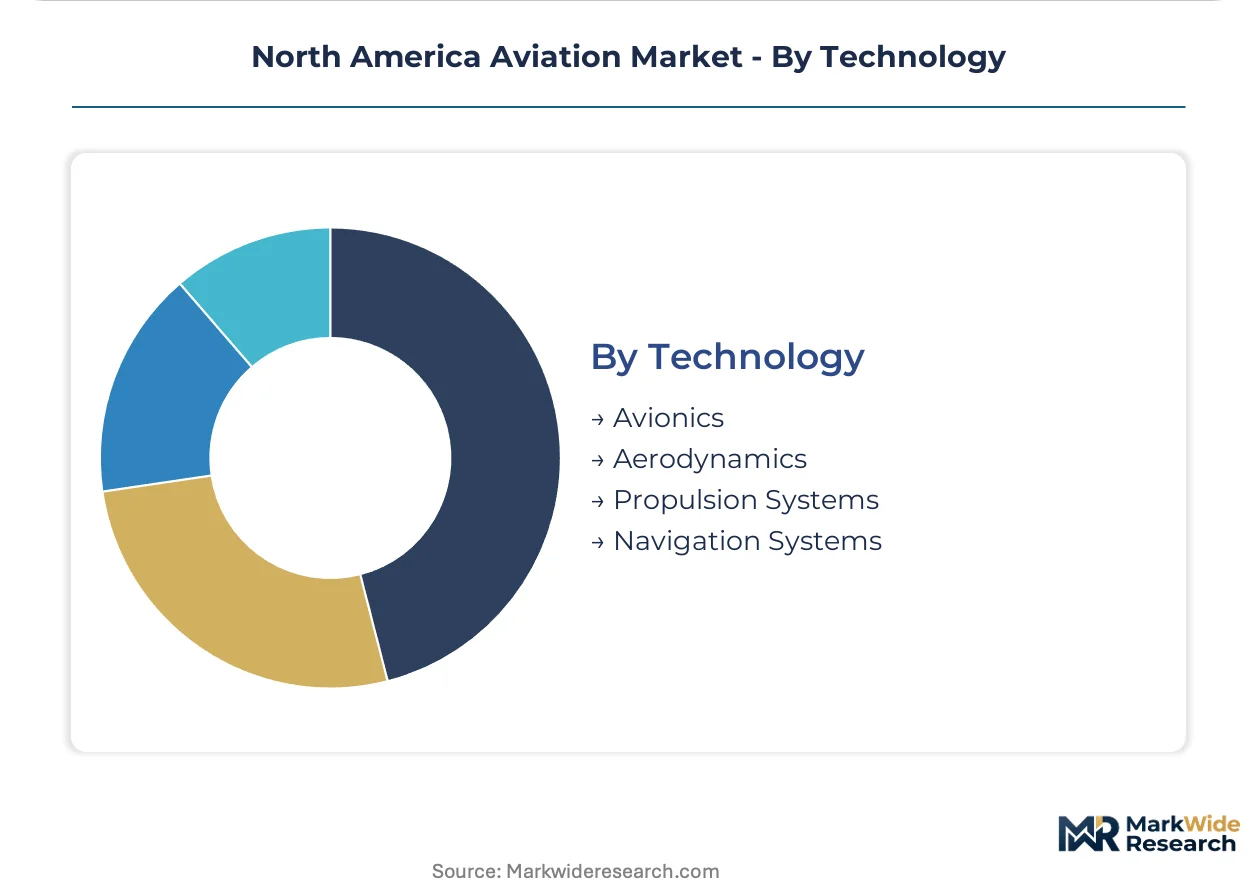
Technology:
Certification timelines fragment across subsystem categories as electric architectures challenge established approval pathways.
- Avionics:NextGen airspace mandates force digital flight deck retrofits on aging fleets. ADS-B Out and CPDLC equipage deadlines compress installation schedules.
- Aerodynamics:Winglet retrofits and laminar flow surfaces yield incremental fuel efficiency gains. Structural composite adoption reduces inspection intervals.
- Propulsion Systems:Turbofan efficiency improvements dominate narrowbody engine selection. Hybrid-electric architectures face 24-36 month FAA certification timelines.
- Navigation Systems:GPS augmentation and GBAS precision approaches reduce weather minima. Multi-constellation receivers add Galileo and BeiDou capability.
Investment intensity centers on Avionics; Propulsion Systems face the longest development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas-Fort Worth anchors North American aviation activity through concentrated airline headquarters, MRO infrastructure, and cargo hub operations that shape regional procurement patterns.
United States
Network carriers drive narrowbody replacement schedules through sale-leaseback arrangements concentrated at Dallas-Fort Worth and Houston. The FAA's NextGen airspace modernization program mandates ADS-B Out and CPDLC equipage that compresses retrofit timelines for regional operators. Memphis and Louisville anchor express cargo hub expansion as e-commerce logistics demand accelerates dedicated freighter acquisitions.
Canada
Transport Canada's National Aircraft Certification division enforces equivalent airworthiness standards to 14 CFR Parts 25 and 33, shaping cross-border supplier market access. Toronto and Vancouver concentrate aerospace manufacturing and MRO infrastructure serving transborder routes. Air Canada anchors fleet renewal cycles targeting fuel efficiency gains through narrowbody platform standardization.
Mexico
Querétaro's aerospace manufacturing corridor attracts foreign direct investment for component fabrication and assembly operations serving North American supply chains. Mexico's DGFT export promotion programs align with USMCA provisions to facilitate duty-free component flows. Tijuana and Mexicali border zones concentrate maquiladora operations for avionics and structural subassemblies.
North America Aviation Market Competitive Landscape
The competitive structure tilts toward vertically integrated OEMs with captive aftermarket services. Three strategic archetypes dominate: network carriers with standardized fleet architectures, diversified aerospace conglomerates spanning commercial and defense segments, and specialized MRO operators capturing revenue from third-party maintenance contracts. Capacity expansion and strategic partnerships constitute the primary competitive moves, with carriers securing exclusive supplier agreements and OEMs establishing regional service centers.
Among US-based network carriers, Southwest Airlines and American Airlines exemplify fleet standardization strategies that simplify crew training and maintenance logistics. Airbus SE and The Boeing Company anchor the OEM tier through duopoly positioning in narrowbody platforms. Lockheed Martin Corporation occupies a position within the defense-specialist archetype, sustaining demand for multi-role platforms and surveillance systems.
| Leading Market Players |
|---|
| Southwest Airlines |
| Airbus SE |
| American Airlines |
| Lockheed Martin Corporation |
| Air Canada |
| Delta Air Lines |
| The Boeing Company |
| General Dynamics Corporation |
| United Airlines |
| Others |
Value Network & Pricing Analysis
Captive MRO networks at Dallas-Fort Worth and Houston anchor both maintenance capacity and aftermarket pricing power for regional carriers. This geographic clustering of heavy maintenance infrastructure concentrates supplier leverage while compressing turnaround premiums for engine overhauls and structural repairs.
Pricing Analysis
Yield-per-available-seat-mile anchors network carrier pricing models across domestic and transborder routes. Price differentiation separates premium cabin configurations from basic economy inventory on identical narrowbody platforms. Cost compression in regional feed operations intensifies as scope-clause labor economics face 14 CFR Part 121 crew-rest mandate compliance. Cargo operators exhibit the lowest price sensitivity due to e-commerce volume commitments, while charter and fractional ownership segments absorb steeper per-hour rates.
Supply Chain Analysis
Turbine blade supply rests on precision casting foundries concentrated in the United States, France, and Japan. Nickel superalloy feedstock and ceramic matrix composites constitute critical input dependencies alongside specialized coating chemistries. Single-source vulnerability concentrates in high-pressure compressor disk forging capacity, where qualified suppliers number fewer than five globally. Distribution runs through OEM-controlled logistics networks and third-party parts distributors serving line maintenance stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America aviation market sits in a propulsion-transition phase as hybrid-electric architectures displace conventional turbofan dominance on regional routes. This technology substitution compresses investment horizons for legacy platform suppliers while opening white-space for novel certification pathways.
For Market Incumbents: Deploy fleet standardization as the primary defensive lever against crew training cost inflation and maintenance complexity. Southwest Airlines' all-Boeing 737 architecture exemplifies how single-type certification reduces spare parts inventory and simulator capital. Incumbents must accelerate narrowbody replacement schedules before 14 CFR Part 25 structural limit mandates force distressed retirements. Backward integration into SAF offtake agreements secures fuel cost visibility against renewable feedstock volatility. For New Entrants and Emerging Players: Enter via electric propulsion subsystem specialization targeting the sub-500-mile regional segment where FAA certification timelines remain asynchronous with EASA. Urban air mobility vertiport networks present the most penetrable white-space, with infrastructure-light entry points compared to hub airport slot constraints. A go-to-market angle anchored in Part 135 on-demand charter certification bypasses scheduled airline operating certificate barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified aerospace conglomerates seeking aftermarket service expansion. Long-term viability favors MRO operators with Texas cluster proximity and proprietary repair station authorizations for next-generation engine platforms. The signal to watch is FAA electric propulsion certification acceleration, which would validate capital deployment into hybrid-electric airframe developers.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Standardization | Southwest Airlines' single-type 737 architecture reduces crew training and spare parts complexity. |
| SAF Offtake Agreements | Delta Air Lines anchors decarbonization roadmap through renewable fuel producer contracts. |
| Avionics Retrofit Mandate Compliance | NextGen ADS-B Out and CPDLC deadlines compress installation schedules for regional operators. |
| MRO Cluster Expansion | Dallas-Fort Worth and Houston infrastructure concentration reduces engine overhaul turnaround times. |
| Electric Propulsion Certification Investment | Hybrid-electric architectures face 24-36 month FAA timelines, rewarding early regulatory engagement. |
Research Methodology
Independent corroboration across FAA certification databases, airline fleet planning disclosures, and MRO utilization records underwrites the qualitative findings. Primary interviews with airline fleet managers, airframe and powerplant mechanics, avionics integration specialists, and cargo operations directors supplied forward-looking procurement intelligence. Secondary validation drew from 14 CFR regulatory filings, Transport Canada airworthiness directives, DOT T-100 traffic data, and EPA emissions compliance records. Bottom-up segment sizing triangulated against top-down market aggregation from OEM delivery schedules and lessor placement data.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects and pricing evolution. Segmentation dimensions modeled include product type, end user archetype, application mission profile, and technology subsystem category, with geographic cluster concentration as an aviation-specific overlay. CAGRs derived from fitted trend lines through historical delivery data and announced backlog conversions. Forecast inputs incorporated turbine engine manufacturing capacity constraints and SAF refinery investment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged FAA certification delays or abrupt SAF subsidy withdrawal. Assumptions reflect current regulatory trajectories for NextGen equipage and emissions thresholds. A small set of triggers warrants ongoing watch: electric propulsion certification acceleration, turbine engine supplier capacity expansion announcements, and cross-border harmonization between FAA and Transport Canada approval timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Light Electric Aircraft Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Australia Aviation Market
Aircraft
Glider Aircraft Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Air Speed Indicator Market
Aircraft
Aircraft Elevator Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Amphibious Aircraft Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aviation Crew Management System Market
Aircraft
Europe General Aviation Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Aeronautic Propeller Market
Aircraft
Commercial Aircraft Market