
 Global LW Sport Aircraft Market | 2026-2036
Global LW Sport Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Global LW Sport Aircraft Market Foresight
The EU Green Deal's aviation decarbonization targets is decoupling European demand toward electric propulsion variants. Pipistrel leverages Slovenian manufacturing scale to dominate the electric light-sport segment across EU member states. Tecnam sustains Italian airframe specialization with aluminum construction expertise spanning decades. Van's Aircraft anchors the North American kit-plane sector through its RV-series ecosystem and builder support network.
Lightweight sport aircraft span factory-built and kit-assembled fixed-wing platforms typically operating under 1,320 pounds maximum takeoff weight with two-seat configurations and non-complex controls. These aircraft serve recreational flight, pilot training, and personal transportation with stall speeds below 51 knots enabling accessible handling characteristics. Ultralight and light-sport aircraft categories capture the dominant volume share as regulatory simplicity attracts first-time owners, while electric propulsion segments represent the fastest-growing margin pool as battery energy density improves and charging infrastructure spreads across aerodromes. Gasoline engine configurations retain mature-market status in regions with limited electrical grid access at rural airfields.
FAA MOSAIC rule changes and EASA CS-LSA standards are reshaping product certification pathways and cross-border market access for manufacturers. The EPA's evolving emissions frameworks for small aviation engines and the EU's F-Gas Regulation on refrigerants in climate systems impose compliance costs that favor larger producers with dedicated certification teams. Stakeholders must monitor how ICAO's environmental targets percolate into national implementations affecting engine choices and airframe materials.
Market Dynamics
FAA's MOSAIC rule revision is compressing certification timelines and expanding performance envelopes, while electric propulsion architectures are forcing airframe redesigns across factory and kit-plane segments simultaneously.
Growth Catalysts
- Pilot Certification Backlog:Flight schools in the United States and Germany are expanding training fleets to address instructor shortages and student queue delays.
- EU Green Deal Aviation Targets:The framework is mandating carbon intensity reductions that favor electric propulsion variants in member state procurement.
- Airpark Community Infrastructure:Residential aviation developments in Florida, Arizona, and Texas sustain factory-built uptake through dedicated runway access and hangar-integrated housing.
Market Restraints
- Battery Energy Density Ceiling:Lithium-ion pack limitations constrain range and payload for electric variants below gasoline-equivalent utility.
- Rural Airfield Electrification Gap:Grid infrastructure inadequacy across the United States Great Plains and Australian Outback limits electric aircraft operational flexibility.
- Special Airworthiness Certification Friction:Cross-border type certificate reciprocity gaps between FAA and EASA CS-LSA standards delay market entry for specialized manufacturers.
Strategic Opportunities
- India's General Aviation Liberalization:DGFT import duty restructuring and new private aerodrome licensing rules open first-mover positioning for light-sport categories.
- Flight School Fleet Electrification Mandates:Netherlands and Norway national aviation authorities are piloting zero-emission training aircraft requirements.
- Modular Quick-Build Kit Systems:Pre-fabricated component shipping models reduce builder completion timelines from years to months, expanding the addressable amateur-builder demographic.
Industry Challenges
- Airframe-Electric Powertrain Integration:Thermal management and weight distribution engineering for battery packs demands cross-disciplinary expertise scarce in traditional airframe houses.
- Part 23 to Light-Sport Regulatory Navigation:Engineering teams must maintain parallel certification competencies as MOSAIC implementation details remain in proposed rule status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LW Sport Aircraft Market |
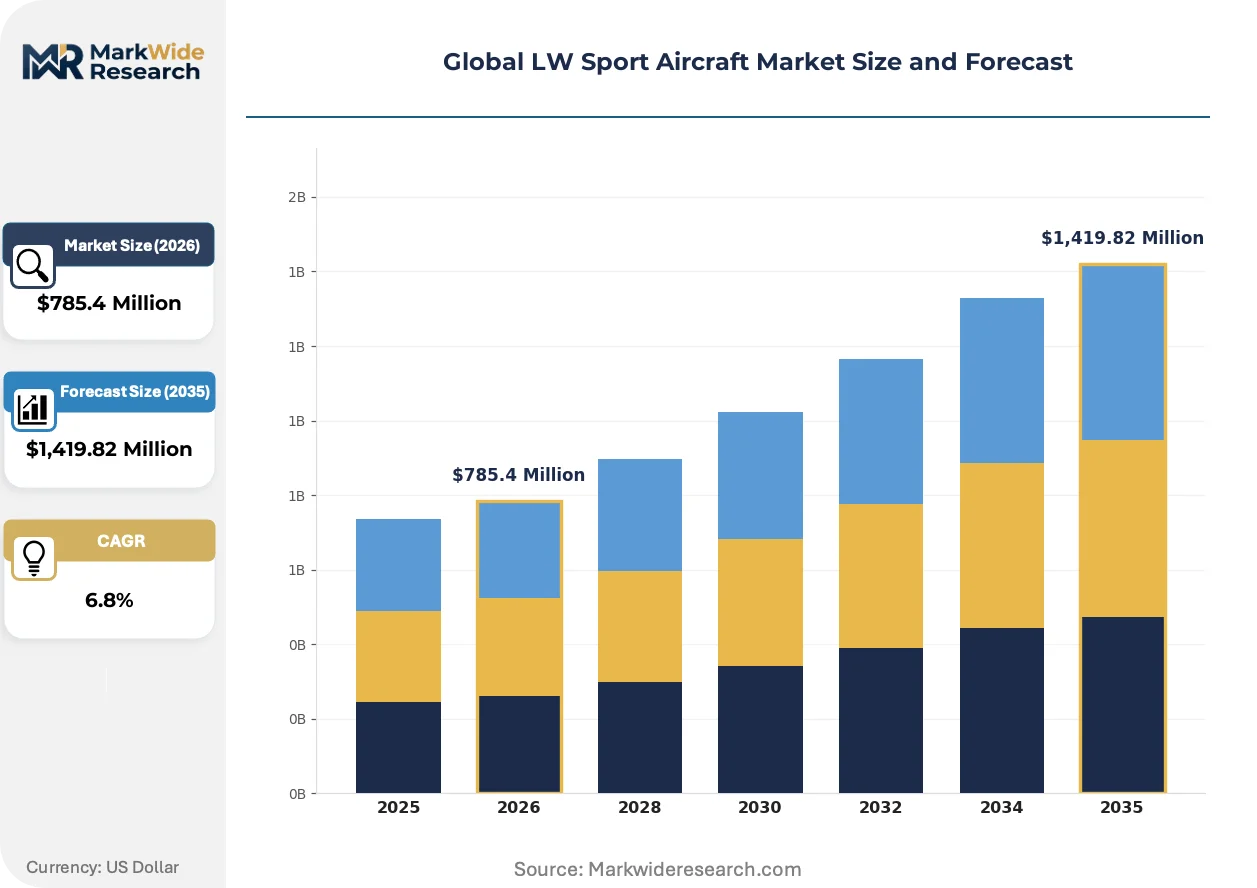
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultralight, Microlight, Light-Sport Aircraft, Experimental, Kit Planes Propulsion: Gasoline Engines, Electric Motors, Hybrid Systems, Turboprop Engines End User: Aeroclubs, Flight Schools, Recreational Pilots, Aerial Photographers Distribution Channel: Direct Sales, Dealers, Online Platforms, Auctions |
| Companies Covered | CubCrafters, Pipistrel, Flight Design General Aviation, Tecnam, ICON Aircraft, Van's Aircraft, Legend Aircraft, Cessna, Kitfox Aircraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LW Sport Aircraft Market Shifts & Advancements
Propulsion electrification is rewriting airframe design priorities, while regulatory modernization and shifting buyer demographics are compressing traditional sales cycles and expanding addressable pilot populations.
Composite manufacturing is converging with electric propulsion packaging requirements. Airframe designers are adopting resin-infused wing structures that integrate battery bay cooling channels and motor mounting hardpoints. Kit-plane builders in the United States and Australia are adopting these methods faster than factory production lines, compressing the innovation-to-flight timeline for amateur constructors.
EPA small aviation engine emissions frameworks are tightening hydrocarbon and nitrogen oxide limits for two-stroke and four-stroke powerplants. The rules are forcing carburetor-to-fuel-injection transitions and exhaust catalyst retrofits. Gasoline engine manufacturers serving the United States market are absorbing compliance costs that favor larger production volumes, pressuring low-volume specialty engine houses.
Flight training procurement is fragmenting from institutional fleet purchases toward individual aircraft ownership with leaseback arrangements to schools. This model shifts capital burden to student pilots while guaranteeing flight hour revenue. The pattern is most visible in the United States Sun Belt, where retired professionals combine recreational ownership with income generation through local flight school partnerships.
Global LW Sport Aircraft Market Segmentation
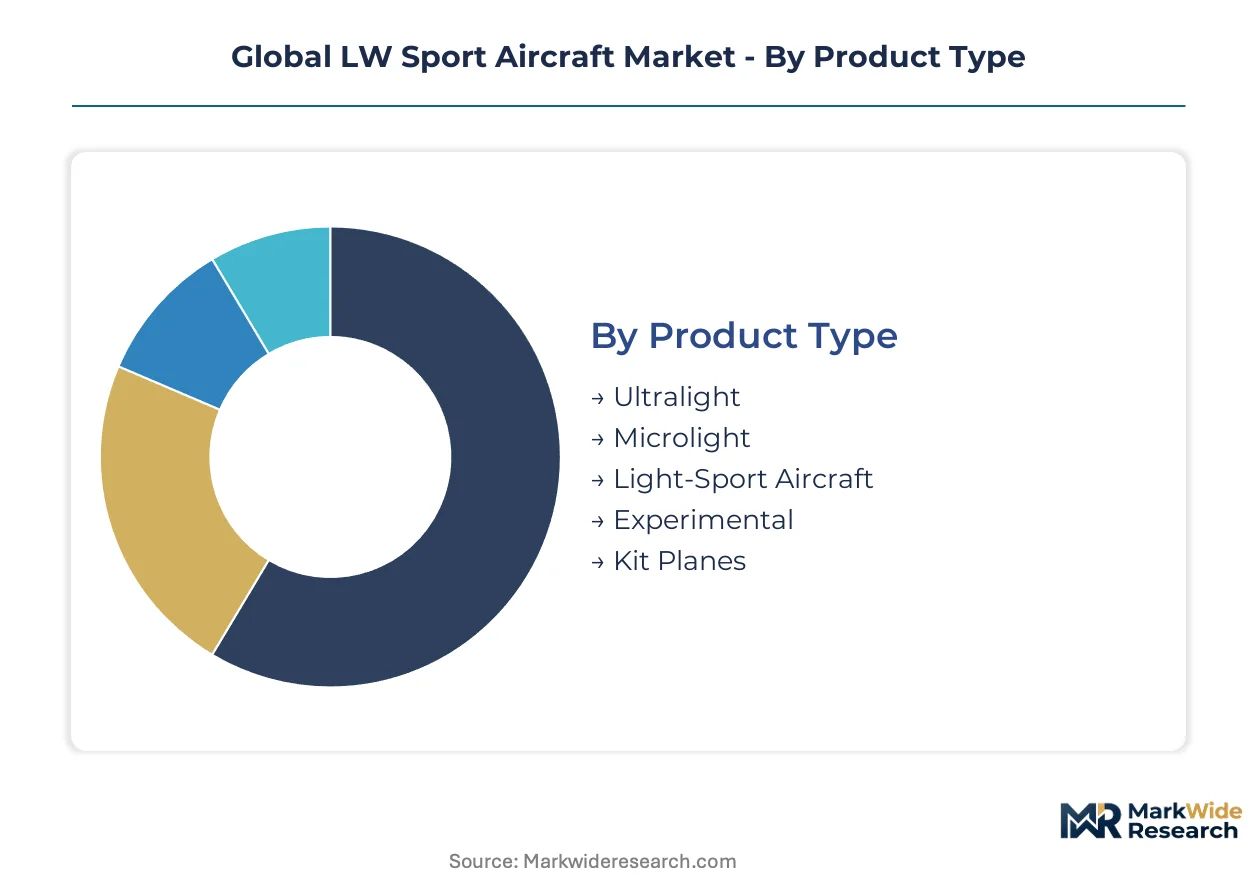
Segmentation in light-weight sport aircraft reveals divergent capital requirements, certification pathways, and customer acquisition economics. Manufacturers must align product architecture with distinct buyer risk profiles and operational use cases across factory-built, kit-assembled, and emerging electric platforms.
Product Type:
Capital intensity varies sharply across this category, with factory certification costs reaching multiples of kit-plane development expenditures.
- Ultralight:Unregulated weight-class platforms below 254 pounds empty weight operate under Part 103 exemptions without pilot medical certification. Demand clusters in the United States Sun Belt where recreational pilots seek minimal regulatory burden and lowest entry cost.
- Microlight:Slightly heavier European-category aircraft with three-axis control and modest stall speeds serve British and German aeroclubs seeking structured training progression. These platforms absorb substantial engineering investment for EASA compliance while maintaining price accessibility below factory-built alternatives.
- Light-Sport Aircraft:ASTM-certified factory-built platforms dominate flight school procurement in the United States and Germany due to standardized maintenance protocols and insurance accessibility.
- Experimental:Amateur-built category under FAA rules attracts technically skilled owners seeking performance customization beyond certified limits.
- Kit Planes:Pre-fabricated component systems from manufacturers like Van's Aircraft enable 1,000+ hour build projects with substantial cost savings over factory equivalents.
Light-Sport Aircraft absorbs the bulk of installed capacity; Kit Planes are expanding most quickly through quick-build subcategory innovations.
Propulsion:
Powertrain selection determines operational envelope, infrastructure dependency, and residual value trajectory across buyer segments.
- Gasoline Engines:Rotax and Continental four-stroke powerplants dominate current fleet composition with established maintenance networks and 4-6 hour endurance. Flight schools in the United States Great Plains and Australian Outback depend on this segment due to absent electrical infrastructure at rural aerodromes.
- Electric Motors:Pipistrel's Slovenian-manufactured powertrains lead European certification with battery-swappable architectures suited to Netherlands training mandates. Energy density limitations constrain range to 60-90 minutes, restricting utility to pattern work and local area training.
- Hybrid Systems:Series-hybrid architectures under development combine gasoline range-extenders with electric primary propulsion for transitional buyers.
- Turboprop Engines:High-performance experimental installations serve builder-owners seeking altitude capability and jet-fuel commonality.
Gasoline Engines retain dominant fleet share; Electric Motors are gaining share fastest through regulatory procurement mandates in EU member states.
End User:
Customer type dictates aircraft specification, financing structure, and aftermarket service intensity.
- Aeroclubs:European member-owned operations prioritize durable airframes with shared maintenance burdens and standardized insurance pools across Germany, France, and the United Kingdom.
- Flight Schools:United States and German institutional buyers demand factory-built platforms with predictable operating costs and manufacturer warranty coverage for high-cycle training operations.
- Recreational Pilots:Individual owners in Florida and Arizona airpark communities combine personal transportation with leisure flying, favoring cross-country capability and avionics modernization potential.
- Aerial Photographers:Specialized operators require slow-flight characteristics, camera mounting hardpoints, and vibration isolation systems for commercial imaging contracts.
Flight Schools drive highest unit volume; Aerial Photographers command steepest expansion trajectory through commercial service diversification.
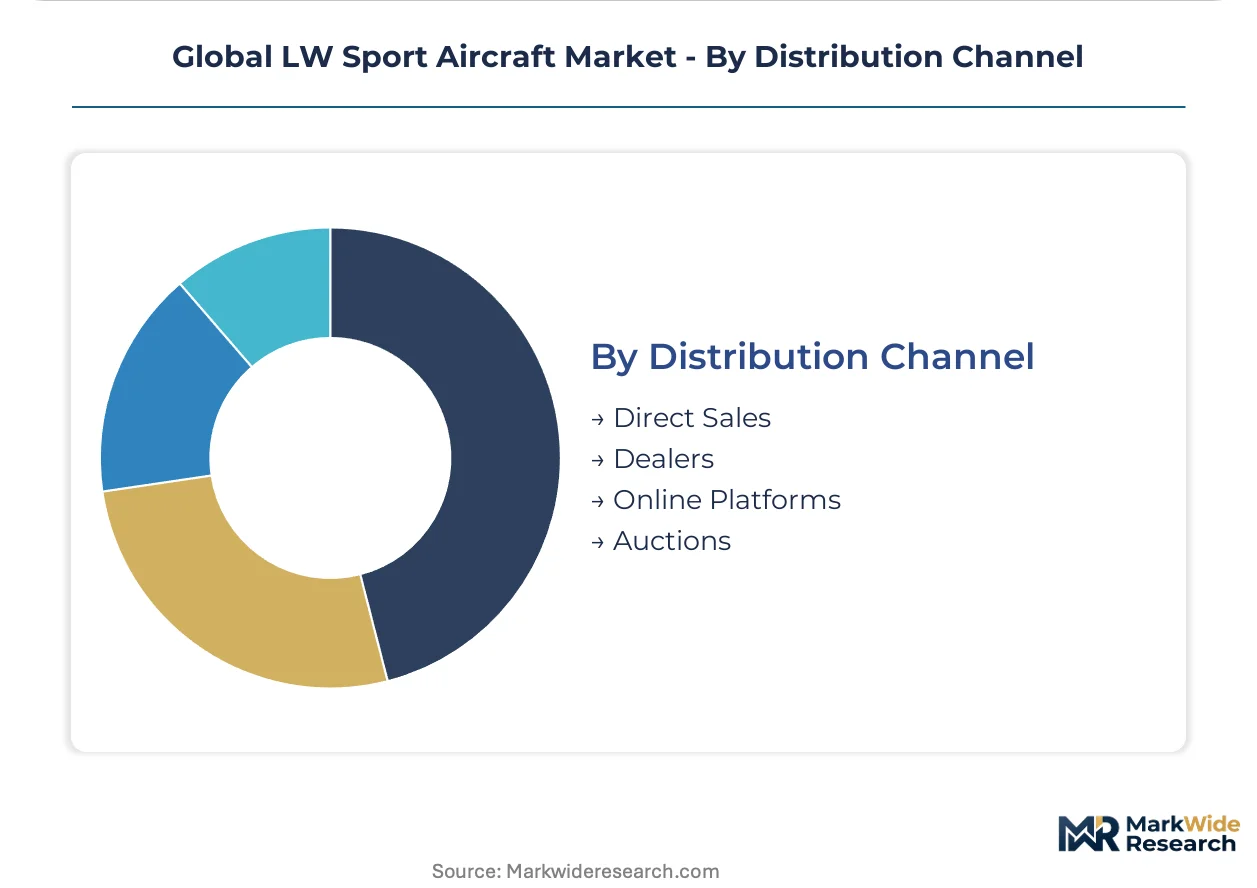
Distribution Channel:
Channel selection reflects buyer technical sophistication, geographic concentration, and capital access.
- Direct Sales:Factory-built manufacturers like Tecnam and Pipistrel sell direct to European flight schools and institutional buyers, capturing margin otherwise allocated to intermediaries.
- Dealers:Regional distributors in the United States provide demonstration flights, financing arrangements, and maintenance training for recreational buyers lacking technical confidence.
- Online Platforms:Kit-plane component ordering and used aircraft marketplaces reduce search costs for experienced builders and value-seeking owners.
- Auctions:Estate sales and bankruptcy liquidations supply project aircraft to restoration-focused builders and parts harvesters.
Dealers absorb the bulk of transaction volume; Online Platforms are climbing the fastest through digital-native buyer demographics and kit-plane component specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's airpark communities and Arizona's recreational aviation clusters generate concentrated factory-built aircraft demand through integrated runway-housing developments.
United States
Flight schools across Texas and the Sun Belt are expanding training fleets to address FAA-certified pilot backlogs. The FAA's MOSAIC rule revision widens light-sport aircraft performance envelopes and compresses certification timelines. Van's Aircraft anchors kit-plane manufacturing in Aurora, Oregon, supplying the amateur-builder ecosystem with pre-fabricated RV-series components.
Germany
Aeroclubs in Bavaria and Baden-Württemberg prioritize durable aluminum airframes for shared ownership models. EASA CS-LSA standards govern type certification pathways for factory-built platforms entering German flight schools. Tecnam maintains production specialization in Capua, Italy, serving German institutional buyers through direct sales channels.
Australia
Recreational pilots in Queensland and New South Wales favor gasoline-engine configurations due to absent electrical infrastructure at Outback aerodromes. The country's national aviation regulator maintains amateur-built aircraft standards parallel to FAA experimental categories. Kit-plane builders in Victoria adopt composite manufacturing methods faster than factory production lines.
Netherlands
National aviation authorities mandate zero-emission training aircraft procurement for flight schools in Amsterdam and Rotterdam corridors. The EU Green Deal's aviation decarbonization targets accelerate electric propulsion adoption. Pipistrel's battery-swappable architectures dominate Dutch institutional procurement through Slovenian manufacturing scale.
India
DGFT import duty restructuring and private aerodrome licensing rules open first-mover positioning for light-sport categories in Maharashtra and Karnataka. The country's national aviation regulator is streamlining type certification reciprocity with ASTM standards. Bangalore's aerospace engineering talent pool supports emerging kit-assembly operations for recreational aviation entrants.
Global LW Sport Aircraft Market Competitive Landscape
The competitive structure tilts toward specialized airframe houses with decades of construction expertise. Factory-certified manufacturers and kit-plane suppliers occupy distinct margin tiers with minimal direct overlap. Three archetypes dominate: European electric-propulsion specialists, North American kit-plane ecosystem builders, and Italian aluminum airframe traditionalists. Capacity expansion and regulatory certification arbitrage constitute the dominant competitive moves as MOSAIC implementation details crystallize.
Among North American fabricators, CubCrafters and Van's Aircraft exemplify divergent pathway specialization—factory-built versus amateur-assembled delivery models. Pipistrel anchors the electric-propulsion archetype through Slovenian manufacturing presence. Tecnam occupies a position within Italian aluminum construction heritage, serving European flight school procurement with ASTM-certified platforms.
| Leading Market Players |
|---|
| CubCrafters |
| Pipistrel |
| Flight Design General Aviation |
| Tecnam |
| ICON Aircraft |
| Van's Aircraft |
| Legend Aircraft |
| Cessna |
| Kitfox Aircraft |
| Others |
Supply & Pricing Matrix
The EU Green Deal's aviation decarbonization mandate gates both qualified battery supply and premium-tier pricing access for electric light-sport variants, while gasoline-engine platforms retain cost advantages where charging infrastructure remains absent. This environmental framework bifurcates manufacturer pricing power between certified electric propulsion specialists and legacy combustion suppliers.
Pricing Analysis
Flight-hour-based value pricing anchors factory-built light-sport aircraft, with leaseback arrangements to United States flight schools commanding premiums over pure retail sales. Certification tier under ASTM standards and EASA CS-LSA protocols drives substantial price differentiation between factory-built and amateur-built categories. Cost compression in kit-plane segments intensifies as quick-build subcategories reduce builder labor inputs. Flight schools demonstrate lowest price sensitivity due to guaranteed utilization, while individual recreational buyers in Florida and Arizona airpark communities exhibit highest elasticity.
Supply Chain Analysis
Aerospace composites and avionics technicians concentrate in Slovenia, Italy, and the Pacific Northwest United States, constraining production scaling for electric airframe integration. Battery cell supply draws from South Korean and Chinese manufacturers, while Rotax gasoline engines source from Austrian production. Single-source vulnerability in lithium-ion pack supply creates exposure for European electric specialists. Distribution runs through direct sales channels for institutional buyers and regional dealer networks for recreational purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive battery assembly capacity to secure supply and margin control against volatile cell pricing.
For Market Incumbents: Acquire battery pack assembly facilities or form exclusive supply partnerships with cell manufacturers to lock in qualified electric propulsion supply. Expand quick-build kit fabrication capacity in Oregon and Arizona to defend against emerging modular component suppliers. The MOSAIC rule implementation timeline uncertainty threatens certification investment returns, favoring manufacturers with parallel Part 23 and light-sport engineering teams. For New Entrants and Emerging Players: The price-point gap between Pipistrel's certified electric platforms and gasoline-powered ultralights presents entry space for hybrid-range-extender architectures targeting Australian Outback and United States Great Plains flight schools. India's DGFT import duty restructuring opens first-mover positioning for ASTM-certified factory-built categories in Maharashtra and Karnataka. Direct digital sales to technically confident amateur builders bypass established dealer margin structures. For Investors and Strategic Acquirers: Netherlands and Norway national aviation authority zero-emission training mandates are the leading indicator that electric fleet conversion will accelerate regulatory procurement shifts across EU member states. Acquisition targets should display integrated airframe-battery thermal management capabilities and existing EASA CS-LSA or FAA ASTM certification. Watch for MOSAIC final rule publication as the signal triggering incumbent capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in MOSAIC-Compliant Platforms | FAA rule expansion widens performance envelopes and compresses type certificate timelines for qualified manufacturers. |
| Backward Integration into Battery Pack Assembly | Captive cell sourcing insulates electric propulsion margins from commodity volatility and supply allocation constraints. |
| Quick-Build Kit System Standardization | Pre-fabricated component models compress amateur-builder completion timelines and expand addressable demographic reach. |
| Flight School Leaseback Program Expansion | Guaranteed utilization contracts shift capital burden to student owners while securing manufacturer aftermarket revenue. |
| Geographic Manufacturing Footprint Diversification | Slovenian and Italian production bases serve EU Green Deal procurement; Oregon and Arizona facilities target Sun Belt recreational demand. |
Research Methodology
Document review covered FAA type certificate databases, EASA CS-LSA certification registries, and ASTM standard publications, complemented by interviews with airframe engineering directors, flight school fleet managers, and recreational aviation association executives. Secondary validation drew from national aviation authority procurement disclosures, aerodrome infrastructure investment reports, and battery energy density research from electrochemical engineering journals. Bottom-up unit demand estimates from flight school expansion plans were triangulated against top-down market value projections.
Installed base forecasts and value projections were generated across the analysis window through segmented modeling by propulsion architecture, product type, and end-user category. The analytical framework incorporated pilot certification backlog trajectories, regulatory implementation timelines, and airpark community development patterns as industry-specific demand drivers. CAGRs were derived from logistic diffusion curves fitted to historical fleet replacement cycles and projected technology adoption S-curves for electric propulsion.
Inputs from FAA rulemaking dockets and EASA certification timelines were available through the study window; gaps in final MOSAIC implementation details and battery energy density improvement trajectories introduce uncertainty bands around electric segment penetration assumptions. Forecasts reflect documented regulatory proposals and manufacturer production capacity announcements. Material deviation in MOSAIC publication timing or lithium-ion cell supply allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Elevator Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Tanker Aircraft Market
Aircraft
General Aviation Market
Aircraft
Sailplane Market
Aircraft
Winglets Market
Aircraft
Light Electric Aircraft Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Aircraft Fairings Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Middle-East Aviation Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Latin America Business Jet Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Commercial Aircraft Wing Market