
 Commercial Aircraft Overhead Stowage Bins Market | 2026-2036
Commercial Aircraft Overhead Stowage Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Overhead Stowage Bins Market Outlook
Buyer concentration among commercial airlines is restructuring procurement dynamics across the supply base. Safran leverages its integrated cabin systems portfolio to capture multi-year outfitting contracts from full-service carriers. FACC AG anchors its position through specialized composite manufacturing capabilities that reduce installed weight versus legacy aluminum designs. Diehl Aviation competes by extending its product range across both OEM line-fit and aftermarket retrofit channels.
Commercial aircraft overhead stowage bins are enclosed passenger cabin storage compartments typically fabricated from thermoplastic composites or aluminum alloys, engineered to meet 9g crash load requirements and 16g dynamic seat criteria while maximizing volumetric efficiency within the crown area. The primary purpose is to secure carry-on luggage during all flight phases while optimizing passenger boarding flow and cabin crew safety access. Lightweight composite bins now lead material-based demand as fuel-burn economics drive airline specifications toward reduced operating empty weight. Modular bin architectures represent the fastest-growing product configuration, enabling carriers to reconfigure cabin density between premium and economy layouts without full system replacement. Standard aluminum bins retain residual demand in emerging-market retrofit programs where acquisition cost sensitivity outweighs lifecycle fuel savings.
FAA airworthiness standards under 14 CFR Part 25 govern flammability, smoke toxicity, and structural integrity requirements for stowage bin installations on US-registered aircraft. EASA CS-25 certification and the EU Green Deal emissions framework are jointly pressuring European operators and suppliers toward lower-mass composite solutions that contribute to fleet CO2 reduction targets. China's CAAC type certification process and GB standards for cabin interior materials are shaping market access for foreign suppliers serving COMAC programs. Stakeholders must monitor evolving flammability test protocols and emerging sustainable material qualifications as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Retrofit demand from narrow-body fleet operators is compressing product lifecycles and forcing suppliers to engineer drop-in composite replacements that maintain legacy mounting interfaces while cutting installed weight.
Growth Catalysts
- 14 CFR Part 25 flammability mandates:FAA tightening of smoke toxicity and burn-through standards is accelerating replacement schedules for aluminum bin inventories across US-registered fleets.
- Thermoplastic composite maturation:Automated fiber placement and out-of-autoclave curing are cutting production cycle times for complex crown-area geometries.
- Low-cost carrier carry-on proliferation:Southwest and Ryanair operational models maximize ancillary fee revenue through expanded bin volume per passenger seat.
Market Restraints
- Carbon fiber prepreg cost volatility:Aerospace-grade epoxy resin and PAN precursor pricing swings compress margin predictability for tier-two fabricators.
- OEM airframer supply concentration:Boeing and Airbus captive sourcing agreements lock retrofit channels for 737 MAX and A320neo family platforms.
- Legacy aluminum interchangeability:Existing MRO tooling and repair station certifications create switching friction against full composite conversions.
Strategic Opportunities
- India narrow-body fleet expansion:IndiGo and Air India order backlogs create line-fit demand for modular bin architectures supporting rapid cabin reconfiguration.
- EU Green Deal emissions weight targets:EASA CS-25 certification pathways now explicitly credit mass reduction toward operator CO2 compliance obligations.
- RFID-integrated smart bins:Convergence of composite structures with embedded sensor networks enables real-time occupancy monitoring and predictive maintenance analytics.
Industry Challenges
- 16g dynamic seat integration certification:Bin-to-seat track load path verification extends FAA DER approval timelines by four to six months.
- Composite repair technician scarcity:Qualified NDT inspectors and scarf repair specialists command premium wages, constraining MRO network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Overhead Stowage Bins Market |
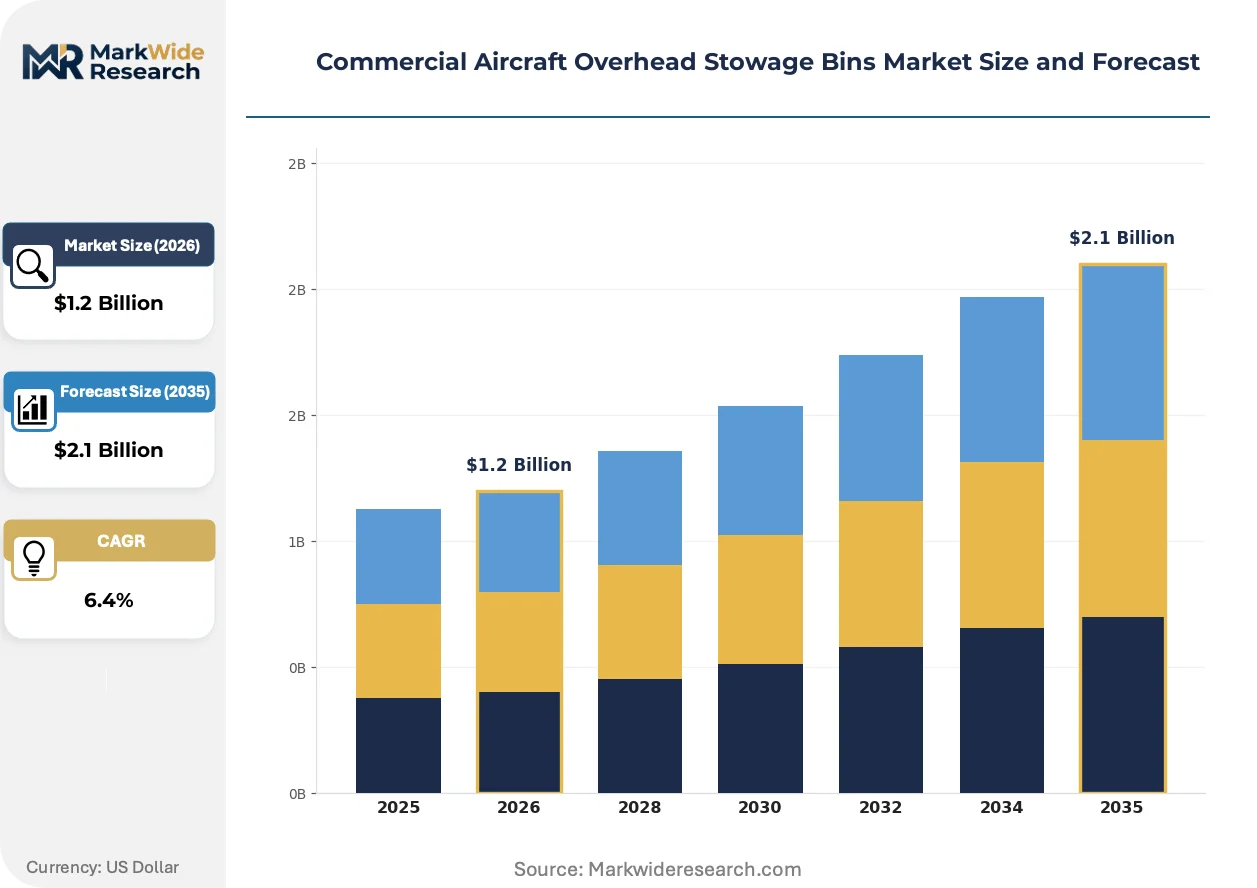
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bins, Lightweight Bins, Modular Bins, Premium Bins Material: Aluminum, Plastic, Composite, Steel End User: Commercial Airlines, Cargo Carriers, Private Jets, Charter Services Installation Type: OEM, Retrofit, Upgrade, Maintenance |
| Companies Covered | Safran, FACC AG, JAMCO Corporation, Airbus SE, Collins Aerospace, Diehl Aviation, Spirit AeroSystems, AVIC Cabin Systems, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Overhead Stowage Bins Market Strategic Shifts
Weight-driven specification changes and embedded intelligence are redefining what constitutes a stowage system, with bin suppliers now competing on data services and cabin integration depth rather than commodity fabrication alone.
Modular bin architectures are absorbing the lion's share of engineering investment as carriers demand plug-and-play volume adjustments. Full-service operators retrofit premium-heavy layouts for summer routes then revert to dense economy configurations within 48-hour turnarounds. This flexibility is absorbing capital that previously flowed to fixed aluminum structures, compressing the addressable market for non-reconfigurable designs.
EASA CS-25 Amendment 25-148 introduced revised flammability test protocols for thermoplastic components in crown areas. European operators must now demonstrate heat release rates below 55 kW/m² and smoke density limits of 200 Ds max. German and French carriers are responding by specifying pre-certified material stacks from qualified suppliers, narrowing the approved vendor base and extending procurement lead times for non-qualifying alternatives.
Airline engineering departments are consolidating vendor relationships around full cabin integrators capable of delivering bins, monuments, and galleys as unified shipsets. This bundling is displacing component-level procurement through fragmented MRO channels. The shift is most visible among US network carriers retrofitting domestic narrow-body fleets, where single-source accountability reduces configuration risk and simplifies post-delivery warranty claims.
Commercial Aircraft Overhead Stowage Bins Market Segmentation
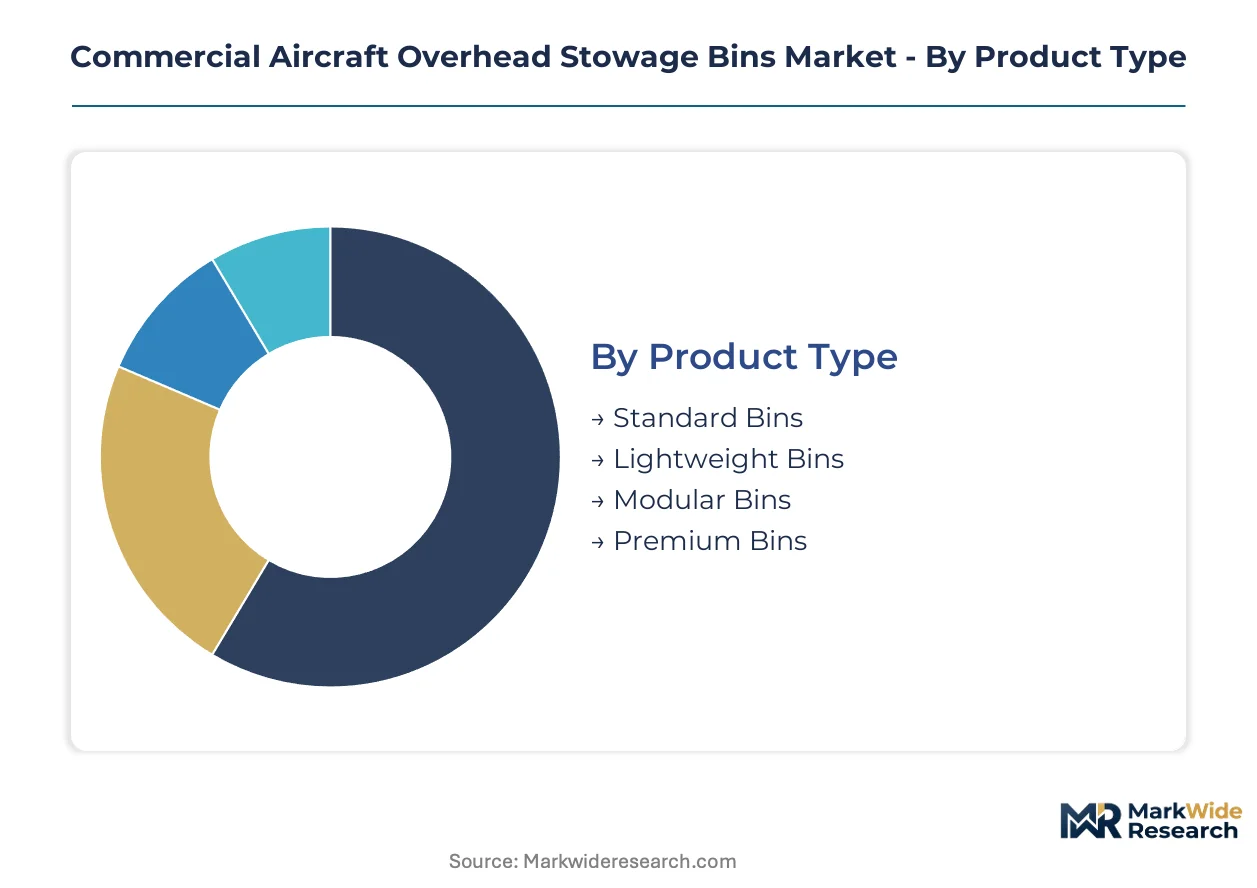
Retrofit cycles and material substitution dynamics create divergent growth paths across product configurations. Fleet operators prioritize segments that reconcile immediate weight savings with regulatory compliance timelines.
Product Type:
Upgrade and replacement cycles favor architectures that minimize downtime while maximizing volumetric gains per passenger seat.
- Standard Bins:Fixed aluminum structures dominate legacy narrow-body retrofits where FAA 14 CFR Part 25 flammability deadlines force rapid replacement schedules. Demand concentrates among US regional carriers with aging 737-700 and A319 fleets facing compressed compliance windows.
- Lightweight Bins:Thermoplastic composite shells reduce installed weight versus legacy aluminum by 25-30 percent. European operators under EU Green Deal emissions targets specify these for A320neo line-fit programs to secure mass-reduction credits toward CO2 compliance obligations.
- Modular Bins:Reconfigurable volume systems enable 48-hour cabin density switches between premium and economy layouts. IndiGo and Air India specify these for rapid-turnaround narrow-body operations.
- Premium Bins:Enhanced finish and integrated LED lighting address full-service carrier differentiation requirements on long-haul wide-body routes.
Volume placements concentrate in Standard Bins; the faster expansion belongs to Modular Bins.
Material:
Cost tiers separate procurement patterns between fuel-economy-focused operators and acquisition-budget-constrained programs.
- Aluminum:Legacy alloy grades retain residual demand in emerging-market retrofit channels where MRO tooling investments and repair station certifications create switching friction. African and Southeast Asian carriers prioritize interchangeability over lifecycle fuel savings.
- Composite:Carbon fiber prepreg and thermoplastic matrices now lead line-fit specifications for 737 MAX and A320neo family platforms. Automated fiber placement cuts production cycle times for complex crown-area geometries.
- Plastic:Injection-molded thermoplastics serve secondary stowage applications and regional aircraft weight classes below 90-seat capacity.
- Steel:Reinforced mounting brackets and hinge hardware retain niche use in high-load pivot mechanisms.
Procurement volume clusters in Composite; Plastic gains share fastest in sub-100-seat regional segments.
End User:
Customer type determines specification complexity and contract duration structures across the supply base.
- Commercial Airlines:Network carriers and low-cost operators generate the dominant revenue share through multi-year outfitting contracts. Southwest and Ryanair operational models maximize ancillary fee revenue through expanded bin volume per passenger seat.
- Cargo Carriers:Converted freighter programs require reinforced structures for crew rest compartment stowage on long-haul routes.
- Private Jets:Custom interiors for Gulfstream and Dassault platforms demand premium finishes with compressed lead times.
- Charter Services:Seasonal operators prioritize rapid reconfiguration capability over fixed architectural investments.
Contract value concentrates with Commercial Airlines; Charter Services show the steepest expansion trajectory as post-pandemic leisure aviation rebounds.
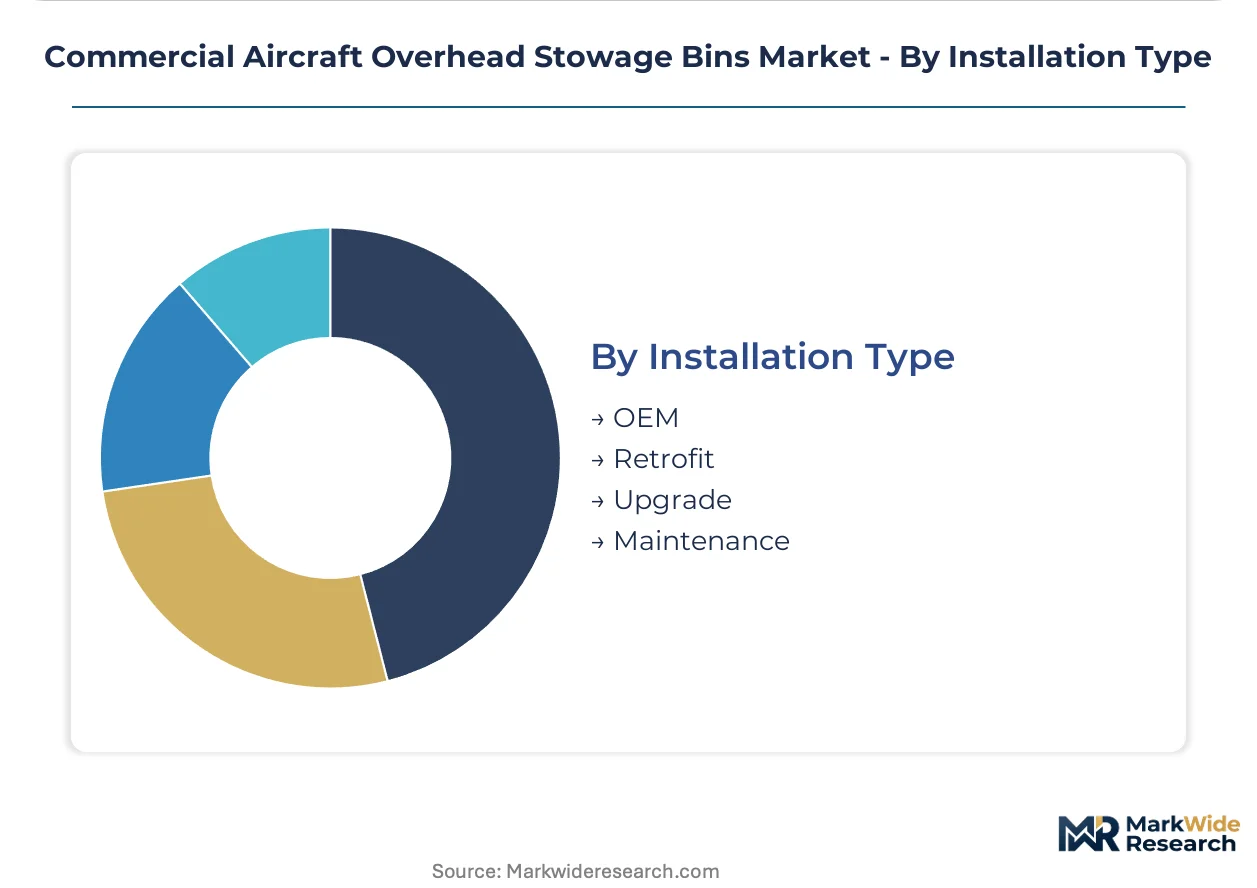
Installation Type:
Supply concentration among OEM airframers locks certain channels while aftermarket independence sustains retrofit specialists.
- OEM:Boeing and Airbus captive sourcing agreements govern 737 MAX and A320neo family line-fit programs. Diehl Aviation and Safran leverage integrated cabin systems portfolios to capture multi-year shipset contracts.
- Retrofit:Third-party MRO providers and independent completion centers serve operators outside OEM direct channels. FAA DER approval timelines extend four to six months for 16g dynamic seat integration certification.
- Upgrade:Mid-life cabin refresh programs combine bin replacement with LED lighting and in-flight entertainment retrofits.
- Maintenance:Scheduled inspection intervals drive replacement of damaged panels and latch mechanisms.
Revenue concentration sits with OEM; Retrofit channels climb fastest as narrow-body fleet age profiles deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber prepreg manufacturing clusters in Japan and Germany anchor composite supply chains for lightweight bin production, while FAA and EASA regulatory timelines drive retrofit demand concentration in North America and Western Europe.
United States
Major carriers retrofit narrow-body fleets with composite alternatives to meet FAA 14 CFR Part 25 flammability mandates. The agency's tightening smoke toxicity standards accelerate replacement schedules for aging aluminum inventories. Seattle-Tacoma aerospace corridor hosts tier-one integrators supplying Boeing 737 MAX line-fit programs.
Germany
Lufthansa Group and Eurowings specify mass-reduction credits toward EU Green Deal CO2 compliance obligations. EASA CS-25 Amendment 25-148 flammability protocols narrow approved vendor bases for thermoplastic components. Hamburg's aircraft completion centers specialize in rapid-turnaround modular bin reconfigurations for seasonal density shifts.
China
COMAC C919 ramp-up drives line-fit demand for CAAC-certified cabin systems. GB standards for interior materials shape market access for foreign suppliers serving domestic programs. Shanghai Pudong aerospace zone concentrates joint-venture fabrication facilities serving both indigenous and imported airframe programs.
India
IndiGo and Air India order backlogs create sustained demand for modular architectures supporting rapid cabin reconfiguration. Directorate General of Civil Aviation type certification alignment with FAA standards streamlines import approvals. Bengaluru and Hyderabad maintenance hubs expand third-party retrofit capacity for narrow-body fleet upgrades.
France
Airbus A320neo family production sustains captive sourcing agreements with integrated cabin systems providers. ANSM oversight of aerospace material qualifications extends procurement lead times for non-pre-certified alternatives. Toulouse-Blagnac aerospace cluster anchors European line-fit engineering and certification expertise.
Commercial Aircraft Overhead Stowage Bins Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart-bin sensor integration and aftermarket retrofit specialization. The vendor base separates into three tiers: full-cabin integrators capturing multi-year shipset contracts, composite specialists leveraging automated fiber placement capabilities, and regional MRO providers serving fragmented retrofit channels. Dominant competitive moves include strategic partnerships between bin fabricators and airframe OEMs, plus backward integration into carbon fiber prepreg supply to secure margin predictability.
Among European-integrated cabin systems providers, Safran and Diehl Aviation exemplify the full-cabin integrator archetype. FACC AG represents the composite specialist tier with Austrian-based manufacturing heritage. These three anchors illustrate how geographic concentration near major airframe assembly sites reinforces competitive positioning through logistics proximity and joint certification workflows.
| Leading Market Players |
|---|
| Safran |
| FACC AG |
| JAMCO Corporation |
| Airbus SE |
| Collins Aerospace |
| Diehl Aviation |
| Spirit AeroSystems |
| AVIC Cabin Systems |
| Boeing |
| Others |
Value Chain & Pricing Dynamics
Full-service carrier procurement concentration around multi-year shipset contracts anchors a value-based pricing model where total cabin integration depth commands premium positioning over standalone component supply. Boeing and Airbus captive sourcing agreements compress margin negotiation leverage for tier-two fabricators serving retrofit channels.
Pricing Analysis
High-volume OEM line-fit programs trade margin for guaranteed offtake, while low-volume aftermarket retrofits capture price premiums through compressed FAA DER approval timelines. Price differentiation rests on EASA CS-25 pre-certification status and automated fiber placement manufacturing capability. Cost compression in legacy aluminum tiers intensifies as flammability mandate deadlines force rapid replacement schedules. Regional carriers with aging 737-700 fleets exhibit highest price sensitivity; network carriers bundling full cabin shipsets show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle Boeing and Airbus line-fit demand through Seattle-Tacoma and Toulouse-Blagnac aerospace corridor concentration. Carbon fiber prepreg supply draws from Japan and Germany manufacturing clusters, while thermoplastic resin feedstock rests on petrochemical complexes in the US Gulf Coast and Singapore. Single-source vulnerability around aerospace-grade PAN precursor creates supply chain risk. Distribution runs through tier-one integrators capturing multi-year outfitting contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
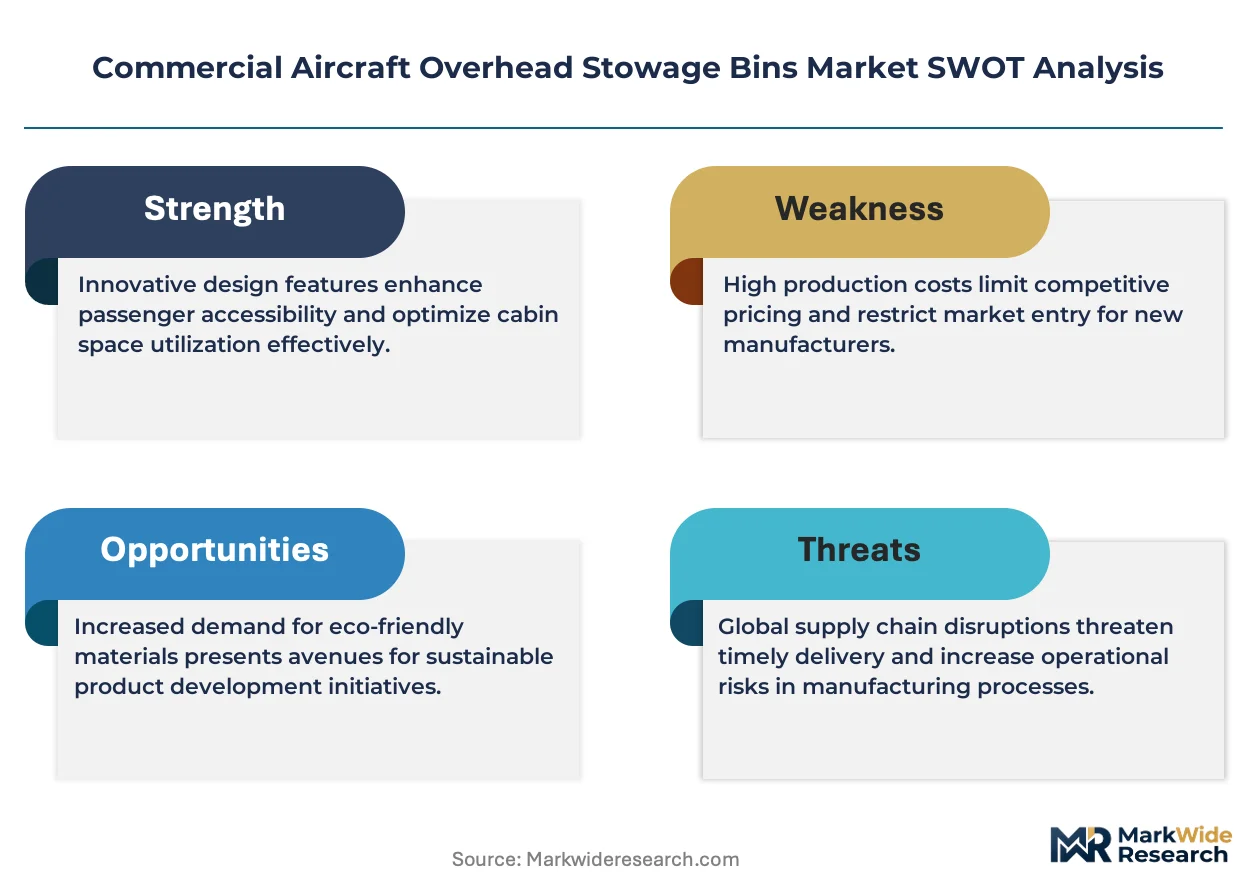
This market is a vertical-integration race where backward control over carbon fiber prepreg supply separates margin-stable incumbents from price-vulnerable competitors.
For Market Incumbents: Cement position through captive sourcing agreements with Boeing and Airbus for 737 MAX and A320neo family platforms. Deepen automated fiber placement capacity in Germany and Japan to offset carbon fiber prepreg cost volatility. Lock in EASA CS-25 pre-certification status before Amendment 25-148 narrows approved vendor bases further. For New Entrants and Emerging Players: FAA 14 CFR Part 25 flammability tightening in the United States opens a window for drop-in composite replacements maintaining legacy aluminum mounting interfaces. Target US regional carriers with compressed compliance windows for 737-700 and A319 retrofit programs. Pursue DER-approved 16g dynamic seat integration certification as differentiated entry credential. For Investors and Strategic Acquirers: The window for entry favors composite specialists with automated fiber placement capabilities and existing EASA pre-certification. Long-term viability hinges on consolidation toward full-cabin integrators capable of unified shipset delivery. Watch for RFID-integrated smart bin adoption rates as inflection indicator for embedded intelligence premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Secures margin predictability against PAN precursor price swings for tier-one fabricators. |
| EASA CS-25 Pre-Certification Investment | Qualifies material stacks before Amendment 25-148 narrows approved vendor bases for European operators. |
| RFID-Integrated Smart Bin Development | Enables real-time occupancy monitoring and predictive maintenance analytics for premium positioning. |
| Modular Architecture Engineering | Supports 48-hour cabin density switches between premium and economy layouts for rapid-turnaround carriers. |
| India Narrow-Body Line-Fit Partnership | Captures IndiGo and Air India order backlogs through DGCA-aligned certification pathways. |
Study Parameters
FAA airworthiness directive filings, EASA certification databases, and OEM annual reports formed the secondary backbone for market sizing and regulatory timeline mapping. Primary interviews with airline engineering directors, tier-one cabin integrator procurement leads, composite manufacturing R&D heads, and MRO station certification managers validated production capacity claims and retrofit demand patterns. Bottom-up fleet age analysis and top-down OEM delivery projections were triangulated against customs data for carbon fiber prepreg trade flows.
Historical narrow-body retrofit cycle analysis established baseline replacement rates across aluminum and composite material transitions. The analytical framework modeled product type, material grade, installation channel, and end-user carrier archetype across the projection horizon. CAGRs were derived from weighted fleet expansion schedules and regulatory compliance deadline clustering. Forecast inputs incorporated EU Green Deal emissions weight targets and CAAC type certification alignment timelines for COMAC programs.
Caveats apply where FAA flammability test protocol revisions or carbon fiber supply disruptions could materially shift the outlook. Forecasts reflect assumptions around OEM delivery schedules and airline capex recovery trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Military Rotorcraft Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Aircraft Leasing Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Airplane Ailerons Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
GCC Business Jet Market
Aircraft
Aero Wing Market