
 Japan Aviation Market | 2026-2036
Japan Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aviation Market Outlook
JIS Q 9100 certification is collapsing the supplier base eligible for defense and commercial tier-one contracts. Mitsubishi Heavy Industries leverages its integrated airframe and engine capabilities to anchor Japan's F-X fighter program. Kawasaki Heavy Industries sustains helicopter and cargo aircraft production through its Saitama and Gifu facilities. ShinMaywa Industries specializes in amphibious aircraft and special-mission platforms, occupying a narrow but protected niche.
Japan aviation encompasses the design, manufacture, maintenance, and operation of crewed and uncrewed aerial vehicles certified for national airspace, with turbine engines typically rated between 2,000 and 90,000 pounds thrust and composite airframe content exceeding fifty percent on newer platforms. Commercial aircraft dominates product type revenue, though UAVs represent the fastest-expanding segment as METI relaxes beyond-visual-line-of-sight flight rules. Passenger transport leads application demand, while military operations commands premium margins under Japan's defense budget expansion.
METI, the Japan Civil Aviation Bureau under MLIT, and PMDA-equivalent airworthiness inspectors govern certification timelines, operational standards, and import equipment approvals. These bodies are compressing type certification cycles for electric propulsion prototypes while tightening noise and emissions thresholds around Osaka Kansai and Tokyo Haneda corridors. Stakeholders must track how revised offset credit rules and sustainable aviation fuel mandates reshape fleet procurement criteria before the next defense and commercial procurement waves lock in supplier selections.
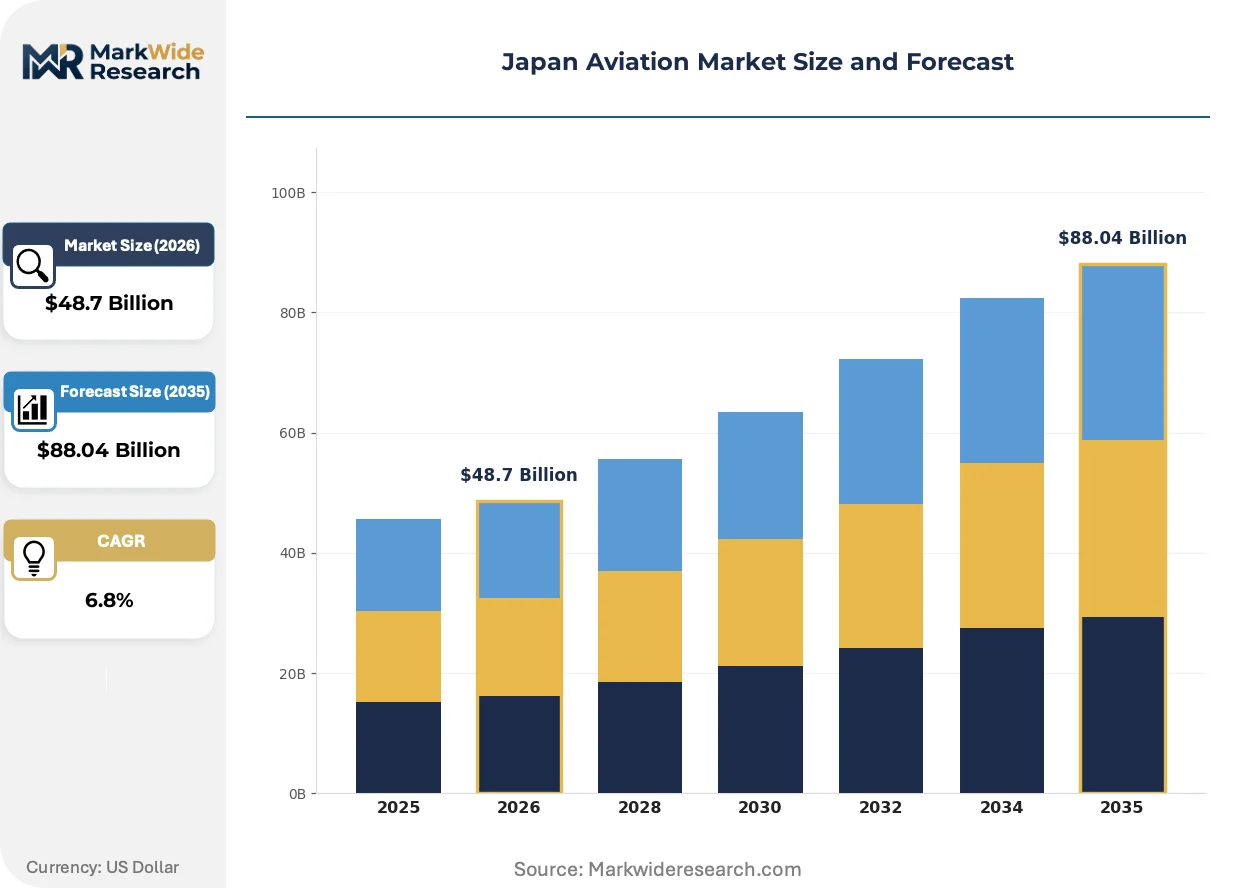
Market Dynamics
Fleet renewal programs at domestic carriers are compressing procurement cycles while METI accelerates electric propulsion certification timelines, creating simultaneous demand pull and supply-side capability strain across Japan's aviation manufacturing base.
Growth Catalysts
- JIS Q 9100 Certification Consolidation:The defense and commercial tier-one supplier base is narrowing as certification requirements intensify, concentrating contract awards among qualified domestic manufacturers.
- Kanto Corridor Demand Density:Passenger transport demand clusters around Tokyo and surrounding prefectures, anchoring route profitability and fleet deployment decisions for regional operators.
- Composite Airframe Adoption:Newer platforms exceed fifty percent composite content, reducing weight and fuel burn while extending maintenance intervals for operating carriers.
Market Restraints
- Turbine Engine Import Dependence:Thrust ratings between 2,000 and 90,000 pounds remain concentrated among foreign suppliers, exposing domestic airframers to currency volatility and delivery scheduling risk.
- Certification Timeline Compression:MLIT's Japan Civil Aviation Bureau is tightening operational certification windows, stretching engineering resources and delaying revenue recognition for prototype developers.
- Specialized Labor Scarcity:Airworthiness inspectors and composite repair technicians face supply constraints relative to fleet expansion targets, inflating training and retention costs.
Strategic Opportunities
- Beyond-Visual-Line-of-Sight UAV Rules:METI relaxation of flight restrictions is opening commercial drone applications in infrastructure inspection and cargo delivery across rural prefectures.
- Sustainable Aviation Fuel Mandates:Revised offset credit rules are reshaping procurement criteria, creating first-mover advantage for domestic suppliers with certified SAF integration capabilities.
- Defense Budget Expansion:Military operations command premium margins as Japan's fighter and special-mission aircraft programs advance, anchoring long-term production schedules at integrated manufacturers.
Industry Challenges
- Electric Propulsion Integration Complexity:Battery thermal management and motor-airframe interface certification are extending development timelines for next-generation prototypes.
- Cross-Program Engineering Resource Competition:Simultaneous commercial fleet renewal and F-X fighter development are straining specialized design talent across Saitama and Gifu manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aviation Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Business Jets, Helicopters, UAVs Application: Passenger Transport, Cargo Transport, Military Operations, Surveillance Technology: Aerospace Engineering, Avionics, Propulsion Systems, Navigation Systems End User: Airlines, Government Agencies, Private Operators, Defense Contractors |
| Companies Covered | JAMCO Corp, Showa Aircraft, Mitsubishi Heavy Industries, Ltd., SMBC Aviation Capital, Sumitomo Precision Products Co. Ltd, Kawasaki Heavy Industries, Ltd., ShinMaywa Industries, Peach Aviation, Subaru Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aviation Market Strategic Shifts
Technological substitution in propulsion systems, regulatory acceleration of certification frameworks, and procurement model evolution toward performance-based contracting are restructuring competitive positioning across Japan's aviation value chain.
Advanced composite manufacturing processes are supplanting traditional aluminum airframe construction in narrow-body and regional aircraft programs. Domestic carriers deploying these platforms are capturing extended maintenance intervals and reduced fuel burn. The shift is compressing supplier qualification timelines as airframers demand demonstrated composite repair capabilities from maintenance providers.
METI's revised noise and emissions thresholds around Osaka Kansai and Tokyo Haneda corridors are forcing accelerated fleet retirement decisions. Operating carriers must either retrofit existing aircraft or accelerate new platform acquisitions to maintain slot access. The policy pressure falls most heavily on regional operators with aging turboprop fleets serving secondary routes.
Carrier procurement departments are unbundling after-sales service contracts from initial aircraft acquisitions, creating standalone competition for maintenance, repair, and overhaul providers. Independent MRO specialists in the Kanto region are capturing long-term service agreements previously held by original equipment manufacturers. This behavior shift is most visible among low-cost carriers optimizing unit economics on high-frequency domestic routes.
Japan Aviation Market Segmentation
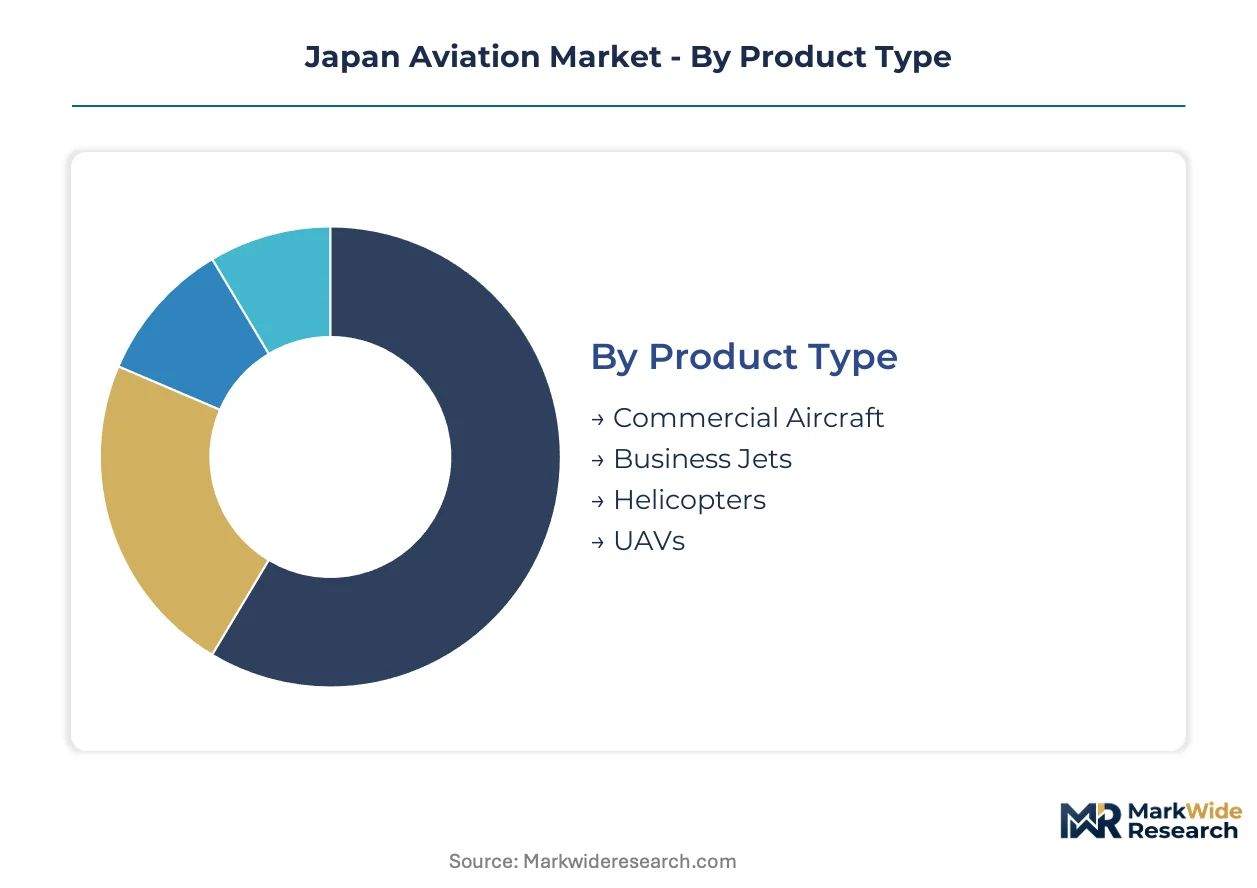
Segmentation reveals how procurement priorities diverge between domestic carriers upgrading narrow-body fleets and defense contractors anchoring long-term fighter programs. Understanding these splits exposes where engineering resources concentrate and where certification bottlenecks bite hardest.
Product Type:
Domestic demand centers on platforms serving the Kanto corridor and defense programs, while export potential concentrates in specialized categories where Japanese manufacturers hold protected niches.
- Commercial Aircraft:Narrow-body and regional jets dominate fleet renewal programs at Japan Airlines and ANA Holdings. Composite airframe content exceeding fifty percent reduces fuel burn on high-frequency Tokyo-Osaka routes while extending maintenance intervals.
- UAVs:Beyond-visual-line-of-sight rule relaxations by METI are opening commercial applications in infrastructure inspection across rural prefectures. Agricultural spraying and last-mile cargo delivery in Hokkaido and Tohoku regions are pulling demand fastest.
- Business Jets:Corporate shuttle services connecting Tokyo with manufacturing hubs in Aichi and Osaka sustain a thin but stable order book.
- Helicopters:Kawasaki Heavy Industries' Saitama and Gifu facilities anchor domestic production for emergency medical services and utility operations.
Commercial Aircraft commands the established base. The steepest expansion runs through UAVs.
Application:
Cost tier stratification separates premium-margin military programs from volume-driven passenger operations where fuel efficiency determines fleet selection.
- Passenger Transport:Dense demand clustering around Tokyo, Osaka, and Fukuoka corridors drives narrow-body procurement cycles. Slot constraints at Haneda and Kansai airports force accelerated retirement of aging turboprop fleets.
- Military Operations:Japan's F-X fighter program and maritime patrol aircraft sustain premium-margin production at integrated manufacturers. Defense budget expansion locks in multi-year procurement schedules with stringent JIS Q 9100 certification requirements.
- Cargo Transport:E-commerce fulfillment networks are expanding freighter conversions and dedicated cargo operations on secondary domestic routes.
- Surveillance:Coast Guard and disaster response agencies deploy specialized platforms for territorial monitoring and humanitarian missions.
Passenger Transport anchors volume scale. Military Operations captures margin concentration.
Technology:
Supply concentration for high-thrust turbine engines creates import dependence, while domestic capabilities cluster in airframe integration and advanced materials.
- Aerospace Engineering:Composite manufacturing processes and structural design capabilities concentrate at Mitsubishi Heavy Industries and Subaru's aerospace division. Airframe integration expertise supports both commercial and defense programs.
- Propulsion Systems:Thrust ratings from 2,000 to 90,000 pounds remain concentrated among foreign suppliers, exposing domestic airframers to currency volatility and delivery scheduling risk on fleet renewal timelines.
- Avionics:Flight control systems and cockpit integration are deepening collaboration between Japanese electronics specialists and foreign tier-one suppliers.
- Navigation Systems:GPS augmentation and precision approach capabilities are being adapted for challenging terrain operations in mountainous prefectures.
Aerospace Engineering holds domestic capability depth. Propulsion Systems faces the steepest import exposure.
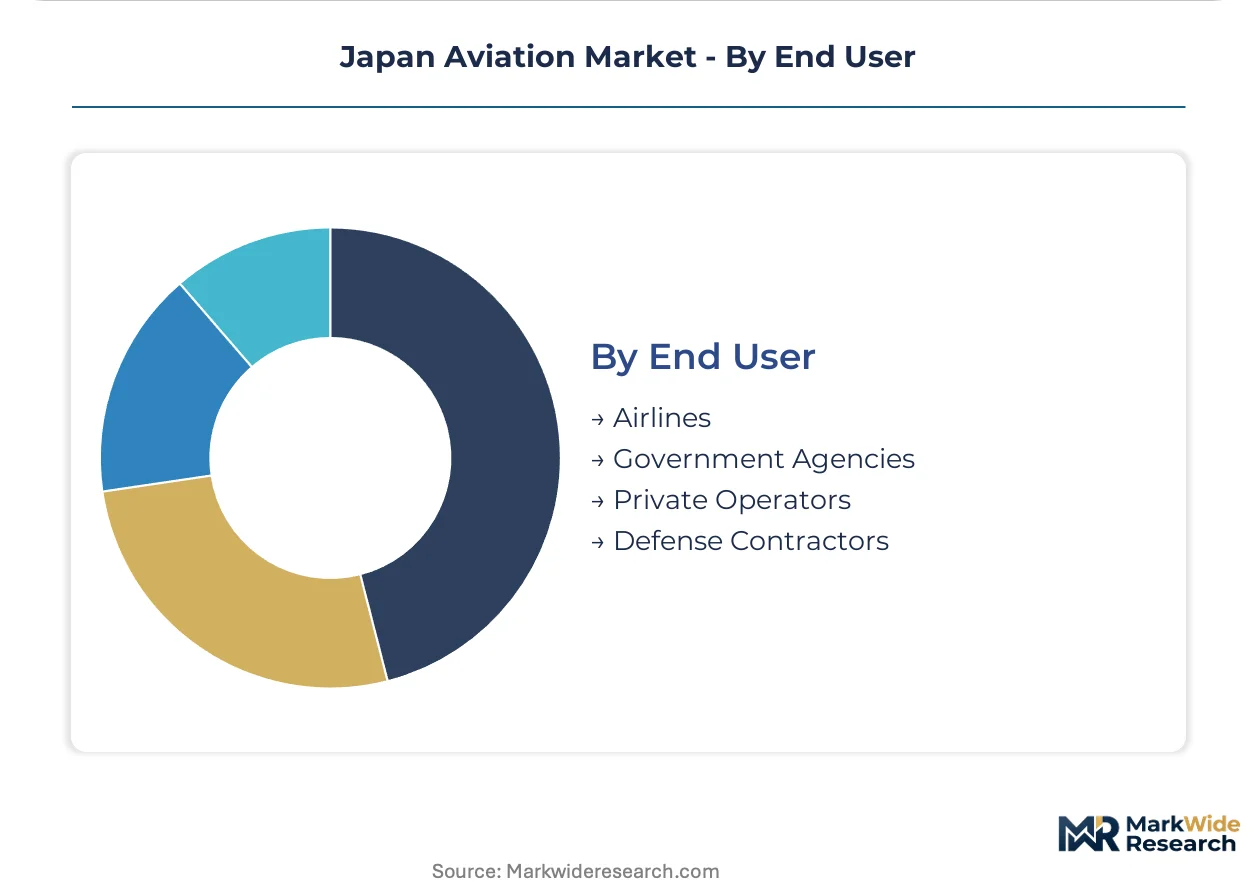
End User:
Customer type determines procurement rigor, with defense contractors and flag carriers imposing certification standards that exclude smaller suppliers.
- Airlines:ANA Holdings and Japan Airlines drive fleet renewal through performance-based contracting that unbundles after-sales service from initial acquisitions. Low-cost carriers in the Skymark and Jetstar Japan networks are capturing standalone MRO agreements.
- Defense Contractors:Mitsubishi Heavy Industries and Kawasaki Heavy Industries integrate subcontractor tiers under JIS Q 9100 mandates, narrowing the qualified supplier base for airframe and engine components.
- Government Agencies:Japan Coast Guard and firefighting authorities procure specialized platforms for search-and-rescue and disaster response missions.
- Private Operators:Corporate flight departments and agricultural services sustain fragmented demand for helicopters and light utility aircraft.
Airlines and Defense Contractors concentrate procurement scale. Government Agencies represent the most specialized requirement set.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's sustainable aviation fuel mandates and defense procurement incentives are redistributing manufacturing capacity across Japan's industrial corridors. Domestic carriers are concentrating fleet renewal decisions around corridor-specific slot constraints and noise regulations.
Kanto/Tokyo
Passenger transport demand clusters around Haneda and Narita airports, driving narrow-body procurement cycles at ANA Holdings and Japan Airlines. MLIT's Japan Civil Aviation Bureau enforces strict noise thresholds that accelerate turboprop retirements on secondary routes. Aerospace engineering capabilities concentrate in Saitama Prefecture, where Kawasaki Heavy Industries sustains helicopter and cargo aircraft production.
Kansai/Osaka
Slot constraints at Kansai International Airport force regional operators into fleet modernization decisions. METI's emissions thresholds around the Osaka corridor are reshaping procurement criteria for sustainable aviation fuel integration. Manufacturing activity clusters in Osaka and Hyogo prefectures, where precision component suppliers serve both commercial and defense programs.
Chubu/Nagoya
Mitsubishi Heavy Industries anchors airframe integration capabilities in Aichi Prefecture, supporting Japan's F-X fighter program and commercial composite manufacturing. The region's supplier base faces JIS Q 9100 certification pressure that narrows qualified tier-one contractors. Composite repair technicians and airworthiness inspectors face supply constraints relative to program timelines.
Kyushu
ShinMaywa Industries specializes in amphibious aircraft production from its Nagasaki facilities, occupying a protected niche in special-mission platforms. Beyond-visual-line-of-sight UAV applications are expanding in rural prefectures for infrastructure inspection and agricultural spraying. Local manufacturing clusters support maritime patrol aircraft components under defense procurement schedules.
Hokkaido
Low-density route networks sustain turboprop operations as regional operators balance fleet economics against METI emissions mandates. Agricultural UAV spraying and last-mile cargo delivery applications are pulling demand fastest in Tohoku-adjacent prefectures. Cold-climate testing facilities support prototype validation for electric propulsion developers.
Japan Aviation Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with integrated conglomerates facing narrower tier-one supplier bases against fragmented component specialists. The market structure concentrates around defense-anchored manufacturers with JIS Q 9100 credentials and commercial fleet service providers unbundling after-sales contracts. Three archetypes dominate: integrated airframe-engine conglomerates, precision component specialists, and independent MRO operators. Competitive moves center on backward integration into composite supply chains and geographic expansion through standalone service agreements.
Among integrated manufacturers, Mitsubishi Heavy Industries, Ltd., Kawasaki Heavy Industries, Ltd., and ShinMaywa Industries occupy positions spanning defense programs and specialized commercial platforms. Mitsubishi Heavy Industries exemplifies the conglomerate archetype with combined airframe and propulsion capabilities. Kawasaki Heavy Industries represents integrated production across helicopter and cargo segments. ShinMaywa Industries anchors the narrow specialization tier through amphibious and special-mission focus. These three entities sit within the qualified supplier base that JIS Q 9100 consolidation has compressed.
| Leading Market Players |
|---|
| JAMCO Corp |
| Showa Aircraft |
| Mitsubishi Heavy Industries, Ltd. |
| SMBC Aviation Capital |
| Sumitomo Precision Products Co. Ltd |
| Kawasaki Heavy Industries, Ltd. |
| ShinMaywa Industries |
| Peach Aviation |
| Subaru Corporation |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month turbine engine lead times from foreign suppliers compress procurement flexibility and amplify pricing power for JIS Q 9100-certified domestic manufacturers who can guarantee delivery certainty. This inventory constraint tightens most acutely for regional operators balancing fleet renewal against METI emissions deadlines, forcing acceptance of premium pricing on accelerated delivery schedules.
Pricing Analysis
Certification level creates the primary spread between JIS Q 9100-qualified tier-one suppliers and uncertified component specialists. Pricing stratifies across defense-grade, commercial-aerospace, and general-aviation tiers based on audit stringency and traceability documentation. Cost compression in the general-aviation tier intensifies because low-cost carriers unbundle after-sales service and drive component sourcing to independent MRO providers. Regional operators with aging turboprop fleets exhibit the highest price sensitivity, while defense contractors under F-X program schedules show minimal elasticity.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes inflate inbound logistics costs for titanium alloys and specialized composite prepregs. Manufacturing concentration rests on Japan, the United States, and France for critical propulsion and avionics inputs. Domestic airframers draw from single-source dependencies on foreign turbine engine suppliers rated between 2,000 and 90,000 pounds thrust. Tariff exposure on precision-machined components threatens margin stability at tier-two suppliers. Distribution runs through original equipment manufacturer captive networks and independent MRO specialists competing for standalone service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's aviation market sustains defensive moats through regulatory entrenchment, where JIS Q 9100 certification creates switching costs that lock qualified suppliers into multi-year defense and commercial procurement cycles.
For Market Incumbents: Compound certification advantages by deepening composite repair capabilities and securing exclusive after-sales agreements with ANA Holdings and Japan Airlines. Electric propulsion startups threaten traditional supplier relationships through METI-accelerated certification timelines. Backward integration into carbon fiber supply chains defends margin position against raw material volatility. For New Entrants and Emerging Players: Differentiate on beyond-visual-line-of-sight UAV integration for infrastructure inspection across Hokkaido and Tohoku prefectures. Agricultural spraying and last-mile cargo delivery in rural corridors represent the most penetrable application segment. Partner with regional operators seeking to bypass OEM service premiums through independent MRO arrangements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrials with stranded aerospace divisions lacking JIS Q 9100 credentials. Long-term viability hinges on defense budget continuity and commercial fleet replacement cycles. Monitor METI electric propulsion certification acceleration as the signal indicating inflection in supplier qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Q 9100 Certification Investment | Defense and commercial tier-one contract eligibility concentrates among qualified domestic manufacturers. |
| Composite Manufacturing Scale-Up | Mitsubishi Heavy Industries and Subaru anchor airframe integration capabilities for next-generation platforms. |
| Beyond-Visual-Line-of-Sight UAV Development | METI rule relaxations open commercial applications in infrastructure inspection and agricultural spraying. |
| Sustainable Aviation Fuel Integration | Revised offset credit rules reshape procurement criteria for domestic carriers at Haneda and Kansai. |
| Independent MRO Service Expansion | Low-cost carriers unbundle after-sales contracts, creating standalone competition previously held by OEMs. |
Study Parameters
Initial hypotheses were tested against primary input from fleet procurement directors at ANA Holdings and Japan Airlines, airworthiness inspectors at MLIT's Japan Civil Aviation Bureau, and composite manufacturing engineers at Mitsubishi Heavy Industries and Kawasaki Heavy Industries, then refined through secondary validation. Regulatory filing databases, customs trade records for turbine engine imports, and defense procurement announcements supplied quantitative anchors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition separated volume drivers from price effects across product type, application, and end-user dimensions. Aerospace engineering capabilities, propulsion system import dependencies, and avionics integration complexity informed segment-specific growth trajectories. CAGRs were derived from fitted trend lines applied to historical procurement data and projected fleet replacement schedules. Electric propulsion certification timelines and sustainable aviation fuel mandate implementation paced the forecast sensitivity analysis.
Material uncertainties — yen volatility affecting turbine engine import costs, MLIT certification timeline compression, and defense budget allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about METI regulatory acceleration and domestic carrier fleet renewal commitments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Tanker Aircraft Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Strategic Bomber Market
Aircraft
UK Military Aviation Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Europe General Aviation Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
North America General Aviation Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Aircraft Galley Systems Market
Aircraft
North America Aircraft Manufacturing Market