
 Aviation Market | 2026-2036
Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Market Analysis
Sustainable propulsion architecture is tilting development priorities across the aviation technology stack. The Boeing Company anchors its position through advanced composite manufacturing scale in wide-body platforms. Airbus SE differentiates via integrated narrow-body family architectures optimized for fuel efficiency. RTX Corporation leverages its three-engineering-centre model to sustain propulsion R&D intensity across commercial and defence applications.
Aviation encompasses the design, manufacture, operation, and maintenance of heavier-than-air vehicles powered by jet, turboprop, or piston engines, with airframe structures typically exceeding 12,500 pounds maximum takeoff weight for commercial certification categories. Its primary commercial purpose is the time-deficient transport of passengers and cargo across distances where surface modes impose prohibitive opportunity costs. Commercial aircraft commands the dominant revenue pool as fleet replacement cycles accelerate, while drones represent the fastest-expanding segment driven by beyond-visual-line-of-sight regulatory liberalisation. Propulsion systems concentrate margin capture as original equipment manufacturers enforce intellectual property control over high-bypass turbofan architectures.
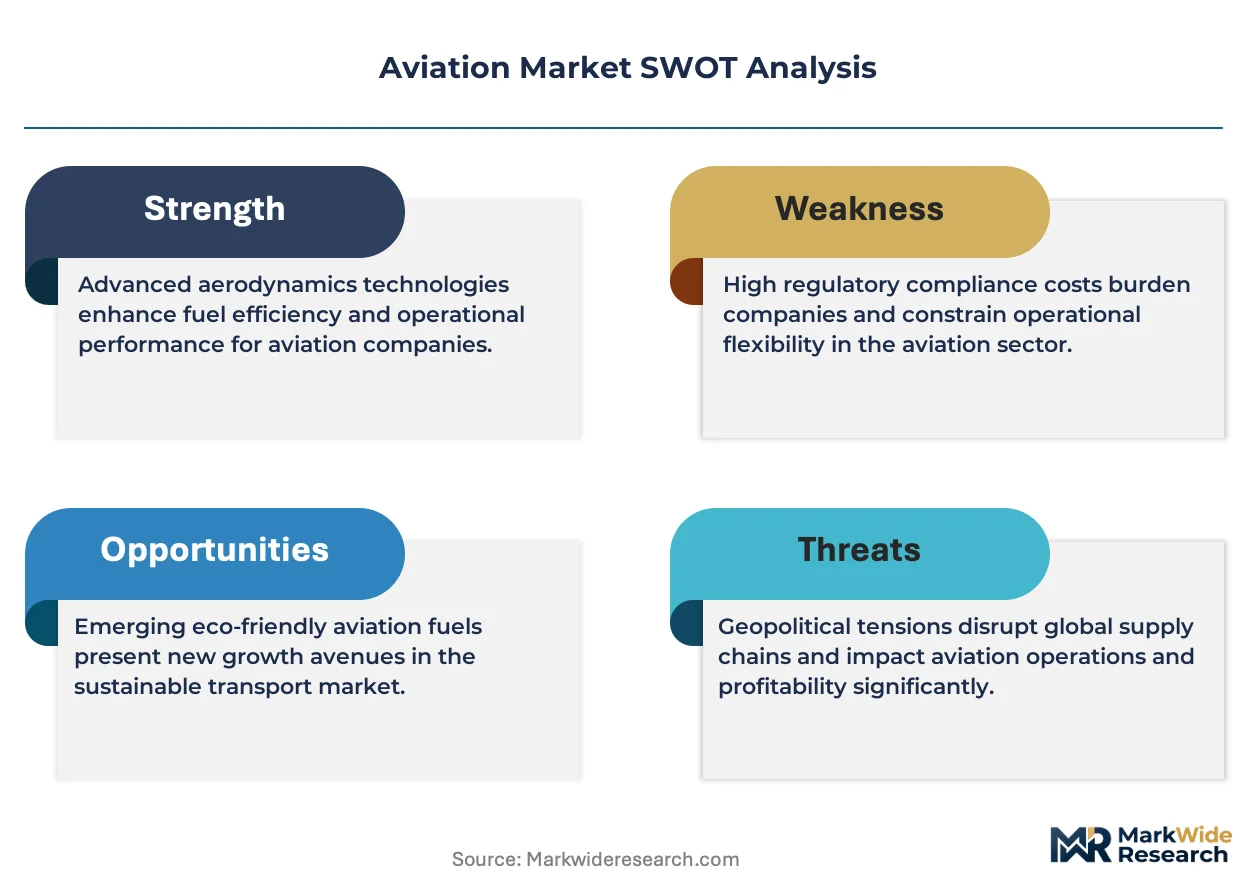
The FAA mandates airworthiness certification under 14 CFR Part 25 standards, while the EU Green Deal's ReFuelEU Aviation regulation progressively binds fuel suppliers to synthetic blending obligations. EASA's evolving CS-25 framework shapes product access for non-European manufacturers seeking European operator placement. Stakeholders must monitor how ICAO's Carbon Offsetting and Reduction Scheme for International Aviation interacts with unilateral national blending mandates to determine compliance pathway economics.
Market Dynamics
The aviation sector confronts a structural inflection where sustainable aviation fuel mandates from the EU's ReFuelEU Aviation regulation are forcing fleet-level reconfiguration decisions. Airlines must now integrate synthetic fuel blending obligations into 15-year procurement horizons, compressing the economic viability window for conventional turbofan architectures.
Growth Catalysts
- ReFuelEU Aviation Mandates:The EU's progressive synthetic fuel blending obligations create guaranteed offtake demand for sustainable aviation fuel producers, locking in investment certainty for biorefinery scale-up.
- Narrow-body Fleet Density:High-frequency domestic route networks across India, Indonesia, and Vietnam concentrate aircraft utilization rates above regional averages, accelerating replacement cycles for fuel-efficient next-generation platforms.
- Open-rotor Architecture R&D:Propulsion manufacturers are redirecting engineering resources toward unducted fan designs that promise double-digit fuel burn reductions over current high-bypass turbofans.
Market Restraints
- Sustainable Aviation Fuel Cost Premium:HEFA-SPK and FT-SPK pathways currently trade at multiples of Jet A-1 kerosene, compressing operating margins for carriers without pass-through pricing power.
- Titanium Sponge Supply Concentration:Aerospace-grade titanium sponge production clusters in Russia and China, exposing Western airframe manufacturers to geopolitical supply disruption risks.
- Airframe Certification Timelines:FAA Part 25 and EASA CS-25 validation cycles for novel propulsion integrations now extend beyond 48 months, delaying revenue recognition for clean-sheet designs.
Strategic Opportunities
- Urban Air Mobility Corridors:Beyond-visual-line-of-sight regulatory frameworks in the United States and United Arab Emirates are opening controlled airspace for electric vertical takeoff and landing cargo networks.
- Digital Twin Maintenance:Predictive analytics platforms that model component degradation in real time enable unbundled power-by-the-hour contracts, shifting aftermarket revenue from parts to data services.
- India's PLI Scheme for Drones:The country's production-linked incentive framework for unmanned aerial systems is attracting component manufacturing away from traditional East Asian supply bases.
Industry Challenges
- Aerospace Systems Integration Talent:The specialized workforce capable of certifying fly-by-wire control laws and integrated modular avionics is aging out faster than training pipelines can replenish.
- Legacy Fleet Interoperability:New sustainable propulsion architectures must maintain operational compatibility with existing ground handling infrastructure, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Market |
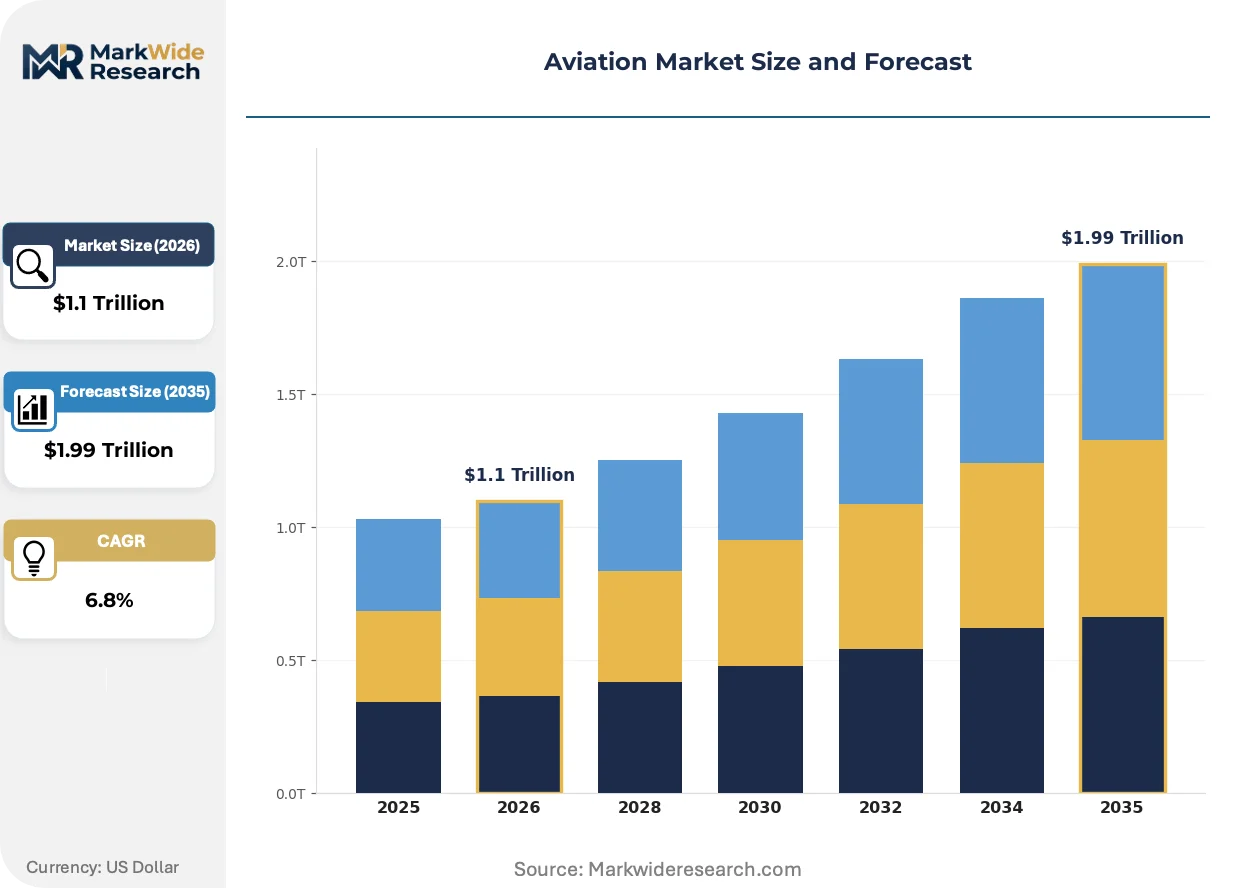
| Market Size in 2026 | $1.1 Trillion |
| Market Size in 2035 | $1.99 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Business Jets, Helicopters, Drones Technology: Avionics, Propulsion Systems, Ground Support Equipment, Navigation Systems End User: Aerospace Manufacturers, Airlines, Government, Maintenance, Repair & Overhaul (MRO) Application: Cargo Transport, Passenger Transport, Military Operations, Aerial Surveying |
| Companies Covered | Northrop Grumman Corporation, General Dynamics Corporation, The Boeing Company, Safran SA, Leonardo S.p.a., Airbus SE, RTX Corporation, TransDigm Group Incorporated, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Market Emerging Trajectories
Aviation technology stacks are undergoing forced recombination as propulsion electrification and software-defined flight control systems rewrite certification baselines. Incumbents and entrants alike must now validate airworthiness through demonstration rather than precedent.
Geared turbofan architectures with ultra-high bypass ratios are rendering obsolete conventional direct-drive fan systems in the narrow-body segment. Airlines operating high-cycle domestic networks are specifying these powerplants for new deliveries, accepting higher acquisition costs to secure 16% fuel burn advantages. The residual value compression for legacy engine types is accelerating lessor portfolio rotation.
The EU Green Deal's ReFuelEU Aviation regulation imposes binding synthetic fuel blending quotas on fuel suppliers at EU airports, rising from 2% in 2025 to 70% by 2050. This mandate forces oil majors to secure long-term offtake agreements with biorefinery developers, restructuring aviation fuel supply chains around renewable feedstock procurement rather than crude oil arbitrage. Long-haul carriers with dense European route networks face the steepest compliance cost trajectories.
Airlines are unbundling maintenance, repair, and overhaul contracts from original equipment manufacturer captivity, instead sourcing component-level services from independent MRO specialists. This disintermediation concentrates in the Asia-Pacific region where third-party workshops have achieved EASA Part 145 certification for engine module overhaul. The shift compresses OEM aftermarket margins while expanding parts manufacturer approval channels for non-proprietary components.
Aviation Market Segmentation
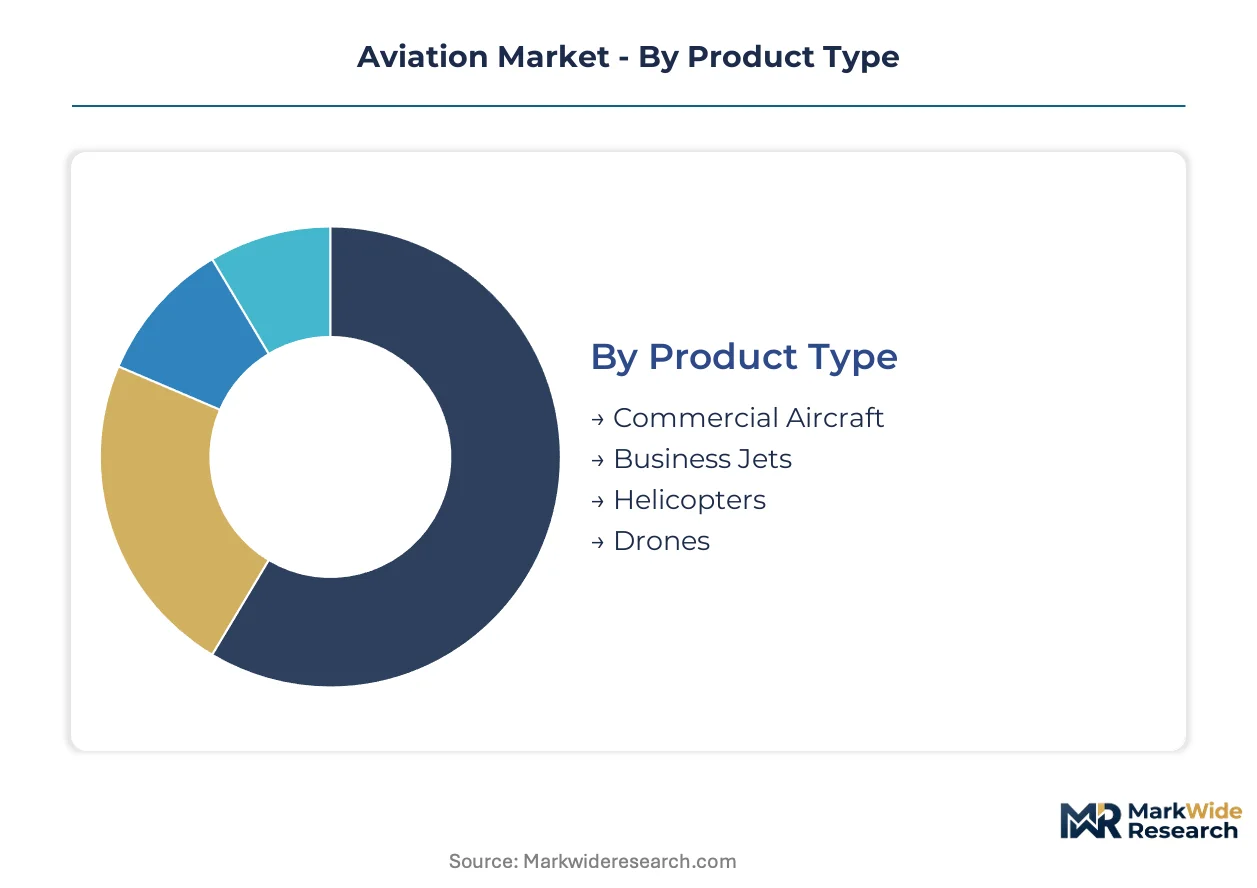
Aviation market segmentation reveals how capital allocation, regulatory pressure, and operational intensity concentrate across distinct product architectures and technology layers. Understanding these divisions exposes where procurement power accumulates and which segments face the steepest compliance cost trajectories.
Product Type:
Cost tier differentiation separates mass-market platforms from specialized mission systems, with acquisition economics and utilization intensity driving divergent fleet strategies.
- Commercial Aircraft:Narrow-body and wide-body platforms certified under FAA Part 25 and EASA CS-25 standards, optimized for high-cycle passenger and cargo operations. Fleet replacement concentrates in India, Indonesia, and Vietnam as low-cost carriers absorb next-generation fuel-efficient architectures to offset ReFuelEU Aviation blending cost premiums.
- Business Jets:Part 25-certified aircraft below 19 passenger seats, featuring bespoke cabin configurations and extended-range capabilities. Demand clusters in the United Arab Emirates and Switzerland where fractional ownership models and corporate flight departments prioritize schedule control over unit economics.
- Helicopters:Rotary-wing platforms spanning light single-engine to heavy twin-turbine configurations for utility and emergency medical services.
- Drones:Unmanned aerial systems operating under evolving beyond-visual-line-of-sight frameworks, with India's PLI scheme redirecting component manufacturing from East Asian supply bases.
Commercial Aircraft commands the established base. The steepest expansion runs through Drones.
Technology:
Application intensity varies across flight-critical systems, with certification burden and intellectual property control determining margin capture.
- Avionics:Integrated modular architectures governing flight management, communication, and surveillance functions. Airlines in the United States and Germany are specifying open-system standards to reduce OEM captivity in retrofit markets.
- Propulsion Systems:High-bypass turbofan and emerging open-rotor architectures, where RTX Corporation and GE Aerospace enforce patent control over core thermal and aerodynamic designs. R&D intensity concentrates on unducted fan configurations promising double-digit fuel burn reductions for narrow-body applications.
- Ground Support Equipment:Aircraft tugs, power units, and de-icing systems required for turnaround operations.
- Navigation Systems:GPS-augmented precision approach equipment and satellite-based augmentation systems.
Propulsion Systems captures the dominant margin pool. Avionics is gaining share fastest through fleet connectivity retrofits.
End User:
Customer type determines procurement scale, with fleet operators facing divergent regulatory exposure versus manufacturing integrators.
- Aerospace Manufacturers:Boeing, Airbus, and tier-1 integrators sourcing airframe structures and system modules. Titanium sponge supply concentration in Russia and China exposes Western producers to geopolitical disruption, accelerating alternative feedstock qualification.
- Airlines:Network carriers and low-cost operators managing fleet lifecycle economics. European operators absorb the steepest ReFuelEU Aviation compliance costs as synthetic fuel blending obligations escalate from initial thresholds toward mid-century targets.
- Government:Military and civilian agencies procuring mission-specific platforms.
- Maintenance, Repair & Overhaul (MRO):Third-party and OEM-captive service providers.
Airlines represent the volume anchor. The MRO segment is expanding most quickly as carriers disintermediate OEM aftermarket captivity.
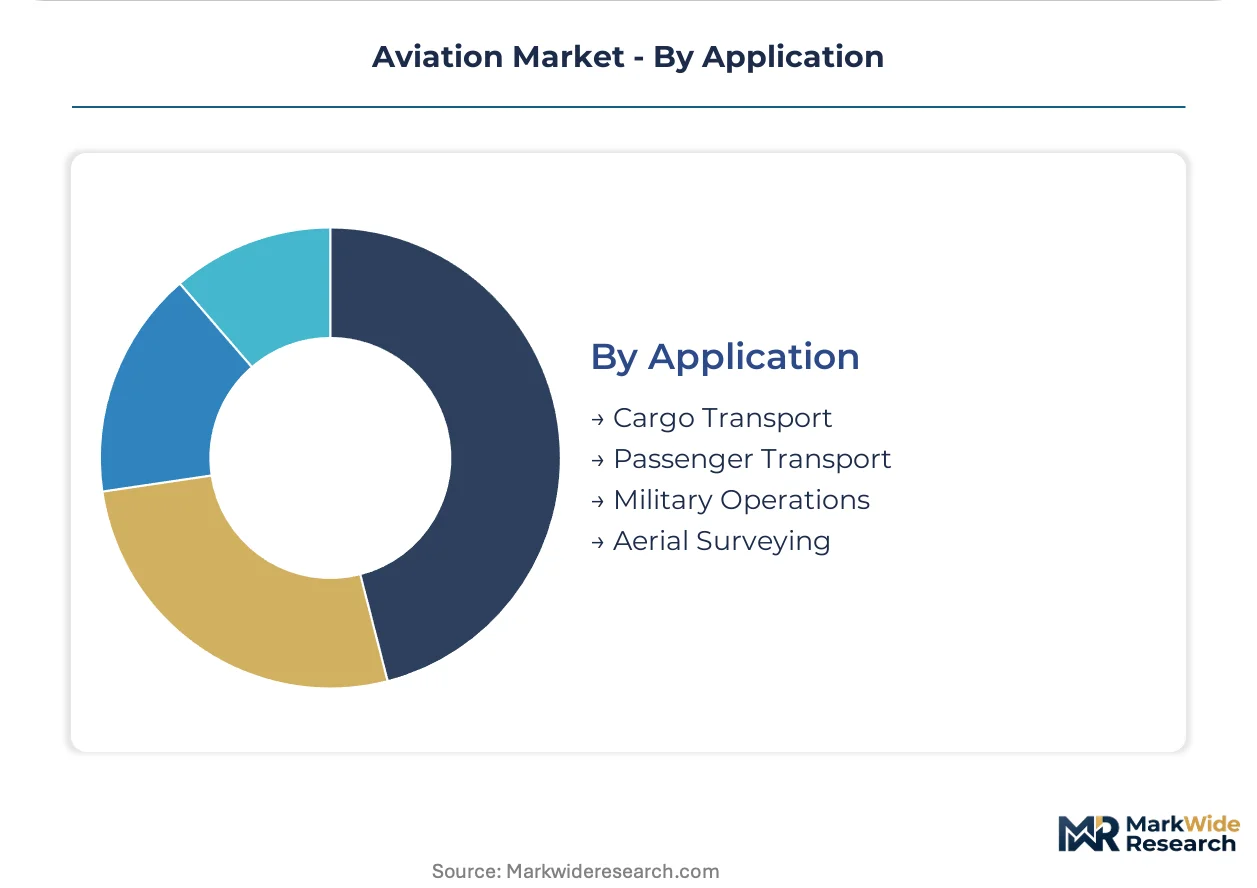
Application:
Volume concentration separates high-frequency scheduled operations from intermittent mission profiles, with asset utilization rates dictating technology refresh cycles.
- Cargo Transport:Dedicated freighter and belly-hold operations moving time-deficient goods. E-commerce fulfillment networks in China and the United States are driving narrow-body freighter conversions as express delivery windows compress.
- Passenger Transport:Scheduled and charter services accounting for the dominant revenue pool. Domestic route density across Southeast Asia is accelerating replacement cycles for fuel-efficient narrow-body platforms as sustainable aviation fuel mandates tighten operating requirements.
- Military Operations:Tactical airlift, surveillance, and combat missions.
- Aerial Surveying:Geospatial mapping and infrastructure inspection deployments.
Passenger Transport holds the installed base. Cargo Transport is climbing the fastest on e-commerce logistics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Low-cost carriers in Southeast Asia dominate procurement volumes, while European operators absorb the steepest regulatory compliance costs. Fleet replacement cycles concentrate where domestic route density exceeds regional utilization benchmarks.
United States
Beyond-visual-line-of-sight regulatory frameworks from the FAA are opening controlled airspace for electric vertical takeoff and landing cargo networks. The country's production-linked incentive schemes for unmanned aerial systems attract component manufacturing investment. Dallas-Fort Worth and Seattle-Tacoma metropolitan clusters host concentrated MRO capacity serving narrow-body fleet operators.
India
High-frequency domestic route networks across Maharashtra and Karnataka drive aircraft utilization rates above regional averages. The PLI scheme for drones redirects component manufacturing from traditional East Asian supply bases. Bangalore and Hyderabad industrial corridors concentrate avionics integration facilities serving both commercial and defence applications.
Germany
ReFuelEU Aviation mandates force synthetic fuel blending obligations into 15-year procurement horizons for network carriers. EASA's evolving CS-25 framework shapes product access for non-European manufacturers seeking European operator placement. Hamburg and Munich aerospace clusters anchor composite airframe manufacturing for next-generation narrow-body platforms.
United Arab Emirates
Fractional ownership models and corporate flight departments prioritize schedule control over unit economics in business jet procurement. The country's aviation regulator liberalizes beyond-visual-line-of-sight frameworks for urban air mobility corridors. Dubai South and Abu Dhabi industrial zones concentrate maintenance, repair, and overhaul capacity serving long-haul carrier fleets.
Vietnam
Low-cost carrier expansion drives fleet orders for fuel-efficient narrow-body architectures serving high-frequency domestic routes. The country's central bank facilitates aircraft leasing structures through offshore financing frameworks. Ho Chi Minh City and Hanoi metropolitan clusters concentrate ground support equipment procurement for accelerating turnaround operations.
Aviation Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct technology layers. The market structure consolidates around airframe integrators and propulsion system architects, with tier-1 suppliers capturing subassembly margins. Strategic archetypes include full-spectrum platform developers, propulsion technology licensors, and aftermarket service consolidators. Dominant competitive moves include strategic partnerships for sustainable aviation fuel offtake agreements and geographic expansion into India's production-linked incentive zones.
Among US-based platform developers, The Boeing Company and Lockheed Martin Corporation represent full-spectrum defence and commercial aerospace archetypes. European airframe and system integrators include Airbus SE and Safran SA, which exemplify transnational collaborative structures spanning multiple regulatory jurisdictions. RTX Corporation anchors the propulsion technology tier through its three-engineering-centre model sustaining R&D intensity across commercial and defence applications.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| The Boeing Company |
| Safran SA |
| Leonardo S.p.a. |
| Airbus SE |
| RTX Corporation |
| TransDigm Group Incorporated |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in narrow-body final assembly lines across Toulouse and Renton is compressing pricing power for airframe integrators while forcing suppliers to absorb extended payment terms. This utilization imbalance cascades through the procurement stack, with tier-1 propulsion manufacturers extracting price premiums from constrained high-bypass turbofan capacity while structural component vendors face margin compression from excess forging and machining capacity.
Pricing Analysis
Long-term cost-plus contracts with labor and materials indexation to Bureau of Labor Statistics producer price indices dominate commercial aircraft procurement. Price differentiation rests on engine fuel efficiency tier and EASA CS-25 certification pedigree, with next-generation geared turbofan platforms commanding acquisition premiums over legacy direct-drive architectures. Pricing pressure intensifies in the freighter conversion segment as e-commerce logistics operators demand volume discounts for multi-aircraft commitments. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while Middle Eastern network carriers prioritize delivery slot security over unit economics.
Supply Chain Analysis
Supplier-financing mechanisms including 180-day extended payment terms and reverse-factoring facilities through aviation-focused trade finance banks are shifting working capital burdens upstream. Geographic supply concentration centers on China for rare earth magnet processing, Russia for aerospace-grade titanium sponge, and Japan for composite carbon fiber precursor. Raw material dependencies encompass nickel-based superalloys for turbine blades, epoxy resin systems for airframe structures, and specialized avionics semiconductors. Single-source vulnerability from titanium sponge concentration exposes Western manufacturers to geopolitical disruption. Distribution runs through airframe integrator final assembly lines, with component logistics managed via dedicated aerospace freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aviation market is recovering through the narrow-body replacement cycle, with fleet age demographics and ReFuelEU Aviation mandates forcing procurement decisions regardless of macroeconomic conditions.
For Market Incumbents: Build regulatory certification moats through accelerated EASA CS-25 validation for sustainable propulsion integrations. Deepen backward integration into composite airframe structures to offset titanium supply disruption exposure. Expand MRO capacity in India and Vietnam to capture aftermarket disintermediation from OEM captivity. For New Entrants and Emerging Players: Pursue urban air mobility cargo corridors in the United Arab Emirates and United States where beyond-visual-line-of-sight frameworks are liberalizing. Target India's drone component manufacturing under PLI scheme incentives. Establish go-to-market partnerships with existing ground handling operators to bypass infrastructure buildout requirements. For Investors and Strategic Acquirers: Capital is best deployed toward propulsion technology licensors with patent control over open-rotor architectures and unducted fan designs. Long-term viability favors suppliers with dual-use commercial and defense revenue streams insulating against airline cyclicality. Monitor sustainable aviation fuel offtake agreement announcements as inflection indicators for biorefinery scale-up commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Offtake Agreement | Locks in long-term feedstock supply for EU ReFuelEU Aviation compliance pathways. |
| Open-Rotor Propulsion R&D Partnership | Accelerates unducted fan validation through shared engineering resources across OEMs. |
| India PLI Zone Manufacturing Expansion | Captures drone component production shifting from East Asian supply bases. |
| Digital Twin Maintenance Platform Launch | Enables predictive analytics contracts shifting revenue from parts to data services. |
| EASA Part 145 Certification Acquisition | Expands third-party MRO capacity serving Asia-Pacific narrow-body fleet operators. |
Methodological Framework
The analysis maps commercial aircraft platforms, propulsion systems, avionics architectures, and unmanned aerial systems, each validated through fleet planning executives at network carriers, procurement directors at low-cost operators, airworthiness certification leads at EASA and FAA, and aftermarket service heads at independent MRO providers. Primary interview intelligence triangulates against secondary sources including FAA Part 25 type certificate databases, EASA CS-25 certification records, ICAO emissions monitoring reports, and airline SEC 10-K fleet disclosure filings. Bottom-up unit economics modeling reconciles with top-down market size estimates across the projection horizon.
Forecast assumptions hold ReFuelEU Aviation blending mandates on announced trajectories, FAA beyond-visual-line-of-sight regulatory liberalization continuing, and titanium sponge supply concentration persisting. Segmentation dimensions include product type, technology layer, end-user category, and application intensity. CAGRs derive from fleet replacement cycle modeling, sustainable fuel cost curve projections, and regional route density analytics. Industry-specific inputs encompass engine fuel burn improvement curves and airframe certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric vertical takeoff and landing entrants or sustainable aviation fuel technology disruptors would shift outcomes. Macroeconomic contraction affecting airline credit availability, unilateral national blending mandates diverging from EU frameworks, or breakthrough battery energy density improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Helicopters Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Air Speed Indicator Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
General Aviation Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Firefighting Aircraft Market