
 Medium and Heavy-Lift Helicopters Market | 2026-2036
Medium and Heavy-Lift Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Medium and Heavy-Lift Helicopters Market Foresight
Aftermarket service revenue is rewriting profit pools across the medium and heavy-lift helicopter value chain. Airbus SE leverages its global MRO network to capture recurring service income from aging H225 fleets. Boeing sustains military sustainment dominance through its Apache and Chinook logistics contracts. Leonardo specializes in naval and SAR configurations, anchoring European defense procurement cycles.
Medium and heavy-lift helicopters are rotary-wing aircraft with maximum takeoff weights exceeding approximately 7,000 pounds, powered by turbine engines driving main and tail rotors through complex transmission systems, designed to transport personnel, cargo, or external loads in conditions fixed-wing aircraft cannot access. Their primary purpose spans military assault, offshore logistics, emergency medical evacuation, and aerial firefighting in restricted terrain. Utility helicopters command the largest installed base due to multi-mission adaptability across government and commercial operators, while autonomous helicopter technology represents the fastest-developing segment as unmanned systems penetrate cargo resupply and surveillance missions. Turbine helicopters retain near-total market share for heavy-lift applications, though hybrid propulsion architectures are emerging for fuel efficiency in medium-lift utility roles.
The FAA enforces Part 29 certification standards that govern transport-category rotorcraft structural integrity, crashworthiness, and systems reliability, directly shaping manufacturer R&D allocation and fleet replacement timelines. EASA's CS-29 harmonized requirements and the EU Green Deal's aviation decarbonization targets are pressuring OEMs to demonstrate emission reduction pathways for new turbine platforms. Military operators must monitor how ITAR-controlled technology transfer restrictions affect cross-border component sourcing, while civilian fleet managers face escalating insurance and liability exposure from aging airframe fatigue-life limits.
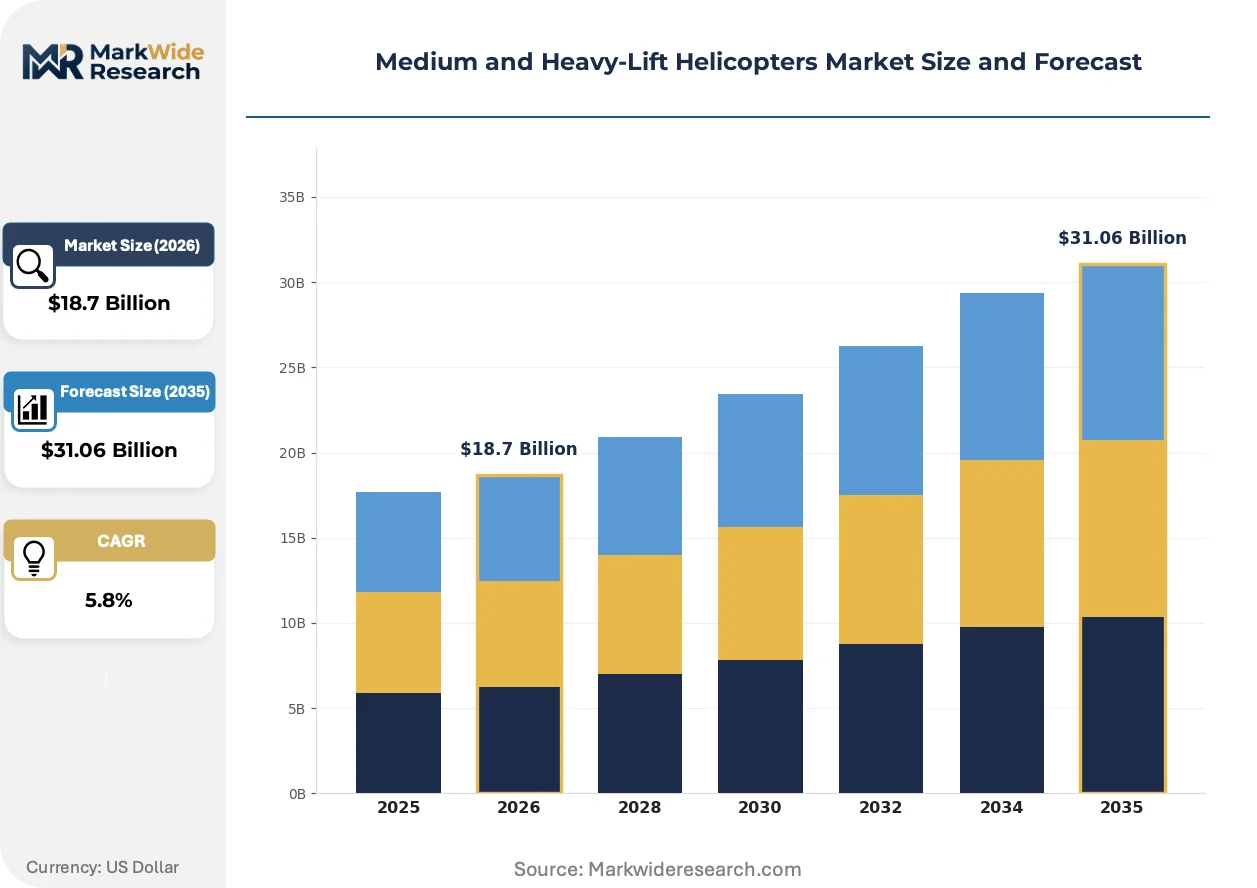
Market Dynamics
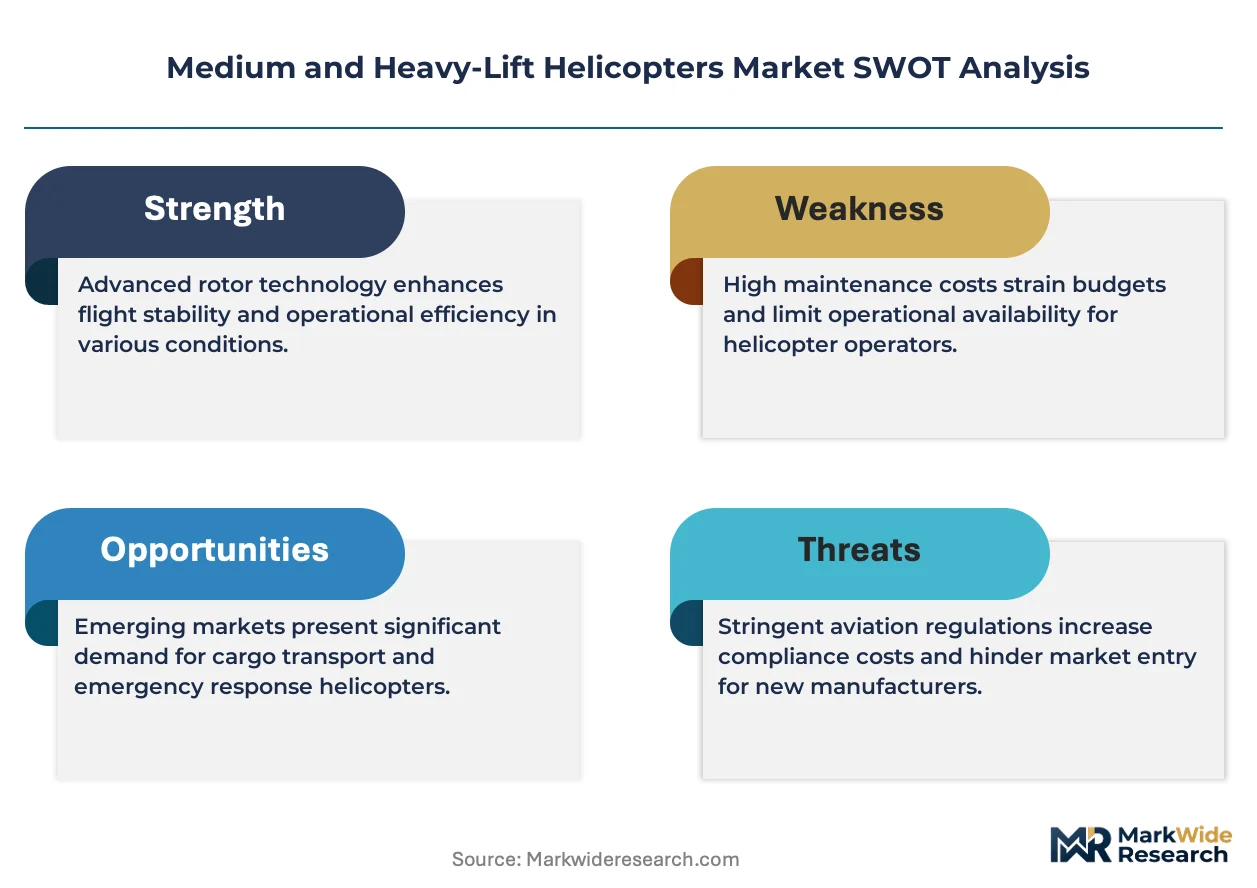
Fleet age demographics and regulatory recertification burdens are forcing operators into accelerated replacement cycles, compressing capital deployment timelines and redistributing bargaining power toward OEMs with available production slots.
Growth Catalysts
- Deepwater Offshore Expansion:Oil and gas platforms operating beyond 200 nautical miles from shore require heavy-lift rotorcraft with extended range and payload capacity. Operators in the Gulf of Mexico and North Sea are renewing fleets to meet these mission profiles.
- FAA Part 29 Recertification:Updated airworthiness standards for transport-category rotorcraft mandate enhanced crashworthiness and systems redundancy. Aging fleets face costly modification or retirement, pulling forward demand for new-build platforms.
- Hybrid-Electric Propulsion Maturation:Turbogenerator-battery architectures are demonstrating fuel efficiency gains in medium-lift utility roles. Development programs in Germany and Japan are validating hybrid systems for certification pathways.
Market Restraints
- Turbine Engine Supply Concentration:Heavy-lift helicopter propulsion systems depend on a concentrated supplier base in the United States and United Kingdom. Geopolitical friction or export control tightening disrupts delivery schedules for international OEMs.
- Airframe Material Cost Volatility:Titanium and advanced composite prepregs face price instability tied to aerospace demand cycles and energy-intensive production. Input cost swings compress margin visibility for manufacturers on fixed-price contracts.
- Certification Timeline Friction:EASA CS-29 harmonization with FAA Part 29 creates dual-compliance burdens for platforms serving both markets. Validation testing duplication extends time-to-revenue by 18-24 months for new entrants.
Strategic Opportunities
- Unmanned Cargo Resupply:Autonomous helicopter systems are penetrating military logistics and remote commercial delivery. The United States Marine Corps and Australian mining operators are funding operational demonstrations for contested-environment resupply.
- India Defense Modernization:The country's armed forces seek indigenous heavy-lift capability under Make-in-India procurement frameworks. Joint ventures with established OEMs offer production footholds in a historically import-dependent market.
- EU Green Deal Aviation Decarbonization:Sustainable aviation fuel mandates and emission reduction targets create demand for fuel-efficient platforms. OEMs demonstrating certified SAF compatibility gain preferential positioning in European defense and civilian tenders.
Industry Challenges
- Powertrain Engineering Talent Scarcity:Hybrid-electric and full-electric propulsion development requires specialized skills in high-voltage systems and thermal management. Competition with automotive and fixed-wing aviation sectors constrains hiring pipelines.
- Legacy Avionics Integration Complexity:New-build platforms must interface with existing military command networks and civilian air traffic infrastructure. Software certification for mixed-fleet operations demands extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium and Heavy-Lift Helicopters Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Utility Helicopters, Cargo Helicopters, Search and Rescue Helicopters, Firefighting Helicopters Technology: Turbine Helicopters, Electric Helicopters, Hybrid Helicopters, Autonomous Helicopters End User: Government Agencies, Oil & Gas Industry, Construction Companies, Emergency Services Application: Transport, Logistics, Surveillance, Medical Evacuation |
| Companies Covered | Airbus SE, The Boeing Company, Leonardo S.p.A, Lockheed Martin Corporation, Bell Textron Inc, Russian Helicopters JSC, Aviation Corporation of China, Hindustan Aeronautics Limited, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium and Heavy-Lift Helicopters Market Shifts & Advancements
Propulsion electrification, regulatory harmonization pressures, and service-based revenue models are converging to restructure how rotorcraft capability is developed, certified, and monetized across defense and commercial segments.
Fly-by-wire flight control architectures are collapsing the traditional mechanical linkage complexity that has constrained heavy-lift helicopter design for decades. Military operators in the United States and United Kingdom are specifying digital flight control for next-generation assault and utility platforms. This technology is collapsing development timelines for variant proliferation while reducing pilot workload in degraded visual environments.
The EU Green Deal's aviation decarbonization targets are pressuring OEMs to demonstrate emission reduction pathways for turbine platforms. EASA is developing certification standards for hybrid-electric propulsion that will apply to medium-lift categories first. European offshore operators are responding by incorporating fuel efficiency metrics into lease-versus-purchase evaluations.
Aftermarket service unbundling is fragmenting traditional OEM captive maintenance relationships. Third-party MRO providers in Singapore and the United Arab Emirates are securing component repair authorizations previously reserved for factory networks. This shift is most visible in the Asia-Pacific offshore oil and gas sector, where operators prioritize turnaround speed over single-source dependency.
Medium and Heavy-Lift Helicopters Market Segmentation
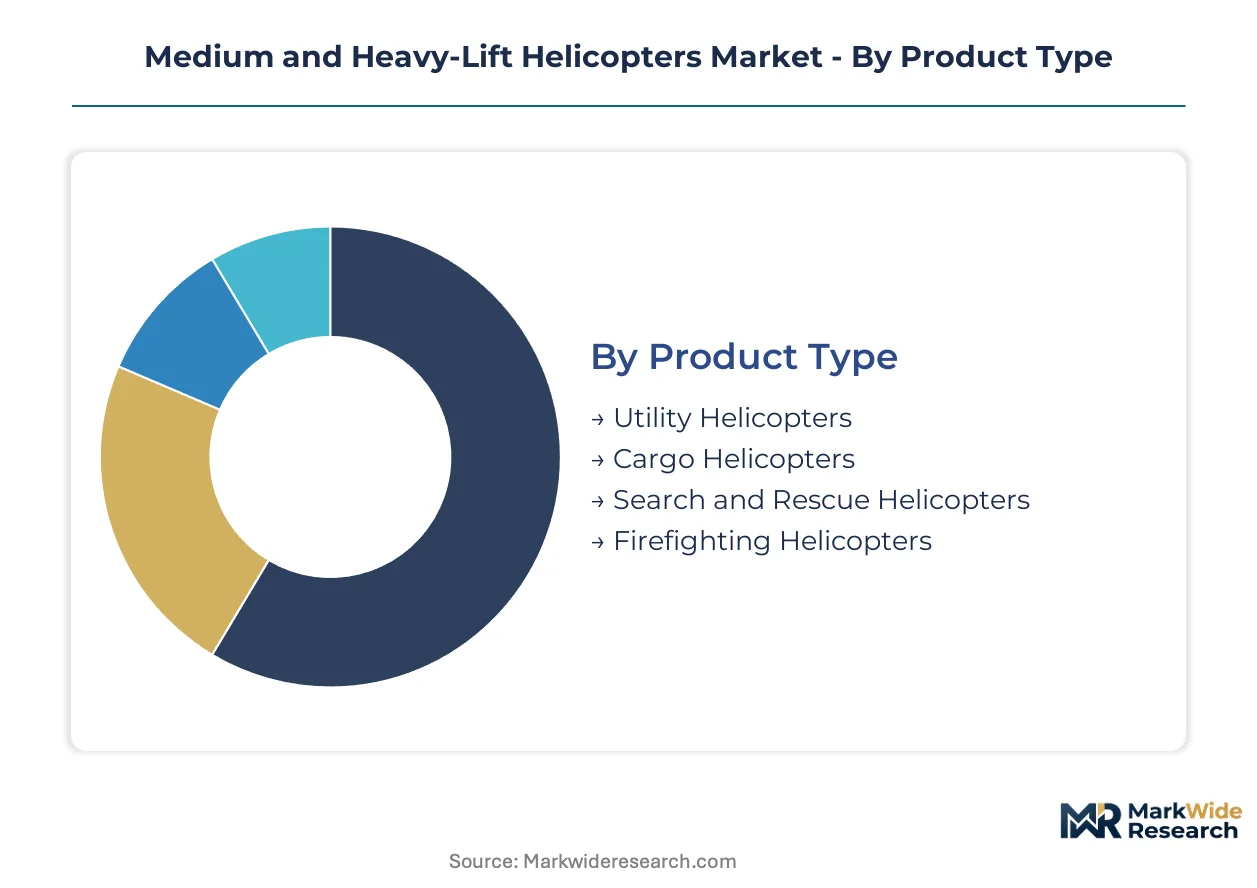
Segmentation reveals how mission requirements, propulsion architecture, and operator economics partition the medium and heavy-lift helicopter market. Understanding these divisions clarifies where capital deployment concentrates and which technology transitions command strategic attention.
Product Type:
Replacement cycles vary dramatically across mission configurations, with commercial utility fleets turning over faster than specialized government platforms.
- Utility Helicopters:Multi-mission airframes configured for personnel transport, external load operations, and equipment repositioning dominate civilian government contracts. Demand concentrates in the United States and Australia where state-level agencies refresh fleets to meet FAA Part 29 recertification deadlines.
- Cargo Helicopters:Heavy-lift platforms with internal cabin volumes exceeding 500 cubic feet and external sling capacities above 10,000 pounds serve offshore logistics and infrastructure construction. Gulf of Mexico operators are renewing fleets as platforms migrate beyond 200 nautical miles from shore.
- Search and Rescue Helicopters:SAR-configured platforms integrate winch systems, medical bays, and extended-range fuel systems for maritime and alpine operations.
- Firefighting Helicopters:Specialized tanker and bucket-equipped rotorcraft face seasonal utilization patterns and concentrated procurement from forestry services in Mediterranean Europe and the western United States.
Utility Helicopters dominate installed base. Cargo Helicopters is where expansion concentrates.
Technology:
Propulsion architecture determines certification pathway complexity and operational cost structure across the forecast window.
- Turbine Helicopters:Turboshaft-powered platforms using single or twin-engine configurations deliver the power-to-weight ratios required for heavy-lift missions. Near-universal market share persists in applications above 7,000 pounds maximum takeoff weight due to energy density requirements.
- Hybrid Helicopters:Turbogenerator-battery architectures are demonstrating fuel efficiency gains in medium-lift utility roles, with development programs in Germany and Japan validating certification pathways. European offshore operators are incorporating fuel efficiency metrics into procurement evaluations under EU Green Deal pressure.
- Electric Helicopters:Battery-electric propulsion remains constrained by energy density limits for heavy-lift applications but attracts investment for short-range urban mobility concepts.
- Autonomous Helicopters:Unmanned systems are penetrating military logistics and remote commercial delivery, with the United States Marine Corps and Australian mining operators funding contested-environment resupply demonstrations.
Turbine Helicopters anchor current revenue. Autonomous Helicopters are climbing the fastest as operational demonstrations accumulate flight hours.
End User:
Procurement authority and budget cycle timing create distinct demand patterns across operator categories.
- Government Agencies:Military and paramilitary operators drive multi-year acquisition programs with embedded sustainment contracts. United States Army modernization and European defense procurement cycles are converging on fly-by-wire platforms.
- Oil & Gas Industry:Offshore operators in the North Sea and Gulf of Mexico prioritize payload-range performance for deepwater platform support. Fleet renewal decisions correlate with exploration permit cycles and production platform commissioning schedules.
- Construction Companies:Heavy-lift contractors serving infrastructure and wind turbine installation face project-based demand volatility.
- Emergency Services:Hospital systems and municipal fire departments operate on compressed procurement timelines with emphasis on availability guarantees.
Government Agencies command the largest committed order backlogs. Oil & Gas Industry is where fleet age demographics are forcing replacement decisions most urgently.
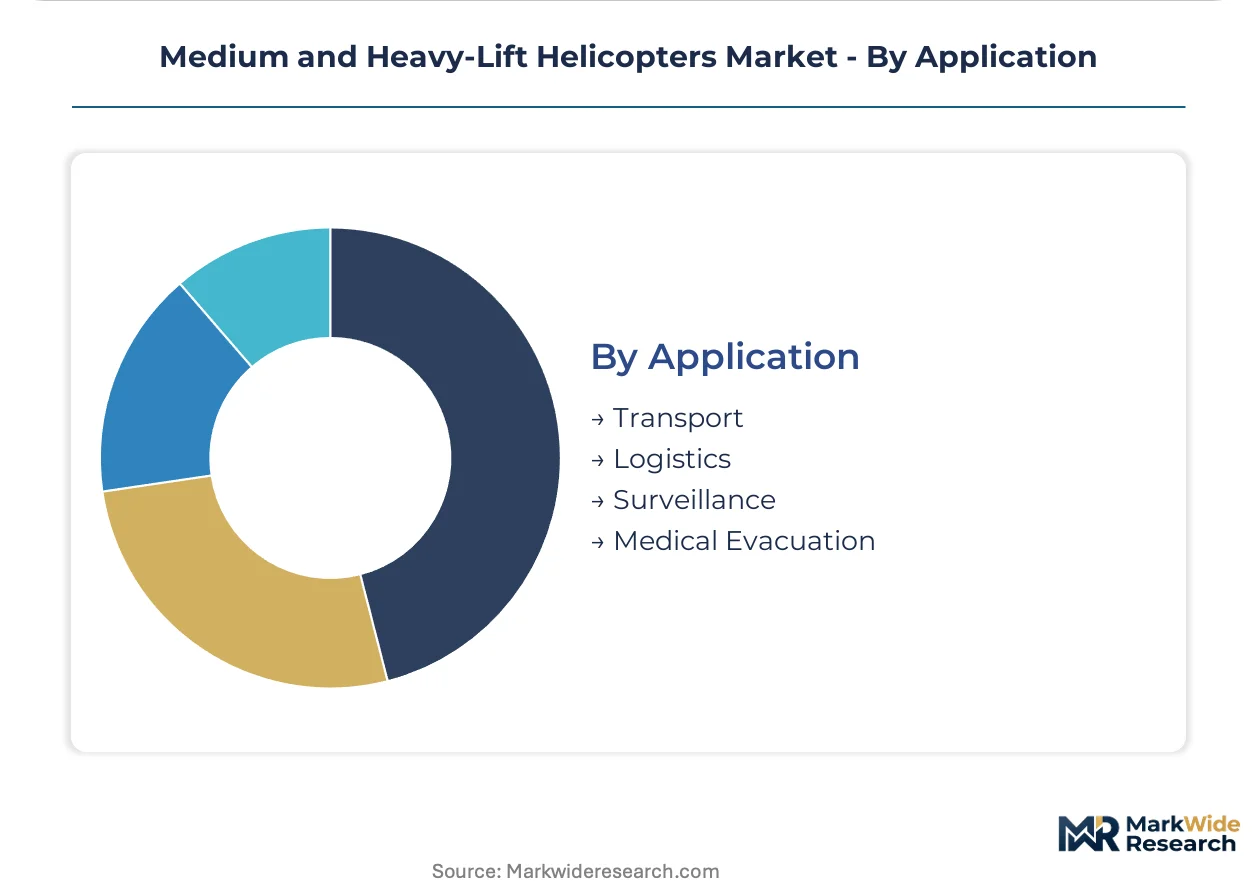
Application:
Mission profile determines equipment configuration requirements and operational tempo expectations.
- Transport:Personnel movement missions require crashworthy seating, environmental control systems, and rapid ingress-egress configurations. Military assault transport specifications are migrating into civilian government procurement.
- Logistics:Cargo delivery operations emphasize external load certification, precision hover capability, and all-weather navigation systems. Remote mining and offshore supply routes are validating autonomous logistics concepts.
- Surveillance:Sensor platform missions integrate electro-optical, radar, and signals intelligence payloads with extended endurance requirements.
- Medical Evacuation:MEDEVAC configurations demand pressurized cabins, life support equipment, and rapid patient loading systems for trauma care delivery.
Transport missions represent the broadest addressable market. Logistics applications are gaining share fastest as unmanned systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across procurement authorities. Military operators absorb premium pricing for fly-by-wire platforms, while municipal emergency services face compressed budgets that favor utility configurations. Offshore oil and gas buyers negotiate payload-range trade-offs against fuel efficiency metrics.
United States
Army modernization programs and state-level fleet renewals drive sustained demand. FAA Part 29 recertification deadlines force aging airframe retirements. The Gulf of Mexico offshore cluster concentrates heavy-lift procurement as platforms migrate beyond 200 nautical miles from shore.
United Kingdom
Ministry of Defence specifications prioritize digital flight control for next-generation assault platforms. EASA CS-29 harmonization with FAA standards creates dual-compliance validation requirements. The North Sea offshore sector anchors European heavy-lift utilization rates.
India
Make-in-India procurement frameworks seek indigenous heavy-lift capability through joint ventures. DGFT import licensing and offset requirements shape foreign OEM entry strategies. Bengaluru and Hyderabad host emerging helicopter manufacturing clusters for defense applications.
Japan
Coast Guard and firefighting agencies refresh multi-mission utility fleets. METI funding validates hybrid-electric propulsion certification pathways. Nagoya's aerospace corridor concentrates MRO infrastructure for regional operators.
Australia
Mining operators fund autonomous cargo resupply demonstrations for remote logistics. Civil Aviation Safety Authority regulations govern unmanned system integration into controlled airspace. The Pilbara region drives heavy-lift demand for iron ore infrastructure construction.
Medium and Heavy-Lift Helicopters Market Competitive Landscape
Capability concentration sits with established defense contractors holding military certification heritage; scale advantage sits with diversified aerospace conglomerates with integrated supply chains. The market structures around three tiers: legacy military platforms, multi-mission utility airframes, and emerging autonomous systems. Dominant competitive moves include strategic partnerships for indigenous production rights and technology licensing for hybrid propulsion architectures.
Within the integrated defense tier, Airbus SE and The Boeing Company occupy positions shaped by sustainment contract longevity and platform lineage breadth. Leonardo S.p.A represents European specialization in naval and SAR configurations. These three exemplify how military logistics dominance translates into aftermarket revenue capture across aging fleet demographics.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| Leonardo S.p.A |
| Lockheed Martin Corporation |
| Bell Textron Inc |
| Russian Helicopters JSC |
| Aviation Corporation of China |
| Hindustan Aeronautics Limited |
| Kawasaki Heavy Industries |
| Others |
Supply & Pricing Matrix
Turbine engine manufacturing concentrates in the United States and United Kingdom, anchoring margin capture in the propulsion tier while downstream OEMs compete on airframe integration and aftermarket service bundling. This upstream concentration forces airframers to absorb cost volatility through long-term supply agreements or captive MRO networks.
Pricing Analysis
Aftermarket parts and service contracts generate lifetime value multiples exceeding original equipment sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by mission criticality and fleet scale. Military operators absorb premium pricing for fly-by-wire platforms with embedded logistics support. Municipal emergency services face compressed procurement budgets that favor utility configurations without advanced avionics packages. Cost compression in the mid-tier utility segment is intensifying as third-party MRO providers in Singapore and the United Arab Emirates secure component repair authorizations previously reserved for factory networks.
Supply Chain Analysis
ITAR-controlled technology transfer restrictions limit cross-border flows of critical rotorcraft components and flight control software. Heavy-lift helicopter propulsion systems draw from concentrated turbine engine suppliers in the United States and United Kingdom, with auxiliary gearbox manufacturing centered in Germany and France. Titanium forgings and advanced composite prepregs feed from aerospace-tier suppliers facing energy-intensive production cycles. Single-source vulnerability runs through precision-machined transmission components where dual-qualification timelines extend 24-36 months. Distribution runs through military logistics channels for defense procurement and direct OEM-operator contracts for commercial fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized powertrain engineering talent for hybrid-electric architectures remains scarce relative to demand from automotive and fixed-wing sectors, compressing development timelines for next-generation platforms. This capability gap rewards early movers who secure dedicated engineering pipelines.
For Market Incumbents: Pre-empt emerging autonomous helicopter entrants by accelerating fly-by-wire certification for legacy platforms and securing exclusive MRO network agreements in Asia-Pacific offshore hubs. Vertical integration into titanium component forging mitigates raw material cost volatility that threatens fixed-price military contracts. For New Entrants and Emerging Players: Establish a beachhead in unmanned cargo resupply demonstrations for mining operators in Australia's Pilbara region, where regulatory frameworks for autonomous system integration are advancing faster than in European or North American airspace. Partner with established MRO providers in Singapore to bypass factory network captive relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aerospace component suppliers holding sole-source positions in transmission and rotor system manufacturing. Long-term viability hinges on exposure to military modernization programs with embedded sustainment contracts rather than spot commercial procurement. Monitor FAA Part 29 recertification deadline acceleration as an inflection indicator for replacement demand pull-forward.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Certification | METI-funded programs in Japan validate fuel efficiency pathways for EASA CS-29 compliance. |
| Autonomous Cargo System Demonstration | United States Marine Corps funding signals contested-environment logistics demand maturation. |
| Indigenous Production Joint Venture | Make-in-India frameworks require local assembly for defense procurement eligibility. |
| Aftermarket Service Network Expansion | Third-party MRO authorization in Singapore fragments traditional OEM captive relationships. |
| Fly-by-Wire Flight Control Integration | United States Army specifications accelerate digital architecture adoption across NATO operators. |
Research Methodology
Operator-level perspectives from fleet managers at offshore oil and gas contractors, military aviation program officers, and third-party MRO facility directors anchored the qualitative base. Primary interviews with procurement leads at state-level emergency services agencies and mining logistics coordinators were cross-validated against FAA certification databases, EASA CS-29 regulatory filings, and customs trade records for turbine engine imports. Bottom-up fleet demographics and top-down OEM production schedules were triangulated to establish market sizing boundaries.
Scenario-bracketing around regulatory timeline acceleration and raw material cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include mission configuration, propulsion architecture, end-user procurement authority, and geographic regulatory cluster. CAGRs were derived from replacement cycle compression analysis and fleet age demographic projections. Hybrid-electric technology readiness levels and autonomous system flight hour accumulation served as industry-specific forecast inputs.
Stress conditions across titanium price volatility, ITAR restriction tightening, and EASA-FAA harmonization timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding military budget authorization continuity and offshore exploration permit cycles. Material shifts in FAA Part 29 enforcement severity or EU Green Deal aviation decarbonization timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Evtol Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Europe Military Helicopters Market
Aircraft
Air Starter Market
Aircraft
Military Helicopters Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
America Attack Helicopter Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Aerospace Turbojet Market
Aircraft
Flight Management Systems Market
Aircraft
Airplane Landing Gear Market
Aircraft
Aeronautic Propeller Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Southeast Asia Aviation Market