
 Commercial Turboprop Aircrafts Market | 2026-2036
Commercial Turboprop Aircrafts Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Turboprop Aircrafts Market Analysis
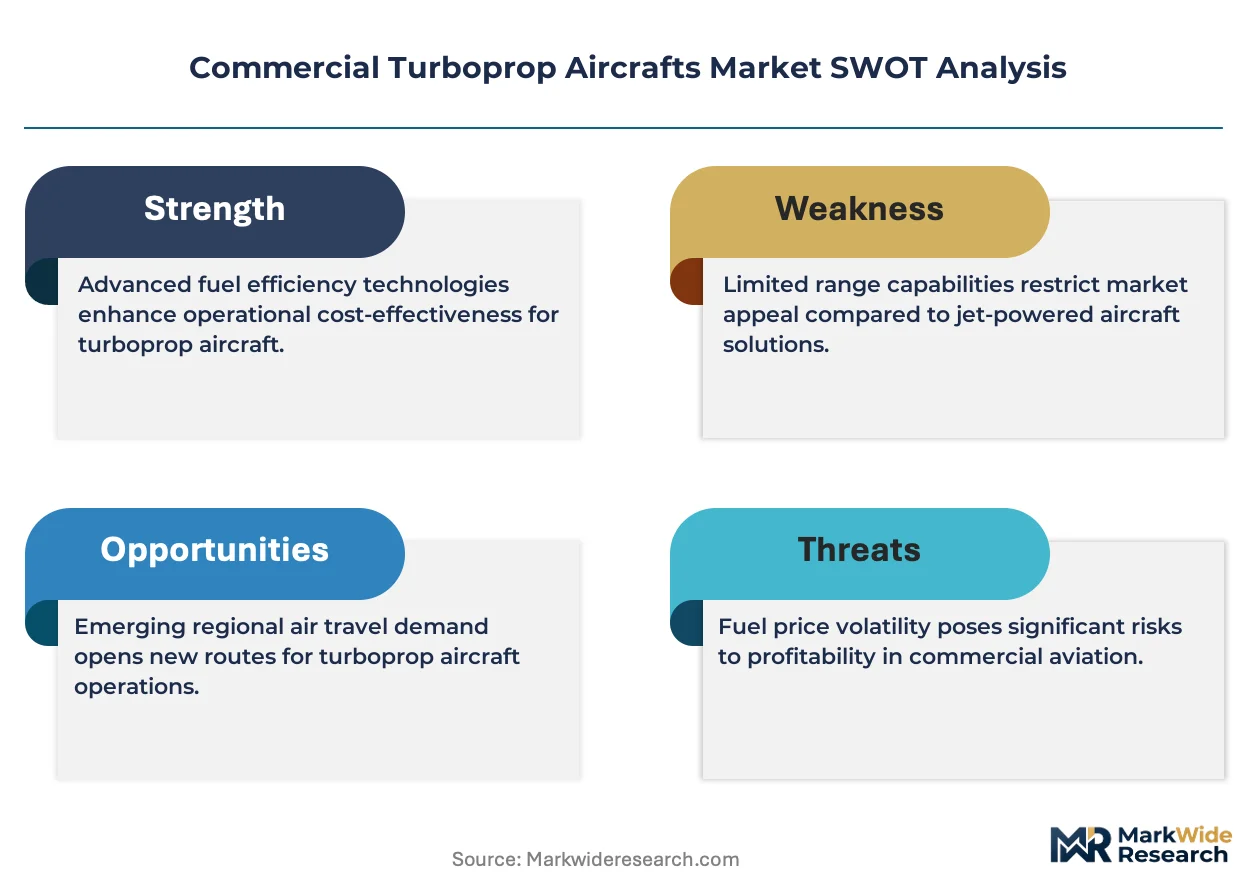
Composite materials are replacing aluminum in wing structures and is pivoting turboprop economics toward lighter, more fuel-efficient designs. ATR leverages its European manufacturing base to sustain dominance in the regional twin-engine segment. Textron Aviation Inc. anchors the North American charter and corporate turboprop niche through its King Air lineage. De Havilland Aircraft of Canada Limited specializes in rugged, high-cycle airframes that dominate remote Canadian and Alaskan operations.
A commercial turboprop aircraft is a fixed-wing airplane powered by gas turbine engines driving propellers, typically operating at cruise speeds of 300-400 knots and altitudes below 25,000 feet, designed for short-haul passenger and cargo transport on runways as short as 800 meters. Twin-engine configurations command the largest installed base due to their operational redundancy and ETOPS flexibility for overwater routes. Cargo operators represent the fastest-growing end-user category as e-commerce logistics networks expand into secondary airports with limited jet infrastructure. Passenger transport remains the most mature application segment, though air ambulance services are gaining share as healthcare systems decentralize critical care access.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern turboprop design, noise, and emissions compliance, with both regulators tightening Stage 5 noise limits that force engine and nacelle redesigns. The EU Green Deal's sustainable aviation fuel mandates and the US Inflation Reduction Act's SAF tax credits are reshaping fleet renewal timelines across North American and European operators. Stakeholders must monitor propulsion technology trajectories—particularly hybrid-electric and hydrogen fuel cell architectures—as these will determine which airframe and engine combinations retain residual value through the next decade.
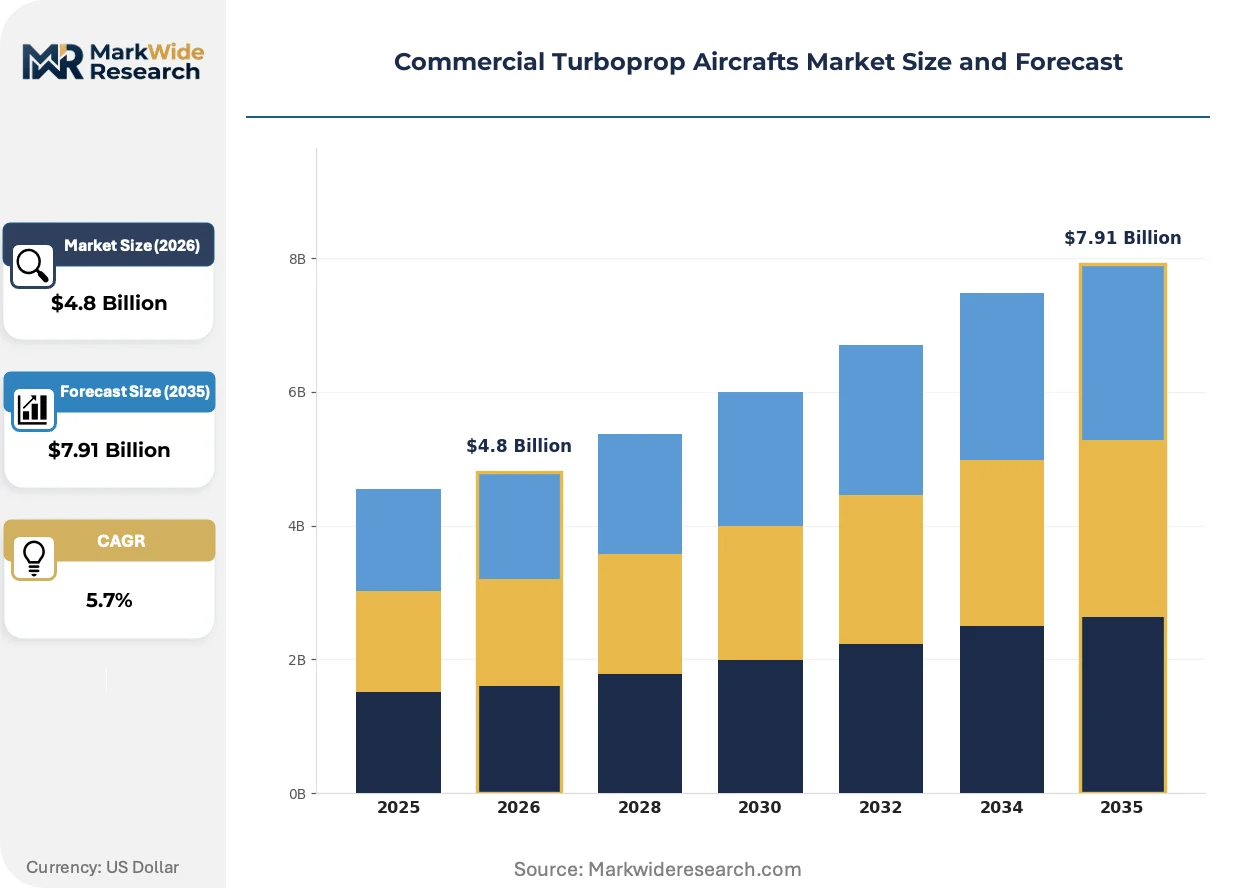
Market Dynamics
Composite material adoption is compressing airframe weights and forcing engine-airframe integration cycles that reshape fleet economics. FAA Stage 5 noise mandates and EASA CS-25 certification updates are accelerating nacelle redesign timelines across the installed base.
Growth Catalysts
- SAF Tax Incentives:The US Inflation Reduction Act's sustainable aviation fuel credits are compressing payback periods for turboprop fleet renewals. Cargo operators at secondary airports with limited jet infrastructure are prioritizing turboprop lift capacity.
- Archipelagic Route Networks:Indonesia's domestic carriers are expanding turboprop deployment across island-hopping corridors where runway lengths restrict jet operations. Short-haul connectivity mandates from national aviation authorities reinforce this pattern.
- Hybrid-Electric Propulsion:Gas turbine-electric architectures are entering flight test phases, promising fuel burn reductions that would reposition turboprops against regional jets on 300-500 nautical mile segments.
Market Restraints
- Titanium Supply Concentration:Russian and Chinese dominance in sponge titanium production creates input cost volatility for engine manufacturers dependent on high-temperature alloys.
- Certification Timeline Friction:FAA Part 25 amendment cycles for novel propulsion systems extend airframe redesign windows, freezing capital deployment for derivative programs.
- Regional Jet Substitution:Embraer's E-Jet family and Airbus A220 are capturing frequency-sensitive routes where turboprops previously held cost advantages on runways exceeding 1,200 meters.
Strategic Opportunities
- Air Ambulance Conversion:Healthcare system decentralization in Canada and Australia is generating demand for pressurized turboprop platforms configured for critical care transport.
- EU Green Deal SAF Mandates:Blending requirements rising toward 2030 targets favor existing turboprop fleets with lower fuel burn baselines against jet alternatives.
- Drone Integration:Unmanned aerial system corridors at secondary airports are converging with turboprop cargo networks, enabling hub-and-spoke models with autonomous last-mile feeders.
Industry Challenges
- Propulsion Engineering Talent Scarcity:Gas turbine specialists with hybrid-electric integration experience command premium compensation, constraining program staffing for airframers.
- Legacy Avionics Integration:Cockpit modernization for 1990s-era airframes requires recertification of flight control software against updated DO-178C standards, compressing upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Turboprop Aircrafts Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Engine, Twin Engine, Regional Aircraft, Freight Aircraft End User: Commercial Airlines, Cargo Operators, Charter Services, Government Agencies Technology: Avionics Systems, Engine Types, Control Systems, Fuel Efficiency Enhancements Application: Passenger Transport, Cargo Transport, Air Ambulance Services, Training Operations |
| Companies Covered | ATR, Airbus SE, Textron Aviation Inc., Pilatus Aircraft Ltd., Lockheed Martin Corporation, De Havilland Aircraft of Canada Limited, Daher, Embraer S.A., Bombardier Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Turboprop Aircrafts Market Emerging Trajectories
Propulsion-airframe integration is accelerating as manufacturers pursue fuel efficiency gains through system-level optimization rather than component substitution alone.
Advanced thermoplastic composites are absorbing primary structural loads in wing boxes and empennage assemblies. Regional carriers operating high-cycle schedules in Southeast Asia are specifying these materials for corrosion resistance in tropical environments. The technology is absorbing maintenance cost premiums that previously favored aluminum repairs, compressing total cost of ownership calculations for fleet planners.
EASA's tightening CS-25 noise certification amendments are forcing active noise cancellation investments in nacelle acoustic treatments. Engine manufacturers must redesign fan blade geometries and exhaust mixers to meet Stage 5 limits without thrust penalties. European operators with night curfew restrictions at hubs like London City and Frankfurt are prioritizing compliant airframes for slot access.
Freight forwarders are consolidating procurement through dedicated turboprop capacity contracts rather than spot charter markets. E-commerce logistics networks in Indonesia and the Philippines are locking multi-year block-hour agreements with regional operators, displacing traditional passenger-to-cargo conversions. This concentration is most visible in archipelagic Southeast Asia where maritime alternatives face port congestion constraints.
Commercial Turboprop Aircrafts Market Segmentation
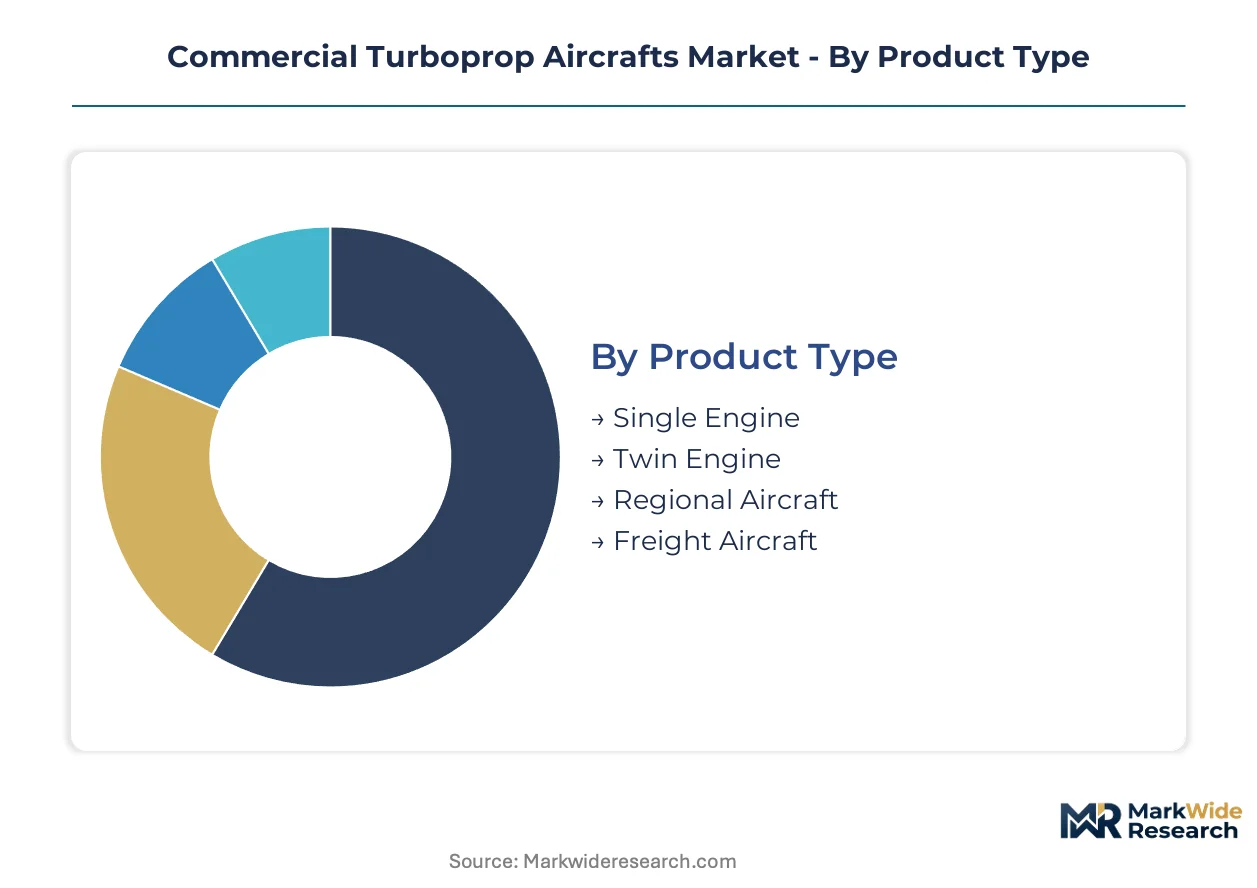
Turboprop segmentation reveals how propulsion architecture, operator economics, and mission profiles fragment procurement patterns across regional aviation networks. Fleet planners weight runway performance against fuel burn curves differently than cargo specialists optimizing for payload density.
Product Type:
Supply concentration in engine-airframe integration favors OEMs with captive propulsion development, tilting procurement toward platforms with vertical control over turbine supply chains.
- Twin Engine:Dual-turbine configurations dominate archipelagic routes requiring ETOPS flexibility for overwater segments. Indonesia's domestic carriers specify these airframes for island-hopping corridors where single-engine redundancy risks strand passengers. Operational reliability commands premium lease rates in Southeast Asian wet markets.
- Freight Aircraft:Dedicated cargo fuselages with reinforced floors and large cargo doors absorb e-commerce volume surges at secondary airports. Dedicated turboprop freighters displace converted passenger airframes as forwarders lock multi-year block-hour agreements. Payload-optimized designs sacrifice passenger windows for cubic volume efficiency.
- Single Engine:Lightweight airframes serve training operations and remote charter markets with simplified maintenance protocols.
- Regional Aircraft:Pressurized cabins and stand-up headroom configurations address scheduled service comfort standards on 200-400 nautical mile sectors.
Today's leader: Twin Engine. Tomorrow's challenger: Freight Aircraft.
End User:
Customer type fragmentation tracks capital access—airlines prioritize residual value preservation while government agencies optimize for total lifecycle cost under public procurement rules.
- Cargo Operators:E-commerce logistics networks in the Philippines and Indonesia are consolidating procurement through dedicated capacity contracts rather than spot charter markets. These operators specify quick-change interior configurations allowing overnight conversion between passenger and freight roles. Fleet decisions center on block-hour economics rather than seat-mile costs.
- Commercial Airlines:Scheduled carriers operating high-cycle routes in tropical environments specify corrosion-resistant composite structures for wing boxes. These operators face pressure from Stage 5 noise mandates at curfew-restricted hubs including London City and Frankfurt. Fleet renewal timelines compress as SAF tax incentives improve payback calculations.
- Charter Services:On-demand operators prioritize cabin flexibility and rapid turnaround capability for corporate shuttle contracts.
- Government Agencies:Public-sector procurement emphasizes multi-mission adaptability for maritime patrol, surveillance, and transport roles under unified fleet management.
Cargo Operators are expanding most quickly. Commercial Airlines retain the largest installed base.
Technology:
Technology selection increasingly determines residual value trajectories as regulators tighten emissions and noise standards across certification jurisdictions.
- Engine Types:Next-generation turbines with advanced compressor stages and single-crystal superalloy hot sections deliver thrust-specific fuel consumption improvements. These powerplants integrate with redesigned nacelles meeting EASA CS-25 Stage 5 noise limits without performance penalties. Manufacturers redesign fan blade geometries and exhaust mixers to preserve climb capability.
- Fuel Efficiency Enhancements:Active noise cancellation systems and improved thermal management reduce fuel burn baselines that determine operating economics against regional jet competition. These systems absorb development costs that OEMs recover through power-by-the-hour maintenance contracts. Hybrid-electric architectures in flight test promise step-change reductions on 300-500 nautical mile segments.
- Avionics Systems:Cockpit modernization for 1990s-era airframes requires recertification against updated DO-178C software standards.
- Control Systems:Digital fly-by-wire integration reduces pilot workload and enables autoland capability at weather-limited airports.
Engine Types anchor current procurement. Fuel Efficiency Enhancements are climbing the fastest.
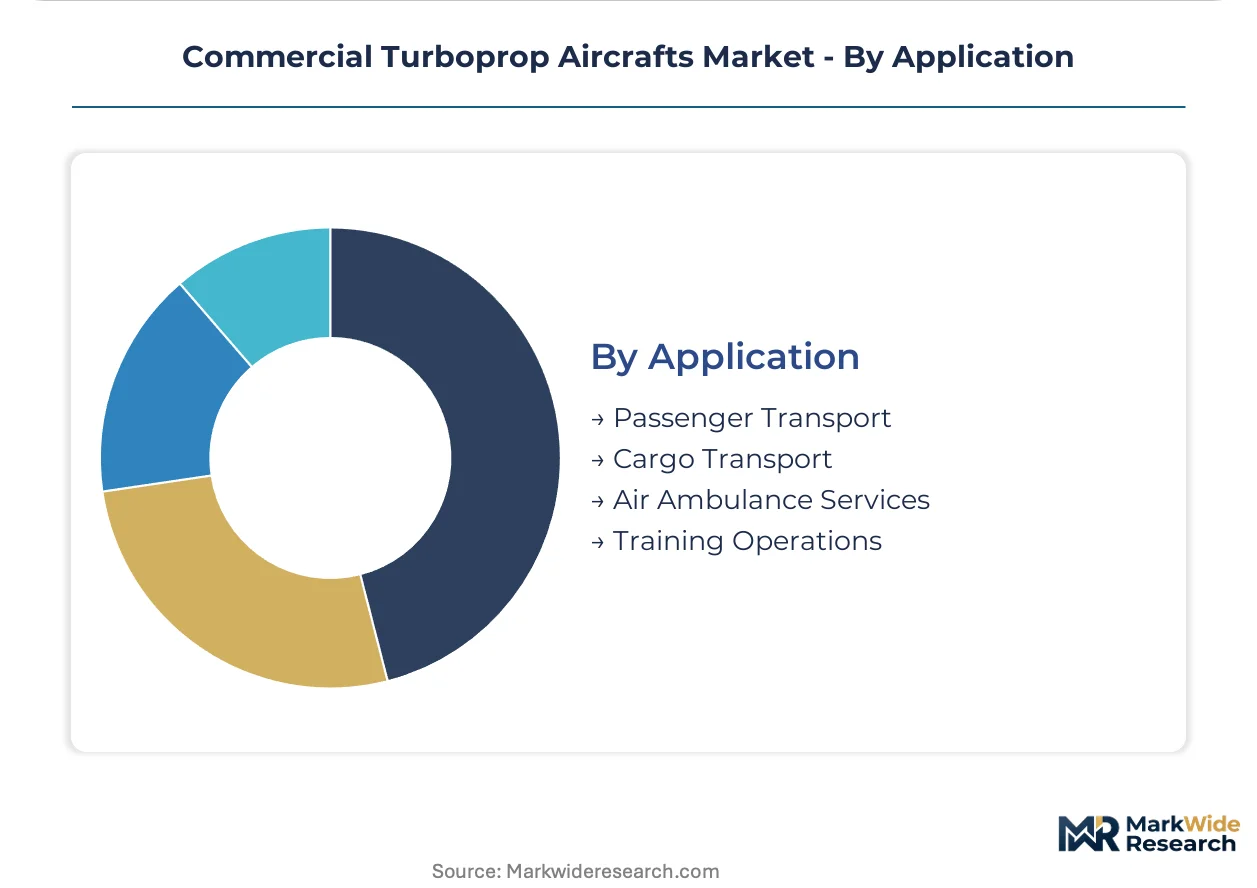
Application:
Application segmentation reveals diverging infrastructure requirements—passenger operations need terminal integration while air ambulance services demand rapid ground access and specialized equipment.
- Air Ambulance Services:Healthcare system decentralization in Canada and Australia generates demand for pressurized turboprop platforms configured for critical care transport. These conversions incorporate medical oxygen systems, electrical inverters for life support equipment, and stretcher loading systems compatible with ground ambulance interfaces. Operators specify short-field capability for hospital helipad and regional airport access.
- Cargo Transport:Dedicated freight networks exploit turboprop economics at secondary airports lacking jet infrastructure, particularly across archipelagic Southeast Asia where maritime alternatives face port congestion. Hub-and-spoke models converge with unmanned aerial system corridors for autonomous last-mile distribution.
- Passenger Transport:Scheduled service remains the most mature segment with established route structures and yield management systems.
- Training Operations:Flight schools specify durable airframes with forgiving handling characteristics for high-cycle ab initio instruction.
Passenger Transport commands current volume. Air Ambulance Services present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's archipelagic airline sector concentrates turboprop deployment for island-hopping connectivity where runway constraints exclude jet operations. FAA and EASA certification standards reshape fleet economics across operator bases. Regional procurement patterns diverge between tropical corrosion resistance requirements and cold-weather operational specifications.
United States
Cargo operators at secondary airports exploit turboprop lift capacity as e-commerce logistics networks expand beyond jet-served hubs. The Inflation Reduction Act's SAF tax credits compress payback periods for fleet renewal decisions. Textron Aviation anchors the North American charter and corporate niche through its King Air manufacturing presence in Wichita, Kansas.
Indonesia
Domestic carriers deploy twin-engine configurations across island corridors where ETOPS flexibility prevents passenger stranding on overwater segments. National aviation authority mandates reinforce short-haul connectivity requirements for underserved routes. Jakarta-based operators lock multi-year block-hour agreements with freight forwarders displacing traditional passenger-to-cargo conversions.
Canada
Healthcare system decentralization generates demand for pressurized turboprop platforms configured for critical care transport to remote communities. Transport Canada certification requirements govern air ambulance modifications for hospital helipad compatibility. De Havilland Aircraft of Canada dominates rugged, high-cycle airframe production for Alaskan and northern operations from its Toronto-area facilities.
France
EASA CS-25 Stage 5 noise limits force nacelle redesign investments to preserve slot access at curfew-restricted hubs including London City and Frankfurt. The EU Green Deal's sustainable aviation fuel mandates favor existing turboprop fleets with lower fuel burn baselines. ATR leverages its Toulouse manufacturing base to sustain European dominance in regional twin-engine segments.
Brazil
Regional jet substitution pressures from Embraer's E-Jet family capture frequency-sensitive routes where turboprops previously held cost advantages on longer runways. ANVISA-equivalent aviation regulations align with FAA Part 25 standards for import certification. São Paulo-state operators balance turboprop economics against jet speed advantages on trunk routes exceeding 1,200 meter runway thresholds.
Commercial Turboprop Aircrafts Market Vendor Landscape
Global majors compete with regional champions across certification jurisdiction and propulsion integration depth. The installed base concentrates around OEMs with captive turbine supply chains and established EASA-FAA dual certification pathways. Three archetypes dominate: European-heritage airframe-engine integrators, North American specialty manufacturers, and diversified aerospace conglomerates with turboprop divisions. Competitive dynamics center on hybrid-electric propulsion partnerships and SAF-ready engine retrofit programs rather than capacity expansion.
Within the European-heritage integrator tier, ATR and Airbus SE exemplify airframe-engine vertical control strategies. Among North American specialists, Textron Aviation Inc. and De Havilland Aircraft of Canada Limited occupy positions defined by mission-specific ruggedness and corporate charter customization. Daher represents the diversified industrial group archetype with aerospace divisions serving regional connectivity mandates. These three groupings anchor procurement patterns across archipelagic Southeast Asia, remote Canadian operations, and European noise-restricted hubs.
| Leading Market Players |
|---|
| ATR |
| Airbus SE |
| Textron Aviation Inc. |
| Pilatus Aircraft Ltd. |
| Lockheed Martin Corporation |
| De Havilland Aircraft of Canada Limited |
| Daher |
| Embraer S.A. |
| Bombardier Inc. |
| Others |
Supply Flow & Price Mechanics
Titanium sponge from Russian and Chinese smelters flows through engine OEM pricing tiers, with aerospace-grade alloy premiums compressing margins for airframers lacking captive metallurgy capacity. Spot market volatility in high-temperature alloys forces long-term offtake contracts that differentiate procurement costs between integrated and non-integrated manufacturers.
Pricing Analysis
Input-cost pass-through from titanium and composite resin suppliers dominates turboprop pricing structures. Three-tier pricing stratifies across ETOPS-certified twin-engine platforms, regional utility configurations, and basic training airframes. Certification grade—specifically FAA Part 25 and EASA CS-25 compliance tiers—commands substantial premiums over non-compliant legacy inventory. Pricing pressure stems from regional jet substitution on runways exceeding 1,200 meters, with Embraer's E-Jet family eroding turboprop cost advantages. Cargo operators exhibit highest price sensitivity due to block-hour economics focus, while air ambulance services prioritize capability over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-scale airline procurement, while specialized distributors serve charter and government segments. Manufacturing concentrates in France, Canada, and the United States, with ATR's Toulouse facilities, De Havilland's Toronto operations, and Textron's Wichita plant anchoring regional output. Supply chains draw from titanium sponge producers in Russia and China, carbon fiber prepregs from Japan and the United States, and avionics systems from European and North American electronics clusters. Single-source vulnerability in high-temperature alloy supply creates exposure to export restriction shocks. Distribution runs through OEM direct sales teams for major carriers, supplemented by regional distributors for aftermarket parts and smaller operator support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial turboprop demand compounds steadily as archipelagic connectivity mandates and e-commerce logistics expansion create durable replacement cycles. Regional jet substitution threats remain localized to specific runway-length segments, preserving core market stability.
For Market Incumbents: Cement airframe-engine integration advantages through hybrid-electric propulsion partnerships that lock in next-generation certification pathways. Defend against regional jet encroachment by emphasizing 800-meter runway performance where competitors cannot operate. Prioritize backward integration into titanium alloy supply through long-term offtake agreements with Australian and Japanese sponge producers, reducing exposure to Russian supply disruption. For New Entrants and Emerging Players: Regional cargo operators in Southeast Asia present the most penetrable entry point, with Indonesian and Philippine forwarders consolidating procurement through dedicated capacity contracts rather than established OEM relationships. Target air ambulance conversion specialists in Canada and Australia seeking pressurized platforms for healthcare decentralization mandates. Pursue STC (Supplemental Type Certificate) pathways for niche mission configurations rather than clean-sheet airframe development. For Investors and Strategic Acquirers: Consolidation pressure builds where hybrid-electric engineering talent scarcity constrains program staffing for mid-tier airframers. Long-term viability favors OEMs with captive turbine supply chains and established EASA-FAA dual certification pathways. Monitor flight-test milestones for gas turbine-electric architectures as the critical signal for residual value inflection across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Flight-test progress at Universal Hydrogen and ZeroAvia determines next-generation platform competitiveness against regional jets. |
| SAF-Ready Engine Retrofit Program | Pratt & Whitney Canada's PT6 E-Series upgrades preserve residual value as EU Green Deal blending mandates tighten. |
| Air Ambulance Conversion Certification | Transport Canada and FAA STC pathways for pressurized critical-care configurations unlock healthcare decentralization budgets. |
| Archipelagic Route Network Expansion | Indonesia's Directorate General of Civil Aviation mandates reinforce twin-engine ETOPS deployment across island corridors. |
| Titanium Supply Diversification | Long-term offtake agreements with Japanese and Australian sponge producers reduce Russian supply concentration risk. |
Methodological Framework
Coverage spans North America, Europe, and Southeast Asia, with primary inputs from each region's regulatory and operator base. The study combines structured interviews with fleet planning executives at regional carriers, procurement leads at cargo operators, certification engineers at FAA and EASA, and aftermarket service directors at MRO facilities. Secondary validation draws from FAA Type Certificate Data Sheets, EASA CS-25 certification amendments, Indonesian DGCA fleet registration databases, and Transport Canada airworthiness directives. Bottom-up unit economics modeling triangulates against top-down market sizing from OEM delivery disclosures and lessor portfolio data.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models propulsion architecture, operator type, and application segments, with additional granularity on runway performance tiers and corrosion-resistant material specifications. CAGRs derive from installed base replacement cycles, route network expansion plans, and regulatory mandate timelines. Forecast inputs incorporate ETOPS rule evolution, SAF tax credit durability, and hybrid-electric technology readiness assessments without specifying transition dates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propulsion technology disruption and titanium supply geopolitics. The analysis reflects assumptions regarding certification timeline stability, regional connectivity mandate continuity, and e-commerce logistics growth persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Strategic Bomber Market
Aircraft
Europe Helicopters Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Helicopter Lighting Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Aircraft Jack Market
Aircraft
America Attack Helicopter Market
Aircraft
Fixed Wing Turbine Aircraft Market