
 Colombia Container Glass Market | 2026-2036
Colombia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Container Glass Market Insights
Lightweighting technology is reconfiguring furnace economics and mold design across Colombian glassworks. O-I Glass, Inc. leverages its Barranquilla furnace complex to sustain bulk supply contracts with multinational beverage brands. Distribuidora Cordoba SAS anchors regional distribution networks through Antioquia and the Coffee Axis. CFC CAFARCOL SAS specializes in decorated and colored glass for premium aguardiente and rum presentations.
Container glass denotes soda-lime-silica vessels formed by blow-and-blow or press-and-blow processes, typically containing 70-74% silica, 12-16% soda ash, and 10-13% lime for chemical durability and thermal shock resistance. These vessels serve as inert, impermeable packaging for carbonated beverages, pharmaceuticals, and personal care formulations. Bottles dominate volume throughput due to entrenched refillable systems in beer and soft drinks, while Jars command margin concentration in gourmet food exports. The Food & Beverage end-user segment absorbs the majority of furnace output, with Pharmaceuticals representing the fastest-expanding demand pool as serialization and anti-counterfeiting requirements intensify.
Colombia's Ministry of Environment and Sustainable Development enforces post-consumer packaging recovery targets through Extended Producer Responsibility frameworks, while the National Food and Drug Surveillance Institute (INVIMA) mandates pharmacopeial-grade glass specifications for sterile drug containment. These dual regulatory tracks elevate compliance costs for imported cullet and virgin batch formulations. Stakeholders must monitor impending carbon pricing mechanisms and their interaction with natural gas-fired furnace operations.
Market Dynamics
Lightweighting technologies are compressing per-unit material throughput across Colombian glassworks while furnace operators recalibrate batch chemistry to maintain thermal shock resistance. This technical pivot intersects with INVIMA's escalating pharmacopeial-grade specifications for sterile drug containment.
Growth Catalysts
- Extended Producer Responsibility frameworks:Colombia's Ministry of Environment recovery mandates are accelerating returnable bottle loop closure rates. Beverage bottlers in Bogotá and Medellín are expanding refillable glass fleets under compliance pressure.
- Aguardiente and rum premiumization:Distilled spirits exporters are commissioning decorated and colored glass presentations. CFC CAFARCOL SAS and specialty decorators are capturing margin concentration through aesthetic differentiation.
- Lightweighting furnace retrofits:Silica consumption per container is declining through precision mold design and optimized blow-and-blow parameters. Barranquilla furnace complexes are achieving energy efficiency gains that lower natural gas exposure.
Market Restraints
- Natural gas price volatility:Furnace operations remain tethered to imported LNG pricing cycles. Colombian glassworks lack fuel-switching flexibility that electric melting alternatives would provide.
- Imported cullet contamination:Post-consumer recovery streams contain ceramic and stone inclusions that damage furnace refractories. INVIMA batch purity standards restrict feedstock sourcing options.
- Aluminum can substitution:Carbonated soft drink bottlers are testing metal formats for single-serve portions. Returnable glass economics weaken when refill rates drop below threshold levels.
Strategic Opportunities
- Antioquia and Coffee Axis distribution densification:Regional logistics networks remain underdeveloped relative to Bogotá corridor concentration. Distribuidora Cordoba SAS infrastructure provides template for hub expansion.
- Pharmaceutical serialization compliance:INVIMA track-and-trace mandates for sterile drug containment are elevating pharmacopeial-grade glass specifications. Dedicated pharma furnace capacity commands premium positioning.
- Carbon pricing mechanism preparation:Pending natural gas emissions levies will reward early furnace efficiency investments. Lightweighting and cullet ratio optimization become defensive capabilities.
Industry Challenges
- Refractory engineering talent scarcity:Colombian technical institutes produce insufficient furnace maintenance specialists. Glassworks compete with mining and cement sectors for high-temperature process engineers.
- Batch chemistry certification timelines:INVIMA pharmacopeial-grade approvals require extended validation cycles. New colorant and coating introductions face regulatory queue bottlenecks.
- Legacy mold inventory stranding:Pre-lightweighting bottle designs accumulate depreciation without volume throughput. Furnace operators face write-down pressure while funding new mold capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Container Glass Market |
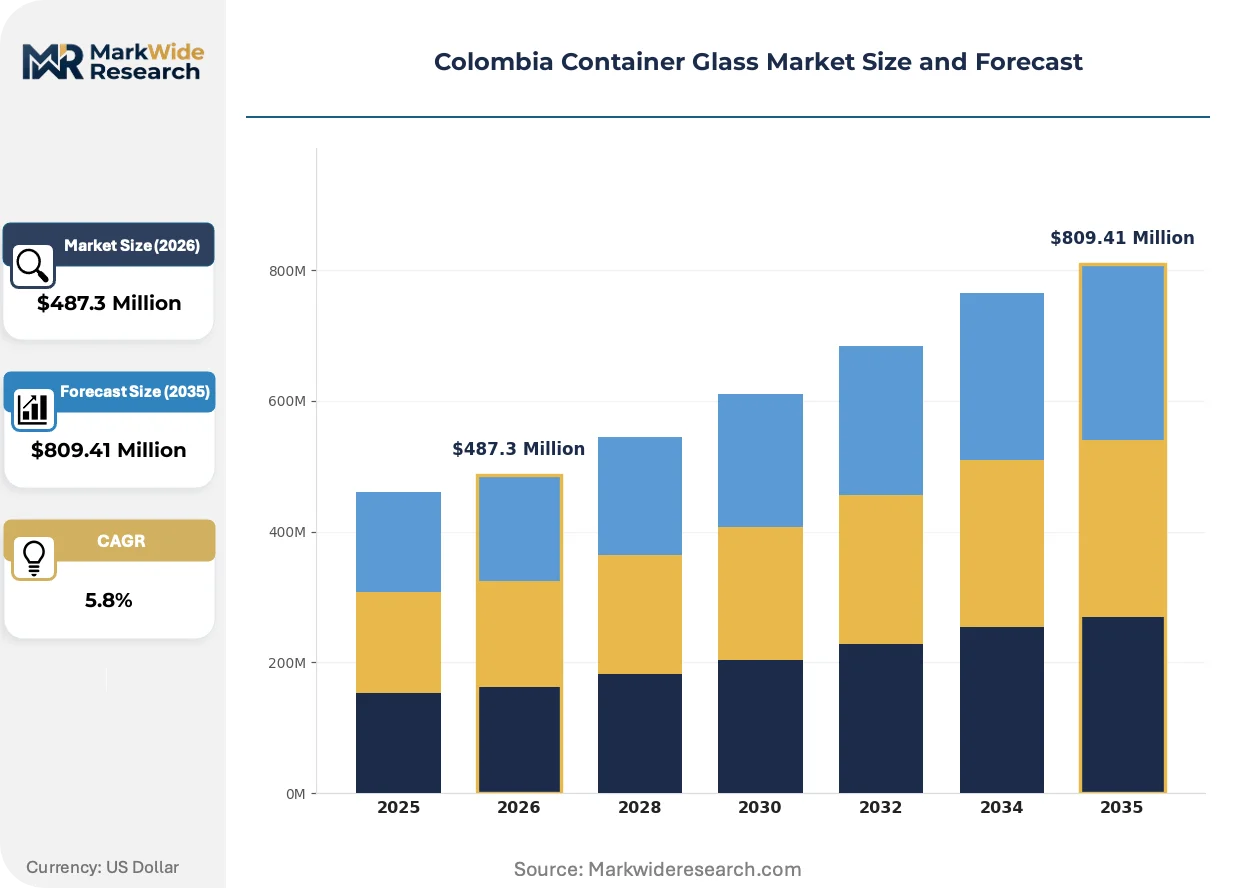
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tumblers, Jugs End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Application: Packaging, Storage, Transportation, Display Weight Category: Lightweight, Standard, Heavyweight, Premium |
| Companies Covered | O-I Glass, Inc., Distribuidora Cordoba SAS, CFC CAFARCOL SAS, New High Glass, Feemio Group Co., Ltd., Vitro, Ardagh Group, Gerresheimer AG, Wheaton Brasil Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Container Glass Market Trends and Innovations
Colombian container glass manufacturing is converging on precision forming and regulatory-grade specialization. Technical investment patterns favor quality certification over commodity volume expansion.
Narrow-neck press-and-blow (NNPB) forming is rendering obsolete traditional blow-and-blow methods for sub-350ml containers. Premium spirits bottlers in the Coffee Axis are specifying NNPB for dimensional consistency and label adhesion. This precision is compressing defect rates and enabling thinner wall profiles without strength compromise.
INVIMA's pharmacopeial-grade glass specifications are tightening permissible alkali leaching thresholds for sterile drug containment. Pharmaceutical contract manufacturers must now qualify dedicated furnace campaigns or source imported molded glass. Compliance costs are concentrating supply relationships around certified domestic producers with validated batch records.
Refillable bottle pooling systems are displacing single-use ownership models among Andean beverage bottlers. Bogotá-based beer producers are outsourcing container fleet management to specialized logistics operators. This service unbundling is visible across carbonated soft drink and mineral water segments where transport economics favor shared infrastructure.
Colombia Container Glass Market Segmentation
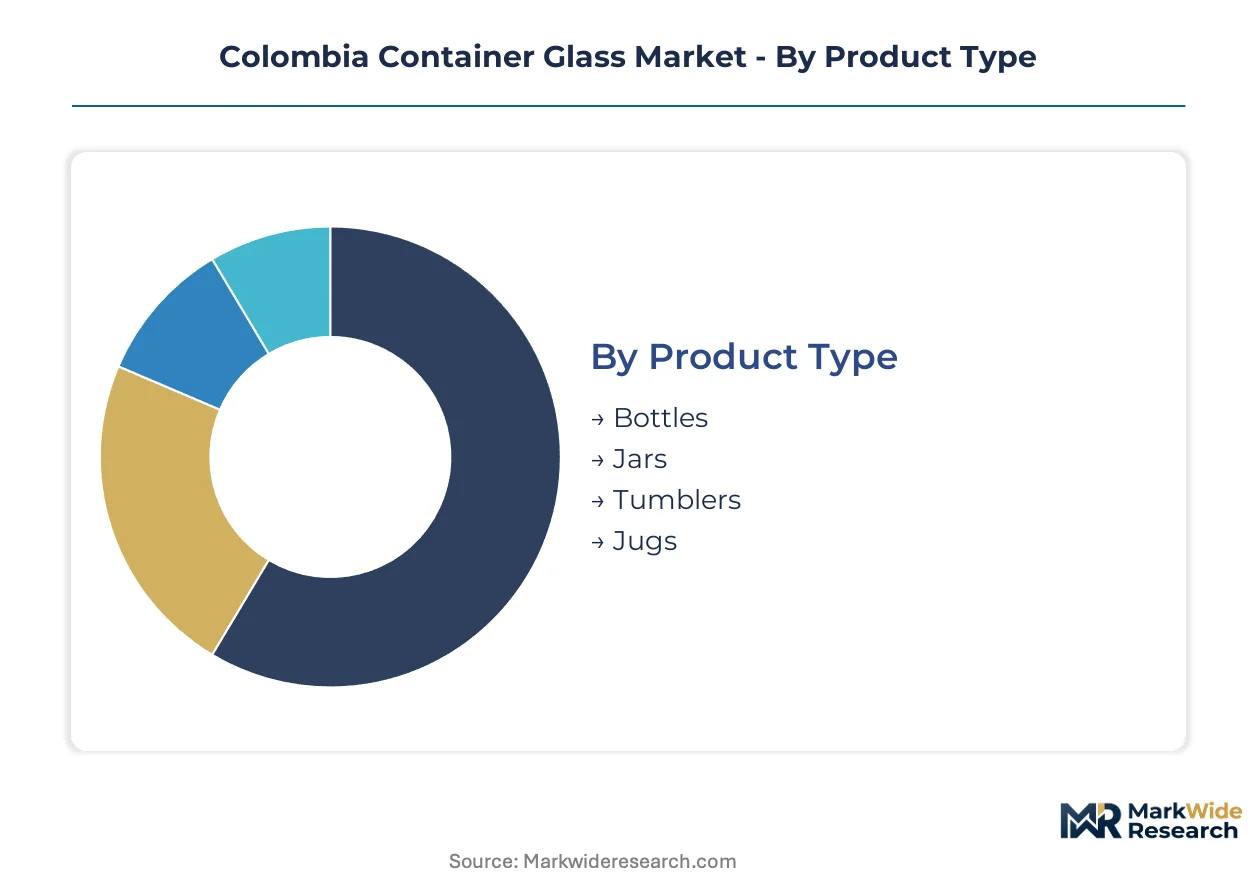
Segmentation in Colombia's container glass market reveals how furnace capacity allocation, INVIMA compliance tiers, and returnable logistics networks intersect. Understanding these divisions exposes where margin concentrates and where lightweighting investments yield competitive defense.
Product Type:
Cost tier differentiation separates commodity volume plays from premium decorated formats across Colombian glassworks.
- Bottles:Soda-lime-silica vessels formed through blow-and-blow or narrow-neck press-and-blow processes dominate furnace throughput. Bogotá and Medellín beverage bottlers sustain demand through refillable beer and soft drink fleets under Extended Producer Responsibility mandates.
- Jars:Wide-mouth containers with heavier wall specifications serve gourmet food exports and premium spirits presentations. Coffee Axis producers commission decorated closures for differentiated shelf positioning in international markets.
- Tumblers:Stemless drinking vessels capture hospitality procurement contracts with standardized durability ratings.
- Jugs:Large-format containers with reinforced handles target bulk liquid distribution and institutional food service channels.
Bottles command the established base. The steepest expansion runs through Jars as premium aguardiente and rum exports accelerate.
End User:
Application intensity varies dramatically across customer types, with compliance burden and volume scale operating in inverse proportion.
- Food & Beverage:Carbonated soft drink, beer, and mineral water bottlers absorb the majority of domestic furnace output. Returnable bottle pooling systems in Bogotá corridor concentrate procurement relationships around O-I Glass and regional distributors.
- Pharmaceuticals:Sterile drug containment demands pharmacopeial-grade batch chemistry with validated alkali leaching thresholds. INVIMA serialization mandates are elevating certification requirements for domestic producers.
- Personal Care:Cosmetic and fragrance brands specify colored and coated glass for premium positioning. Shorter production runs favor flexible furnace operators with quick color change capability.
- Household Products:Cleaning and chemical formulations require chemical durability specifications distinct from food-grade standards. Price sensitivity drives procurement toward standard weight categories.
Food & Beverage commands the established base. The steepest expansion runs through Pharmaceuticals as track-and-trace compliance intensifies.
Application:
Functional role determines wall thickness, closure specification, and logistics durability requirements across the segment set.
- Packaging:Primary containment functions demand hermetic sealing compatibility and label adhesion surfaces. Lightweighting investments target this segment for per-unit material reduction without transport damage compromise.
- Storage:Extended shelf-life applications require UV protection through amber or cobalt coloration. Gourmet food exporters in Antioquia specify storage-optimized jars for international distribution.
- Transportation:Returnable fleet containers prioritize impact resistance over aesthetic finish. Pooled bottle operators in Medellín corridor amortize durability through high trip rates.
- Display:Point-of-sale visibility drives decorated, embossed, and specialty color demand. Premium spirits bottlers commission limited runs with CFC CAFARCOL SAS for differentiated retail presence.
Packaging commands the established base. Display applications are climbing the fastest as premiumization strategies proliferate.
Weight Category:
Material throughput per unit separates efficiency-optimized formats from durability-premium specifications in furnace campaign planning.
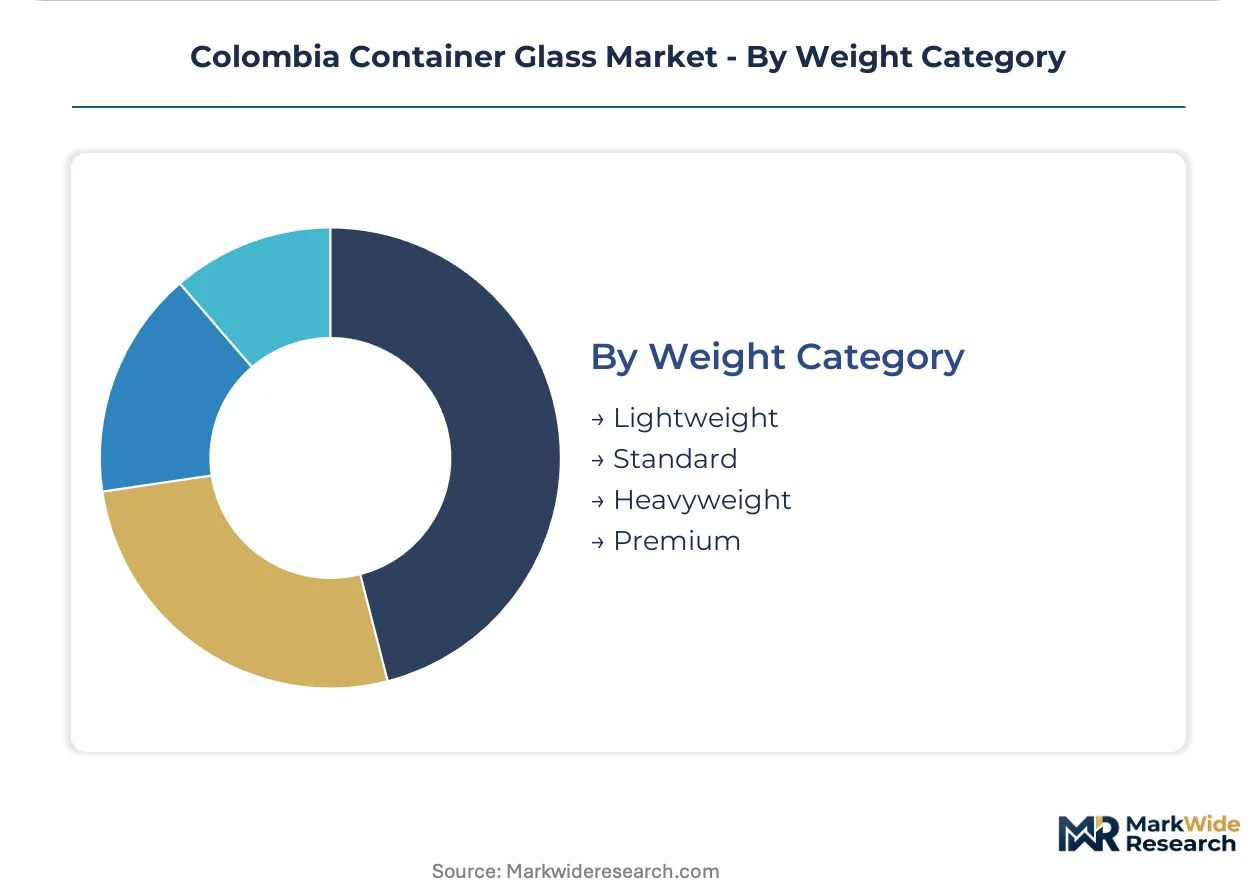
- Lightweight:Precision-formed containers below historical wall thickness thresholds reduce silica consumption and natural gas exposure. Barranquilla furnace retrofits target this category for carbon pricing preparation.
- Standard:Conventional weight specifications balance material cost against supply chain damage rates. Majority of refillable beverage bottles operate in this tier.
- Heavyweight:Reinforced walls for high-trip returnable fleets or hazardous contents. Limited production runs due to material cost disadvantage.
- Premium:Massive decorative pieces for luxury spirits gifting and collector markets. Marginal volume contribution but disproportionate margin capture.
Standard weight commands the established base. Lightweight formats are gaining share fastest as furnace efficiency investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and pharmaceutical contract manufacturers anchor demand across Colombia's regional markets. Furnace capacity clusters around coastal logistics nodes and Andean population centers. Extended Producer Responsibility mandates and INVIMA compliance requirements reshape procurement geography.
Andean Region
Bogotá's metropolitan beverage bottlers sustain the highest refillable bottle trip rates under Ministry of Environment recovery targets. INVIMA pharmacopeial-grade specifications concentrate sterile drug containment demand in Cundinamarca's qualified furnace campaigns. Medellín corridor glassworks serve Antioquia's aguardiente premiumization wave through decorated format specialization.
Caribbean Coast
Barranquilla's furnace complex leverages deepwater port access for bulk silica import and export-oriented spirits packaging. National Circular Economy Strategy compliance pressures drive returnable fleet expansion among coastal soft drink distributors. Lightweighting retrofits at this node target natural gas efficiency ahead of pending carbon pricing mechanisms.
Coffee Axis
Caldas, Quindío, and Risaralda gourmet food exporters commission decorated jar formats for international shelf differentiation. Regional logistics networks through Pereira and Manizales remain underdeveloped relative to Bogotá corridor density. Distribuidora Cordoba SAS infrastructure provides template for hub-and-spoke distribution densification.
Pacific Region
Buenaventura port proximity offers theoretical cullet import advantages for batch chemistry flexibility. Post-consumer recovery stream contamination with ceramic inclusions limits actual feedstock utilization under INVIMA purity standards. Valle del Cauca pharmaceutical manufacturers source qualified containment glass from certified domestic campaigns.
Colombia Container Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across furnace capacity and decoration capabilities. The market structure concentrates around multinational furnace operators with bulk supply contracts and regional distributors with logistics integration. Three archetypes dominate: scale-driven bulk suppliers, premium decoration specialists, and regional logistics integrators. Capacity expansion and lightweighting technology licensing represent the primary competitive moves.
Among multinational furnace operators, O-I Glass, Inc. anchors the scale-driven tier with Barranquilla complex positioning. Regional specialists exemplify logistics-integrated distribution models—Distribuidora Cordoba SAS occupies the Antioquia corridor consolidation position, while CFC CAFARCOL SAS represents the premium decoration archetype for spirits aesthetic differentiation. These three entities collectively illustrate the competitive spectrum from commodity volume to margin-capture specialization.
| Leading Market Players |
|---|
| O-I Glass, Inc. |
| Distribuidora Cordoba SAS |
| CFC CAFARCOL SAS |
| New High Glass |
| Feemio Group Co., Ltd. |
| Vitro |
| Ardagh Group |
| Gerresheimer AG |
| Wheaton Brasil Group |
| Others |
Pricing and Supply Chain Analysis
Barranquilla furnace complex utilization rates above 85% are tightening supply discipline among Colombian glassworks and compressing buyer negotiation leverage across refillable beverage contracts. This capacity tightness simultaneously elevates supplier pricing power and accelerates lightweighting investments that reduce per-unit silica exposure.
Pricing Analysis
Natural gas-indexed cost-plus contracts dominate procurement relationships between beverage bottlers and furnace operators, with silica batch and soda ash pass-through clauses resetting quarterly. Three-tier pricing structure across pharmacopeial-grade, food-grade, and industrial-grade certifications captures margin differentiation, with INVIMA-validated pharma glass commanding substantial premiums over commodity beverage formats. Pricing pressure stems from aluminum can substitution trials in single-serve soft drink portions. Carbonated soft drink bottlers exhibit highest price sensitivity due to thin refill economics, while pharmaceutical contract manufacturers accept premium positioning for serialization compliance.
Supply Chain Analysis
Upstream silica sand feeds from domestic deposits in Cundinamarca and Boyacá, with high-purity batch chemicals imported from Brazil and the United States. Soda ash, limestone, and specialty colorants constitute the critical input trinity, with furnace refractories sourced from European suppliers. Single-source vulnerability concentrates in natural gas supply through imported LNG regasification terminals at Cartagena and Buenaventura. Distribution runs through hub-and-spoke networks anchored by Bogotá and Medellín, with coastal export corridors utilizing Barranquilla port access for spirits packaging shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container glass economics in Colombia are reconfiguring around service-attach revenue streams, with refillable bottle fleet management and pooling logistics expanding faster than virgin container sales. This operational service layer captures recurring revenue from beverage bottlers outsourcing container lifecycle management.
For Market Incumbents: Entrench market position through dedicated pharmaceutical furnace campaigns certified to INVIMA pharmacopeial-grade specifications, defending against imported molded glass substitution. Backward integration into cullet preprocessing facilities mitigates contamination risk from post-consumer recovery streams. Capacity discipline at Barranquilla prevents oversupply erosion in standard-weight beverage formats. For New Entrants and Emerging Players: Premium spirits decoration capabilities in the Coffee Axis represent the most penetrable entry point, with gourmet food exporters commissioning limited-run colored and embossed jars for international shelf differentiation. Quick-color-change furnace flexibility targets personal care and cosmetic brands with short production runs. Direct relationships with Antioquia aguardiente bottlers bypass established distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among logistics-integrated operators managing pooled refillable fleets under Extended Producer Responsibility mandates. Long-term viability over a 5-10 year horizon favors certified domestic producers with validated batch records and carbon pricing preparation. The signal to watch is INVIMA serialization mandate expansion beyond sterile drugs into biologics and vaccines.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Furnace Retrofit | Barranquilla complex investments reduce natural gas exposure ahead of pending carbon pricing mechanisms. |
| Pharmacopeial-Grade Certification | INVIMA validation opens sterile drug containment contracts with premium pricing over commodity beverage glass. |
| Returnable Fleet Management Service | Outsourced pooling logistics capture recurring revenue from Bogotá beverage bottlers under recovery mandates. |
| Cullet Preprocessing Integration | In-house contamination control secures feedstock quality for batch chemistry compliance without import dependency. |
| Coffee Axis Distribution Densification | Hub-and-spoke infrastructure through Pereira and Manizales reduces logistics cost for gourmet food exporters. |
Research Methodology
A standing panel of furnace operations managers, beverage procurement directors, pharmaceutical quality assurance leads, and logistics fleet operators provided ongoing calibration across primary interview rounds. Secondary validation drew from INVIMA regulatory filings, Ministry of Environment Extended Producer Responsibility compliance reports, customs import data for batch chemicals, and natural gas pricing indices from Colombian energy regulators. Bottom-up segmentation modeling triangulated against top-down macroeconomic projections for container glass demand intensity.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing for natural gas price volatility and carbon pricing implementation timing. Segmentation dimensions modeled include product type, end-user industry, weight category, and regional logistics corridor. CAGRs were derived from historical furnace capacity utilization trends projected against refillable fleet expansion rates and pharmaceutical serialization compliance deadlines. Lightweighting technology adoption curves and cullet ratio optimization pathways served as industry-specific forecast inputs.
Practitioners should monitor INVIMA regulatory queue bottlenecks and natural gas import tariff adjustments for early signals requiring forecast revision. Cross-checking against furnace capacity announcements from O-I Glass and regional distributor expansion disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market