
 Uruguay Container Glass Market | 2026-2036
Uruguay Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Uruguay Container Glass Market Insights
Premium beverage exporters is unwinding legacy procurement patterns among commodity food packagers. Uruglass Ltda. anchors domestic supply through its Montevideo manufacturing base, while Owens-Illinois extends regional distribution networks into Uruguay from its broader Latin American footprint. Fabrica de Envases de Vidrio SA differentiates through specialized pharmaceutical-grade container output.
Container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, typically containing 70% silica, 15% soda ash, and 10% lime with thermal shock resistance exceeding 40°C for beverage applications. Bottles command the largest volume share as wine and spirits producers standardize on heavyweight designs, while amber glass captures expanding share from pharmaceutical serialization mandates requiring UV-blocking properties. Jars maintain steady demand in artisanal food segments where visual product display drives shelf appeal.
Uruguay's Ministry of Industry, Energy and Mining (MIEM) enforces energy efficiency benchmarks for glass furnace operations, while LATU certification requirements shape export acceptance criteria for European-bound shipments. INAVI's wine origin labeling rules indirectly mandate container provenance documentation. Stakeholders must weigh furnace electrification timelines against natural gas price volatility when committing to capacity additions.
Market Dynamics
INAVI's tightening wine origin labeling rules are forcing container provenance documentation throughout Montevideo's industrial corridor, compressing supplier qualification timelines and elevating traceability investments across the glass value chain.
Growth Catalysts
- Pharmaceutical serialization mandates:UV-blocking amber glass demand accelerates as drug packaging regulations require enhanced light protection for temperature-sensitive formulations.
- MIEM furnace efficiency benchmarks:Energy performance standards for glass manufacturing operations are driving capital allocation toward electrification retrofits and natural gas hedging strategies.
- Artisanal food visual merchandising:Premium jar formats gain traction among specialty food producers prioritizing shelf transparency and handcrafted brand positioning.
Market Restraints
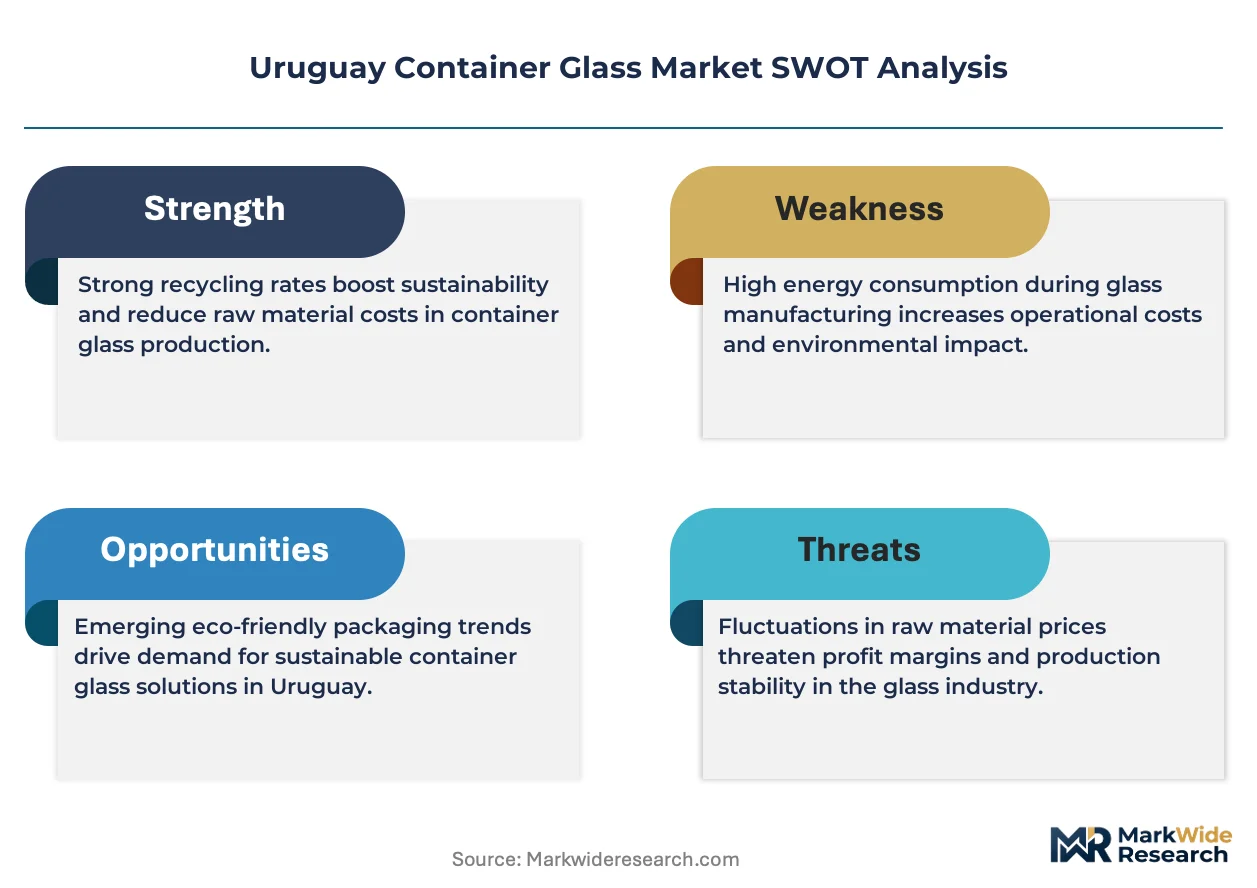
- Soda ash and silica input volatility:Raw material price swings compress margin predictability for furnace operators dependent on imported bulk chemicals.
- Montevideo supply concentration:Domestic manufacturing clusters around a single metropolitan production base, amplifying logistics vulnerability and regional disruption exposure.
- Lightweight PET substitution:Beverage packagers in cost-sensitive segments are trialing plastic alternatives for non-premium wine and spirits distribution.
Strategic Opportunities
- Paysandú corridor expansion:Secondary industrial zones outside Montevideo offer greenfield furnace sites with lower land costs and improved port access.
- Electrochemical glass melting:Hybrid furnace architectures combining oxy-fuel and electric boosting technologies promise 30-40% emissions reductions.
- Direct-to-winery bulk glass programs:Bypassing traditional distributor layers, manufacturers are piloting consignment inventory models with large estate producers.
Industry Challenges
- Furnace rebuild cycle compression:Accelerated refractory wear from higher cullet ratios demands more frequent hot repairs, straining technical crew availability.
- LATU certification timeline uncertainty:Export-bound batches face extended laboratory verification periods, complicating just-in-time delivery commitments to European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uruguay Container Glass Market |
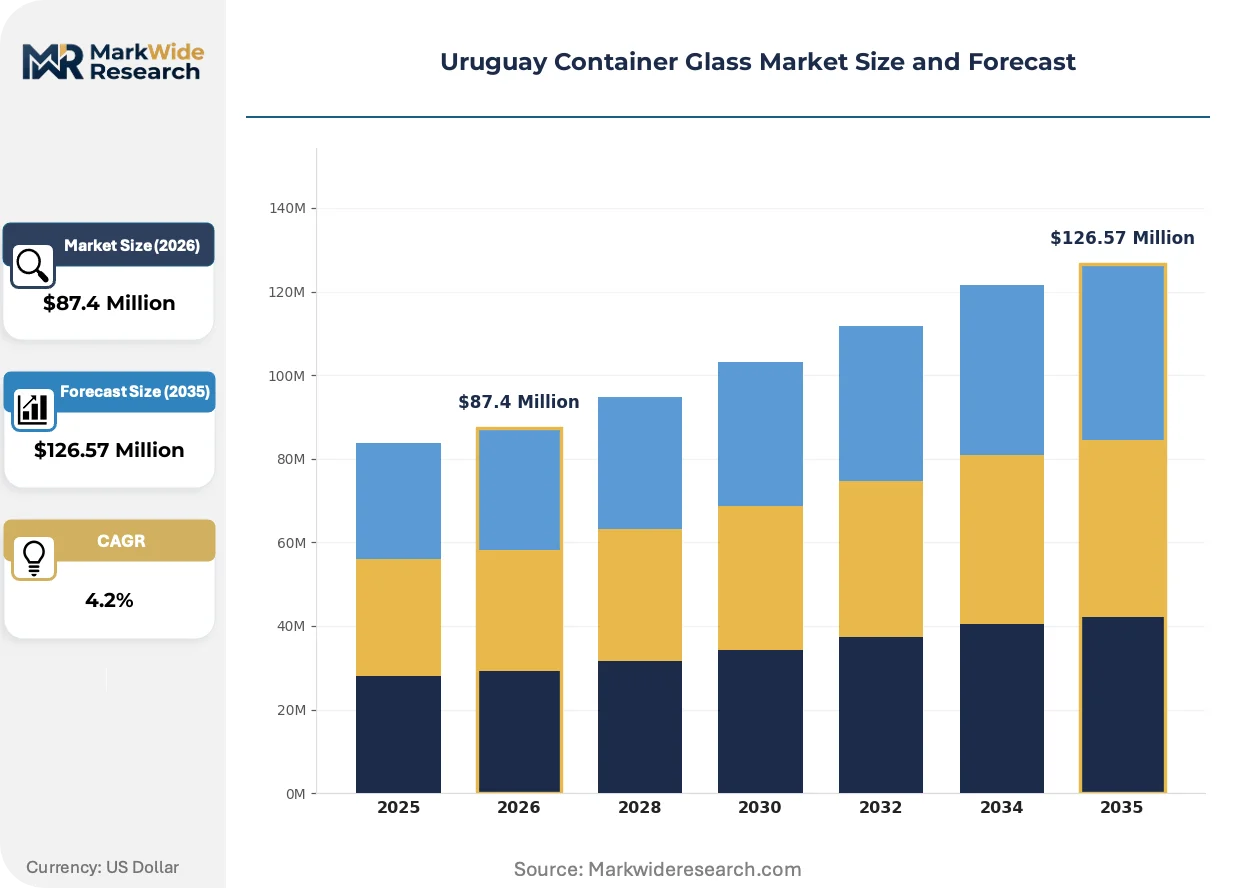
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $126.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Size: Small, Medium, Large, Custom Color: Clear, Green, Amber, Frosted |
| Companies Covered | Feemio Group Co. Ltd, Acril Ltda., Uruglass Ltda., Fabrica de Envases de Vidrio SA, Ebigold S.A., Envidrio, SIMSA, Owens-Illinois, Verallia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uruguay Container Glass Market Trends and Innovations
Container glass manufacturing in Uruguay is experiencing fundamental process reinvention as energy transition pressures intersect with premium beverage packaging demands, reshaping furnace technology roadmaps and procurement relationships simultaneously.
Hybrid oxy-fuel furnace architectures are bifurcating the installed base between legacy natural gas-dependent assets and electrification-ready platforms. Premium wine exporters with INAVI certifications are prioritizing suppliers with verified low-carbon melting credentials, compressing demand toward furnace operators with demonstrated emissions transparency. This technology stratification is forcing mid-tier manufacturers into accelerated capex decisions or niche positioning.
MIEM's phased energy efficiency mandates are tightening operational parameters for soda-lime silica production. Furnace operators must now document thermal performance against declining emissions intensity thresholds, with non-compliant facilities facing production volume restrictions. Montevideo-based manufacturers are responding with regenerative burner retrofits and cullet preheating investments to maintain license continuity.
Winery procurement departments are consolidating supplier rosters around fewer glass partners offering integrated decoration and logistics services. Large estate producers in Canelones and Maldonado are replacing fragmented multi-vendor arrangements with single-source container programs bundling bottle supply, label application, and warehouse staging. This concentration trend is most pronounced among export-oriented wineries shipping to European markets where LATU certification simplifies customs clearance.
Uruguay Container Glass Market Segmentation
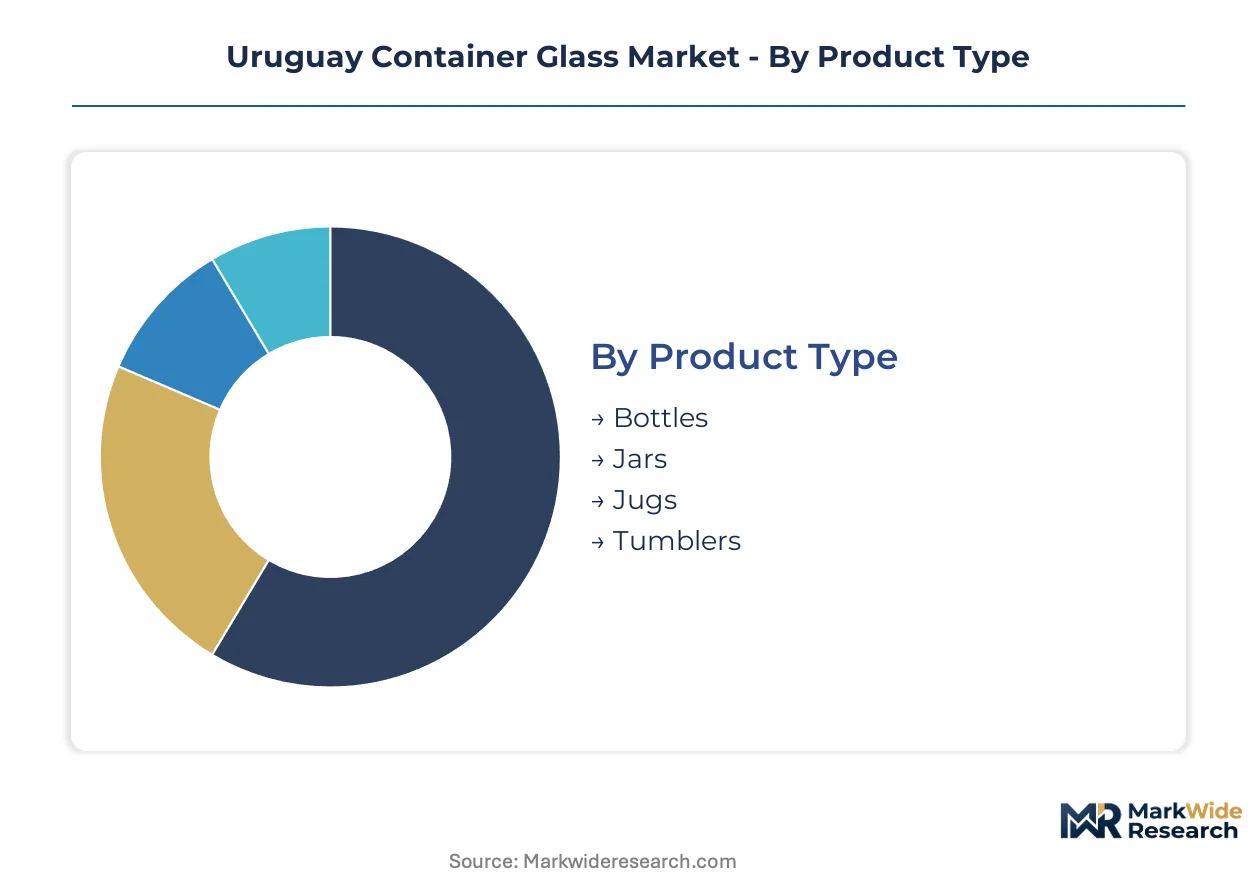
Uruguay's container glass market stratifies across four dimensions that determine furnace scheduling, inventory staging, and distributor relationships. Product geometry and end-use certification requirements create distinct margin profiles, while color specifications tie directly to INAVI traceability mandates and pharmaceutical serialization rules.
Product Type:
Bottles flow through beverage distributors in Montevideo's industrial corridor, while jars and jugs serve fragmented artisanal channels requiring smaller batch runs.
- Bottles:Soda-lime silica vessels formed through blow-and-blow processes, typically 70% silica composition with thermal shock resistance exceeding 40°C. Wine and spirits producers in Canelones and Maldonado standardize on heavyweight designs, compressing procurement toward suppliers with integrated decoration capabilities.
- Jars:Wide-mouth containers produced via press-and-blow forming for visual product display. Artisanal food packagers in Montevideo prioritize shelf transparency, driving demand for clear and frosted finishes with handcrafted brand positioning.
- Jugs:High-capacity vessels for bulk beverage distribution. Regional logistics operators favor standardized formats compatible with existing crate systems.
- Tumblers:Drinking glasses with lower wall thickness requirements. Hospitality procurement in Punta del Este seasonal markets sustains intermittent volume.
Bottles dominate installed base. Jars are where expansion concentrates.
End User:
Margin structure varies sharply across end-use segments, with pharmaceutical and premium beverage applications commanding qualification-intensive supply relationships.
- Food & Beverage:Wine exporters with INAVI certifications require container provenance documentation, elevating traceability investments. MIEM furnace efficiency benchmarks further filter supplier eligibility for this segment.
- Pharmaceuticals:UV-blocking amber glass demand accelerates under drug packaging regulations. LATU certification requirements shape export acceptance criteria, extending laboratory verification timelines.
- Personal Care:Cosmetic brands prioritize aesthetic differentiation through frosted and colored finishes. Batch flexibility matters more than volume scale.
- Household:Standard clear glassware for domestic consumption. Price sensitivity limits supplier margins to commodity-tier furnace economics.
Food & Beverage anchors volume throughput. Pharmaceuticals is climbing the fastest.
Size:
Production scheduling bifurcates between high-volume standardized formats and custom tooling runs requiring dedicated mold investments.
- Medium:750ml wine bottles and 500ml food jars constitute the production sweet spot. Furnace operators optimize pull rates around these dimensions, minimizing changeover downtime.
- Large:Bulk wine formats and industrial chemical containers. Paysandú corridor expansion plans target this segment with improved port access for export-bound shipments.
- Small:Sample sizes and premium miniature spirits. Lower per-unit margins require consolidated batching across multiple SKUs.
- Custom:Estate-specific bottle designs for differentiated brand positioning. Wineries absorb mold amortization costs through multi-year supply commitments.
Medium sizes command furnace priority. Custom formats are gaining share fastest.
Color:
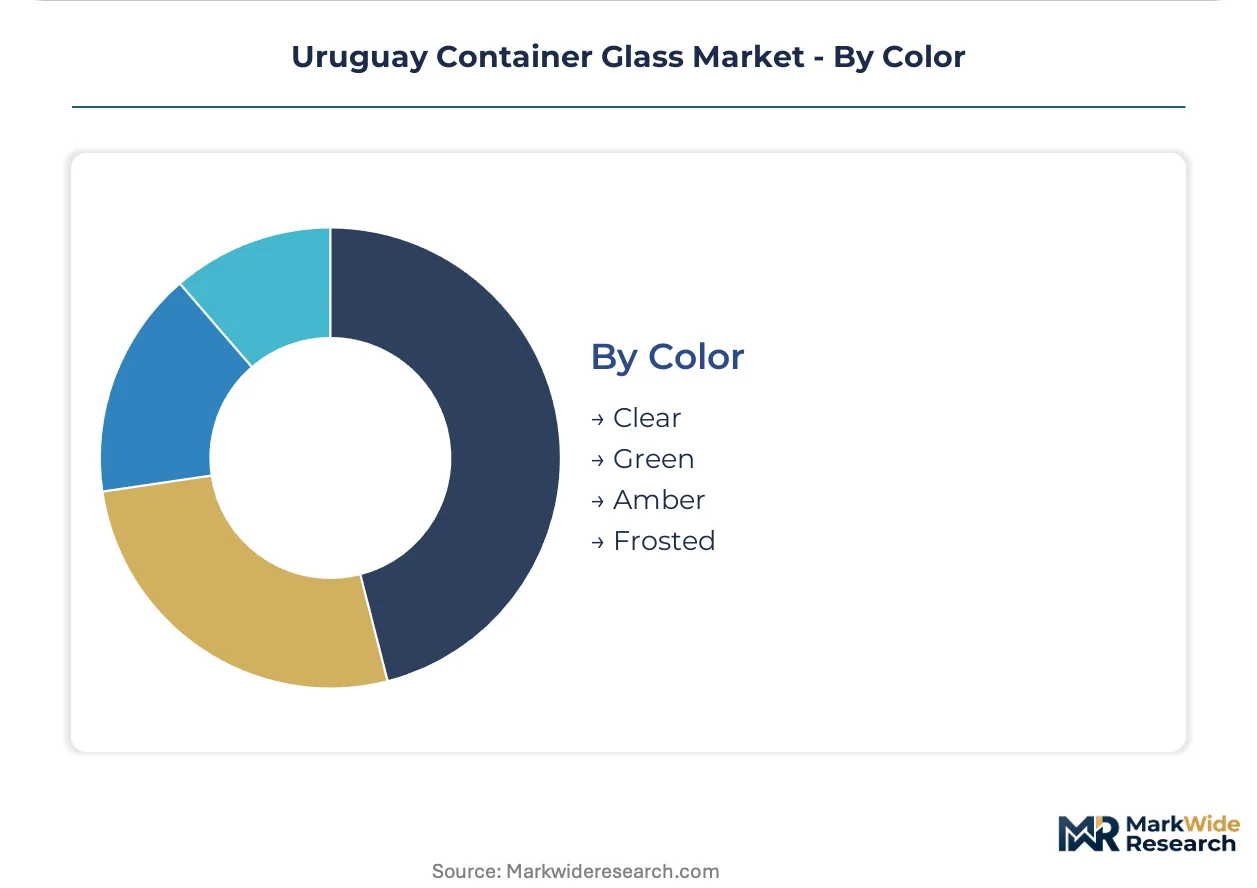
Color selection drives raw material sourcing strategies and recycling loop economics, with amber commanding premium positioning.
- Amber:Iron-sulfur colored glass blocking UV transmission below 450nm. Pharmaceutical serialization mandates and premium wine light protection requirements concentrate demand.
- Clear:Standard soda-lime silica without colorants. Visual merchandising priorities in artisanal food segments sustain steady offtake.
- Green:Chromium oxide tinted glass historically associated with wine traditions. European export markets show declining preference relative to amber alternatives.
- Frosted:Acid-etched or molded matte surfaces for premium cosmetic and gift applications. Secondary processing adds margin but extends lead times.
Clear glass dominates unit volume. Amber is where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Montevideo anchors Uruguay's container glass distribution network, handling silica sand imports and finished glass exports for the Southern Cone beverage corridor.
Montevideo
MIEM furnace efficiency benchmarks filter supplier eligibility for export-bound wineries clustered in the capital's industrial corridor. INAVI traceability mandates compress qualification timelines for container provenance documentation. Paysandú corridor expansion plans target secondary furnace sites with improved Atlantic port access.
Canelones
Premium wine estate producers in this department consolidate procurement around single-source container programs bundling bottle supply with label application. LATU certification requirements extend laboratory verification timelines for European-bound shipments. Maldonado-adjacent bottling clusters anchor amber glass demand for UV-blocking applications.
Maldonado
Export-oriented wineries shipping to European markets prioritize suppliers with verified low-carbon melting credentials. INAVI wine origin labeling rules indirectly mandate container provenance documentation throughout the coastal production zone. Punta del Este seasonal hospitality markets sustain intermittent tumbler volume.
Paysandú
Secondary industrial zones offer greenfield furnace sites with lower land costs and improved port infrastructure for bulk chemical container distribution. MIEM energy performance standards drive capital allocation toward electrification retrofits in this emerging corridor. Regional logistics operators favor standardized jug formats compatible with existing crate systems.
Colonia
Artisanal food packagers prioritize shelf transparency through clear and frosted jar finishes with handcrafted brand positioning. The country's national agricultural regulator enforces packaging material standards for specialty food exports. Buenos Aires-proximate distribution channels concentrate procurement volumes for medium-format food jars.
Uruguay Container Glass Market Competitive Landscape
Listed leaders compete with private specialists across furnace scale and export certification capabilities. The installed base stratifies between multinational volume players and domestic specialists differentiated by pharmaceutical-grade output or integrated decoration services. Three archetypes dominate: scale-driven exporters with regional distribution networks, MIEM-compliant domestic manufacturers with provenance documentation systems, and niche specialists serving serialization-mandated pharmaceutical demand. Competitive moves concentrate on furnace electrification retrofits and direct-to-winery consignment inventory models.
Among domestic specialists, Uruglass Ltda. and Fabrica de Envases de Vidrio SA exemplify the MIEM-compliant archetype with Montevideo manufacturing concentration. Owens-Illinois occupies a position representing scale-driven regional distribution from broader Latin American footprints. These three anchors illustrate how certification depth and furnace technology roadmaps determine competitive positioning under tightening energy efficiency mandates.
| Leading Market Players |
|---|
| Feemio Group Co. Ltd |
| Acril Ltda. |
| Uruglass Ltda. |
| Fabrica de Envases de Vidrio SA |
| Ebigold S.A. |
| Envidrio |
| SIMSA |
| Owens-Illinois |
| Verallia |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Montevideo furnace operators and INAVI-certified wineries lock in silica sand supply access and insulate amber glass pricing from soda ash spot volatility. These arrangements concentrate procurement power among large estate producers in Canelones while compressing margin flexibility for mid-tier commodity packagers.
Pricing Analysis
Volume-discount tiering separates premium INAVI-traceable amber glass from standard clear lines and economy-grade commodity containers. Price differentiation hinges on MIEM furnace efficiency certification status and LATU export clearance bundling. Pricing pressure stems from soda ash import cost swings, with commodity food packagers exhibiting highest price sensitivity and pharmaceutical serializers showing lowest.
Supply Chain Analysis
Inventory staging and lead-time compression dominate supply chain management as LATU laboratory verification extends European-bound shipment windows. Silica sand feeds from Argentina and Brazil, soda ash from the United States and Kenya, with furnace electrodes sourced from Germany. Single-source vulnerability concentrates in Montevideo's industrial corridor. Distribution runs through beverage bottling clusters anchored to Port of Montevideo logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass container incumbents face urgent substitution defense as lightweight PET trials penetrate cost-sensitive wine segments. The structural threat demands repositioning around premium certification tiers where material traceability creates defensible moats.
For Market Incumbents: Consolidate supplier rosters around integrated decoration and logistics capabilities to match single-source container programs demanded by large estate producers. Accelerate MIEM-compliant furnace electrification retrofits before efficiency benchmarks tighten. Channel control through direct-to-winery consignment inventory models defends against PET substitution in non-premium tiers.
For New Entrants and Emerging Players: Integrated pharmaceutical-grade serialization services represent the most penetrable white-space as Fabrica de Envases de Vidrio SA's specialized output faces capacity constraints. Paysandú corridor greenfield sites offer geographic differentiation with lower land costs and improved Atlantic port access. A LATU certification-first go-to-market angle captures European export demand underserved by Montevideo-concentrated incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward MIEM-compliant furnace operators with provenance documentation systems and verified low-carbon melting credentials. Long-term viability favors assets positioned at the intersection of INAVI traceability mandates and pharmaceutical serialization growth. Electrification retrofit completion rates signal inflection timing for margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Retrofit | MIEM compliance secures license continuity under tightening emissions intensity thresholds. |
| Direct-to-Winery Consignment Model | Bypasses distributor layers for large estate producers in Canelones and Maldonado. |
| Pharmaceutical Serialization Certification | Captures UV-blocking amber glass demand under drug packaging regulations. |
| Paysandú Corridor Expansion | Greenfield sites offer lower land costs and improved port access for bulk containers. |
| Integrated Decoration Capability | Matches winery procurement consolidation around bundled bottle supply and label application. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, winery procurement directors, pharmaceutical packaging engineers, and LATU certification officers and refined through secondary validation. Bottom-up triangulation combined customs records on silica sand and soda ash imports, MIEM energy efficiency disclosure filings, and INAVI wine origin labeling compliance databases with top-down market sizing.
Variance decomposition across product type, end-user segment, color specification, and regional production cluster shaped the analytical framework. CAGRs were derived from furnace pull rate projections, winery export volume trajectories, and pharmaceutical packaging regulation implementation timelines. Electrification capex cycles and cullet preheating adoption curves provided industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover MIEM enforcement consistency, LATU laboratory capacity expansion, and soda ash import price corridors, with deviation risk concentrated in furnace rebuild cycle compression and PET substitution acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Spain Packaging Market