
 Switzerland Container Glass Market | 2026-2036
Switzerland Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Container Glass Market Analytics
Swiss container glass manufacturing capacity is hardening around established production clusters in Eastern Switzerland and the Mittelland region. Vetropack Holding SA leverages its integrated furnace network to dominate domestic supply for beverage and food applications. Ardagh Group S.A. competes through specialized lightweighting technologies that reduce per-unit material costs for premium spirits brands. O-I Glass, Inc. anchors its position via long-term supply contracts with multinational pharmaceutical packagers operating from Basel.
Container glass denotes silica-based packaging formed through blow-and-blow or press-and-blow processes, typically comprising 70-75% silicon dioxide with soda ash and limestone fluxes, engineered to provide inert barriers against moisture, oxygen, and chemical migration for sensitive contents. The Food & Beverage end-use segment sustains the largest volume absorption, driven by Swiss mineral water, wine, and craft spirits producers requiring premium presentation and regulatory-compliant contact surfaces. Amber-form glass commands disproportionate margin contribution from pharmaceutical applications, where light-blocking properties protect photosensitive drug formulations across the 100-500ml capacity tier favored by injectable and oral dosage packagers.
Swissmedic enforces pharmacopeial compliance standards that mandate Type I borosilicate or Type III soda-lime glass for drug-contact packaging, while the EU Green Deal's packaging and packaging waste regulation extends producer responsibility for post-consumer collection. REACH chemical registration requirements govern colorant and stabilizer additives used in decorative and functional glass treatments. Stakeholders must monitor evolving Swiss federal ordinances on recycled content mandates and assess furnace decarbonization pathways against natural gas dependency.
Market Dynamics
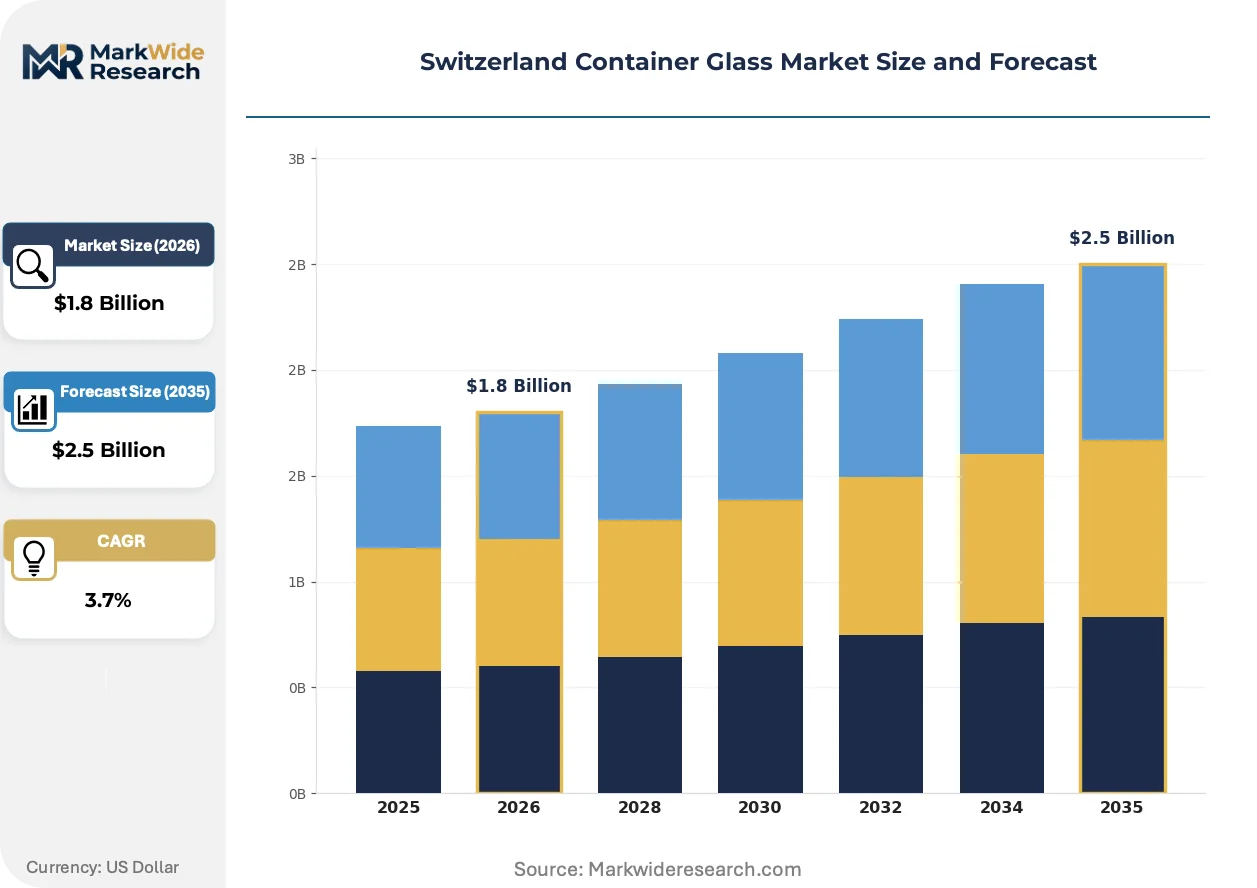
EU Green Deal circular economy mandates are forcing Swiss container glass producers to reconfigure furnace operations around post-consumer cullet recovery, while Basel's pharmaceutical cluster intensifies Type I borosilicate demand.
Growth Catalysts
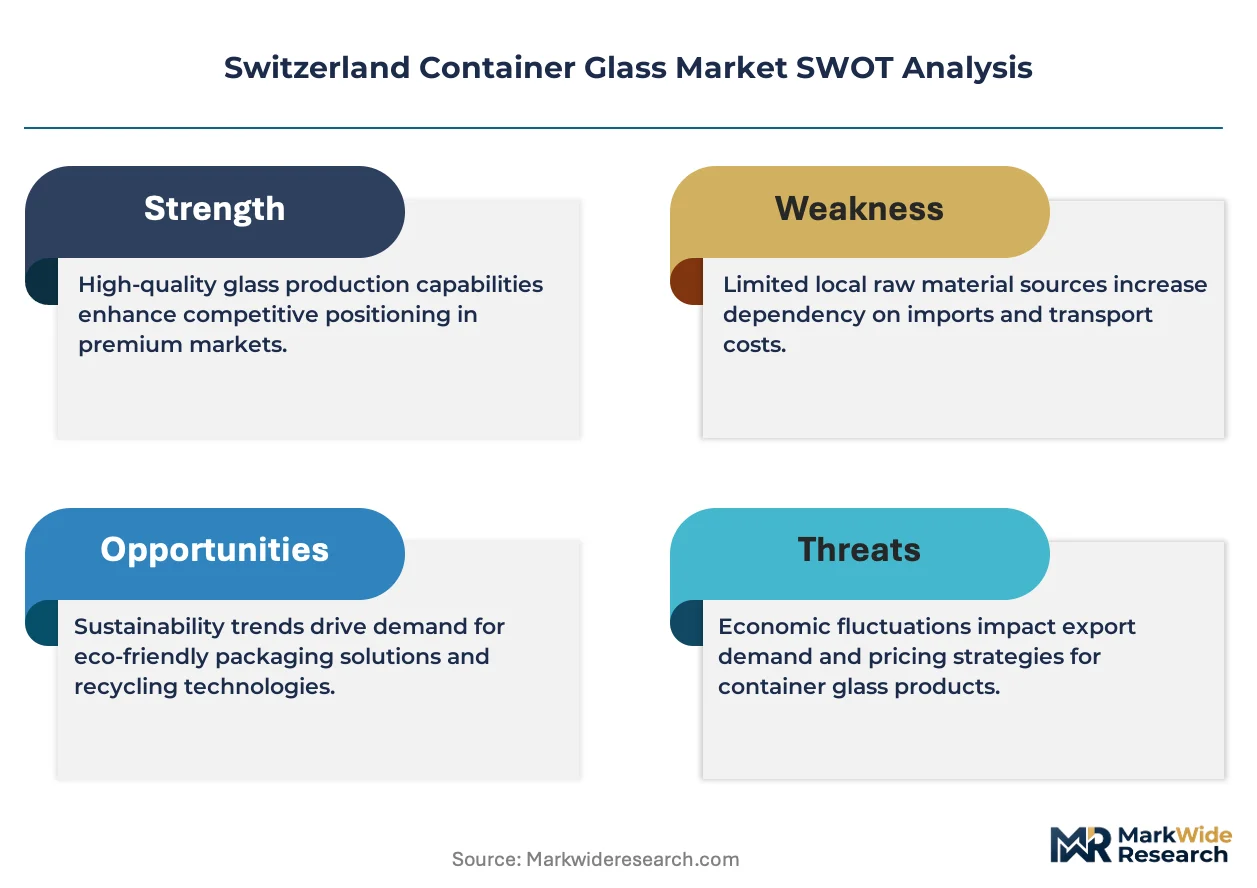
- Swissmedic pharmacopeial standards:Mandatory Type I and Type III glass specifications for drug-contact packaging create captive demand from Basel-based pharmaceutical packagers.
- Lake Geneva industrial corridor concentration:Vaud and Geneva cantons host mineral water and spirits producers requiring premium amber and flint glass presentation formats.
- Lightweighting process advances:Press-and-blow forming technologies reduce per-unit silica consumption while maintaining structural integrity for carbonated beverage applications.
Market Restraints
- Natural gas furnace dependency:High-temperature melting operations remain tethered to volatile natural gas feedstock costs with limited short-term fuel-switching alternatives.
- Eastern Switzerland supply concentration:Domestic production clusters create geographic vulnerability to single-point logistics disruptions along Rhine corridor transport routes.
- Aluminum can substitution:Beverage brands in carbonated soft drinks and beer segments are migrating toward metal packaging for weight and recycling convenience advantages.
Strategic Opportunities
- Swiss federal recycled content mandates:Pending ordinances on post-consumer glass minimums would advantage domestic producers with established cullet collection infrastructure.
- Pharmaceutical serialization integration:Track-and-trace compliance requirements create demand for glass containers with embedded marking compatibility.
- Carbon capture retrofitting:Furnace exhaust treatment technologies align with Switzerland's net-zero industrial pathway and attract green financing instruments.
Industry Challenges
- Furnace refractory engineering expertise:Specialized thermal management skills required for oxy-fuel conversion projects face scarcity in the Swiss labor market.
- REACH additive reformulation:Colorant and stabilizer re-registration timelines create uncertainty for decorative glass treatment portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Container Glass Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Form: Amber, Clear, Green, Frosted Capacity: Under 100ml, 100-500ml, 500-1000ml, Over 1000ml |
| Companies Covered | Vetropack Holding SA, Ardagh Group S.A., O-I Glass, Inc., Saverglass Group, Berlin Packaging LLC, FILL ME AG, Supermatic Plastic Packaging GmbH, MONDGLAS AG, Verallia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Container Glass Market Evolving Landscape
Swiss container glass production is pivoting toward closed-loop material systems and precision forming technologies that compress energy intensity while expanding pharmaceutical-grade output capacity.
Electromagnetic boosting systems are automating temperature control in regenerative furnaces, allowing Vetropack and Ardagh facilities to maintain thermal stability with reduced natural gas throughput. Pharmaceutical packagers in Basel are prioritizing suppliers with installed electromagnetic infrastructure for batch consistency. This automation is compressing fuel cost variance and narrowing the operating cost gap with European competitors.
EU Green Deal packaging waste regulation is extending producer responsibility obligations to post-consumer collection targets for glass containers entering Swiss commerce. Swiss Federal Council ordinances are transposing these requirements into national enforcement frameworks with 2025 implementation horizons. Amber-form pharmaceutical glass faces heightened documentation burdens for cross-border shipment compliance.
Direct procurement contracts between spirits brands and furnace operators are displacing merchant glass distributor intermediaries in premium packaging categories. Craft distilleries in Valais and Ticino are negotiating volume commitments with Eastern Switzerland producers for bespoke mold designs. This disintermediation concentrates margin capture with manufacturers possessing in-house mold fabrication capabilities.
Switzerland Container Glass Market Segmentation
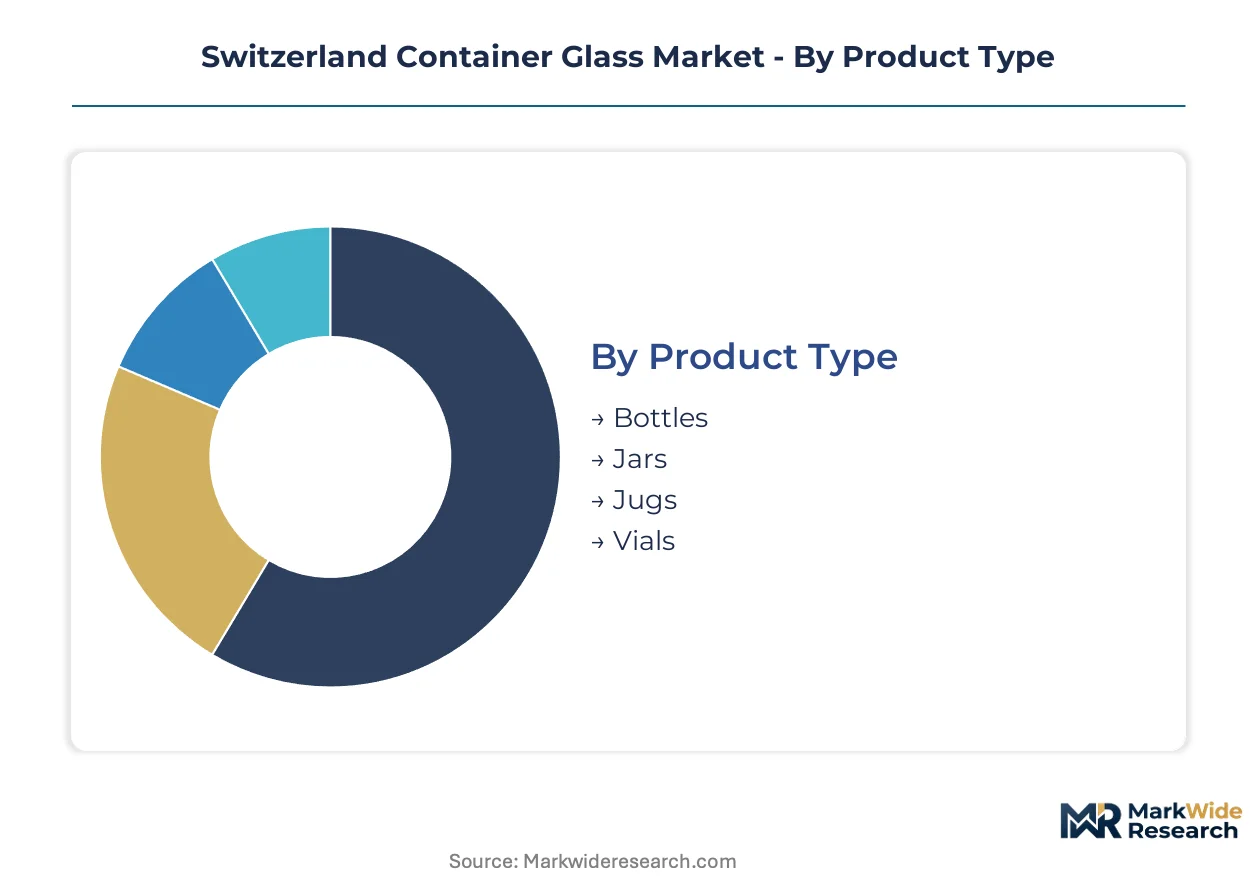
Swiss container glass procurement divides across four critical dimensions that determine furnace scheduling, mold inventory, and regulatory documentation burdens. Product type and end-use specifications dictate Swissmedic compliance tiers, while form and capacity selections shape cullet recovery economics and lightweighting feasibility.
Product Type:
Swissmedic Type I and Type III certifications apply differentially across container geometries, with pharmaceutical-contact surfaces facing stricter borosilicate mandates than food-grade soda-lime alternatives.
- Bottles:Narrow-neck cylindrical containers formed through blow-and-blow processes dominate carbonated mineral water and wine packaging from Lake Geneva producers. Vetropack furnaces dedicate specific production lanes to 75cl and 1-liter formats favored by Valais vintners.
- Jars:Wide-mouth press-and-blow containers with threaded finishes accommodate viscous food preserves and cosmetic creams. Swiss private-label retailers specify jar geometries compatible with automated filling lines at Mittelland co-packing facilities.
- Jugs:Large-format handled containers serve bulk condiment and edible oil distribution. Eastern Switzerland glassworks maintain dedicated mold sets for 2-liter and 5-liter jug capacities demanded by foodservice distributors.
- Vials:Small-diameter tubular containers require Type I borosilicate glass for parenteral drug compatibility. Basel pharmaceutical packagers enforce Swissmedic pharmacopeial compliance with documented batch certification for every vial shipment.
Bottles sit at the top of the volume ranking, with vials climbing the fastest.
End Use Industry:
Customer procurement patterns split between premium presentation requirements in beverages and stringent barrier specifications in pharmaceuticals.
- Food & Beverage:Mineral water bottlers in Vaud and Geneva cantons specify flint glass clarity for premium shelf differentiation. Craft spirits distilleries negotiate bespoke amber and clear bottle designs through direct furnace contracts.
- Cosmetics:Frosted and decorated glass containers for skincare serums require REACH-compliant colorant additives. Swiss beauty brands source from Ardagh facilities with installed electromagnetic boosting for batch color consistency.
- Pharmaceuticals:Injectable and oral dosage packaging mandates Type I borosilicate or Type III soda-lime glass per Swissmedic enforcement. Basel-based multinational packagers anchor long-term supply agreements with furnace operators maintaining dedicated pharmaceutical production lanes.
- Household Products:Cleaning chemical containers utilize thicker-walled soda-lime formulations for chemical resistance. Domestic producers serve this segment through standard mold catalogs with minimal customization lead times.
Food & Beverage captures the largest share, while Pharmaceuticals expands most quickly.
Form:
Color selection determines both functional light-blocking performance and post-consumer cullet sorting complexity under EU Green Deal circular economy mandates.
- Amber:Iron-sulfur colorant additions create UV-blocking properties essential for photosensitive pharmaceutical formulations. Basel packagers specify amber vials and bottles across the 100-500ml capacity tier for drug stability assurance.
- Clear:Low-iron flint glass maximizes optical clarity for premium beverage presentation. Lake Geneva mineral water brands mandate clear bottles for brand visibility in retail refrigeration cases.
- Green:Chromium-based coloration provides moderate light protection with distinctive brand differentiation. Wine producers in Valais and Ticino specify green bottles for traditional varietal packaging conventions.
- Frosted:Acid-etched or molded surface treatments create tactile cosmetic packaging aesthetics. Swiss skincare brands source frosted jars and bottles for premium positioning in pharmacy and department store channels.
Clear dominates current volume, with Amber gaining share fastest.
Capacity:
Size tier selection correlates directly with lightweighting feasibility and per-unit transportation economics across Rhine corridor distribution routes.
- Under 100ml:Small-format vials and sample containers serve pharmaceutical unit-dose and cosmetic trial-size applications. Swissmedic documentation requirements apply uniformly regardless of volume for drug-contact packaging.
- 100-500ml:Mid-range bottles and jars accommodate standard wine, spirits, and oral medication formats. This tier attracts the most intensive lightweighting engineering to reduce per-unit silica consumption.
- 500-1000ml:Family-size food containers and premium spirits bottles occupy this transitional capacity band. Eastern Switzerland producers maintain specialized press-and-blow tooling for structural integrity at reduced wall thicknesses.
- Over 1000ml:Bulk-format jugs and industrial containers face aluminum and plastic substitution pressure. Foodservice and institutional buyers in this tier prioritize weight reduction over glass material preference.
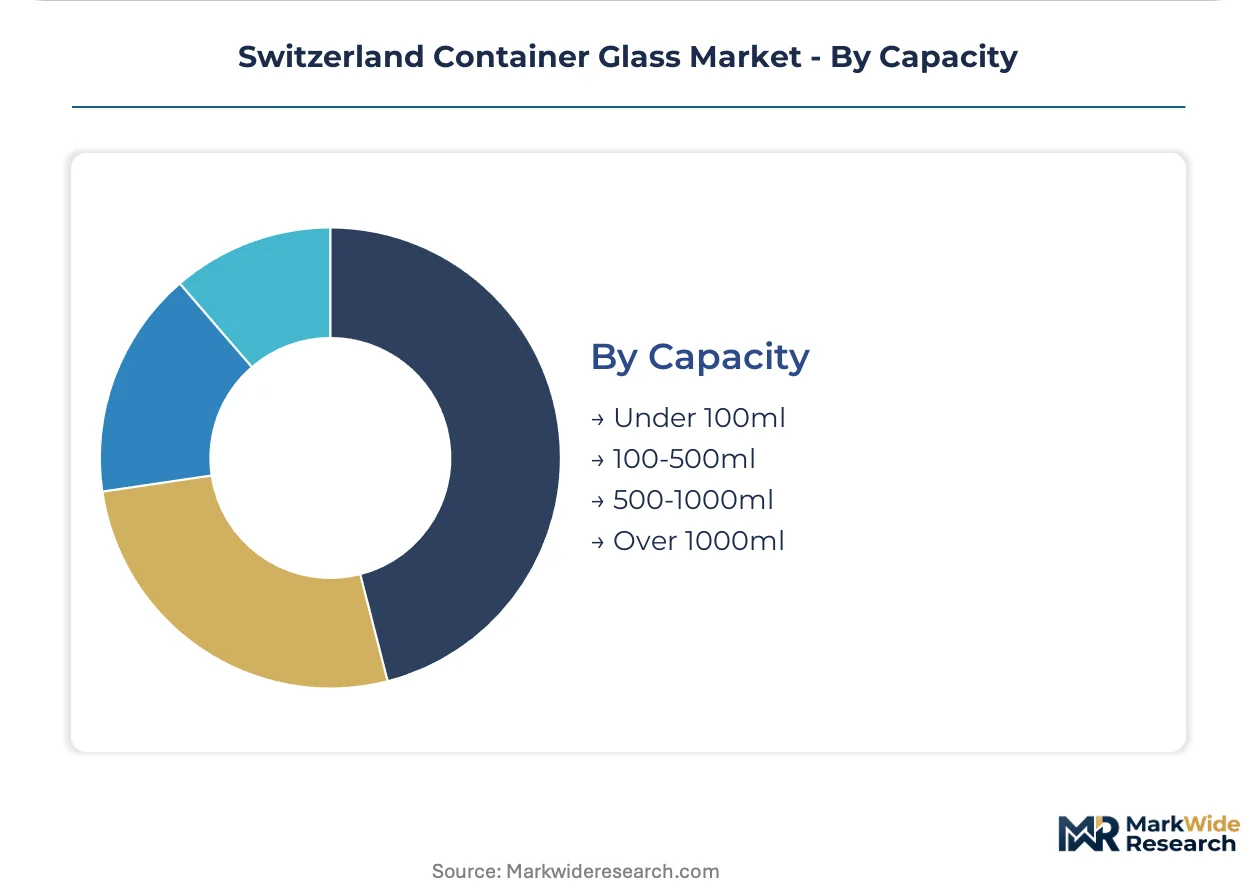
100-500ml sits at the top of the volume ranking, with Under 100ml climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping container glass procurement patterns across European borders, as Swiss producers absorb EU Green Deal compliance costs while neighboring jurisdictions exploit transitional enforcement gaps. Production capacity migrates toward jurisdictions with streamlined permitting for furnace retrofits and favorable cullet recovery subsidies.
Germany
Rhineland-Palatinate and North Rhine-Westphalia host integrated glassworks serving cross-border Swiss beverage clients. ECHA REACH enforcement on colorant additives exceeds Swiss stringency, creating compliance cost premiums that disadvantage German decorative glass specialists. Cologne-Bonn logistics corridors handle bulk cullet backhaul from Swiss collection points.
France
Alsace and Franche-Comté glassworks leverage proximity to Basel pharmaceutical packagers for just-in-time vial supply. ANSM pharmacopeial alignment with Swissmedic standards eliminates regulatory friction for Type I borosilicate shipments. Strasbourg industrial zone furnaces process Swiss-origin post-consumer cullet under bilateral waste transfer agreements.
Italy
Lombardy and Piedmont producers compete for premium spirits bottle contracts from Valais and Ticino distilleries. Italian furnace operators exploit natural gas price differentials against Swiss grid-connected facilities. Milan-Turin logistics hubs coordinate mold fabrication for bespoke Swiss craft beverage packaging.
Austria
Vorarlberg glassworks anchor Alpine corridor supply for Eastern Switzerland beverage bottlers. Austrian federal packaging ordinances lag EU Green Deal implementation timelines, attracting Swiss brands seeking transitional regulatory relief. Bregenz industrial zone maintains dedicated production lanes for flint glass mineral water containers.
Netherlands
Randstad glass distributors intermediate merchant supply for Swiss private-label retailers lacking direct furnace contracts. Dutch packaging waste regulations mandate aggressive post-consumer collection targets that exceed Swiss federal minimums. Rotterdam logistics nodes consolidate fragmented Swiss cullet streams for furnace-ready processing.
Switzerland Container Glass Market Competitive Landscape
Eastern Switzerland producers anchor one tier; cross-border specialists hold procurement relationships with Basel pharmaceutical packagers. Market structure concentrates around three integrated furnace operators with captive cullet collection networks, supplemented by merchant distributors serving fragmented craft beverage accounts. Strategic archetypes include integrated multi-furnace holding companies, specialized lightweighting technology licensors, and pharmaceutical-grade certification specialists. Dominant competitive moves encompass direct contracting disintermediation and electromagnetic boosting infrastructure deployment.
Within the integrated holding company tier, Vetropack Holding SA and O-I Glass, Inc. exemplify divergent geographic anchoring strategies. Vetropack leverages Eastern Switzerland production density for Lake Geneva beverage corridor access, while O-I Glass anchors pharmaceutical supply relationships through Basel-proximate furnace lanes. Ardagh Group S.A. occupies a position between these archetypes, representing specialized lightweighting capability without domestic Swiss furnace ownership. Cross-border competition intensifies as French and German producers exploit regulatory timing gaps to capture Swiss spirits and mineral water accounts.
| Leading Market Players |
|---|
| Vetropack Holding SA |
| Ardagh Group S.A. |
| O-I Glass, Inc. |
| Saverglass Group |
| Berlin Packaging LLC |
| FILL ME AG |
| Supermatic Plastic Packaging GmbH |
| MONDGLAS AG |
| Verallia Group |
| Others |
Value Network & Pricing Analysis
Swissmedic certification tiers bifurcate container glass procurement into pharmaceutical-grade Type I borosilicate corridors and commodity soda-lane channels, with that divergence compressing margins in unregulated beverage segments while concentrating pricing power with Basel-proximate furnace operators holding pharmacopeial accreditations. Eastern Switzerland production clusters exploit this tiered demand structure through direct contracting with Lake Geneva mineral water brands, bypassing merchant distributors and capturing margin that would otherwise fragment across Rhine corridor logistics intermediaries.
Pricing Analysis
Distributor margins in Swiss container glass typically absorb 12-18 percentage points between furnace gate and end-user dock, though direct procurement contracts between Valais spirits distilleries and Eastern Switzerland producers are compressing that spread. Three-tier pricing structure across premium amber pharmaceutical, standard flint beverage, and economy green wine tiers reflects Swissmedic compliance burdens and electromagnetic boosting infrastructure investments. Pricing pressure stems from aluminum can substitution in carbonated soft drinks, with beverage brands demanding per-unit cost parity. Private-label retailers exhibit highest price sensitivity, while Basel pharmaceutical packagers prioritize batch consistency over unit economics.
Supply Chain Analysis
Silica sand supply rests on Bavarian and Austrian specialty mineral deposits, with soda ash feedstock drawing from Solvay's Dombasle-sur-Meurthe operations in France and synthetic alternatives from Germany's Ruhr chemical corridor. Limestone flux sources concentrate in Jura region quarries straddling the Swiss-French border. Supply chain risk manifests as Rhine waterway logistics chokepoints, where low-water events disrupt heavy bulk material transport from Rotterdam through Basel. Distribution runs through dedicated furnace-direct contracts for pharmaceutical and premium beverage accounts, supplemented by merchant glass distributors serving fragmented craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swiss container glass functions as a regulatory compounder, with EU Green Deal circular economy mandates and Swissmedic pharmacopeial standards layering compliance costs that advantage incumbent furnace operators with installed certification infrastructure.
For Market Incumbents: To counter aluminum can substitution in carbonated beverages, Vetropack and O-I Glass should accelerate lightweighting process deployment to achieve per-unit weight parity with metal alternatives. Electromagnetic boosting infrastructure investments in Eastern Switzerland facilities will compress natural gas cost variance against German and Italian competitors. Captive cullet collection network expansion secures feedstock advantage under pending Swiss federal recycled content mandates. For New Entrants and Emerging Players: Craft distillery direct contracting represents an underserved buyer archetype seeking bespoke mold capabilities without volume commitments that justify incumbent furnace scheduling. Valais and Ticino spirits producers offer penetrable entry points for specialized lightweighting technology licensors lacking domestic Swiss furnace ownership. A go-to-market angle emphasizing rapid prototype mold fabrication and Swiss-origin sustainability credentials bypasses established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where electromagnetic boosting capex requirements and Swissmedic certification timelines create barriers for sub-scale Eastern Switzerland producers. Long-term viability favors furnace operators with integrated cullet collection networks and pharmaceutical-grade production lanes. The signal to watch is Swiss Federal Council ordinance finalization on post-consumer glass minimums, which would revalue domestic cullet infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electromagnetic Boosting Deployment | Reduces natural gas throughput variance and narrows operating cost gap with German competitors. |
| Pharmaceutical Serialization Integration | Aligns container output with Swissmedic track-and-trace mandates for Basel injectable packagers. |
| Cullet Collection Network Expansion | Positions operators for Swiss federal recycled content mandates with captive feedstock security. |
| Direct Distillery Contracting | Disintermediates merchant distributors and concentrates margin with mold-fabrication capabilities. |
| Carbon Capture Retrofitting | Attracts green financing instruments under Switzerland's net-zero industrial pathway commitments. |
Research Methodology
Coverage spans Switzerland, Germany, France, Italy, and Austria, with primary inputs from each market combining furnace operator interviews, pharmaceutical packaging procurement leads, beverage brand supply chain directors, and regulatory affairs specialists at Swissmedic and EU ECHA with secondary validation through customs trade data, SEC filings from listed glass manufacturers, Swiss Federal Council ordinance databases, and EU Green Deal implementation tracking. Bottom-up volume modeling triangulates against top-down value estimates derived from furnace capacity utilization and regional pricing benchmarks.
Granularity-level framing models product type, end-use industry, form, and capacity tier at the SKU-equivalent level, with pharmaceutical certification status and electromagnetic boosting infrastructure presence as cross-cutting dimensions. CAGRs derive from segment-level volume trajectories weighted by value-per-unit differentials across Swissmedic-compliant and commodity tiers. Forecast inputs include natural gas price scenario modeling, aluminum substitution elasticity estimates for carbonated beverages, and Swiss federal ordinance implementation probability assessments.
Underlying measurement precision varies by segment; pharmaceutical-grade Type I borosilicate volumes carry tighter precision than commodity beverage containers due to documented Swissmedic batch certification requirements. Forecasts reflect assumptions on EU Green Deal transposition timing, furnace retrofit capex availability, and Rhine corridor logistics reliability. A small set of triggers—Swiss federal recycled content mandate finalization, electromagnetic boosting technology cost curves, and aluminum pricing volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Mason Jars Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Global Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market