
 Sri Lanka Container Glass Market | 2026-2036
Sri Lanka Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Container Glass Market Insights
Multi-source procurement among beverage bottlers is recalibrating supplier relationships across Sri Lanka's container glass value chain. PGP Glass Ceylon PLC leverages its domestic furnace capacity to anchor supply security for alcoholic and non-alcoholic brands. Verallia Indian Ocean Ltd competes through specialized wine and spirits bottle designs that command premium positioning. Piramal Glass PLC extends its technical glass expertise into pharmaceutical-grade container outputs, diversifying beyond mainstream beverage applications.
Sri Lanka container glass comprises soda-lime-silica formulations manufactured through blow-and-blow or press-and-blow forming, with thermal endurance typically ranging between 40°C and 200°C depending on wall thickness and annealing quality. These vessels store, preserve, and distribute consumable and non-consumable goods across temperature-variable supply chains. Bottles dominate volume throughput in food and beverage end uses where carbonated soft drink and beer bottlers require standardized neck finishes and pressure resistance. Jars capture expanding margin pools in premium spice and condiment segments where Sri Lankan exporters seek differentiated shelf presence. Custom design types attract cosmetics and specialty pharmaceutical customers seeking molded embossing and colored glass options that standard formats cannot accommodate.
Sri Lanka Standards Institution certifies dimensional tolerances and chemical durability for food-contact glassware, while the Central Environmental Authority enforces post-consumer collection targets that push manufacturers toward lighter-weight and higher-recycled-content designs. The Central Bank of Sri Lanka monitors import duty structures on cullet and raw materials that directly affect furnace economics for domestic producers. Stakeholders must track how extended producer responsibility enforcement and energy pricing reforms reshape the cost structure of local melting operations versus imported finished container alternatives.
Market Dynamics
Extended producer responsibility mandates from the Central Environmental Authority are forcing domestic manufacturers to reconfigure furnace operations around lighter-weight designs and higher cullet ratios, compressing legacy cost structures.
Growth Catalysts
- Alcoholic beverage bottling expansion:Local distilleries and beer producers are scaling production capacity to serve domestic consumption and regional export markets, creating sustained pull for amber and flint glass formats.
- Central Environmental Authority enforcement:Mandatory post-consumer collection targets and packaging waste rules under extended producer responsibility frameworks are accelerating investment in closed-loop recycling infrastructure.
- Colombo industrial corridor concentration:Beverage manufacturing clusters in and around Colombo generate logistics efficiencies that reduce per-unit distribution costs for container glass suppliers.
Market Restraints
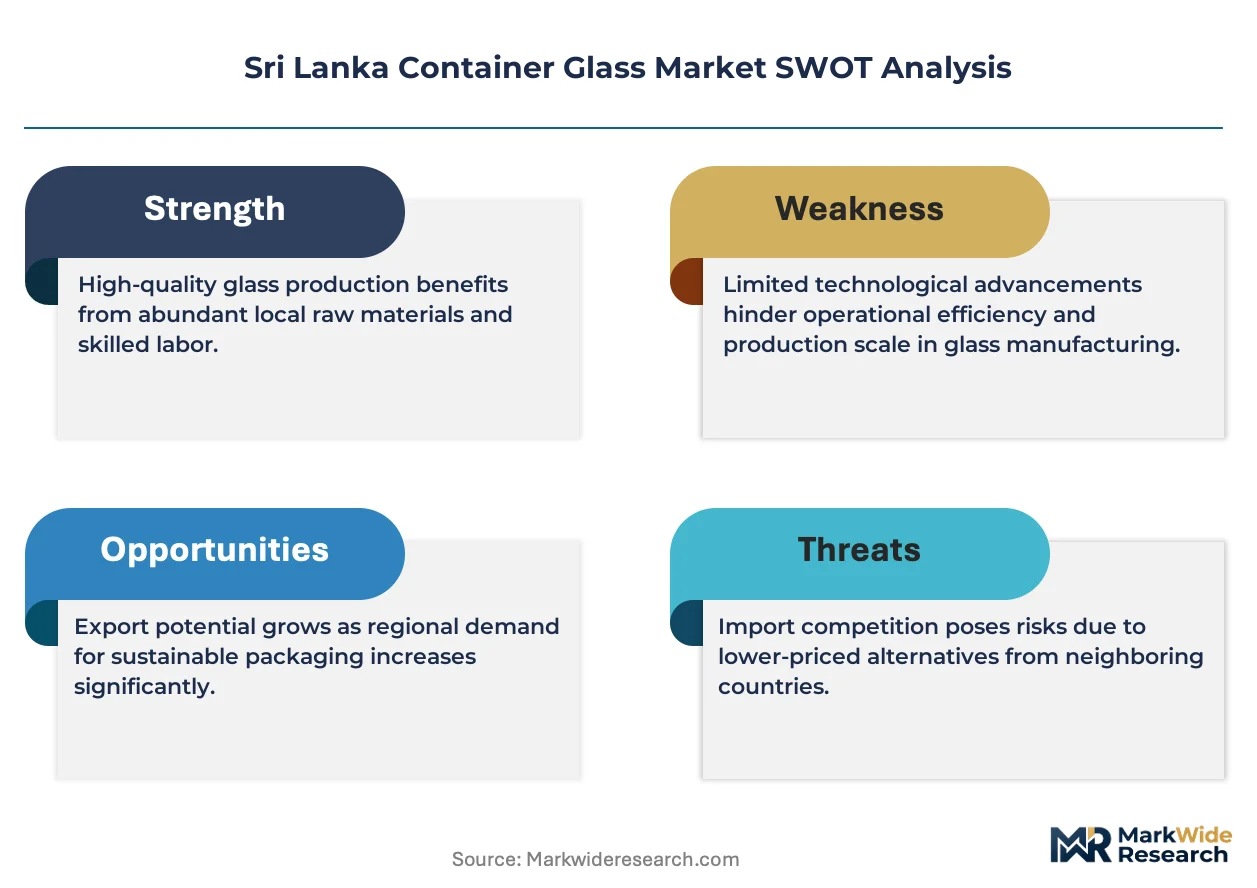
- Natural gas pricing volatility:Furnace melting operations depend heavily on imported LNG, exposing domestic producers to currency fluctuation and global energy market swings that directly affect unit economics.
- Cullet import dependency:Domestic recovered glass supply falls short of manufacturing requirements, forcing reliance on imported recycled content that faces duty structures monitored by the Central Bank of Sri Lanka.
- Plastic substitution pressure:PET bottles and flexible pouches compete aggressively in mass-market beverage segments where weight reduction and freight cost minimization override premium packaging preferences.
Strategic Opportunities
- Pharmaceutical-grade container expansion:Technical glass expertise can extend into vials and ampoules serving Sri Lanka's growing pharmaceutical formulation sector, diversifying beyond beverage dependence.
- Premium spice and condiment export packaging:Jars with custom embossing and colored glass options capture margin pools in Sri Lankan spice exports targeting European and Middle Eastern retail channels.
- Sri Lanka Standards Institution certification leverage:Food-contact glassware standards that exceed regional benchmarks create positioning advantages for exporters seeking differentiated compliance credentials.
Industry Challenges
- Furnace rebuild capex cycles:Glass melting furnaces require major capital injection every 10-15 years, straining balance sheets during periods of currency depreciation and import financing constraints.
- Specialized mold engineering talent scarcity:Design and fabrication of custom bottle molds depends on skilled technicians whose training pipelines remain underdeveloped in Sri Lanka's technical education system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Container Glass Market |
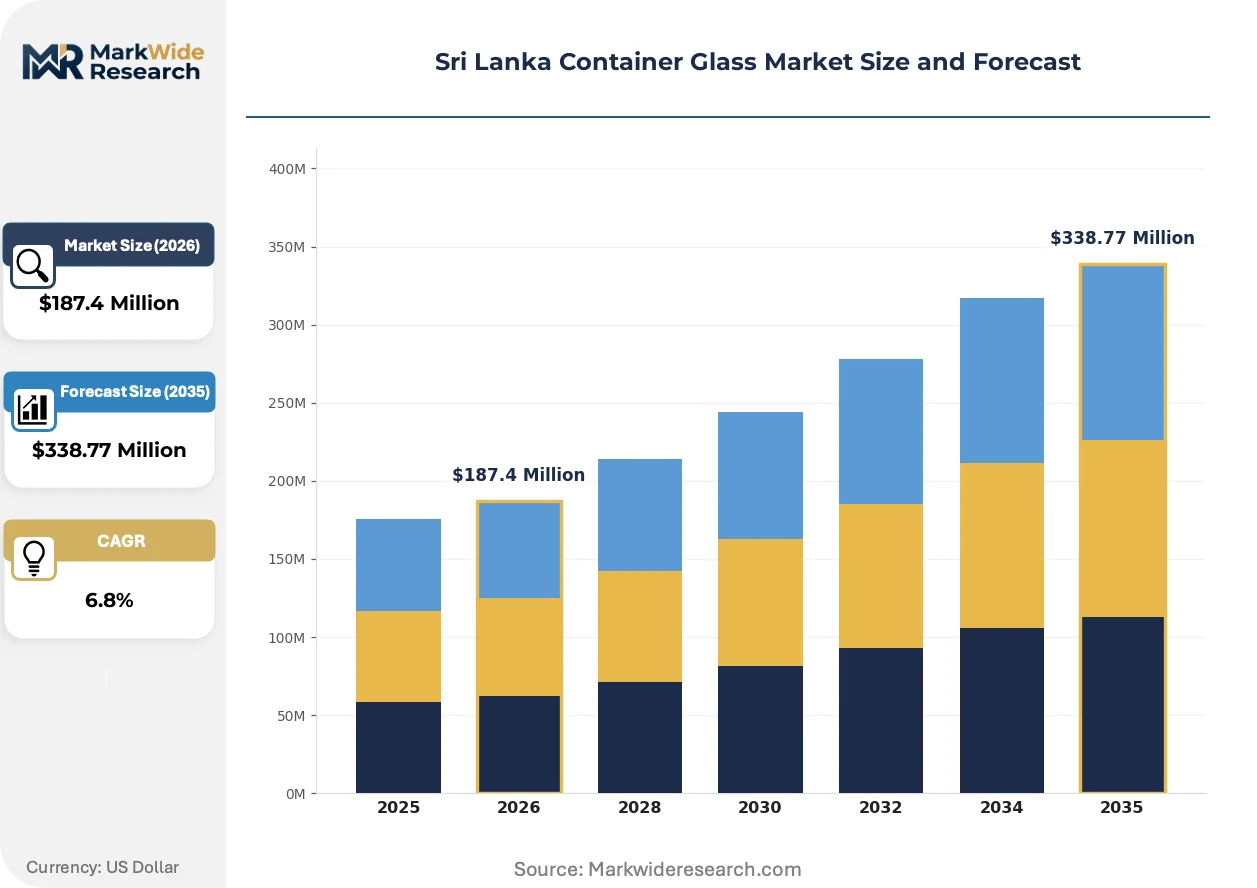
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Household Capacity: Small Scale, Medium Scale, Large Scale, Bulk Design Type: Standard, Custom, Decorative, Eco-friendly |
| Companies Covered | PGP Glass Ceylon PLC, Mapple Packaging (Pvt) Ltd, Glass Pack LK, DHProducts, Shanghai Hejing Packaging Co., Ltd, Verallia Indian Ocean Ltd, Piramal Glass PLC, Consol Glass Pty Ltd, Hindustan National Glass & Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Container Glass Market Trends and Innovations
Lightweighting technologies and digital furnace controls are compressing energy intensity per container, while regulatory pressure on circularity is reshaping raw material sourcing strategies across Sri Lanka's glass value chain.
Oxygen-enriched combustion and electric boosting systems are absorbing fossil fuel dependence in melting operations. PGP Glass Ceylon PLC and domestic competitors are retrofitting furnaces with these technologies to mitigate natural gas price exposure. The structural consequence is a narrowing cost gap between local production and imported finished containers.
The Central Environmental Authority's extended producer responsibility framework is tightening post-consumer collection targets and lightweighting mandates. Manufacturers must now certify recycled content ratios and end-of-life recovery pathways. Food and beverage bottlers in Colombo face the steepest compliance adjustments as enforcement concentrates in industrial zones.
Direct procurement relationships between brand owners and furnace operators are displacing traditional distributor intermediaries. Large beverage bottlers now negotiate volume commitments and technical specifications directly with PGP Glass Ceylon PLC and Verallia Indian Ocean Ltd. This pattern is most visible in the beer and carbonated soft drink segments where standardized neck finishes and pressure resistance requirements favor consolidated supplier relationships.
Sri Lanka Container Glass Market Segmentation
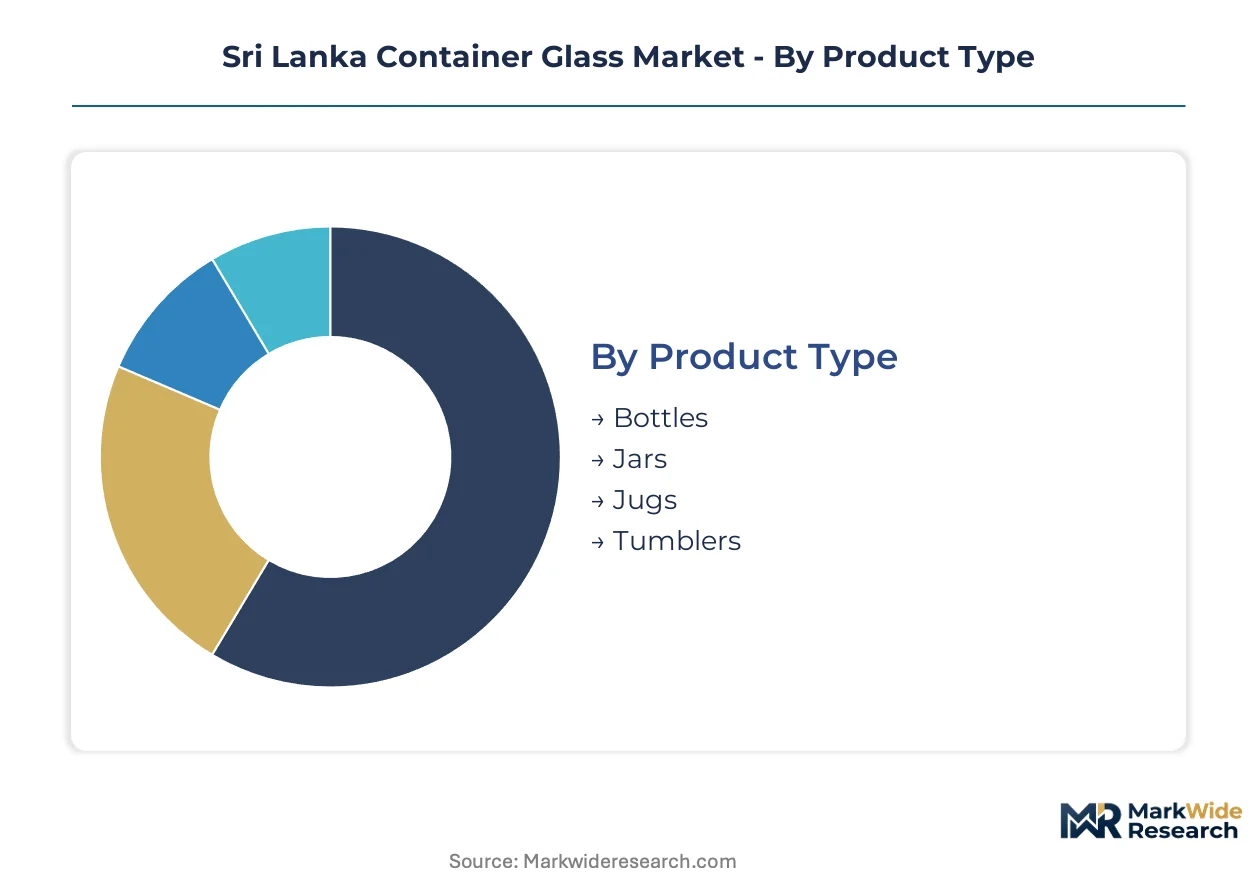
Sri Lanka's container glass market fragments across four structural axes that determine furnace scheduling, mold investment, and distribution economics. Product geometry and end-use specifications dictate forming method selection, while capacity tiers and design complexity shape capital allocation patterns across Colombo's industrial corridor.
Product Type:
Forming technology and thermal endurance specifications differentiate container geometries for distinct content protection requirements.
- Bottles:Blow-and-blow forming produces cylindrical vessels with standardized neck finishes for carbonated beverages and spirits. Colombo's beer and soft drink bottlers drive volume throughput, requiring pressure resistance and crown cap compatibility.
- Jars:Press-and-blow forming yields wide-mouth containers with thicker walls for spice and condiment preservation. Sri Lankan exporters targeting European retail channels demand custom embossing and colored glass options that command premium positioning.
- Jugs:Larger-volume press-blown containers serve bulk liquid storage with reinforced handles and thicker bases. Domestic food service and institutional buyers concentrate procurement in medium-scale capacity tiers.
- Tumblers:Straight-sided drinking vessels utilize simpler mold geometries with lower thermal endurance specifications. Household and hospitality end uses generate intermittent demand outside beverage manufacturing clusters.
Mature deployment sits with bottles. Newer deployment is concentrated in jars.
End Use Industry:
Regulatory compliance intensity and margin structure vary sharply across customer categories.
- Food & Beverage:Sri Lanka Standards Institution certification for food-contact durability anchors procurement specifications. Alcoholic and non-alcoholic bottlers in Colombo's industrial corridor generate logistics efficiencies that reduce per-unit distribution costs.
- Pharmaceuticals:Technical glass expertise extends into vials and ampoules requiring chemical inertness and sterilization compatibility. Piramal Glass PLC leverages this segment to diversify beyond beverage dependence.
- Cosmetics:Decorative finishes and colored glass options serve premium personal care brands seeking shelf differentiation. Custom mold engineering requirements strain limited local technical talent pipelines.
- Household:Standardized tumblers and storage containers compete with ceramic and plastic alternatives on price. Volume concentration lags behind industrial end uses.
Food & Beverage anchors current revenue. Pharmaceuticals represent the steepest expansion trajectory.
Capacity:
Production batch economics and furnace utilization rates stratify across output scales.
- Small Scale:Manual pressing and semi-automatic blow molding serve niche cosmetic and specialty pharmaceutical orders. Custom design work absorbs higher per-unit labor costs.
- Medium Scale:Automated IS machine lines balance flexibility with throughput for regional beverage brands and spice exporters. Central Environmental Authority lightweighting mandates concentrate compliance investment here.
- Large Scale:Continuous furnace operations dedicated to single-format high-volume output serve multinational bottlers. Direct procurement relationships displace traditional distributor intermediaries.
- Bulk:Dedicated tank furnace capacity for standardized commodity containers minimizes changeover downtime. Natural gas pricing volatility exposes unit economics to currency fluctuation.
Large-scale deployment dominates volume. Small-scale deployment is gaining share fastest in premium export segments.
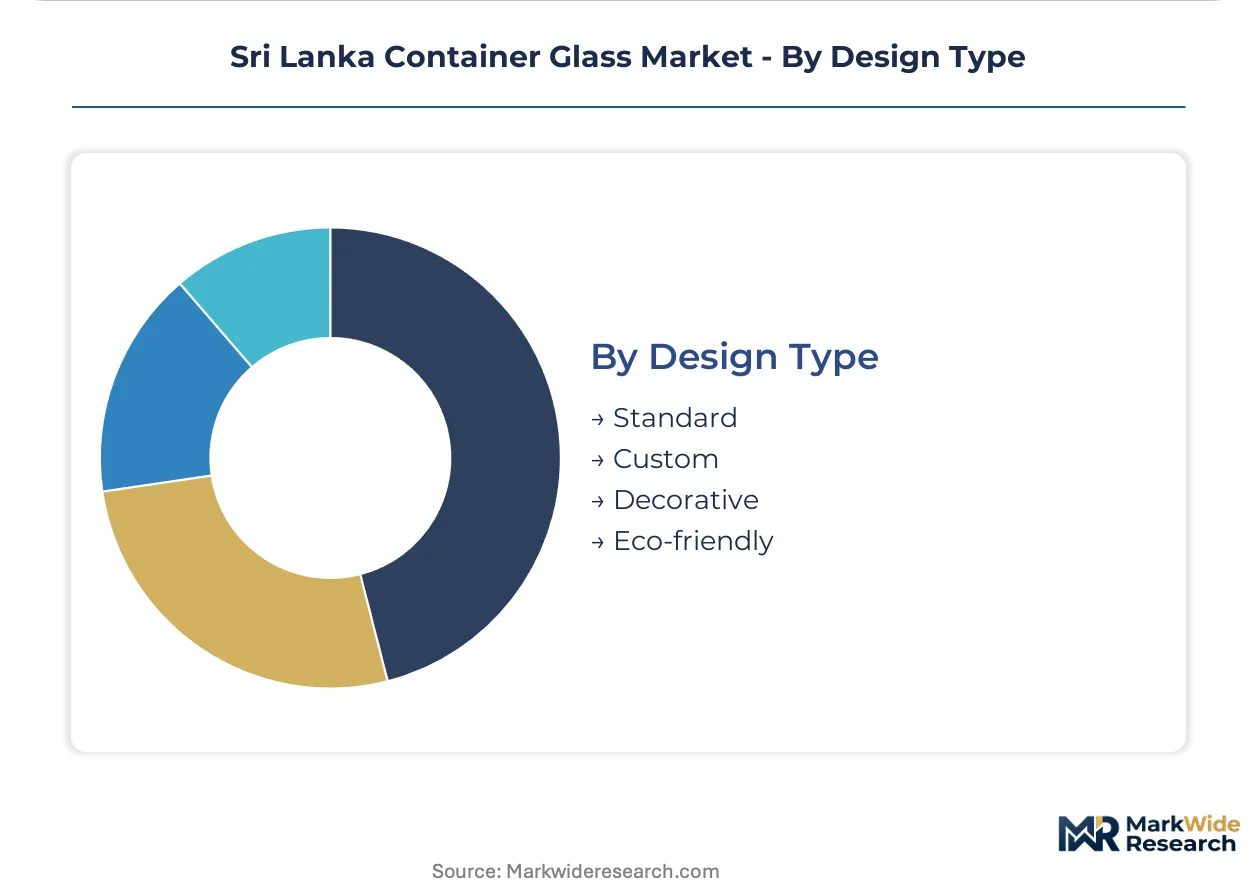
Design Type:
Specification complexity determines mold capital requirements and production scheduling flexibility.
- Standard:Industry-common neck finishes and wall thicknesses minimize tooling investment for beverage bottlers. Pressure resistance and dimensional tolerances align with Sri Lanka Standards Institution benchmarks.
- Custom:Proprietary embossing, proprietary colors, and unique silhouettes serve brand differentiation strategies. Verallia Indian Ocean Ltd competes through specialized wine and spirits bottle designs.
- Decorative:Applied color labels, metallic finishes, and textured surfaces target cosmetics and gift packaging segments. Higher defect rates compress effective yield.
- Eco-friendly:Lightweight wall profiles and elevated cullet content respond to Central Environmental Authority extended producer responsibility mandates. Post-consumer collection targets drive recycled content certification.
Standard designs anchor furnace throughput. Eco-friendly specifications are climbing the fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in Puttalam and quartz-rich zones of the island's north-central belt anchor Sri Lanka's container glass manufacturing geography, with furnace operations clustering near these feedstock sources and Colombo's port infrastructure.
Western Province
Colombo's industrial corridor hosts the densest concentration of beverage bottling plants and container glass furnaces in Sri Lanka. The Central Environmental Authority enforces extended producer responsibility mandates most stringently here, pushing manufacturers toward lightweighting investments. Kelaniya and Biyagama zones see direct procurement relationships displacing traditional distributor networks.
North Western Province
Puttalam district silica sand extraction feeds furnace operations across the island with high-purity raw material. The Sri Lanka Standards Institution certifies dimensional tolerances for glassware produced from these feedstocks. Chilaw and surrounding areas concentrate mining activity that reduces import dependency for soda-lime-silica formulations.
Southern Province
Galle and Matara districts generate demand from tourism-linked beverage distribution and spice export packaging. Local bottlers serving the hospitality sector require smaller batch runs with custom embossing. Hambantota port development creates alternative logistics channels reducing Colombo corridor congestion.
Central Province
Kandy and surrounding highland zones anchor tea and spice export packaging demand for premium jar formats. Sri Lankan exporters targeting European retail channels source custom-colored glass from Colombo-based suppliers. Peradeniya technical education institutions struggle to supply specialized mold engineering talent.
Sri Lanka Container Glass Market Competitive Landscape
Global majors compete with regional champions across furnace capacity and design specialization, producing a tiered structure where scale-driven operators anchor high-volume beverage contracts while niche specialists capture premium export packaging margins. The market consolidates around three strategic archetypes: integrated domestic furnace operators, regional technical glass specialists, and import-dependent trading entities. Capacity expansion and direct procurement relationships constitute the dominant competitive moves reshaping supplier-brand owner dynamics.
Among Sri Lanka-based furnace operators, PGP Glass Ceylon PLC exemplifies the integrated domestic archetype with continuous melting capacity serving standardized beverage formats. Verallia Indian Ocean Ltd represents the regional specialist tier competing through design differentiation in wine and spirits segments. Piramal Glass PLC occupies a diversification position extending technical glass expertise into pharmaceutical-grade applications beyond mainstream beverage dependence.
| Leading Market Players |
|---|
| PGP Glass Ceylon PLC |
| Mapple Packaging (Pvt) Ltd |
| Glass Pack LK |
| DHProducts |
| Shanghai Hejing Packaging Co., Ltd |
| Verallia Indian Ocean Ltd |
| Piramal Glass PLC |
| Consol Glass Pty Ltd |
| Hindustan National Glass & Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Imported LNG feeds furnace melting economics and cascades through three distinct pricing tiers for Sri Lankan container glass buyers. Natural gas pricing volatility compresses margins at the bulk capacity tier while enabling premium positioning for lightweight and pharmaceutical-grade formats that recover energy costs through technical specifications.
Pricing Analysis
After-sales technical support and mold modification services are unbundled from base container pricing, creating transparent cost structures for beverage bottlers negotiating direct procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade technical glass from food-contact certified formats and commodity beverage containers. Price differentiation hinges on Sri Lanka Standards Institution certification grade and volume scale commitments. Pricing pressure stems from PET substitution in mass-market beverage segments where freight cost minimization overrides premium packaging preferences. Small-scale cosmetic and specialty pharmaceutical buyers exhibit lowest price sensitivity due to custom embossing requirements and limited alternative supply.
Supply Chain Analysis
Central Environmental Authority extended producer responsibility mandates are reshaping sourcing patterns toward higher domestic cullet recovery and lightweight feedstock specifications. Raw material supply concentrates in Sri Lanka's Puttalam silica sand deposits and imported soda ash from the United States and Turkey. Furnace operations draw from LNG shipments through Colombo port, quartz-rich north-central belt minerals, and recycled glass cullet that falls short of manufacturing requirements. Single-source vulnerability sits with natural gas import dependency exposing unit economics to currency fluctuation. Distribution runs through direct procurement relationships between Colombo-based furnace operators and multinational beverage bottlers, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sri Lanka's container glass sector is transitioning from fossil-fuel furnace dependence toward oxygen-enriched combustion and electric boosting systems. This technology shift is compressing the cost gap between local production and imported finished containers while reshaping competitive positioning.
For Market Incumbents: Anchor furnace utilization rates through long-term volume commitments with Colombo corridor beverage bottlers while retrofitting melting operations with electric boosting to mitigate LNG price exposure. Defend against PET substitution by certifying premium lightweight designs that satisfy Central Environmental Authority post-consumer collection targets. Prioritize backward integration into Puttalam silica sand extraction to secure feedstock cost control. For New Entrants and Emerging Players: Enter via pharmaceutical-grade technical glass segments where Piramal Glass PLC has demonstrated viable diversification beyond beverage dependence. Target Kandy and Central Province spice exporters demanding custom-embossed jars for European retail channels. Pursue white-label manufacturing partnerships with regional cosmetics brands seeking molded colored glass options that strain limited local mold engineering talent. For Investors and Strategic Acquirers: Central Environmental Authority enforcement tightening post-consumer collection targets is the leading indicator that furnace retrofit capex cycles will accelerate consolidation among medium-scale operators. Five-to-ten year viability favors integrated domestic furnace operators with captive silica sand access and technical glass diversification capabilities. Watch for direct procurement relationship announcements between multinational bottlers and furnace operators as signals of volume commitment stability.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Technology Retrofit | Oxygen-enriched combustion adoption at PGP Glass Ceylon PLC narrows cost gap with imports. |
| Direct Procurement Relationship | Volume commitments between Verallia Indian Ocean Ltd and multinational bottlers displace distributor intermediaries. |
| Technical Glass Diversification | Pharmaceutical-grade vial production extends Piramal Glass PLC beyond beverage sector dependence. |
| Lightweight Design Certification | Eco-friendly specifications satisfy Central Environmental Authority extended producer responsibility mandates. |
| Silica Sand Backward Integration | Puttalam deposit control reduces import dependency for soda-lime-silica furnace feedstock. |
Research Methodology
Central Bank of Sri Lanka trade statistics, Sri Lanka Standards Institution certification records, and Central Environmental Authority regulatory filings formed the secondary backbone of this analysis. Primary interviews with furnace operations managers, beverage bottler procurement leads, pharmaceutical formulation executives, and spice exporter supply chain directors were combined with secondary validation. Bottom-up and top-down triangulation cross-checked production capacity data against end-use consumption patterns.
Bottom-up modeling anchored volume projections while top-down macroeconomic filters tested scenario consistency across the analysis window. Segmentation dimensions included product geometry, end-use industry, capacity tier, and design complexity. CAGRs were derived from trend extrapolation of furnace utilization rates and import substitution patterns. Natural gas pricing volatility and currency fluctuation were modeled as structural inputs affecting unit economics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained LNG price spikes or accelerated PET substitution in mass-market beverages. Forecasts reflect assumptions regarding Central Environmental Authority enforcement intensity and furnace retrofit financing availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
India Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Colombia Container Glass Market