
 United States Glass Packaging Market | 2026-2036
United States Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Glass Packaging Market Analytics
Buyer consolidation among multinational beverage conglomerates is realigning procurement volumes toward fewer, larger contracts with stringent sustainability terms. Owens-Illinois Inc. leverages its furnace modernization program to secure long-term supply agreements with carbon-neutral commitments. Ardagh Packaging Group anchors its position through backward integration into recycled cullet processing. Anchor Glass Container Corporation competes on regional logistics density, operating plants within delivery radius of major Midwest bottling facilities.
United States glass packaging encompasses silica-based container products formed through blow-and-blow or press-and-blow processes, typically containing sodium carbonate, lime, and recycled cullet at ratios exceeding twenty percent, serving as chemically inert barriers for oxygen-sensitive contents. Amber glass commands premium positioning in pharmaceutical and craft spirits segments where UV protection justifies higher unit economics. Clear glass dominates food and beverage volume but faces margin compression from lightweighting mandates. Jars sustain growth in premium cosmetics and specialty food channels where tactile aesthetics drive shelf differentiation.
The FDA governs food contact notifications for glass compositions, while the EPA enforces emissions standards under the Clean Air Act that affect furnace fuel choices and cullet beneficiation investments. State regulators in California and Oregon administer extended producer responsibility frameworks that elevate post-consumer recycled content minimums. Stakeholders must monitor how the SEC's climate disclosure rules reshape supply chain reporting obligations for publicly traded container customers.
Market Dynamics
Buyer consolidation among multinational beverage conglomerates is compressing contract volumes into fewer, larger agreements with binding carbon-neutral clauses. Furnace operators must modernize or exit as procurement power concentrates with sustainability-mandated customers.
Growth Catalysts
- State bottle deposit frameworks:Oregon and California extended producer responsibility laws mandate post-consumer recycled content minimums that pull cullet supply into regional manufacturing corridors.
- Premium spirits differentiation:Craft distillers are expanding amber glass procurement for UV-protected packaging that commands shelf price premiums over standard clear alternatives.
- Southeast furnace clustering:New container glass capacity is concentrating near recycled cullet processing hubs in Georgia and South Carolina, shortening inbound material loops.
Market Restraints
- Natural gas price volatility:Furnace operations depend on natural gas for melting, exposing margins to FERC-jurisdictional pipeline rate fluctuations and regional supply constraints.
- Silica sand supply concentration:High-purity silica deposits suitable for pharmaceutical-grade glass concentrate in limited Midwest mining districts, creating single-source vulnerability.
- Aluminum can substitution:Lightweight metal packaging is displacing glass in mass-market beer and carbonated soft drinks where UV protection is not required.
Strategic Opportunities
- SEC climate disclosure rules:Publicly traded beverage customers face new supply chain emissions reporting obligations that favor glass suppliers with verified carbon accounting systems.
- Pharmaceutical serialization:Track-and-trace mandates for drug packaging create demand for laser-etched glass vials with integrated authentication features.
- Cosmetics channel expansion:Premium skincare brands are adopting heavy-wall glass jars for tactile differentiation in direct-to-consumer subscription boxes.
Industry Challenges
- Electrical furnace engineering talent:The shift from natural gas to electric melting requires scarce metallurgical and high-temperature process engineers.
- Cullet beneficiation capex:Removing ceramic contaminants and color-sorting post-consumer glass demands optical sorting equipment investments that strain mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Glass Packaging Market |
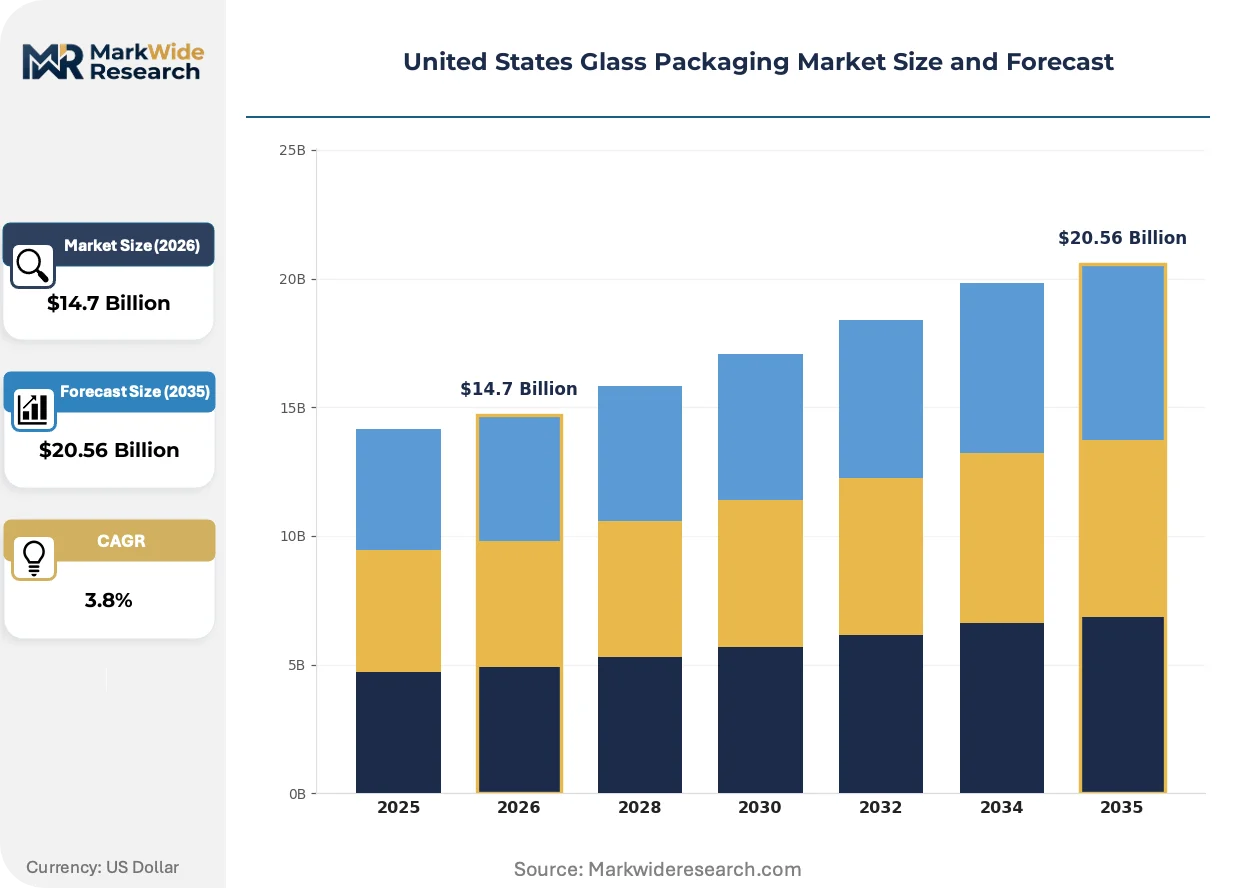
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $20.56 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Ampoules End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Grade: Recycled Glass, Amber Glass, Clear Glass, Green Glass Application: Packing, Storage, Distribution, Preservation |
| Companies Covered | Owens-Illinois Inc., Ardagh Packaging Group, Anchor Glass Container Corporation, Verallia North America, Gerresheimer Glass Inc., Vitro Packaging, Piramal Glass USA, Kaufman Container, West-Pack LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Glass Packaging Market Evolving Landscape
Active furnace electrification and lightweighting mandates are compressing traditional process economics while opening premium positioning for specialized glass grades. These shifts favor capital-rich operators capable of absorbing technology transition costs.
Electrode-boosted electric melting is expanding into container glass production as natural gas volatility erodes fossil-fired furnace economics. Ardagh and Owens-Illinois are piloting all-electric lines at Ohio and Texas facilities. The technology is expanding into mainstream volume segments previously reserved for specialty pharmaceutical glass.
EPA Clean Air Act emissions standards are tightening particulate and nitrogen oxide limits on glass melting operations. Furnace operators must install baghouse filters and selective catalytic reduction systems or face production curtailments. Amber glass producers in Pennsylvania and West Virginia face the steepest retrofit timelines due to older regenerative furnace fleets.
Direct-to-contractor procurement is fragmenting traditional distributor channels in the specialty food segment. Small-batch hot sauce and preserves makers now source jars through manufacturer e-commerce portals rather than packaging distributors. The Pacific Northwest and New England exhibit the highest portal adoption rates among craft food startups.
United States Glass Packaging Market Segmentation
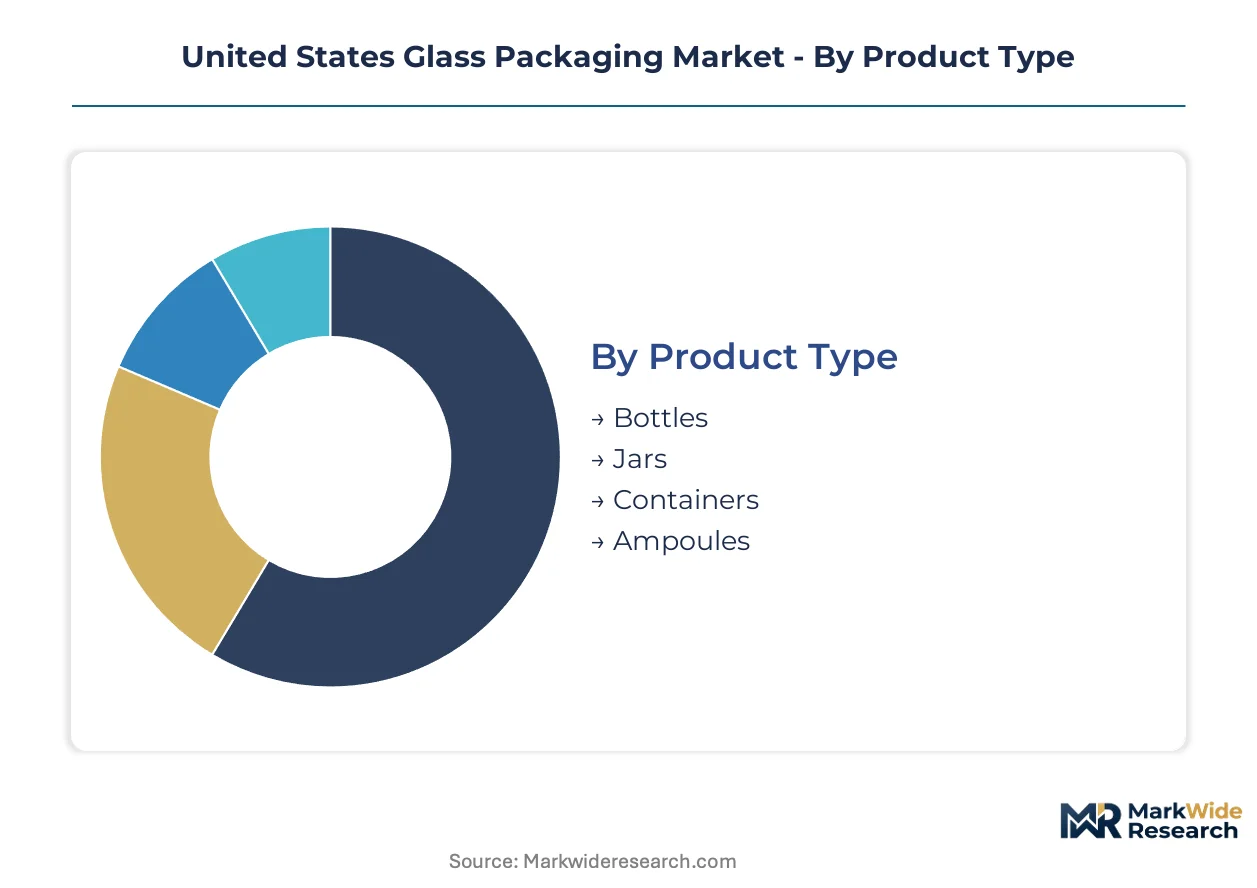
Glass packaging segmentation in the United States reflects divergent technical requirements across oxygen-sensitive contents, UV protection needs, and recycling compliance mandates. Procurement patterns differ sharply between commodity beverage volumes and specialized pharmaceutical or cosmetic applications where material purity commands premium positioning.
Product Type:
Standalone container formats dominate procurement volumes, while embedded systems such as ampoules serve specialized dispensing functions in controlled-dose applications.
- Bottles:Cylindrical or shaped vessels with narrow necks formed through blow-and-blow processes, typically 12-750ml capacity. Demand concentrates in premium spirits and craft beverage segments across Kentucky and Tennessee distilleries, where brand differentiation through embossed glass and custom closures justifies higher unit economics against aluminum alternatives.
- Jars:Wide-mouth containers with continuous thread finishes, press-and-blow formed for dimensional stability. The Pacific Northwest and New England specialty food corridors drive procurement through direct-to-contractor e-commerce portals, bypassing traditional packaging distributors for small-batch preserves and hot sauce applications.
- Containers:General-purpose rectangular or cylindrical storage vessels with lug or snap-fit closures. Food service bulk packaging in the Southeast manufacturing corridor sustains volume placements near recycled cullet processing hubs.
- Ampoules:Sealed single-dose vials requiring flame-sealed necks or score-break designs. Pharmaceutical serialization mandates in New Jersey and Massachusetts manufacturing clusters pull demand for laser-etched authentication features.
Volume placements concentrate in bottles; the faster expansion belongs to ampoules.
End User:
Cost tier stratification separates mass-market beverage procurement from premium-positioned cosmetic and pharmaceutical applications where material certification drives supplier selection.
- Food & Beverage:The largest procurement segment spanning carbonated drinks, juices, sauces, and preserves. Clear glass dominates mass-market volumes while amber variants command shelf price premiums in craft segments; Oregon and California extended producer responsibility laws mandate post-consumer recycled content minimums that reshape supplier qualification criteria.
- Pharmaceuticals:USP Type I borosilicate and soda-lime glass for parenteral and oral dosage forms. FDA food contact notifications govern composition approvals; Pennsylvania and West Virginia amber glass producers face accelerated furnace retrofit timelines under EPA Clean Air Act tightening.
- Cosmetics:Heavy-wall jars and fragrance bottles where tactile aesthetics drive direct-to-consumer subscription box differentiation. Premium skincare brands in California and New York metro areas are expanding glass procurement for unboxing experience optimization.
- Household Products:Industrial cleaners, solvents, and specialty chemicals requiring chemical-resistant closures. Regional logistics density in the Midwest anchors procurement patterns near Anchor Glass Container Corporation's plant network.
Food & Beverage captures the dominant procurement volume; Cosmetics is climbing the fastest on premium positioning tailwinds.
Grade:
Supply concentration in recycled cullet processing creates geographic clustering effects, while virgin glass grades differentiate on spectral protection properties.
- Recycled Glass:Post-consumer cullet beneficiated to ceramic-contaminant-free flake, typically 20-70% of batch composition. Georgia and South Carolina furnace clustering shortens inbound material loops; optical sorting equipment investments strain mid-tier operator balance sheets.
- Amber Glass:Iron-sulfur-carbon colorant systems absorbing UV wavelengths below 450nm. Craft distillers and pharmaceutical packagers in Kentucky and New Jersey drive demand where light protection justifies higher unit economics.
- Clear Glass:Decolorized soda-lime silica with manganese or selenium additives. Lightweighting mandates compress margins in mass-market beer and carbonated soft drinks where aluminum can substitution accelerates.
- Green Glass:Chromium-iron colorant systems for wine and certain beer applications. Limited domestic furnace capacity concentrates supply in select Ohio and Texas facilities piloting electrode-boosted electric melting.
Clear glass sustains the largest volume placements; recycled glass is gaining share fastest on state bottle deposit framework expansion.
Application:
Functional purpose segmentation aligns with supply chain position, from primary containment through distribution logistics to shelf-life extension.
- Packing:Primary containment at point of fill, requiring dimensional tolerance for high-speed bottling lines. Carbonated beverage producers in the Southeast specify pressure-resistant heel designs.
- Storage:Intermediate and long-duration holding with stackability and closure integrity priorities. Warehouse automation in Midwest distribution centers drives standardized pallet footprint requirements.
- Distribution:Transit-optimized packaging with shock resistance and label adhesion specifications. Regional logistics density determines supplier selection within delivery radius constraints.
- Preservation:Oxygen and moisture barrier functions for shelf-life extension. Pharmaceutical and premium food segments in New Jersey and Massachusetts specify low-permeability closure systems.
Volume placements concentrate in packing; preservation applications show the steepest expansion trajectory on pharmaceutical serialization and specialty food growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits in Wisconsin and Illinois anchor domestic container glass production, while recycled cullet processing clusters in Georgia and South Carolina reshape furnace siting decisions across the Southeast manufacturing corridor.
Southeast
New container glass furnaces are clustering near recycled cullet processing hubs in Georgia and South Carolina, shortening inbound material loops for major beverage producers. State bottle deposit frameworks in neighboring markets pull cullet supply into this regional corridor. Atlanta and Charleston anchor expanding capacity for carbon-neutral procurement commitments.
Midwest
Regional logistics density determines supplier selection within delivery radius constraints of major bottling facilities across Ohio, Indiana, and Illinois. Anchor Glass Container Corporation operates plants optimized for food service bulk packaging and industrial chemical containment. EPA Clean Air Act emissions standards are accelerating furnace retrofit timelines for older regenerative fleets in Pennsylvania-adjacent western Ohio.
Pacific Northwest
Direct-to-contractor procurement via manufacturer e-commerce portals is fragmenting traditional distributor channels for specialty food startups in Oregon and Washington. State-level extended producer responsibility laws mandate post-consumer recycled content minimums that reshape supplier qualification criteria. Portland and Seattle exhibit the highest portal adoption rates among craft preserves and hot sauce makers.
New England
Pharmaceutical serialization mandates for drug packaging are pulling demand for laser-etched glass vials with integrated authentication features into Massachusetts and New Jersey manufacturing clusters. FDA food contact notifications govern composition approvals for USP Type I borosilicate applications. Boston and Cambridge anchor track-and-trace investment for parenteral dosage form containment.
California
Premium skincare brands in Los Angeles and San Francisco metro areas are expanding heavy-wall glass jar procurement for unboxing experience optimization in direct-to-consumer subscription boxes. State regulators administer extended producer responsibility frameworks that elevate post-consumer recycled content minimums above federal baselines. SEC climate disclosure rules are reshaping supply chain reporting obligations for publicly traded container customers headquartered in the state.
United States Glass Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized pharmaceutical and cosmetic containment applications with premium positioning. The supplier base concentrates around capital-intensive furnace operators capable of absorbing electrification and lightweighting technology transition costs. Three archetypes dominate: integrated cullet processors leveraging backward integration into recycled material supply, regional logistics specialists optimizing plant placement within delivery radius constraints, and premium-grade manufacturers serving oxygen-sensitive pharmaceutical and spirits segments. Competitive moves center on furnace modernization programs securing long-term supply agreements and optical sorting equipment investments tightening cullet beneficiation quality.
Within the integrated processing tier, Owens-Illinois Inc. and Ardagh Packaging Group exemplify capital-rich operators absorbing technology transition costs through furnace electrification pilots. Anchor Glass Container Corporation occupies a regional logistics density position serving Midwest food service and industrial chemical channels. These three represent the dominant competitive archetypes: carbon-neutral commitment anchoring, backward integration into recycled cullet supply, and delivery-radius optimization for bulk procurement volumes.
| Leading Market Players |
|---|
| Owens-Illinois Inc. |
| Ardagh Packaging Group |
| Anchor Glass Container Corporation |
| Verallia North America |
| Gerresheimer Glass Inc. |
| Vitro Packaging |
| Piramal Glass USA |
| Kaufman Container |
| West-Pack LLC |
| Others |
Value Network & Pricing Analysis
Natural gas feedstock costs cascade through furnace economics into three-tier pricing structure across premium, standard, and economy levels, with carbon-neutral certification bundles commanding unbundled premiums from sustainability-mandated beverage conglomerates.
Pricing Analysis
Carbon accounting verification services bundled into long-term supply agreements separate carbon-neutral commitments from baseline procurement, while unbundled spot purchases exclude emissions tracking. Price differentiation hinges on recycled content certification tiers and furnace modernization status, with state bottle deposit compliance premiums widening spreads. Pricing pressure stems from aluminum can substitution in mass-market beer, compressing clear glass margins. Mass-market beverage producers exhibit highest price sensitivity; pharmaceutical packagers show lowest due to USP Type I purity requirements.
Supply Chain Analysis
Direct-to-contractor e-commerce portals fragment traditional distributor channels for specialty food startups in Oregon and Washington, bypassing packaging distributors entirely. Geographic supply concentrates in Wisconsin and Illinois silica deposits, Georgia and South Carolina cullet processing hubs, and Ohio furnace manufacturing corridors. Raw material dependencies center on high-purity silica sand, natural gas melting fuel, and post-consumer cullet beneficiated to ceramic-free flake. Single-source vulnerability in Midwest silica mining districts elevates supply chain risk. Distribution runs through regional logistics density networks anchored by plant placement within delivery radius constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace electrification capex requirements and scarce metallurgical engineering talent constrain capacity expansion, propping pricing power for operators with verified carbon accounting systems.
For Market Incumbents: Deepen backward integration into recycled cullet processing to secure feedstock against state bottle deposit framework competition. Anchor carbon-neutral supply agreements with binding long-term offtake terms before SEC climate disclosure rules tighten reporting obligations. Electrification pilot programs at Ohio and Texas facilities represent the priority capacity lever against natural gas volatility.
For New Entrants and Emerging Players: Laser-etched pharmaceutical vials with integrated serialization authentication offer a technology-first wedge into Massachusetts and New Jersey manufacturing clusters. Target direct-to-contractor e-commerce portal penetration in Pacific Northwest specialty food corridors where traditional distributor relationships remain underdeveloped. Premium cosmetics heavy-wall jars for subscription box unboxing optimization present the most penetrable white-space target.
For Investors and Strategic Acquirers: First commercial-scale all-electric furnace commissioning is the leading indicator that electrification economics have crossed threshold viability for mainstream container glass. Five-to-ten-year viability favors capital-rich operators with optical sorting equipment already deployed and furnace modernization programs underway. Acquisition target archetype: regional logistics specialists with underutilized plant capacity near Southeast cullet processing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Pilot | EPA Clean Air Act compliance secures production permits in Pennsylvania and West Virginia corridors. |
| Cullet Beneficiation Investment | Optical sorting equipment tightens post-consumer glass quality for state recycled content mandates. |
| Carbon-Neutral Supply Agreement | Verified emissions accounting meets SEC climate disclosure obligations for publicly traded beverage customers. |
| Direct-to-Contractor Portal Launch | E-commerce channels capture Pacific Northwest and New England specialty food procurement fragmentation. |
| Pharmaceutical Serialization Integration | Laser-etched authentication features align with FDA track-and-trace mandates in New Jersey clusters. |
Research Methodology
Multi-period observation of furnace capacity utilization, cullet beneficiation investment flows, and state bottle deposit framework expansion anchored the trend analysis, supplemented by interviews with furnace operations directors, beverage procurement executives, pharmaceutical packaging engineers, and recycled materials processing managers. Secondary validation drew from EPA Clean Air Act filings, FERC pipeline rate proceedings, SEC climate disclosure submissions, and state-level extended producer responsibility regulatory texts. Bottom-up plant-level capacity assessments triangulated against top-down procurement volume estimates from beverage and pharmaceutical end-use segments.
Input-output matrices mapped silica sand extraction through furnace melting to end-use container shipments across product type, grade, and application dimensions over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by recycled content compliance premiums and electrification cost curves. Forecast inputs incorporated natural gas price volatility scenarios and state bottle deposit law adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated aluminum substitution or breakthrough electric furnace engineering talent availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Mason Jars Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Glass Growlers Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
France Glass Packaging Market